
 North America Microgrid Market | 2026-2036
North America Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microgrid Market Analysis
Containerized battery inverters paired with modular solar arrays is narrowing the deployment gap between utility-scale and behind-the-meter microgrids. Schneider Electric leverages its EcoStruxure platform to anchor integrated control software across North American commercial campuses. Siemens Energy sustains technology leadership in gas-to-power hybrid systems for industrial microgrids in the US Gulf Coast. ABB competes on medium-voltage switchgear specialization that differentiates its offerings for municipal utilities.
A microgrid constitutes a localized group of electricity sources and loads that operates connected to or isolated from a traditional centralized grid, typically incorporating generation assets, energy storage, and control systems with response times under 100 milliseconds to maintain voltage and frequency stability. Its primary purpose is to deliver resilient, controllable power to critical facilities or communities while enabling bidirectional energy flows and demand-side optimization. Grid-tied configurations dominate installed capacity across North America, though hybrid architectures combining renewable generation with battery storage represent the fastest-expanding segment as lithium-ion costs decline and software controls mature. Commercial end users anchor near-term revenue pools, while educational and municipal buyers are emerging as high-growth verticals driven by resilience mandates and sustainability procurement policies.
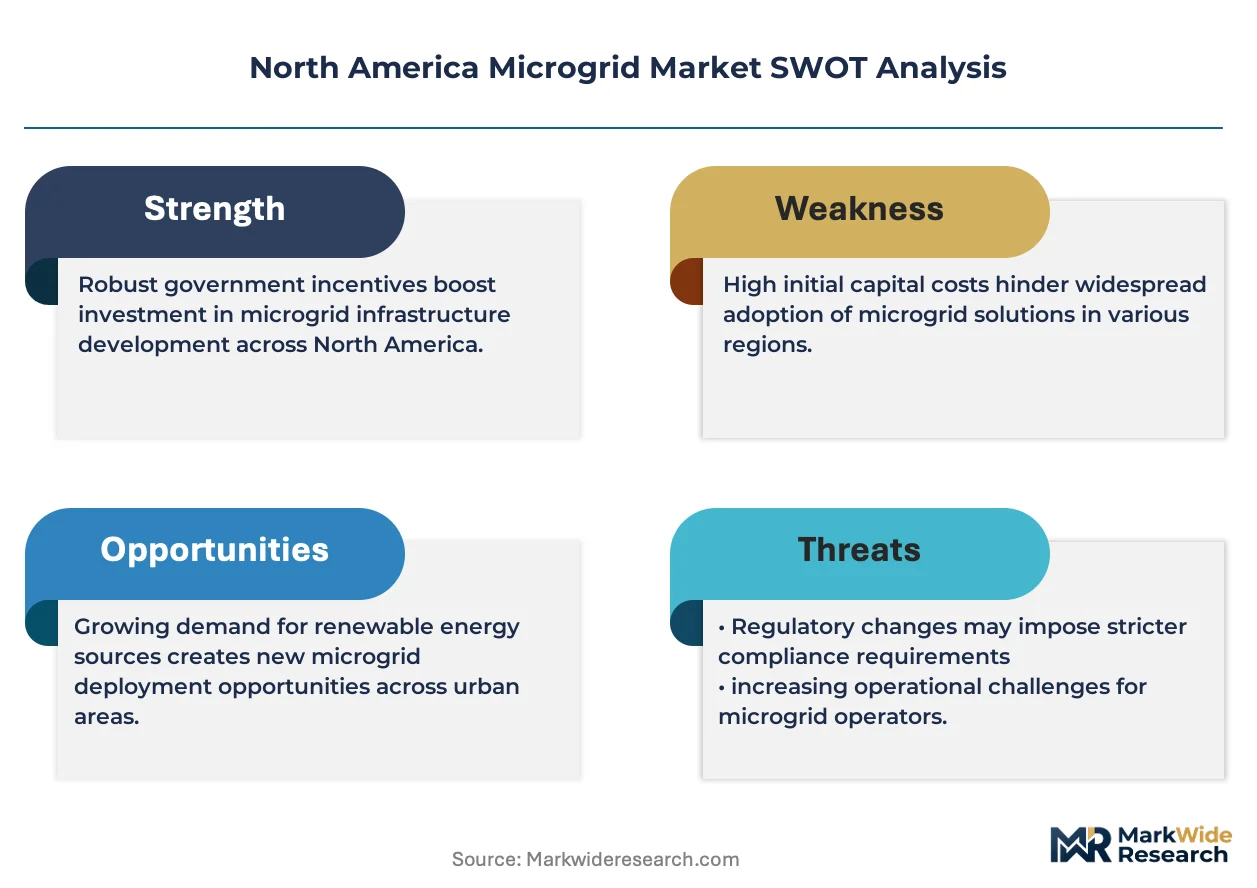
The US Federal Energy Regulatory Commission Order 2222 enables distributed energy resource aggregation, reshaping how microgrid operators participate in wholesale markets across multiple states. EPA emissions standards and state-level renewable portfolio standards in California, New York, and Illinois compel technology choices toward zero-carbon generation portfolios and advanced inverter functionalities. IEEE 1547-2018 interoperability requirements govern grid interconnection equipment, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving state utility commission rulings on microgrid cost recovery mechanisms and behind-the-meter rate structures as these decisions will determine project economics more than hardware advances alone.
Market Dynamics
Containerized battery inverters paired with modular solar arrays is compressing deployment timelines for behind-the-meter microgrids, while FERC Order 2222 reconfigures how distributed energy resources aggregate into wholesale markets across multiple US states.
Growth Catalysts
- US Inflation Reduction Act tax credits:Standalone energy storage incentives accelerate battery-plus-solar hybrid configurations for commercial campuses.
- Data center load growth:Operators across the United States and Canada deploy microgrids to ensure uninterrupted power for AI computing infrastructure.
- California decarbonization mandates:Aggressive renewable portfolio standards compel zero-carbon generation portfolios and advanced inverter functionalities.
Market Restraints
- Lithium-ion supply concentration:Cathode and cell manufacturing concentrates in East Asia, exposing North American project developers to input cost volatility and geopolitical supply risk.
- Utility franchise protection:State-level regulatory friction from incumbent utilities limits behind-the-meter microgrid cost recovery mechanisms in multiple jurisdictions.
- Interconnection queue delays:IEEE 1547-2018 compliance requirements and understaffed utility review processes extend project commissioning timelines by 18-36 months.
Strategic Opportunities
- Texas ERCOT market participation:Real-time energy price volatility creates arbitrage revenue streams for battery-equipped microgrids in the state's deregulated wholesale market.
- Educational campus vertical:Resilience mandates and sustainability procurement policies position universities and K-12 districts as high-growth buyer segments.
- Gas-to-power hybrid convergence:Siemens Energy's industrial microgrid architecture demonstrates path for natural gas reciprocating engines paired with solar-plus-storage to serve Gulf Coast manufacturing loads.
Industry Challenges
- Control systems integration:Schneider Electric's EcoStruxure platform and competing proprietary architectures create interoperability friction for multi-vendor microgrid deployments.
- Medium-voltage engineering talent:ABB's switchgear specialization highlights scarcity of technicians qualified to design and maintain utility-interfaced protection systems.
- State utility commission variability:Divergent rulings on net metering, standby charges, and microgrid tariffs fragment project economics across California, New York, and Texas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microgrid Market |
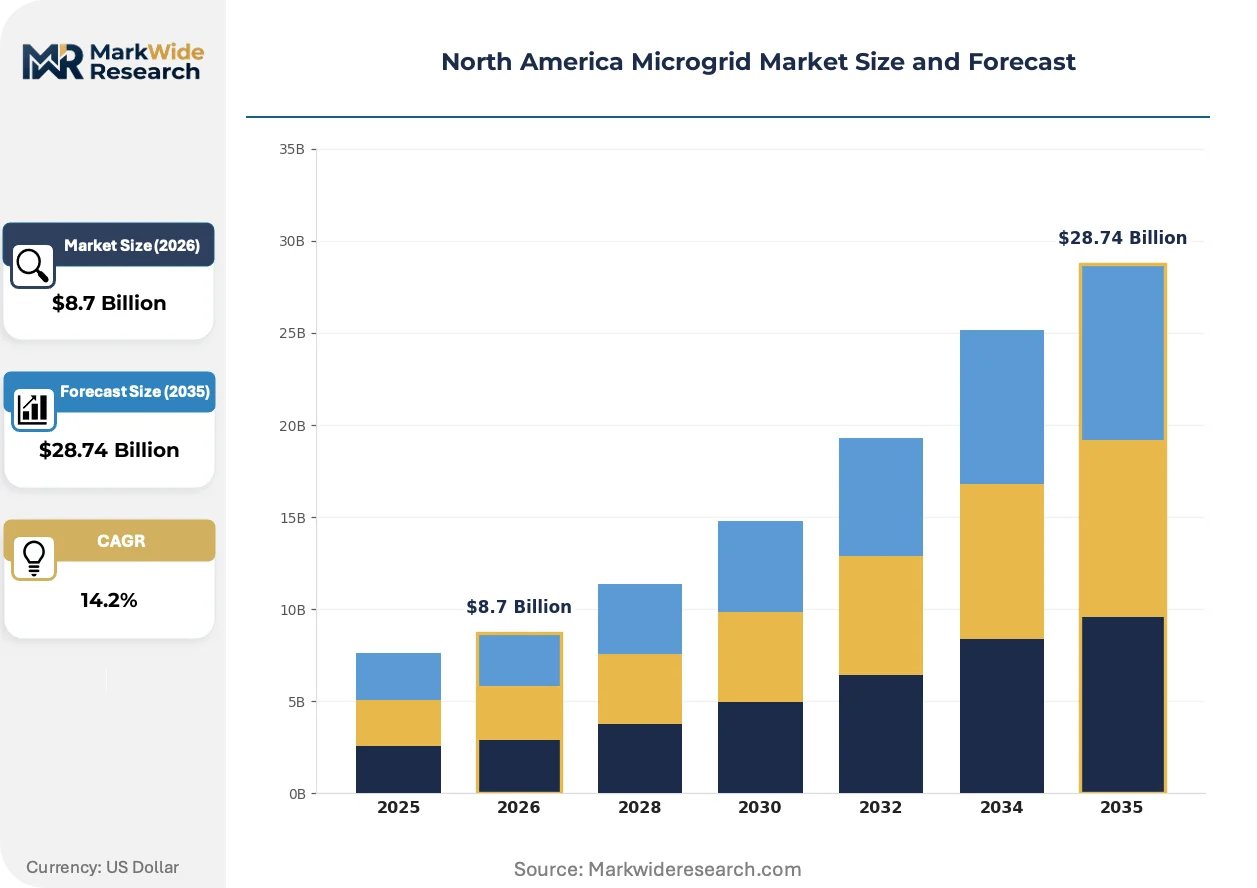
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Hybrid, Virtual Technology: Renewable Energy, Battery Storage, Distributed Generation, Smart Meters End User: Commercial, Industrial, Municipal, Educational Application: Energy Management, Demand Response, Emergency Backup, Renewable Integration |
| Companies Covered | Schneider Electric, ABB, Siemens Energy, General Electric, Eaton, Honeywell International, Caterpillar, S&C Electric, Ameresco, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microgrid Market Emerging Trajectories
Software-defined control architectures are displacing hardware-centric protection systems, compressing commissioning timelines and enabling remote optimization of distributed energy assets.
Artificial intelligence-driven predictive control is digitizing microgrid operations by forecasting load patterns and renewable generation 15-60 minutes ahead. Commercial and industrial buyers in California and Texas adopt these platforms fastest. Real-time optimization is compressing battery cycling costs and maximizing arbitrage revenue.
FERC Order 2222 implementation is reshaping wholesale market participation rules for aggregated distributed energy resources across US states. Grid operators must now accommodate microgrid bidirectional flows and demand-side flexibility. Texas and New York utilities are advancing fastest in tariff structures that compensate microgrid operators for grid services.
Outcome-based resilience contracting is emerging as the dominant procurement model for critical facility microgrids. Data center and healthcare buyers now specify uptime guarantees rather than equipment lists. This shift concentrates vendor selection on operational track records in California, Texas, and Illinois markets.
North America Microgrid Market Segmentation
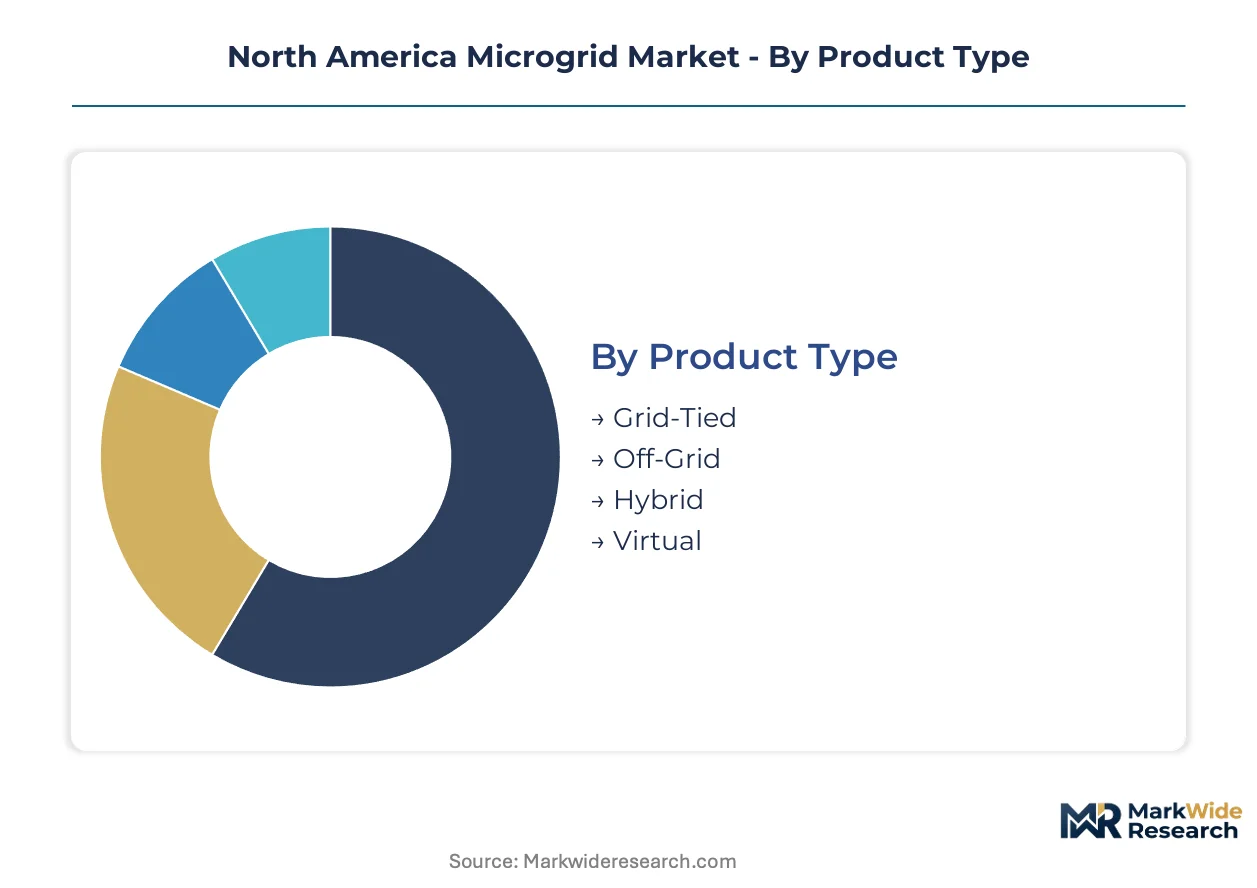
Microgrid segmentation in North America reveals how deployment architectures, technology stacks, and buyer priorities diverge across regulatory environments and resilience requirements. Each dimension captures distinct procurement patterns that shape vendor positioning and project economics.
Product Type:
Deployment configurations span the use-case spectrum from grid-dependent resilience to complete energy autonomy.
- Grid-Tied:Maintains synchronous interconnection with utility infrastructure while enabling islanding during outages. Data center operators in Northern Virginia and Phoenix deploy these configurations to satisfy uptime guarantees without sacrificing wholesale market participation.
- Hybrid:Combines multiple generation assets with battery storage and intelligent switching for seamless transition between grid-connected and islanded states. Texas ERCOT market participants favor this architecture to arbitrage real-time price volatility while maintaining backup capability.
- Off-Grid:Operates in permanent electrical isolation, requiring oversized generation and storage capacity to manage load variability. Remote mining camps in Canada's Northwest Territories and indigenous communities in Alaska represent primary demand pockets.
- Virtual:Aggregates geographically dispersed distributed energy resources through software control without physical interconnection. California community choice aggregators pilot these arrangements to optimize renewable dispatch across municipal boundaries.
Established volume favors Grid-Tied; emerging adoption favors Hybrid.
Technology:
Technology selection tracks cost trajectories and control sophistication across the hardware stack.
- Battery Storage:Lithium-ion systems with four-hour duration dominate new deployments, though sodium-ion alternatives gain traction for longer-duration applications. FERC Order 2222 compliance requirements drive inverter procurement toward advanced grid-forming capabilities.
- Renewable Energy:Solar photovoltaic arrays anchor zero-carbon generation portfolios, with bifacial modules and tracking systems improving yield in Southwestern US installations. California Title 24 building codes accelerate rooftop solar-plus-storage adoption.
- Distributed Generation:Natural gas reciprocating engines and fuel cells provide dispatchable backup for critical loads. Industrial buyers in Louisiana and Texas petrochemical corridors prioritize these assets for black-start capability.
- Smart Meters:Advanced metering infrastructure enables sub-second load monitoring and demand-side flexibility signals. Illinois and Ontario utility rollouts create installed bases for microgrid control integration.
Technology concentration is shifting fastest toward Battery Storage as IRA incentives reshape project economics.
End User:
Buyer categories reflect divergent procurement authority and resilience mandates.
- Commercial:Corporate campuses and retail chains prioritize sustainability commitments alongside uptime guarantees. Microsoft and Amazon data center expansions in Arizona and Ohio drive premium-tier demand for modular, rapidly deployable systems.
- Educational:Universities and K-12 districts combine resilience planning with curriculum integration and research partnerships. University of California campuses and Texas A&M system installations demonstrate scalable procurement templates.
- Industrial:Manufacturing facilities require power quality assurance for sensitive process equipment. Semiconductor fabrication plants in New York's Hudson Valley and Oregon's Silicon Forest specify microgrids for voltage sag protection.
- Municipal:Cities and counties deploy community-scale systems for emergency services and critical infrastructure. New York City post-Sandy resilience investments and Puerto Rico grid hardening programs anchor public-sector demand.
Procurement momentum concentrates in Commercial; policy tailwinds favor Educational.
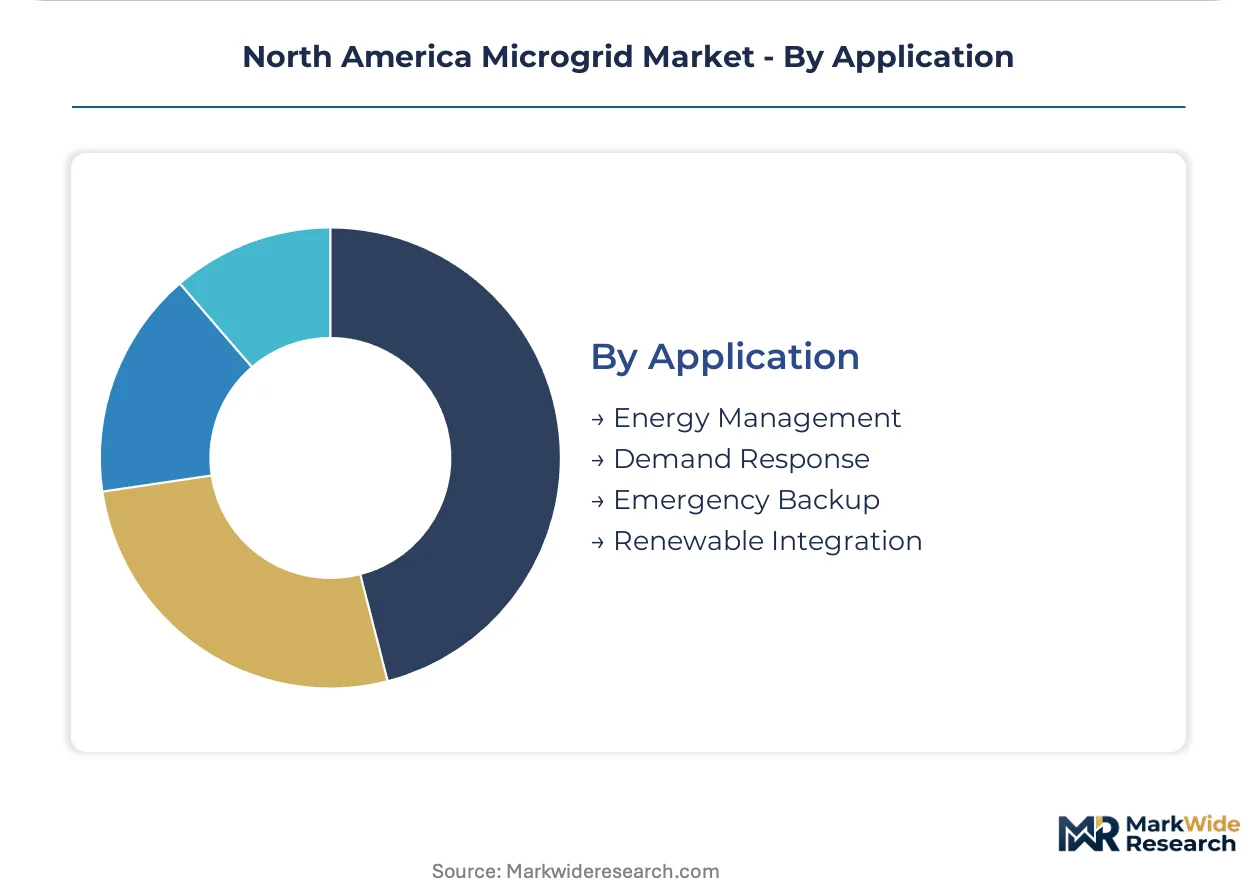
Application:
Functional priorities determine control system architecture and asset sizing.
- Energy Management:Real-time optimization of generation dispatch, storage cycling, and load scheduling to minimize electricity costs. Texas and California commercial buyers deploy these platforms for peak demand charge reduction.
- Emergency Backup:Guaranteed power continuity for life-safety and critical operations during grid outages. Healthcare systems in Florida hurricane zones and California wildfire territories specify 72-hour autonomous operation.
- Demand Response:Bidirectional participation in utility or wholesale market programs for capacity and ancillary services. PJM Interconnection and ISO-New England tariff structures compensate microgrid aggregators for grid flexibility.
- Renewable Integration:Maximizing self-consumption of on-site solar and wind while managing intermittency through forecasting and storage. Corporate renewable energy buyers in Colorado and Minnesota prioritize this application for carbon accounting.
Revenue model maturity favors Energy Management; regulatory evolution favors Demand Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial campuses concentrate procurement authority across North American microgrid deployments. California, Texas, and New York anchor near-term capacity additions. State-level decarbonization mandates and grid reliability concerns reshape technology selection.
United States
Texas ERCOT market participants exploit real-time price volatility through battery-equipped hybrid systems. FERC Order 2222 enables distributed energy resource aggregation into wholesale markets. Northern Virginia data center clusters deploy grid-tied configurations to satisfy uptime guarantees.
California
Commercial campuses and educational institutions drive solar-plus-storage adoption under Title 24 building codes. CPUC renewable portfolio standards compel zero-carbon generation portfolios. Silicon Valley technology campuses specify microgrids for voltage sag protection and carbon accounting.
Texas
Industrial buyers in Houston petrochemical corridors prioritize natural gas reciprocating engines for black-start capability. ERCOT deregulated market structures create arbitrage revenue streams for battery-equipped systems. Dallas-Fort Worth logistics hubs deploy modular configurations for resilience.
New York
Post-Sandy resilience investments anchor municipal demand for community-scale emergency backup systems. NYSERDA clean energy programs accelerate behind-the-meter deployments. Hudson Valley semiconductor fabrication plants specify microgrids for power quality assurance.
Canada
Remote mining camps in Northwest Territories and indigenous communities in Alaska represent off-grid demand pockets. Natural Resources Canada funding programs support northern electrification. Ontario commercial campuses leverage provincial smart metering infrastructure for demand-side optimization.
North America Microgrid Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and integration layers. The vendor base clusters around three strategic archetypes: integrated platform providers, component specialists, and engineering-construction hybrids. Incumbents defend position through control software ecosystems. New entrants attack through modular, rapidly deployable system architectures.
Among integrated platform providers, Schneider Electric and Siemens Energy occupy positions spanning hardware and software stacks. ABB exemplifies the component-specialist archetype through medium-voltage switchgear concentration. These three anchors demonstrate how competitive positioning fragments between full-stack control and targeted equipment excellence.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens Energy |
| General Electric |
| Eaton |
| Honeywell International |
| Caterpillar |
| S&C Electric |
| Ameresco |
| Others |
Supply Flow & Price Mechanics
Port of Los Angeles container throughput cost dynamics cascade through North American microgrid project economics, amplifying lithium-ion battery import expenses while compressing margins for EPC contractors serving price-sensitive municipal buyers. This freight corridor volatility intersects with cathode material concentration in East Asia to create tiered pricing power across integrated platform providers and component specialists.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange cobalt and lithium carbonate benchmarks dominate battery procurement for commercial microgrid deployments. Three-tier pricing structure across premium, standard, and economy levels separates Schneider Electric's integrated EcoStruxure bundles from ABB's switchgear-focused offerings and regional EPC assembler alternatives. Price erosion runs through the economy tier as Chinese inverter manufacturers expand US distribution. Municipal utilities exhibit highest price sensitivity due to ratepayer scrutiny, while data center operators absorb premium pricing for guaranteed uptime specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates lithium-ion cell sourcing strategies for North American developers. Cathode active material production concentrates in China, South Korea, and Japan, drawing from Chilean and Australian lithium spodumene concentrate. Semiconductor-grade silicon carbide wafers for advanced inverters hinge on Taiwanese and German supply. Distribution runs through master distributor networks serving EPC contractors, with direct OEM relationships reserved for multi-hundred-megawatt utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American microgrid incumbents face substitution pressure from virtual power plant aggregators and grid-edge software platforms that bypass hardware-heavy capital deployment models entirely.
For Market Incumbents: Build switching-cost moats through captive control software ecosystems that lock in multi-vendor hardware interoperability. Schneider Electric's EcoStruxure architecture demonstrates this path by embedding proprietary communication protocols across competitor switchgear. Siemens Energy should deepen backward integration into grid-forming inverter firmware to defend against modular solar-plus-battery challengers. FERC Order 2222 compliance certification investments create regulatory barriers for unqualified entrants. For New Entrants and Emerging Players: Canadian indigenous community electrification represents underpenetrated demand with favorable Natural Resources Canada funding flows and limited incumbent presence. Alaska remote microgrids offer similar white-space characteristics with diesel displacement mandates accelerating renewable hybrid adoption. Educational campuses in Illinois and Ohio provide the most penetrable near-term segment given sustainability procurement policy tailwinds and standardized RFP templates emerging from University of California system deployments. Channel partnerships with established EPC contractors accelerate credibility faster than direct utility sales cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined control specialists over hardware-commoditized component manufacturers. Grid-forming inverter algorithm developers and AI-driven predictive optimization platforms command scarcity premiums as lithium-ion hardware costs commoditize. Acquisition target archetypes include medium-voltage protection engineering boutiques with IEEE 1547-2018 certification track records and established utility relationships. The signal to watch is Texas ERCOT tariff rulings on distributed energy resource aggregation compensation, which would validate virtual microgrid economics and compress traditional hardware deployment multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | FERC Order 2222 compliance unlocks wholesale market participation revenue streams for battery-equipped systems. |
| Backward Integration into Battery Assembly | Domestic cell manufacturing mitigates tariff exposure and secures supply for IRA tax credit-eligible deployments. |
| Control Software Platform Licensing | EcoStruxure-type architectures generate recurring revenue while reducing hardware margin dependence. |
| Educational Campus Vertical Expansion | University of California procurement templates enable scalable replication across sustainability-mandated institutions. |
| ERCOT Market Participation Structuring | Real-time arbitrage algorithms maximize battery cycling returns in Texas price volatility environments. |
Methodological Framework
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions underlying this analysis. Primary interviews with microgrid control system engineers and commercial campus energy managers were cross-referenced against FERC filings, EIA project development databases, IEA distributed energy resource reports, and state utility commission ruling archives. Bottom-up installation capacity tallies by technology stack and end-use vertical were reconciled with top-down market size estimates derived from vendor revenue disclosures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling spanning product type, technology stack, end-user vertical, and application priority. Capacity expansion pipelines, IRA incentive uptake trajectories, and interconnection queue progression rates fed into CAGR derivation through iterative scenario testing. Grid reliability event frequency and wholesale market price volatility patterns informed resilience premium valuation assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by virtual power plant platform providers or Chinese inverter manufacturers with subsidized pricing would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Technology Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
China Smart Grid Network Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Power Grid Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Demand Response Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
Microgrid Market
Smart Grid
Smart Energy Switch Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Smart Grid Market