
 South and Central America Smart Grid Market | 2026-2036
South and Central America Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
South and Central America Smart Grid Market Analytics
Brazilian equipment manufacturers and system integrators is broadening their smart grid capabilities to serve the region's largest power market. Siemens AG leverages its automation portfolio to anchor large-scale distribution management deployments across the Andean region. Schneider Electric SE sustains competitive positioning through specialized energy management software tailored to Latin American grid architectures. ABB Ltd dominates high-voltage substation automation segments where technical specifications exceed regional norms.
The South and Central America Smart Grid encompasses digitally networked electricity infrastructure integrating sensors, communication protocols, and control systems to enable bidirectional power flow and real-time grid optimization, typically operating across voltage classes from 0.4 kV to 230 kV with IEC 61850 protocol compliance. Its primary purpose is to reduce technical losses, integrate renewable generation, and improve reliability across concession areas where utilities serve dispersed populations. Advanced Metering Infrastructure leads technology deployment due to regulator-mandated rollout schedules in Brazil and Colombia, while Demand Response solutions represent the fastest-expanding segment as industrial tariffs incentivize load flexibility. Cloud-Based deployment models capture growing share among mid-size utilities seeking to avoid capital-intensive on-premise infrastructure.
ANEEL in Brazil mandates smart meter penetration targets that reshape procurement patterns for distribution concessionaires. Colombia's CREG and Mexico's CRE establish complementary technical standards for grid interconnection and data security that influence product certification requirements across the regional supply chain. Stakeholders must monitor regulatory harmonization progress between national agencies to anticipate whether unified certification pathways emerge or fragmented compliance costs persist.
Market Dynamics
ANEEL's smart meter mandates are compressing deployment timelines across Brazil's distribution utilities, forcing concessionaires to accelerate procurement cycles while integrating AMI with legacy SCADA architectures.
Growth Catalysts
- ANEEL Resolution 1000:Brazil's regulatory mandate for universal smart meter coverage by 2035 creates binding procurement obligations for 63 distribution concessionaires, locking in hardware demand.
- Industrial load flexibility:São Paulo's automotive and steel sectors are deploying demand response systems to exploit time-of-use tariff differentials, creating software revenue pools.
- Colombia's CREG interconnection standards:Grid code harmonization with IEC 61850 protocols reduces integration friction for substation automation vendors serving the Andean corridor.
Market Restraints
- Copper and semiconductor input costs:Metering hardware margins compress when commodity prices spike, squeezing mid-tier Brazilian equipment suppliers without captive material sourcing.
- Technical debt in legacy distribution networks:Utilities in Peru and Chile face 15-20 year-old transformer fleets incompatible with bidirectional power flow requirements.
- CREG data localization rules:Colombian cybersecurity mandates requiring domestic data centers add 12-18 months to cloud deployment timelines for foreign platform providers.
Strategic Opportunities
- Central American microgrid integration:Costa Rica and Panama's distributed solar penetration exceeds 25% in rural concession areas, creating control system demand unmet by incumbent suppliers.
- ANEEL non-technical loss reduction targets:Brazil's 13% loss ceiling for urban distributors mandates theft-detection analytics, opening software subscription revenue streams.
- Edge-AI convergence:Real-time fault detection algorithms running on substation gateways are absorbing latency-sensitive applications previously requiring centralized control centers.
Industry Challenges
- IEC 61850 certification bottlenecks:Only two accredited labs in South America can validate protocol compliance, creating 8-10 month approval queues for new product introductions.
- Utility capex cycle misalignment:Five-year regulatory tariff reviews in Brazil delay smart grid investments to final years of concession periods, compressing implementation windows.
- SCADA-AMI integration complexity:Utilities running proprietary legacy control systems face protocol translation failures requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Central America Smart Grid Market |
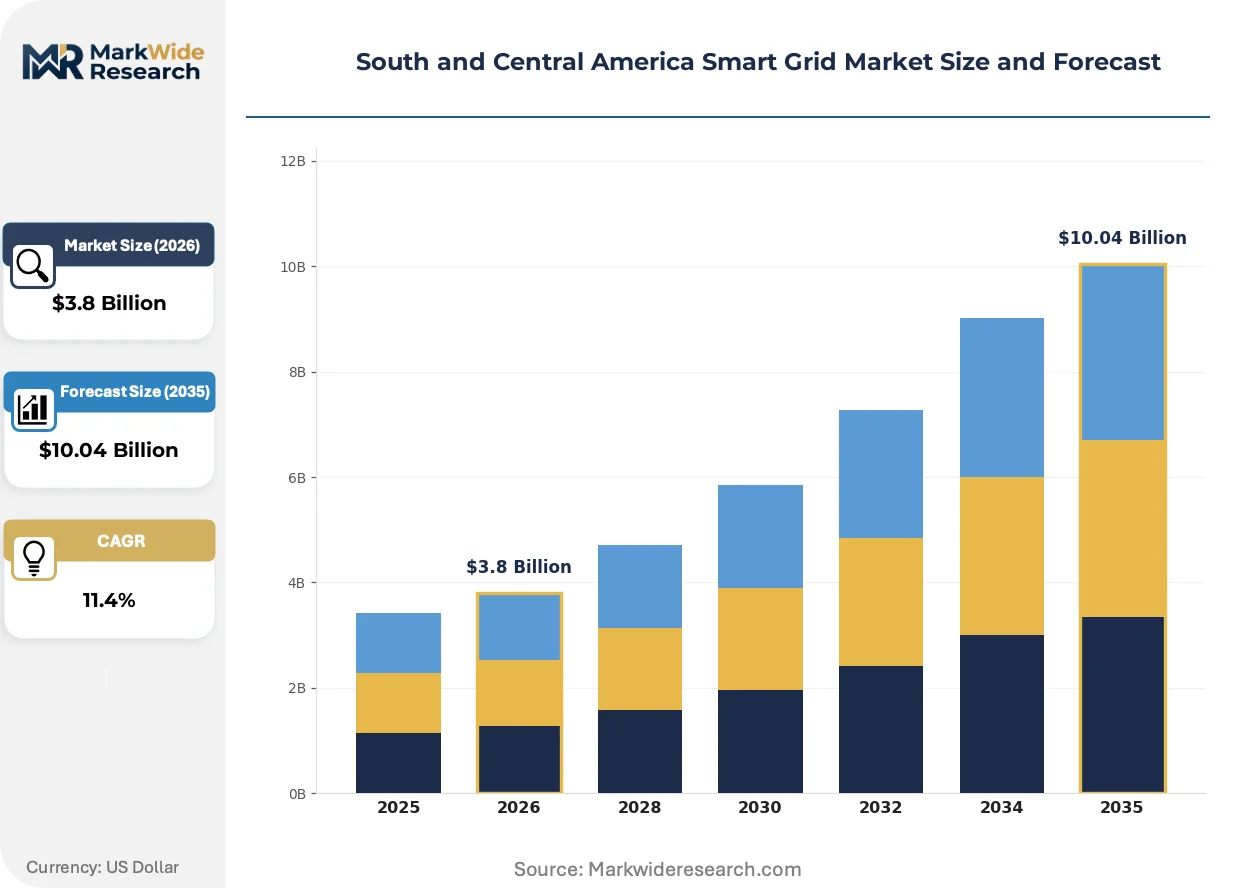
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Distribution Management Systems, Supervisory Control and Data Acquisition End User: Utilities, Industrial Sector, Commercial Buildings, Residential Users Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Energy Management, Load Forecasting, Asset Management, Outage Management |
| Companies Covered | Enel Group, Honeywell International Inc., Siemens AG, Schneider Electric SE, Itron Inc., ABB Ltd, General Electric Company, Cisco Systems Inc, Landis+Gyr Group AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Central America Smart Grid Market Evolving Landscape
Digital substation architectures are displacing conventional hardwired protection systems across the region's transmission backbone, while edge computing nodes redistribute intelligence from centralized control rooms to field equipment.
Distribution-level digital twins are absorbing planning and operations workflows previously executed through physical commissioning and manual switchgear manipulation. Brazilian utilities including Eletrobras subsidiaries are deploying these virtual models for contingency analysis, compressing outage restoration times from hours to minutes. The technology is absorbing capital previously allocated to redundant physical infrastructure.
ANEEL's regulatory sandbox framework permits concessionaires to pilot non-standard tariff structures and grid-edge services without full regulatory approval. This policy mechanism accelerates demand response and electric vehicle integration trials in São Paulo and Rio de Janeiro metropolitan zones. Distribution operators are responding by restructuring procurement specifications to accommodate bidirectional metering and dynamic pricing engines.
Industrial energy buyers are consolidating procurement authority into centralized sourcing functions, displacing plant-level maintenance departments as the primary smart grid technology decision-makers. Mining and pulp conglomerates in Minas Gerais and Paraná are negotiating enterprise-wide AMI and demand management contracts with utilities, extracting volume discounts and service-level guarantees unavailable to fragmented commercial accounts. This concentration is most visible in Brazil's southeastern industrial corridor where large load aggregators represent 40% of distribution utility revenue.
South and Central America Smart Grid Market Segmentation
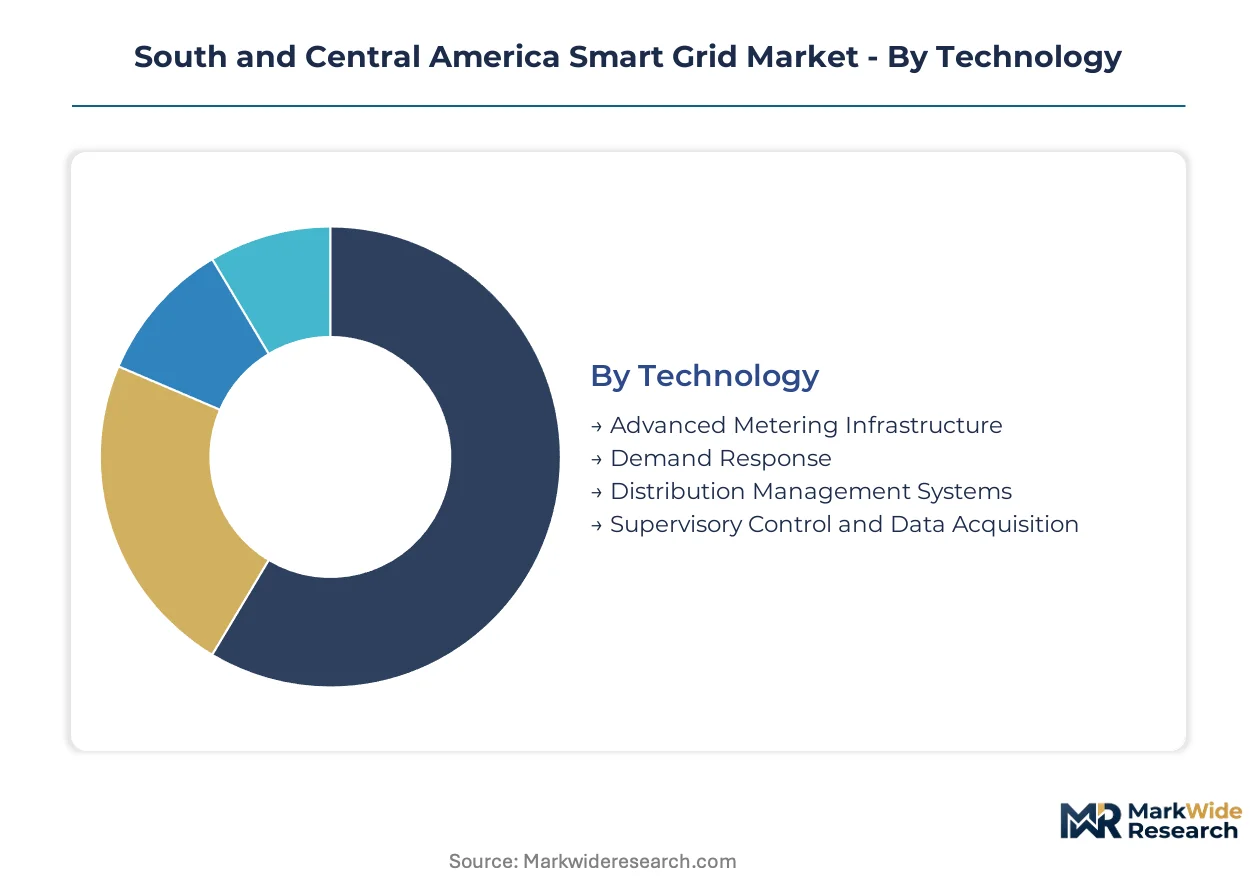
Segmentation reveals how smart grid procurement patterns diverge across technology maturity and integration complexity. Understanding these fault lines helps suppliers calibrate product roadmaps and pricing architectures for distinct buyer workflows.
Technology:
Standalone deployments dominate where legacy infrastructure resists deep integration, while embedded systems penetrate greenfield installations.
- Advanced Metering Infrastructure:Meter hardware, communication modules, and head-end systems form the foundational layer. ANEEL mandates in Brazil's southeastern industrial corridor drive procurement concentration among Eletrobras distribution subsidiaries facing binding coverage targets.
- Demand Response:Load curtailment platforms and automated dispatch systems enable price-responsive consumption. São Paulo's automotive and steel sectors deploy these systems aggressively to exploit time-of-use tariff differentials, creating software revenue pools independent of hardware cycles.
- Distribution Management Systems:Network modeling and switching optimization platforms for medium-voltage grids. Colombian utilities prioritize these for Andean corridor reliability improvements.
- Supervisory Control and Data Acquisition:Real-time monitoring infrastructure spanning substations to control centers. Legacy protocol translation challenges slow replacement cycles in Peru and Chile.
Volume placements concentrate in Advanced Metering Infrastructure; the faster expansion belongs to Demand Response.
End User:
Procurement authority is consolidating toward centralized sourcing functions, displacing fragmented plant-level decision-making.
- Utilities:Distribution concessionaires and transmission operators across Brazil, Colombia, and Chile. ANEEL's 2035 smart meter deadline compresses implementation windows for 63 Brazilian distributors.
- Industrial Sector:Mining conglomerates in Minas Gerais and pulp processors in Paraná negotiate enterprise-wide demand management contracts. These large load aggregators represent 40% of distribution utility revenue in Brazil's southeastern industrial corridor.
- Commercial Buildings:Retail and office complexes seeking sub-metering granularity. Deployment lags industrial adoption due to tariff structure misalignment.
- Residential Users:Individual households receiving smart meters through utility-mandated rollouts. Passive recipients rather than active procurement agents.
Revenue concentration sits with Utilities; Industrial Sector buyers command the steepest expansion trajectory through aggregated contracting.
Deployment:
Capital constraints and data sovereignty rules shape infrastructure location decisions across the technology stack.
- On-Premise:Dedicated hardware installations within utility control centers. Preferred by large Brazilian distributors with established IT security frameworks and available capital budgets.
- Cloud-Based:Third-party hosted platforms with subscription pricing. Mid-size utilities in Colombia and Central America adopt these to avoid capital-intensive infrastructure, though CREG data localization rules add 12-18 months to deployment timelines.
- Hybrid:Split architectures retaining critical control functions on-premise while pushing analytics to cloud layers. Emerging preference for substation automation projects.
- Edge Computing:Real-time processing nodes deployed to field equipment. Fault detection algorithms on substation gateways are absorbing latency-sensitive applications previously requiring centralized control centers.
Current procurement favors On-Premise for mission-critical systems; Cloud-Based models are climbing the fastest among resource-constrained mid-tier utilities.
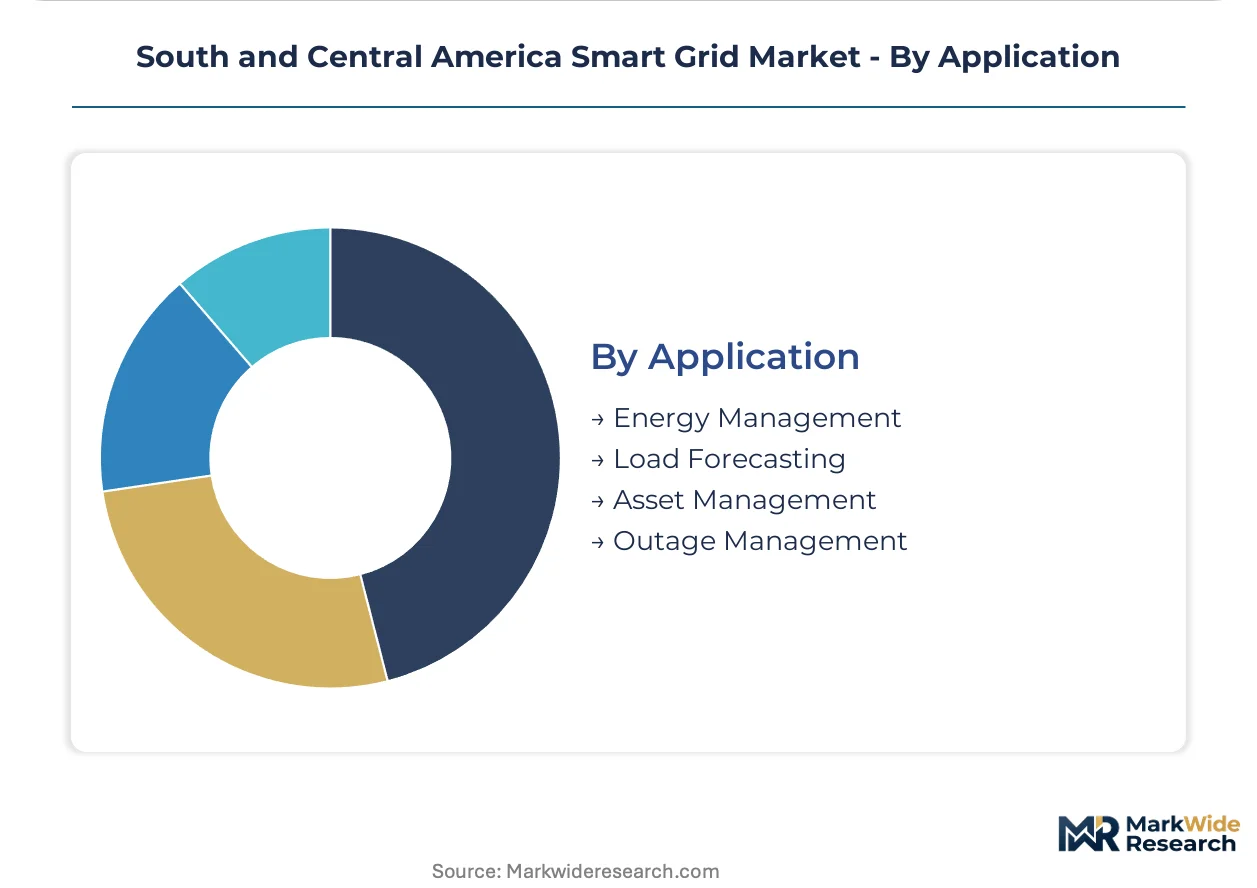
Application:
Functional priorities shift with grid stress patterns and regulatory incentive structures.
- Energy Management:Real-time consumption monitoring and optimization dashboards. Industrial buyers in Brazil's automotive sector deploy these for tariff arbitrage.
- Load Forecasting:Predictive analytics for demand planning and resource scheduling. Integration with AMI data streams improves accuracy for Brazilian distributors.
- Asset Management:Transformer health monitoring and predictive maintenance workflows. Critical for Peru and Chile utilities managing 15-20 year-old transformer fleets.
- Outage Management:Fault location, isolation, and restoration systems. Digital twin deployments by Eletrobras subsidiaries compress restoration times from hours to minutes.
Deployment density peaks in Energy Management; Outage Management is gaining share fastest through digital twin convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper deposits in Chile's Atacama Desert and northern mining belts supply critical conductor materials for regional grid infrastructure, anchoring procurement networks that extend into Brazilian and Colombian distribution markets.
Brazil
ANEEL's Resolution 1000 mandates universal smart meter coverage by 2035, binding 63 distribution concessionaires to accelerated procurement timelines. Eletrobras subsidiaries in the southeastern industrial corridor spanning São Paulo and Minas Gerais states deploy AMI systems at scale to meet binding coverage targets. Mining conglomerates in Minas Gerais negotiate enterprise-wide demand management contracts that concentrate procurement authority.
Colombia
CREG interconnection standards harmonize with IEC 61850 protocols, reducing integration friction for substation automation vendors. The Andean corridor utilities prioritize distribution management systems for reliability improvements across mountainous terrain. Bogotá-based distributors accelerate cloud-based deployments despite data localization rules adding deployment complexity.
Chile
Utilities manage 15-20 year-old transformer fleets incompatible with bidirectional power flow requirements, creating asset replacement demand. The central bank's infrastructure financing programs support grid modernization in Santiago's metropolitan distribution zones. Northern mining operations drive industrial demand response adoption for tariff arbitrage.
Peru
Technical debt in legacy SCADA architectures slows replacement cycles as utilities prioritize AMI integration over control system upgrades. The Ministry of Energy and Mines promotes rural electrification programs that absorb smart metering hardware. Lima's coastal industrial zone concentrates early demand response pilots among textile and food processors.
Mexico
CRE establishes technical standards for grid interconnection and data security that influence product certification across regional supply chains. Northern border states deploy smart grid infrastructure to support cross-border industrial load management. Monterrey's manufacturing cluster drives private microgrid development for energy resilience.
South and Central America Smart Grid Market Competitive Landscape
Global majors compete with regional champions across technology integration depth, with European automation conglomerates holding dominant positions in high-voltage substation segments while Brazilian system integrators capture distribution-level deployment contracts. The vendor structure tiers across three archetypes: full-stack automation conglomerates, specialized metering hardware suppliers, and regional system integration firms. Strategic moves concentrate on AMI-legacy SCADA protocol translation capabilities and edge-AI algorithm development for fault detection applications.
Within the full-stack automation tier, Siemens AG and ABB Ltd occupy positions exemplifying integrated hardware-software portfolios, while Schneider Electric SE anchors specialized energy management software positioning. Among metering-focused suppliers, Itron Inc. and Landis+Gyr Group AG represent hardware-centric archetypes serving regulator-mandated rollout schedules. These named entities illustrate competitive positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Enel Group |
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric SE |
| Itron Inc. |
| ABB Ltd |
| General Electric Company |
| Cisco Systems Inc |
| Landis+Gyr Group AG |
| Others |
Value Network & Pricing Analysis
ANEEL's 2035 universal smart meter mandate gates both qualified supply access and premium-tier pricing power, restricting procurement eligibility to vendors with IEC 61850 certification and domestic manufacturing presence while compressing margins for non-compliant hardware tiers.
Pricing Analysis
Warranty and service bundling separates premium-tier offerings from unbundled economy alternatives, with full-stack automation conglomerates anchoring pricing around 10-year service contracts while mid-tier Brazilian suppliers compete on transactional hardware-only terms. Price differentiation hinges on certification grade and after-sales service depth, with ANEEL-mandated protocol compliance creating tier separation. Pricing pressure stems from copper and semiconductor input volatility squeezing mid-tier equipment suppliers without captive material sourcing. Industrial buyers in São Paulo's automotive sector demonstrate lowest price sensitivity due to tariff arbitrage value capture, while residential utility-mandated rollouts drive volume procurement at compressed margins.
Supply Chain Analysis
Brazil's local-content rules under ANEEL Resolution 1000 reshape sourcing patterns, mandating domestic manufacturing presence for smart meter eligibility and forcing foreign suppliers into joint ventures with Brazilian system integrators. Geographic supply concentration centers on Brazil, China, and Germany for metering hardware, with semiconductor components drawing from Taiwan and South Korea. Raw material dependencies span copper conductors, silicon wafers, and lithium-ion battery cells for field equipment backup power. Single-source vulnerability around IEC 61850-certified protocol stacks creates approval bottlenecks. Distribution runs through utility concessionaire procurement departments with five-year regulatory tariff review cycles compressing implementation windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
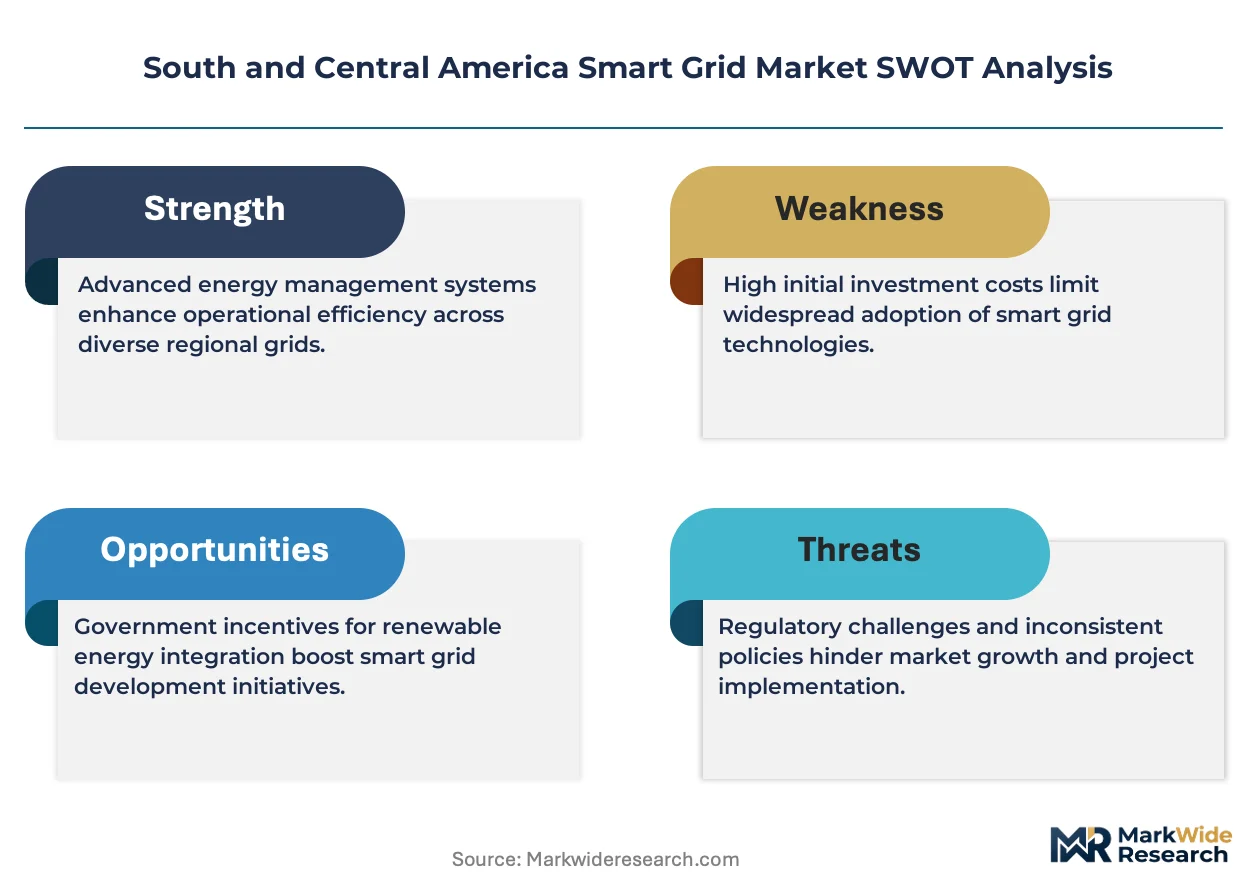
ANEEL's binding smart meter mandates transform this market into a cost-of-compliance story, where certification investment and domestic manufacturing presence erect barrier-to-entry moats that favor established players with regulatory relationships and accredited testing access.
For Market Incumbents: Anchor defensive positioning through backward integration into semiconductor sourcing and captive copper supply arrangements, insulating margin structures from commodity volatility while accelerating IEC 61850 certification pipelines to exploit 8-10 month lab approval queues as competitive moats against unqualified entrants. For New Entrants and Emerging Players: Begin with Central American microgrid integration opportunities in Costa Rica and Panama, where distributed solar penetration exceeds 25% in rural concession areas and control system demand remains unmet by incumbent suppliers, leveraging cloud-based deployment models to bypass capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: ANEEL regulatory sandbox approvals for non-standard tariff pilots are the leading indicator that demand response and electric vehicle integration trials are scaling toward commercial deployment, signaling long-term viability for edge-AI algorithm developers and dynamic pricing engine specialists as acquisition targets with 5-10 year technology relevance windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive silicon supply secures margin stability against Taiwan foundry pricing volatility for Brazilian equipment manufacturers. |
| IEC 61850 Certification Pipeline Expansion | Accelerated lab accreditation captures procurement eligibility ahead of ANEEL's 2035 coverage deadline for concessionaires. |
| Cloud-Based Platform Development | Subscription pricing models penetrate mid-tier Colombian utilities facing CREG data localization compliance timelines. |
| Edge-AI Algorithm Commercialization | Real-time fault detection on substation gateways displaces centralized control center investments for latency-sensitive applications. |
| Central American Microgrid Partnership | Rural electrification programs in Costa Rica and Panama absorb distributed solar control systems from non-incumbent suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with utility planning officers, AMI procurement managers, substation automation engineers, and distribution concessionaire executives with validation against ANEEL resolutions, CREG technical standards, and IEC protocol documentation, employing bottom-up equipment shipment tracking and top-down grid investment flow analysis for triangulation.
Granularity-level modeling deployed technology-segment, end-user-category, and deployment-mode dimensions at country-level resolution across Brazil, Colombia, Chile, Peru, and Mexico, with voltage-class and application-function cross-tabs for substation automation projects, deriving CAGRs from regulatory mandate timelines and utility capex cycle alignment patterns while incorporating copper price elasticity and semiconductor lead time volatility as industry-specific forecast inputs.
Regulatory schedule slippage, commodity price spikes, and certification lab capacity constraints are the dominant revision risks to modeled outputs, with forecasts reflecting documented assumptions around ANEEL enforcement consistency and CREG harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Power Grid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Smart Grid Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Smart Microgrid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
North America Smart Grid Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Asia-Pacific Smart Grid Network Market