
 GCC Smart Grid Security Market | 2026-2036
GCC Smart Grid Security Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Smart Grid Security Market Intelligence
The UAE Telecommunications and Digital Government Regulatory Authority's critical infrastructure protection mandate is rebalancing capital allocation toward encrypted network segmentation and continuous monitoring architectures. Cisco Systems Inc leverages its Gulf-distributed threat intelligence nodes to sustain preemptive vulnerability assessment contracts with Saudi Electricity Company. BAE Systems Plc anchors its regional footprint through sovereign-level cybersecurity operations centers serving Abu Dhabi National Oil Company subsidiaries. Siemens AG competes by embedding IEC 62351-compliant security stacks directly into its substation automation hardware, reducing integration friction for Gulf utilities.
GCC smart grid security encompasses hardware, software, and service layers engineered to protect advanced metering infrastructure, distribution automation networks, and energy management systems from unauthorized access, data manipulation, and service disruption. These systems employ cryptographic protocols meeting IEC 62351 and NIST SP 800-53 standards, with latency thresholds below 10 milliseconds for real-time anomaly detection in substation communication networks. Encryption solutions currently dominate product-type revenue as Gulf utilities retrofit legacy SCADA links with AES-256 tunneling, while AI-based solutions within the technology dimension represent the fastest-expanding segment as Saudi Aramco and ADNOC deploy machine-learning-driven behavioral analytics across their grid-connected industrial campuses. Cloud-based deployment models are gaining traction among smaller Emirates-based utilities seeking to avoid capital-intensive on-premises security operations centers.
Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority enforce mandatory incident reporting and baseline security controls for all energy sector operators, directly shaping procurement specifications in utility tenders. The Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology are converging on IEC 62351 adoption timelines, creating unified compliance expectations across the six GCC states. Stakeholders must monitor whether Bahrain, Kuwait, Oman, and Qatar accelerate their national cybersecurity authority formations to match Saudi and Emirati enforcement intensity, as this divergence will fragment or consolidate vendor certification requirements across the Gulf.
Market Dynamics
State-owned utilities across Saudi Arabia and the UAE are accelerating procurement of AI-based intrusion detection systems as grid digitization deepens, tightening compliance thresholds for critical infrastructure operators throughout the Gulf Cooperation Council.
Growth Catalysts
- IEC 62351 Convergence:Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority are converging on unified adoption timelines, creating harmonized procurement specifications across utility tenders in both countries.
- Smart City Cluster Expansion:Riyadh-anchored smart city developments and Dubai Silicon Oasis energy innovation corridors are generating concentrated demand for encrypted network segmentation and continuous monitoring architectures.
- AI-Based Behavioral Analytics:Machine-learning-driven anomaly detection systems are displacing signature-based intrusion prevention in substation automation networks, with latency thresholds compressing below 10 milliseconds for real-time response.
Market Restraints
- Legacy SCADA Retrofit Costs:AES-256 tunneling deployment across decades-old distribution automation networks requires substantial capital reallocation, stretching procurement cycles for smaller Emirates-based utilities.
- Vendor Certification Fragmentation:Divergent national cybersecurity authority formation timelines across Bahrain, Kuwait, Oman, and Qatar risk fragmenting vendor certification requirements and compliance testing protocols.
- Specialized Talent Scarcity:Gulf utilities face acute shortages of cybersecurity engineers with dual expertise in IEC 62351 cryptographic protocols and industrial control systems architecture.
Strategic Opportunities
- Cloud-Based Security Operations:Smaller utilities in Oman and Bahrain are bypassing capital-intensive on-premises security operations centers through managed detection and response services hosted in regional cloud infrastructure.
- Substation Automation Integration:Security stack embedding directly into hardware platforms reduces integration friction, creating white space for vendors offering pre-certified IEC 62351-compliant modules.
- Sovereign-Level Operations Centers:Abu Dhabi National Oil Company subsidiaries and Saudi Aramco industrial campuses are establishing dedicated cybersecurity command facilities, opening service contract opportunities for specialized integrators.
Industry Challenges
- Multi-Vendor Interoperability:Distribution automation networks combining Siemens, Cisco, and BAE Systems components require complex API harmonization and protocol translation layers.
- Incident Reporting Mandate Compliance:Mandatory breach disclosure requirements enforced by Saudi Arabia's National Cybersecurity Authority impose operational overhead on understaffed security teams.
- Real-Time Anomaly Detection Tuning:Machine-learning models trained on European or North American grid data generate false positives when deployed across Gulf-specific load profiles and climate-induced demand patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Smart Grid Security Market |
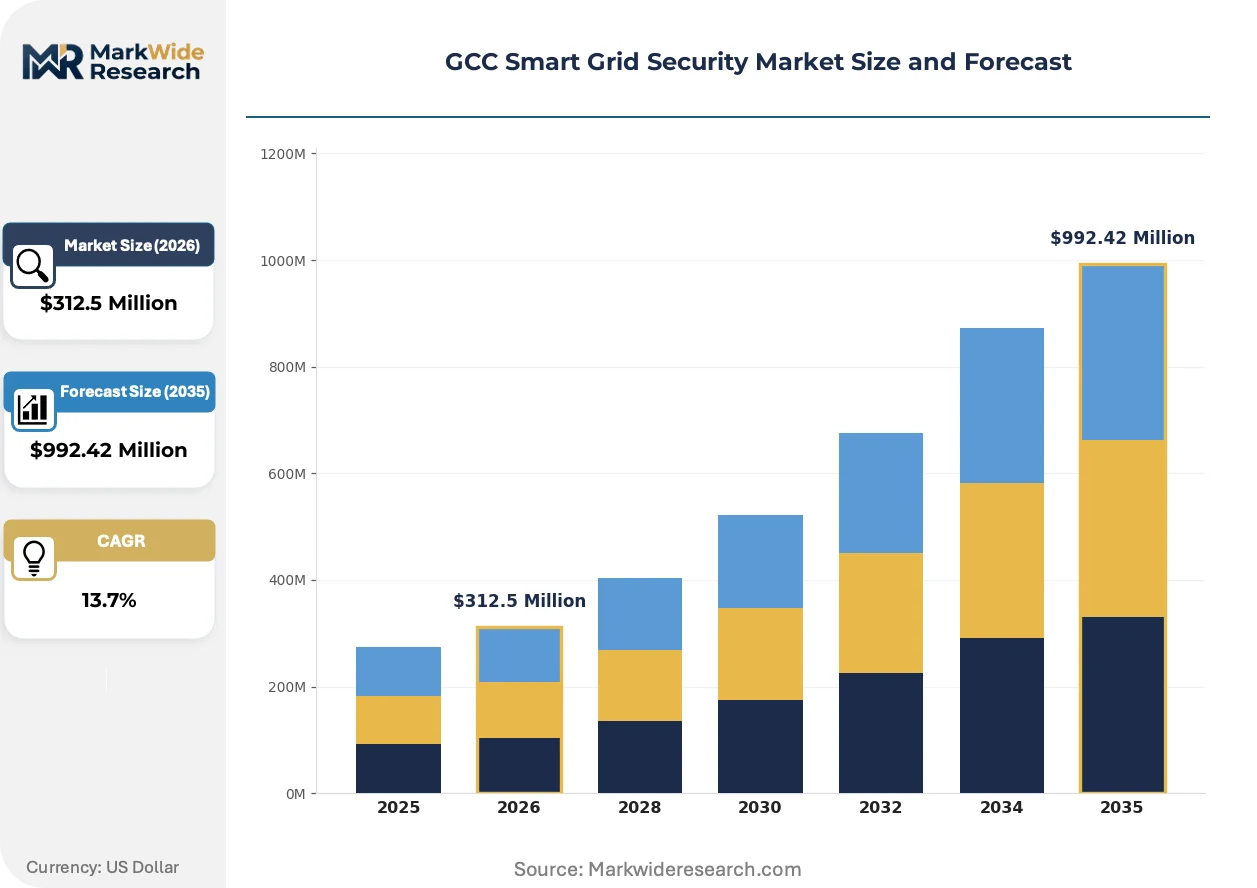
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $992.42 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewalls, Intrusion Detection Systems, Antivirus Software, Encryption Solutions End User: Utilities, Government Agencies, Industrial Sector, Commercial Establishments Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: AI-Based Solutions, Blockchain Technology, IoT Security, Network Security |
| Companies Covered | Cisco Systems Inc, BAE Systems Plc, Siemens AG, Eaton Corporation plc, Lockheed Martin Corporation, ABB Ltd, International Business Machines Corporation, Leidos Holdings Inc, Schneider Electric SE, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Smart Grid Security Market Strategic Shifts & Innovations
Grid security architecture is modularizing around software-defined perimeters and zero-trust network access, compressing the traditional hardware-software-service stack into integrated platforms that reduce deployment friction for Gulf utilities.
Security orchestration platforms are modularizing threat detection, incident response, and compliance reporting into discrete microservices that utilities can deploy incrementally. Saudi Electricity Company and ADNOC subsidiaries are piloting containerized security modules at substation edge nodes. This modularization is compressing vendor lock-in and enabling multi-supplier architectures that were previously technically infeasible.
Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority are tightening mandatory baseline security controls and incident reporting timelines for all energy sector operators. These mandates are rebalancing capital allocation toward encrypted network segmentation and continuous monitoring architectures. Advanced metering infrastructure deployments in Riyadh and Dubai are experiencing the most acute compliance-driven procurement acceleration.
Utility procurement teams are unbundling after-sales service contracts from initial hardware and software acquisitions, creating separate competitive bidding streams for multi-year managed security operations. This unbundling is compressing margins for traditional equipment vendors while opening recurring revenue opportunities for specialized Gulf-based cybersecurity service providers. The shift is most visible among mid-sized utilities in Kuwait and Qatar seeking operational expenditure flexibility over capital-intensive ownership models.
GCC Smart Grid Security Market Segmentation
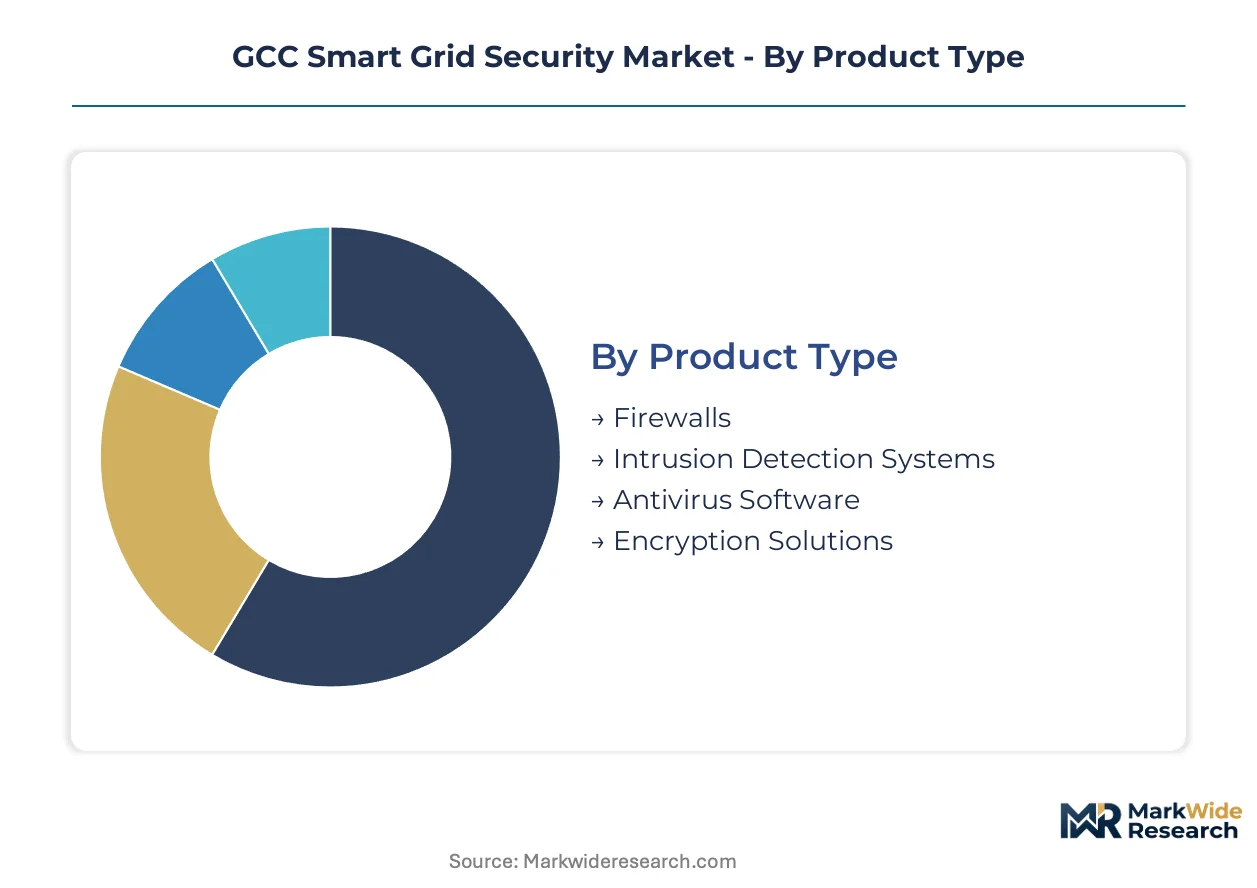
GCC utilities segment procurement across four intersecting dimensions: protective technology stacks, operational deployment models, customer risk profiles, and underlying technical architectures. Procurement specifications from Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority shape how these categories combine in competitive tenders.
Product Type:
Technical specifications for grid protection layer according to IEC 62351 cryptographic mandates and latency thresholds for real-time substation communication.
- Encryption Solutions:AES-256 tunneling protocols dominate retrofit contracts as Saudi Electricity Company and Abu Dhabi National Oil Company subsidiaries replace legacy SCADA links. Gulf utilities prioritize hardware security modules with sub-10 millisecond latency for distribution automation networks.
- Intrusion Detection Systems:Signature-based platforms are yielding to behavioral analytics in Riyadh-anchored smart city clusters and Dubai Silicon Oasis corridors. AI-enhanced variants command premium positioning in tenders from state-owned utilities with sovereign-level security mandates.
- Firewalls:Next-generation platforms with deep packet inspection for industrial protocols secure perimeter boundaries at substation edge nodes.
- Antivirus Software:Endpoint protection tailored for Windows-based SCADA workstations and engineering stations remains standard in older infrastructure.
Mature deployment sits with Encryption Solutions. Newer deployment is concentrated in Intrusion Detection Systems.
End User:
Procurement scale and compliance intensity vary sharply across customer types, with sovereign-backed entities driving specification elevation.
- Utilities:State-owned transmission and distribution operators in Saudi Arabia and the UAE anchor volume demand, mandating IEC 62351-compliant architectures across advanced metering infrastructure and substation automation. Procurement cycles stretch 18-36 months for integrated security operations centers.
- Industrial Sector:Saudi Aramco and ADNOC industrial campuses deploy machine-learning-driven behavioral analytics across grid-connected facilities, generating concentrated demand for encrypted network segmentation.
- Government Agencies:National cybersecurity authorities and regulatory bodies purchase threat intelligence and audit services rather than operational technology.
- Commercial Establishments:Large commercial and residential developments in Dubai and Riyadh purchase managed security services for building-level energy management systems.
Volume concentration rests with Utilities. Specification elevation is climbing fastest in Industrial Sector.
Deployment Model:
Capital availability and operational expertise determine whether Gulf operators own, lease, or outsource security infrastructure.
- On-Premises:Saudi Electricity Company and major Emirates utilities maintain dedicated security operations centers with 24/7 analyst staffing, absorbing capital intensity for control retention.
- Cloud-Based:Smaller utilities in Oman and Bahrain bypass capital expenditure through regional cloud-hosted managed detection and response services.
- Hybrid:Split architectures segment critical substation controls on-premises while pushing analytics and reporting to cloud infrastructure.
- Managed Services:Multi-year operational contracts unbundled from hardware procurement are gaining traction among mid-sized utilities in Kuwait and Qatar seeking expenditure flexibility.
Control retention favors On-Premises. Fastest expansion trajectory belongs to Managed Services.
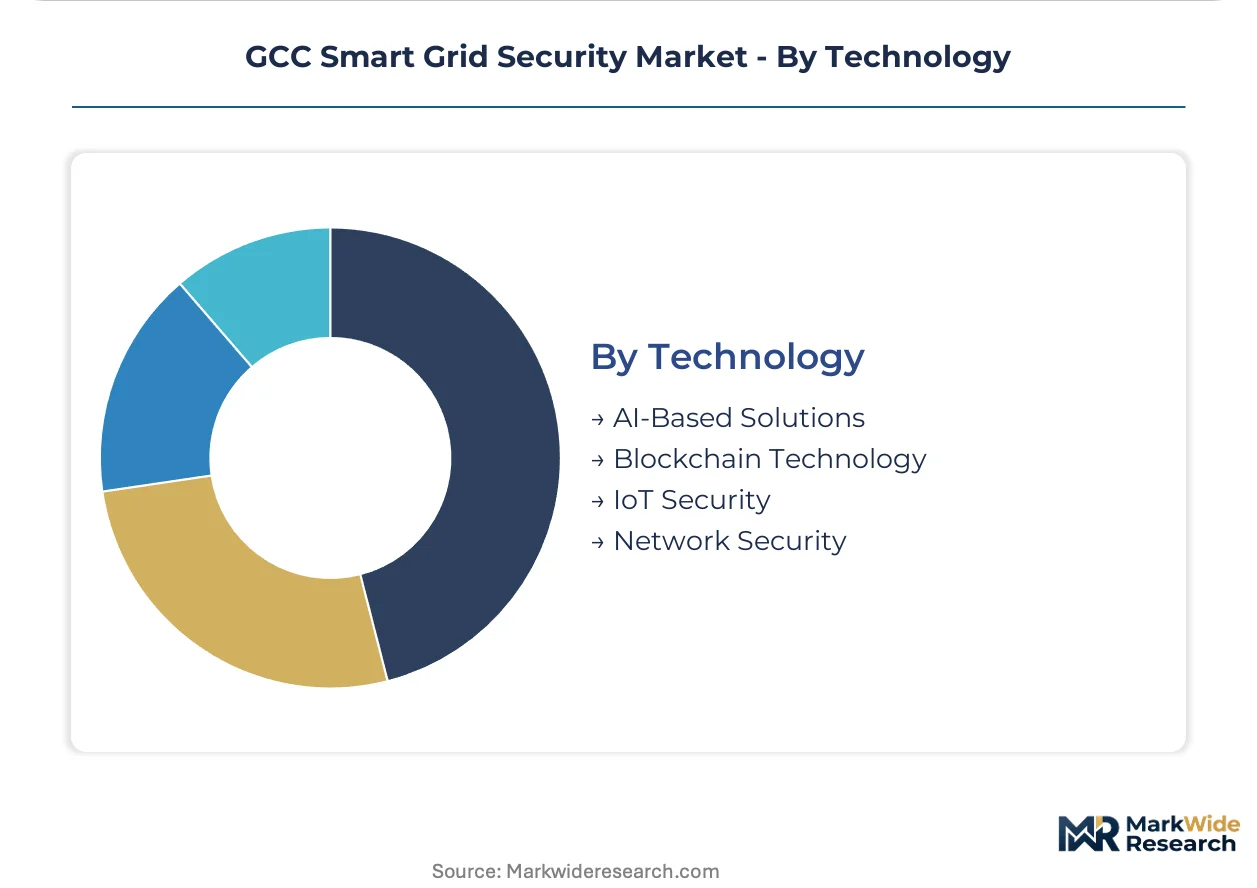
Technology:
Underlying technical architectures differentiate vendor positioning from commodity network protection to predictive threat intelligence.
- AI-Based Solutions:Machine-learning models trained on Gulf-specific load profiles and climate-induced demand patterns displace European-trained systems that generate false positives. Saudi Aramco and ADNOC deployments are compressing latency thresholds below 10 milliseconds for real-time anomaly response.
- Network Security:Software-defined perimeters and zero-trust architectures modularize around encrypted tunneling for legacy SCADA integration, reducing deployment friction.
- IoT Security:Lightweight cryptographic protocols protect distributed sensors and actuators in advanced metering infrastructure deployments across Riyadh and Dubai.
- Blockchain Technology:Distributed ledger applications for tamper-evident audit trails remain pilot-stage in Saudi Electricity Company innovation programs.
Proven deployment concentrates in Network Security. Steepest expansion trajectory is in AI-Based Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Silicon Oasis and Saudi Arabia's King Abdullah Economic City concentrate smart grid security procurement through tax-incentive zones purpose-built for energy technology clusters. These special economic zones anchor regional demand.
Saudi Arabia
Riyadh-anchored smart city developments and NEOM's northwest corridor drive AES-256 tunneling deployments across advanced metering infrastructure. The National Cybersecurity Authority enforces mandatory incident reporting timelines for all energy sector operators. Eastern Province industrial campuses host Saudi Aramco's machine-learning-driven behavioral analytics pilots.
United Arab Emirates
Abu Dhabi National Oil Company subsidiaries and Dubai Electricity and Water Authority anchor volume demand for encrypted network segmentation. The Telecommunications and Digital Government Regulatory Authority mandates baseline security controls through critical infrastructure protection frameworks. Dubai Silicon Oasis energy innovation corridors concentrate sovereign-level cybersecurity operations center contracts.
Kuwait
Mid-sized utilities are unbundling after-sales service contracts from hardware acquisitions to secure operational expenditure flexibility. The Ministry of Electricity and Water awaits formal national cybersecurity authority formation to match Saudi and Emirati enforcement intensity. Al-Zour South power complex developments are accelerating procurement of managed detection and response services.
Oman
Smaller utilities bypass capital-intensive on-premises security operations centers through regional cloud-hosted architectures. The National Cybersecurity Agency is developing compliance frameworks converging toward IEC 62351 adoption timelines. Muscat metropolitan grid modernization projects are deploying lightweight cryptographic protocols for distributed sensor networks.
Qatar
Utility procurement teams are compressing vendor lock-in through modular security orchestration platforms. The National Cyber Security Agency is aligning critical infrastructure mandates with GCC-wide standardization efforts. Lusail smart city infrastructure integrates zero-trust network access for building-level energy management systems.
GCC Smart Grid Security Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service layers. The vendor base clusters around three strategic archetypes: industrial automation incumbents embedding security stacks into substation hardware, network infrastructure specialists supplying encrypted tunneling protocols, and sovereign-defense contractors operating dedicated cybersecurity command facilities. Competitive positioning hinges on pre-certified IEC 62351 compliance and multi-year managed service contract capture.
Within the industrial automation tier, Siemens AG and ABB Ltd exemplify European-based conglomerates leveraging embedded security architectures. Schneider Electric SE anchors the French-origin specialist position. Among network infrastructure providers, Cisco Systems Inc represents US-based technology platforms. BAE Systems Plc and Lockheed Martin Corporation occupy positions within the defense-contractor archetype serving sovereign-level operations centers. These named entities illustrate how competitive dynamics fragment across technical specializations rather than consolidating around unified platform dominance.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| BAE Systems Plc |
| Siemens AG |
| Eaton Corporation plc |
| Lockheed Martin Corporation |
| ABB Ltd |
| International Business Machines Corporation |
| Leidos Holdings Inc |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority are tightening mandatory IEC 62351 compliance timelines, forcing suppliers to accelerate certification cycles and compress margins on non-compliant inventory.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Gulf utilities face compressed procurement windows tied to regulatory deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because smaller Emirates-based utilities prioritize operational expenditure flexibility over capital-intensive ownership. State-owned transmission operators exhibit least price sensitivity, while mid-sized utilities in Oman and Bahrain drive hardest bargain on unit economics.
Supply Chain Analysis
Reverse logistics flows remain underdeveloped for hardware security modules and substation automation components, creating aftermarket service gaps. Manufacturing concentrates in Germany, the United States, and Japan for industrial-grade cryptographic hardware. Supply chains draw from specialized semiconductor foundries, IEC-certified firmware developers, and regional systems integrators. Single-source vulnerability sits with proprietary cryptographic chip architectures. Distribution runs through authorized vendor channels and sovereign-level cybersecurity operations center contractors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cybersecurity engineering talent scarcity props pricing power for vendors with pre-certified IEC 62351 compliance and established Gulf delivery capabilities.
For Market Incumbents: Acquire machine-learning behavioral analytics platforms to counter displacement threat from AI-native entrants. Integrate security stacks directly into substation automation hardware to reduce customer integration friction. Pursue backward integration into cryptographic module manufacturing to capture margin from semiconductor supply constraints. For New Entrants and Emerging Players: Regional cloud service providers offer fastest channel access for managed detection and response services targeting smaller utilities in Bahrain and Oman. White space concentrates in containerized security microservices for substation edge nodes. Lead with operational expenditure pricing models to bypass capital budget approval cycles. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play AI security vendors given Saudi Aramco and ADNOC behavioral analytics deployment acceleration. Long-term viability favors specialists with dual expertise in IEC 62351 protocols and Gulf-specific grid architectures. Monitor national cybersecurity authority formation timelines across Kuwait, Qatar, and Oman for regulatory harmonization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI Security Platform Acquisition | Machine-learning behavioral analytics displace signature-based systems at Saudi Electricity Company. |
| IEC 62351 Certification Investment | Pre-certified modules reduce procurement friction with National Cybersecurity Authority mandates. |
| Managed Detection and Response Launch | Cloud-hosted services bypass capital constraints for smaller utilities in Oman and Bahrain. |
| Sovereign Operations Center Partnership | ADNOC and Saudi Aramco campuses generate multi-year service contract visibility. |
| Substation Hardware Integration | Embedded security stacks reduce API harmonization complexity for multi-vendor networks. |
Research Approach
Document review covered regulatory filings from Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority, complemented by interviews with utility cybersecurity officers, industrial control systems engineers, and managed security service providers. Secondary sources included IEC standards documentation, GCC utility procurement tender databases, and substation automation technical specifications. Bottom-up segment sizing triangulated against top-down market aggregation.
Historical deployment trajectories were cross-referenced against panel input from grid operators and security vendors to validate adoption curve assumptions across the projection horizon. Segmentation dimensions modeled include protective technology stack, deployment model, end-user risk profile, and underlying technical architecture. CAGRs were derived from utility capital expenditure patterns and regulatory compliance deadline clustering. Forecast inputs incorporated AI adoption rates in substation networks and cloud migration timelines for smaller utilities.
Caveats apply where national cybersecurity authority formation delays or IEC 62351 timeline extensions could materially shift the outlook. Practitioners should monitor regulatory harmonization progress across Bahrain, Kuwait, Oman, and Qatar for early signals of procurement specification convergence or fragmentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Smart Grid Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Smart Grid Network Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market