
 United States Smart Grid Security Market | 2026-2036
United States Smart Grid Security Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Grid Security Market Intelligence
Buyer concentration among electric utilities is shifting as smaller municipal and cooperative utilities accelerate cybersecurity procurement alongside large investor-owned operators. IBM leverages its hybrid cloud security portfolio to anchor enterprise-scale utility deployments. Dragos Inc. specializes in industrial control system threat intelligence for power sector infrastructure. Cisco Systems Inc. competes through network-layer segmentation products tailored to substation environments.
United States Smart Grid Security encompasses hardware, software, and services that protect generation, transmission, and distribution systems from cyber intrusions, data manipulation, and operational disruption, with encryption standards typically requiring AES-256 or quantum-resistant algorithms for command-and-control communications. The primary purpose is maintaining grid reliability while enabling two-way digital flows between utilities and distributed energy resources. AI & Machine Learning technology leads investment as utilities deploy behavioral analytics for anomaly detection in SCADA and AMI networks. Cloud Security is gaining share fastest among deployment models, though on-premises architectures still dominate critical generation facilities where air-gapped requirements persist. Encryption Solutions command premium margins as NERC CIP compliance deadlines harden key management obligations.
FERC, NERC, and CISA collectively shape demand through mandatory reliability standards, incident reporting requirements, and cross-sector threat briefings that force utilities into continuous security refresh cycles. The Infrastructure Investment and Jobs Act channels federal funding toward grid modernization with cybersecurity strings attached, accelerating vendor qualification timelines. Stakeholders must monitor how NERC CIP version 7 evolutions and state-level public utility commission rulings reshape procurement specifications before committing to multi-year platform investments.
Market Dynamics
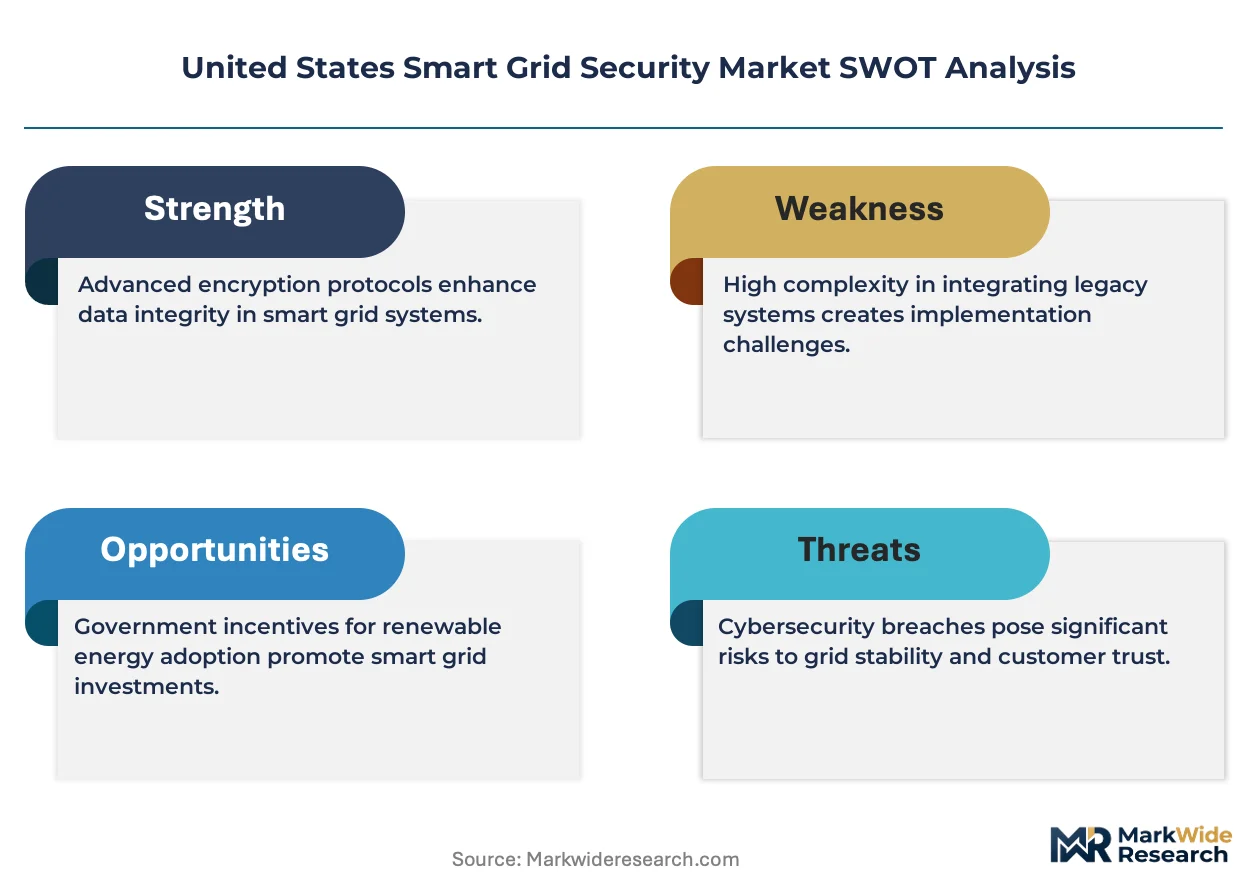
NERC CIP enforcement tightening around critical cyber assets is forcing utilities into continuous security refresh cycles, compressing vendor qualification timelines and elevating procurement urgency for encryption and monitoring platforms.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation mandates expand attack surfaces across Texas and California, requiring utilities to deploy edge security for bidirectional grid communications.
- AI-driven threat detection:Behavioral analytics platforms are accelerating adoption as utilities automate anomaly detection across SCADA and AMI networks.
- Rural electric cooperatives:Smaller municipal utilities are accelerating cybersecurity procurement to meet NERC CIP compliance deadlines previously dominated by investor-owned operators.
Market Restraints
- Quantum-resistant algorithm migration:AES-256 replacement timelines create technical debt as utilities balance backward compatibility with post-quantum cryptographic standards.
- Air-gapped facility requirements:On-premises deployment mandates at critical generation sites limit cloud security adoption despite operational efficiency gains.
- Specialized ICS talent scarcity:Industrial control system security expertise concentrates among limited consulting pools, inflating implementation costs for mid-tier utilities.
Strategic Opportunities
- Texas ERCOT grid modernization:Renewable integration and battery storage expansion create demand for distributed energy resource cybersecurity in the state's deregulated market structure.
- Infrastructure Investment and Jobs Act funding:Federal cybersecurity strings attached to grid modernization grants accelerate vendor qualification for compliant solution providers.
- Edge computing convergence:Integration of containerized security workloads with substation automation systems enables real-time threat response without core network dependency.
Industry Challenges
- Multi-vendor interoperability:Integration complexity across heterogeneous SCADA, DMS, and AMI platforms from different eras creates configuration vulnerabilities.
- NERC CIP version 7 transition:Evolving compliance specifications force utilities to defer multi-year platform commitments until regulatory clarity stabilizes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Grid Security Market |
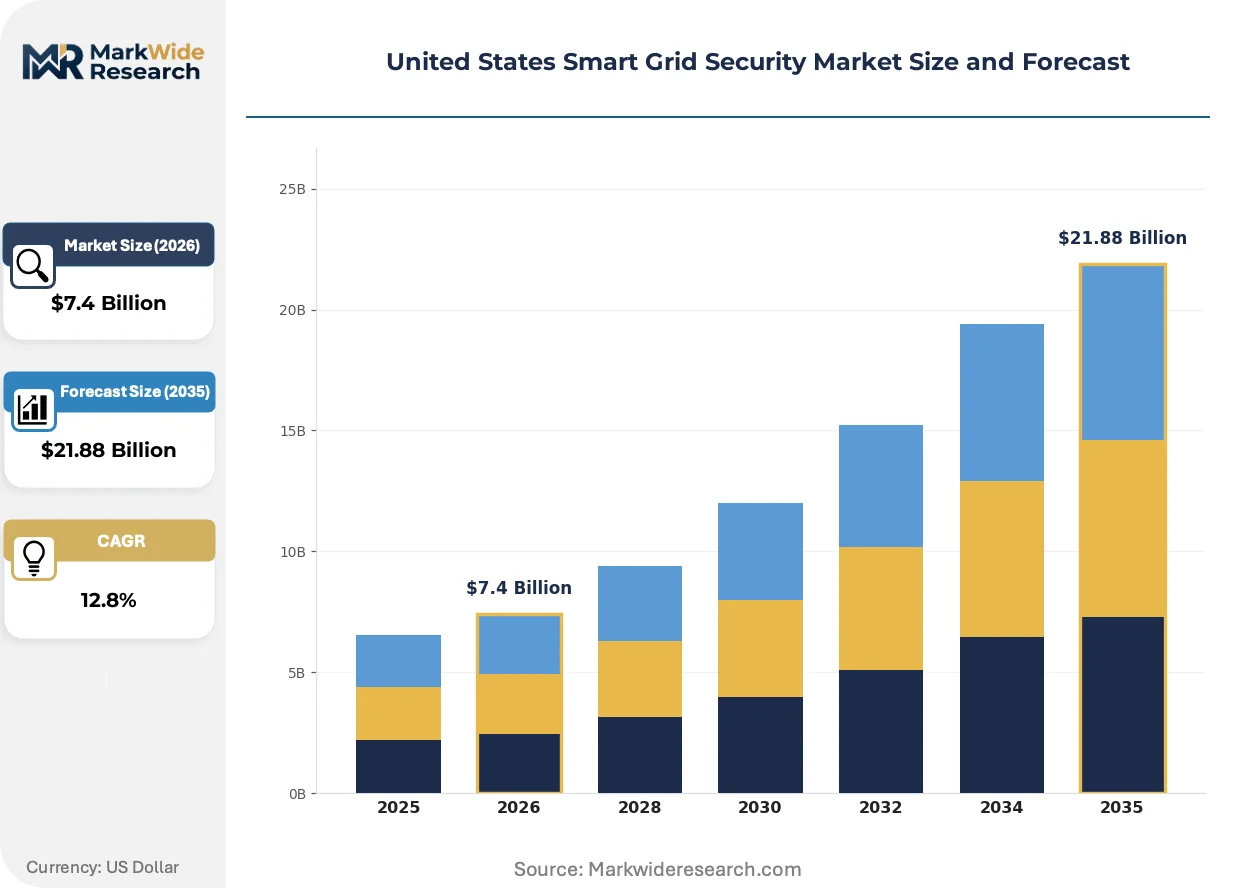
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $21.88 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Detection Systems, Firewalls, Antivirus Software, Encryption Solutions Technology: AI & Machine Learning, Blockchain, Quantum Cryptography, Cloud Security End User: Utilities, Government, Industrial, Commercial Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | IBM, Lockheed Martin Corporation, Cisco Systems Inc., IOActive, BAE Systems Plc, Honeywell International Inc., Dragos Inc., Claroty Ltd., Leidos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Grid Security Market Strategic Shifts & Innovations
Security architecture is fragmenting across edge, core, and cloud layers as utilities reconcile operational technology isolation with digital transformation imperatives. This structural tension favors vendors offering unified policy management across deployment models.
Zero-trust network architecture is modularizing access control for substation environments. Mid-sized municipal utilities in the Southwest are adopting microsegmentation faster than projected. This approach is modularizing security policy enforcement away from perimeter-based firewalls toward identity-verified session controls.
CISA's Secure by Design pledge for critical infrastructure software is reshaping vendor accountability. Suppliers must now attest to memory-safe languages and SBOM transparency for federal procurement eligibility. Encryption solution providers serving California utilities are restructuring development pipelines to meet attestation requirements before NERC CIP deadlines.
Utility procurement committees are consolidating vendor relationships to reduce integration overhead. Single-source security platforms are displacing best-of-breed point solutions in RFP evaluations. This concentration is most visible among Texas investor-owned utilities managing multi-territory renewable portfolios.
United States Smart Grid Security Market Segmentation
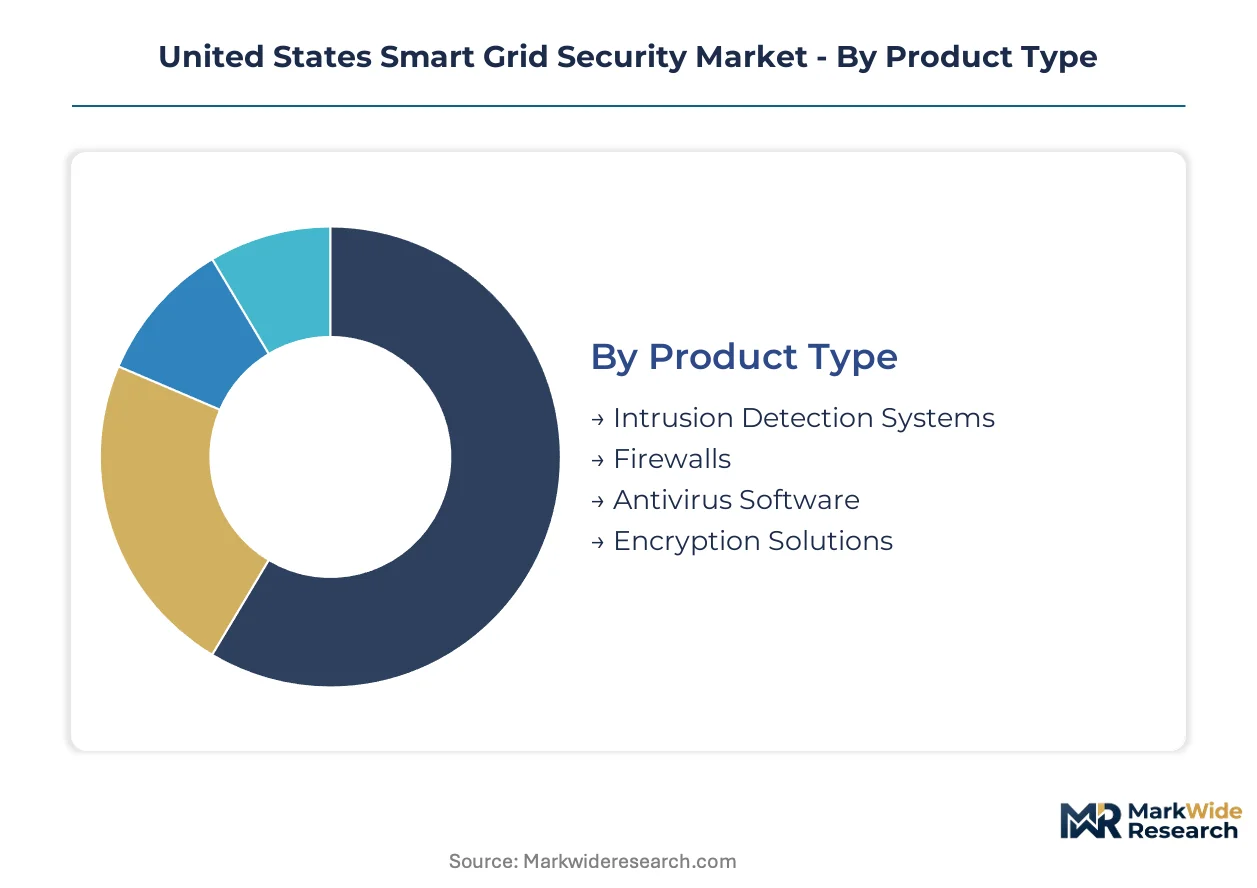
Segmentation in the United States Smart Grid Security Market reveals divergent procurement patterns across utility ownership structures and operational technology maturity. Understanding these divides enables vendors to align product roadmaps with compliance-driven investment cycles and geographic concentration of renewable integration projects.
Product Type:
Cost tier differentiation separates enterprise-grade platforms from modular point solutions that smaller utilities deploy incrementally.
- Intrusion Detection Systems:Network behavioral monitoring platforms analyze SCADA traffic patterns for anomaly flagging. Texas and California utilities prioritize these for distributed energy resource aggregation points under FERC Order 2222 implementation.
- Encryption Solutions:AES-256 and emerging quantum-resistant algorithms protect command-and-control channels between control centers and field devices. NERC CIP key management mandates are compressing procurement timelines for these offerings across investor-owned operators.
- Firewalls:Industrial protocol-aware perimeter controls segment operational technology networks from enterprise IT.
- Antivirus Software:Endpoint protection tailored for Windows-based HMI and engineering workstations in substation environments.
Volume sits with Intrusion Detection Systems; growth tilts toward Encryption Solutions.
Technology:
Application maturity varies sharply between proven operational deployments and experimental pilots that utilities hesitate to scale.
- AI & Machine Learning:Behavioral analytics platforms automate anomaly detection across AMI and SCADA data streams. California municipal utilities are deploying these for renewable forecasting integrity verification.
- Cloud Security:Containerized workloads and zero-trust access controls enable remote monitoring without core network dependency. Texas cooperatives are adopting these fastest where air-gapped constraints are less stringent.
- Blockchain:Distributed ledger approaches to energy transaction verification remain largely pilot-stage.
- Quantum Cryptography:Post-quantum algorithm preparation is generating consulting demand but limited product revenue.
Revenue concentrates in AI & Machine Learning; Cloud Security is expanding most quickly among deployment-ready offerings.
End User:
Customer type determines procurement sophistication, with regulatory exposure and IT staff scale driving solution complexity.
- Utilities:Investor-owned, municipal, and cooperative operators represent the core demand base with differentiated NERC CIP compliance obligations. Texas ERCOT participants are accelerating spending following winter storm-related reliability scrutiny.
- Government:Federal power marketing administrations and military installations require specialized supply chain attestation under CISA Secure by Design pledges.
- Industrial:Cogeneration facilities and large manufacturing campuses with behind-the-meter generation assets.
- Commercial:Data centers and critical facility operators procuring microgrid security independently.
Procurement volume clusters with Utilities; Government segment exhibits steepest expansion trajectory following federal infrastructure funding activation.
Deployment Model:
Operational constraints at generation facilities enforce hybrid architectures that vendors must accommodate without performance degradation.
- On-premises:Air-gapped hardware and software deployed within critical generation control rooms where cloud connectivity is prohibited. Nuclear and large hydro facilities maintain strict on-premises mandates.
- Hybrid:Policy-unified management across edge, core, and cloud layers reconciles operational isolation with analytics demands. Southwest municipal utilities are adopting microsegmentation faster than projected through this model.
- Cloud-based:SaaS-delivered security analytics for non-critical distribution operations and AMI backhaul.
- Managed Services:Outsourced security operations centers addressing ICS talent scarcity among mid-tier cooperatives.
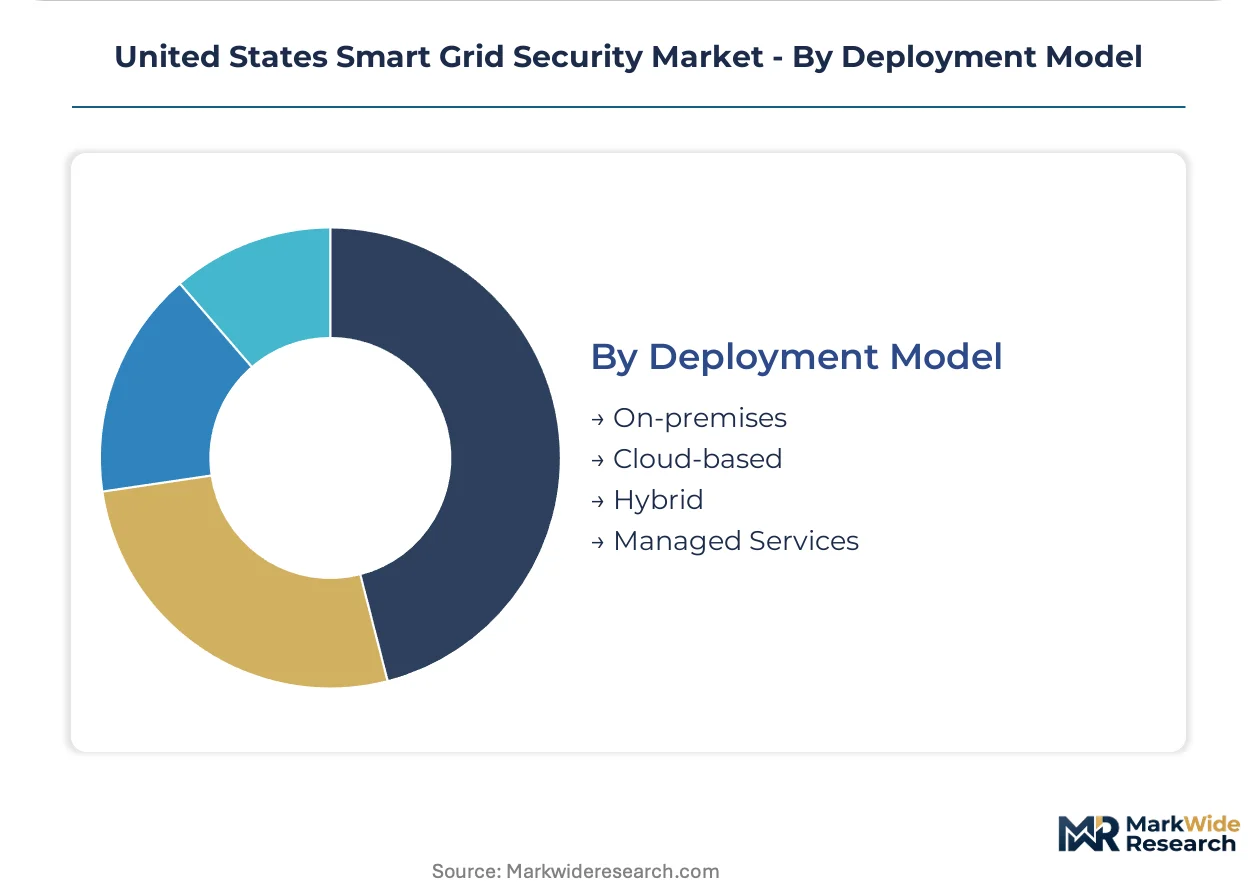
Installed base remains with On-premises; Hybrid deployments are gaining share fastest as utilities modernize substation automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cybersecurity talent density anchors United States Smart Grid Security development. Federal infrastructure funding flows disproportionately toward states with renewable integration mandates. Procurement clusters reflect NERC CIP enforcement intensity and distributed energy resource penetration rates.
California
California municipal utilities accelerate AI-driven behavioral analytics deployment for AMI network integrity. The state's Public Utilities Commission enforces microgrid security standards that exceed federal baselines. Greater Los Angeles and San Diego clusters concentrate edge computing security pilots for solar-plus-storage aggregation.
Texas
Texas ERCOT participants expand cybersecurity procurement following winter storm reliability scrutiny. FERC Order 2222 implementation drives demand for distributed energy resource edge protection. Houston and Dallas-Fort Worth utilities anchor multi-territory renewable portfolio security consolidation.
New York Metro
Con Edison's grid modernization program channels investment toward substation microsegmentation. The state's climate leadership requirements mandate quantum-resistant algorithm preparation timelines. Downstate municipal utilities adopt hybrid deployment models faster than national averages.
Pacific Northwest
Bonneville Power Administration facilities maintain strict on-premises security mandates for federal hydro assets. Washington and Oregon public utility districts leverage Infrastructure Investment and Jobs Act funding for AMI backhaul protection. Seattle-area cooperatives pilot managed security services addressing ICS talent scarcity.
Southeast
Florida and Georgia utilities prioritize hurricane-resilient SCADA redundancy alongside cyber hardening. State public service commissions in the region lag NERC CIP enforcement intensity seen elsewhere. Atlanta anchors federal power marketing administration security operations center consolidation.
United States Smart Grid Security Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized industrial control system threat intelligence. The vendor base stratifies across three maturity levels: legacy IT security incumbents with utility verticalization, pure-play operational technology specialists, and federal contractors with critical infrastructure mandates. Dominant competitive moves include strategic partnerships bridging IT-OT security domains and portfolio diversification into edge computing workloads.
Within the industrial control system specialist tier, Dragos Inc. and Claroty Ltd. exemplify pure-play operational technology security positioning. IBM anchors enterprise-scale utility deployments through hybrid cloud security integration. Cisco Systems Inc. occupies the network-layer segmentation vector for substation environments.
| Leading Market Players |
|---|
| IBM |
| Lockheed Martin Corporation |
| Cisco Systems Inc. |
| IOActive |
| BAE Systems Plc |
| Honeywell International Inc. |
| Dragos Inc. |
| Claroty Ltd. |
| Leidos |
| Others |
Cost & Logistics Intelligence
Captive integration of threat intelligence feeds with encryption key management anchors both supply security and pricing power for United States Smart Grid Security vendors serving NERC CIP-compliant utilities. Federal procurement mandates under CISA's Secure by Design pledge compress vendor qualification timelines, tightening the link between in-house cryptographic development and premium positioning.
Pricing Analysis
Warranty and incident-response bundling separates enterprise-grade platform pricing from unbundled point solutions. Three-tier pricing structure across premium, standard, and economy levels reflects NERC CIP certification tier and deployment scale. Pricing pressure stems from municipal utility budget constraints accelerating SaaS migration. Rural electric cooperatives exhibit highest price sensitivity; investor-owned operators in Texas and California prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Domestic-content requirements under the Infrastructure Investment and Jobs Act reshape sourcing toward US-based semiconductor fabrication and cryptographic module assembly. Hardware security modules draw from domestic foundries and Taiwanese chip fabrication. Supply chain risk centers on single-source vulnerability for quantum-resistant algorithm IP. Distribution runs through utility procurement committees and federal contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Smart Grid Security Market operates as a vertical-integration race where threat intelligence acquisition and cryptographic IP control determine long-term positioning. Vendors securing upstream algorithm development or downstream managed security service channels capture durable advantage.
For Market Incumbents: Anchor enterprise-scale deployments through hybrid cloud security integration while consolidating point-solution vendors to reduce interoperability overhead. Quantum-resistant algorithm development represents the critical lever against emerging pure-play OT specialists. NERC CIP version 7 uncertainty threatens multi-year platform commitments; defer large capital deployments until regulatory clarity stabilizes. For New Entrants and Emerging Players: Launch via managed security service models addressing ICS talent scarcity among mid-tier rural electric cooperatives. Municipal utilities in the Southwest present the most penetrable segment given accelerated microsegmentation adoption and lighter legacy infrastructure burdens. Partner with established utility integrators to bypass lengthy procurement committee qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by federal contractors seeking OT security verticalization. Five-to-ten-year viability hinges on quantum-resistant algorithm readiness and CISA Secure by Design attestation compliance. Monitor NERC CIP enforcement intensity in Texas and California as the inflection signal for sector-wide procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Threat Intelligence Platform Integration | Consolidates Dragos and Claroty feeds into unified utility SOC workflows, reducing alert fatigue. |
| Quantum-Resistant Algorithm Certification | Positions vendors for NIST post-quantum cryptographic standards before NERC CIP mandates tighten. |
| Managed Security Service Expansion | Addresses ICS talent scarcity among municipal cooperatives through outsourced SOC operations. |
| Edge Computing Security Convergence | Enables real-time threat response at substations without core network dependency under FERC Order 2222. |
| Federal Contracting Vehicle Qualification | Unlocks Infrastructure Investment and Jobs Act funding streams for grid modernization cybersecurity. |
Research Approach
Multi-period observation of NERC CIP enforcement actions, utility capital expenditure disclosures, and vendor contract awards anchored the trend analysis, supplemented by interviews with utility CISOs, OT security engineers, federal procurement officers, and industrial control system integrators. Secondary validation drew from FERC filings, CISA advisories, EIA grid modernization data, and NERC reliability standards documentation. Bottom-up segment sizing triangulated against top-down federal funding allocation estimates.
Input-output matrices modeled deployment model adoption, utility ownership structure, and technology maturity across the projection horizon. Segmentation dimensions included product type, end-user category, and regional regulatory intensity. CAGRs derived from utility procurement cycle analysis and compliance deadline clustering. Forecast inputs incorporated renewable integration penetration rates and distributed energy resource aggregation timelines under FERC Order 2222.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant cryptography migration would alter the outlook. Forecasts reflect assumptions about NERC CIP version 7 stability, federal infrastructure funding continuity, and ICS talent market tightness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Power Grid Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Smart Microgrid Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Demand Response Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Smart Grid Network Market
Smart Grid
Microgrid Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Global Self-Healing Grid Market