
 AC Grid Connected Microgrid Market | 2026-2036
AC Grid Connected Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
AC Grid Connected Microgrid Market Insights
Utility-grade resiliency specifications are redrawing competitive boundaries in AC grid connected microgrids. Siemens leverages its digital twin platforms to dominate European utility deployments. Schneider Electric anchors its position through integrated energy management software and hardware stacks. ABB competes with high-voltage switching expertise tailored to campus and industrial configurations.
An AC grid connected microgrid is a localized energy system that synchronizes with the main utility grid through bidirectional power converters operating at standard AC frequencies, typically 50 or 60 Hz, enabling seamless islanding during grid disturbances while maintaining voltage and frequency stability. Its primary purpose is to deliver reliable, controllable power to critical facilities while enabling participation in wholesale energy markets and ancillary services. Campus and industrial microgrid types capture the deepest margin pools due to long-term service contracts and complex load profiles. Battery storage and solar hybrid configurations represent the fastest-expanding energy source pairing as lithium-ion costs decline and dispatch algorithms mature. Grid-tied deployment models retain volume leadership, though hybrid architectures gain traction where regulatory frameworks reward flexibility.
FERC Order 2222 in the United States enables distributed energy resource aggregation, while IEEE 1547-2018 governs interconnection technical requirements. Germany's BNetzA implements grid codes that mandate frequency-watt and volt-watt response capabilities for connected assets. Stakeholders must monitor evolving interconnection standards and capacity market rules that determine whether microgrid assets qualify for grid services revenue.
Market Dynamics
Bidirectional power converters with advanced grid-forming capabilities are restructuring procurement priorities as military installations and hyperscale data centers demand sub-cycle islanding performance. This technical specification shift favors vendors with integrated hardware-software stacks over component suppliers.
Growth Catalysts
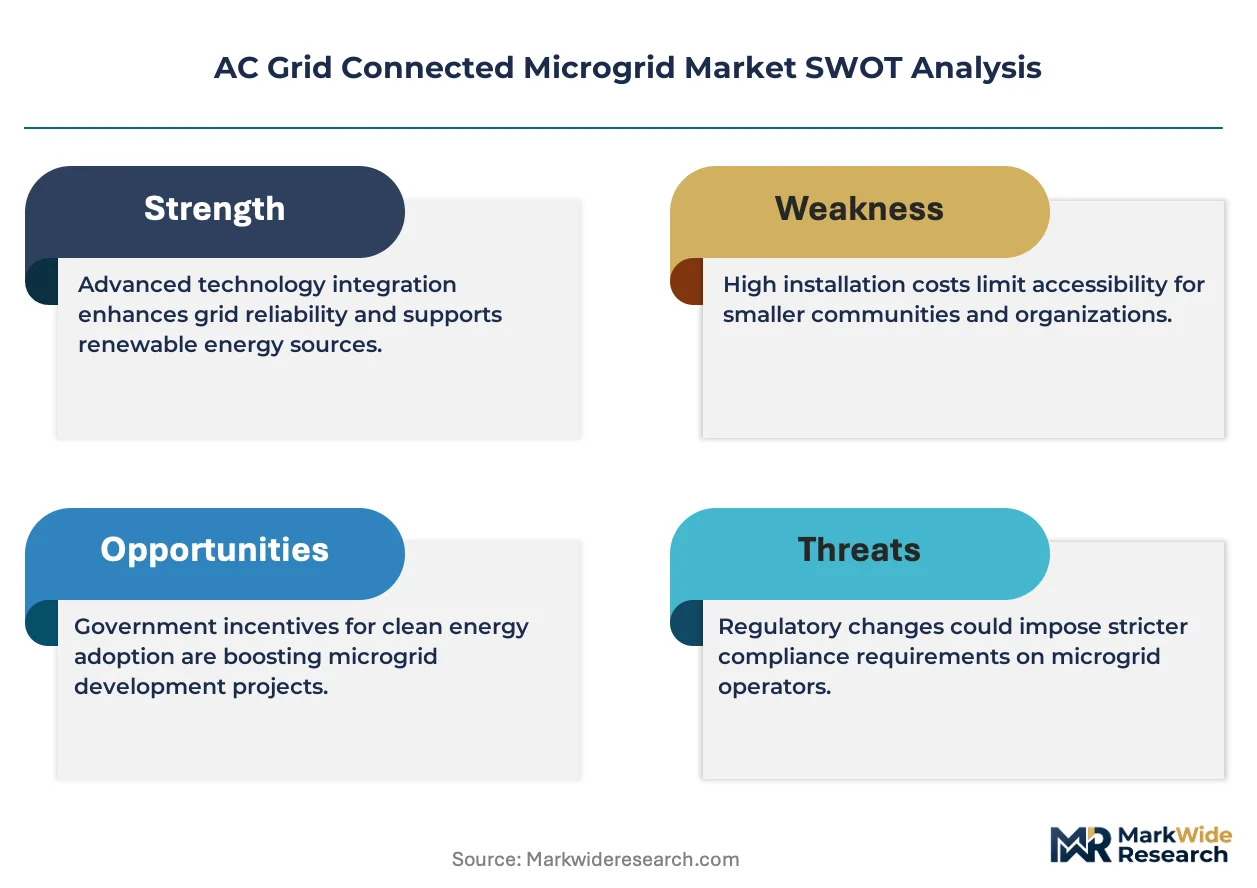
- FERC Order 2222 Aggregation Framework:Distributed energy resource aggregation rules in the United States enable microgrid assets to participate in wholesale capacity markets. Revenue stacking from ancillary services accelerates project economics for campus and industrial deployments.
- Lithium-Ion Cost Trajectory:Battery pack prices below critical thresholds unlock solar-plus-storage configurations at commercial and industrial scale. Dispatch algorithms with predictive load forecasting maximize value capture from time-of-use rate arbitrage.
- Data Center Resiliency Mandates:Hyperscale operators in Northern Virginia and Phoenix require N+1 redundancy with grid-synchronization capabilities. Uptime Institute Tier certification standards now explicitly reward grid-tied microgrid architectures.
Market Restraints
- Copper and Rare Earth Input Volatility:Power converter manufacturing depends on copper winding materials and neodymium-dysprosium permanent magnets. Price swings in Chinese processed rare earth concentrates compress hardware margins unpredictably.
- Interconnection Queue Congestion:Utility study timelines for IEEE 1547-2018 compliance verification extend 18-36 months in California and Texas. Project developers face carrying cost accumulation during regulatory limbo.
- Natural Gas Peaker Substitution Threat:Turbine-based rapid response assets compete for frequency regulation contracts in PJM and ERCOT markets. Established reciprocating engine fleets retain operational familiarity among utility dispatchers.
Strategic Opportunities
- India Industrial Corridor Electrification:Delhi-Mumbai Industrial Corridor and Bengaluru-Chennai manufacturing belt lack reliable grid infrastructure. State-level open access regulations permit direct power purchase agreements with renewable microgrid developers.
- Vehicle-to-Grid Convergence:Bidirectional EV charging infrastructure merges with building microgrid controllers. Fleet depot electrification creates aggregated storage capacity for frequency response services.
- Germany BNetzA Grid Code Evolution:Upcoming revisions to medium-voltage connection technical requirements prioritize synthetic inertia provision. Early certification positions vendors for mandatory capability procurement.
Industry Challenges
- Power Systems Engineering Talent Scarcity:Grid-forming inverter design requires specialized expertise in small-signal stability analysis and harmonic impedance modeling. University programs produce insufficient graduates with hybrid power electronics and power systems training.
- Multi-Standard Certification Complexity:Simultaneous UL 1741 SA, IEEE 1547.1, and regional grid code compliance testing extends product launch timelines. Test facility bottlenecks in North America and Europe create queue delays.
- Legacy SCADA Integration Friction:Industrial microgrid deployments must interface with decades-old distributed control systems. Protocol translation gateways introduce latency and cybersecurity surface area expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Grid Connected Microgrid Market |
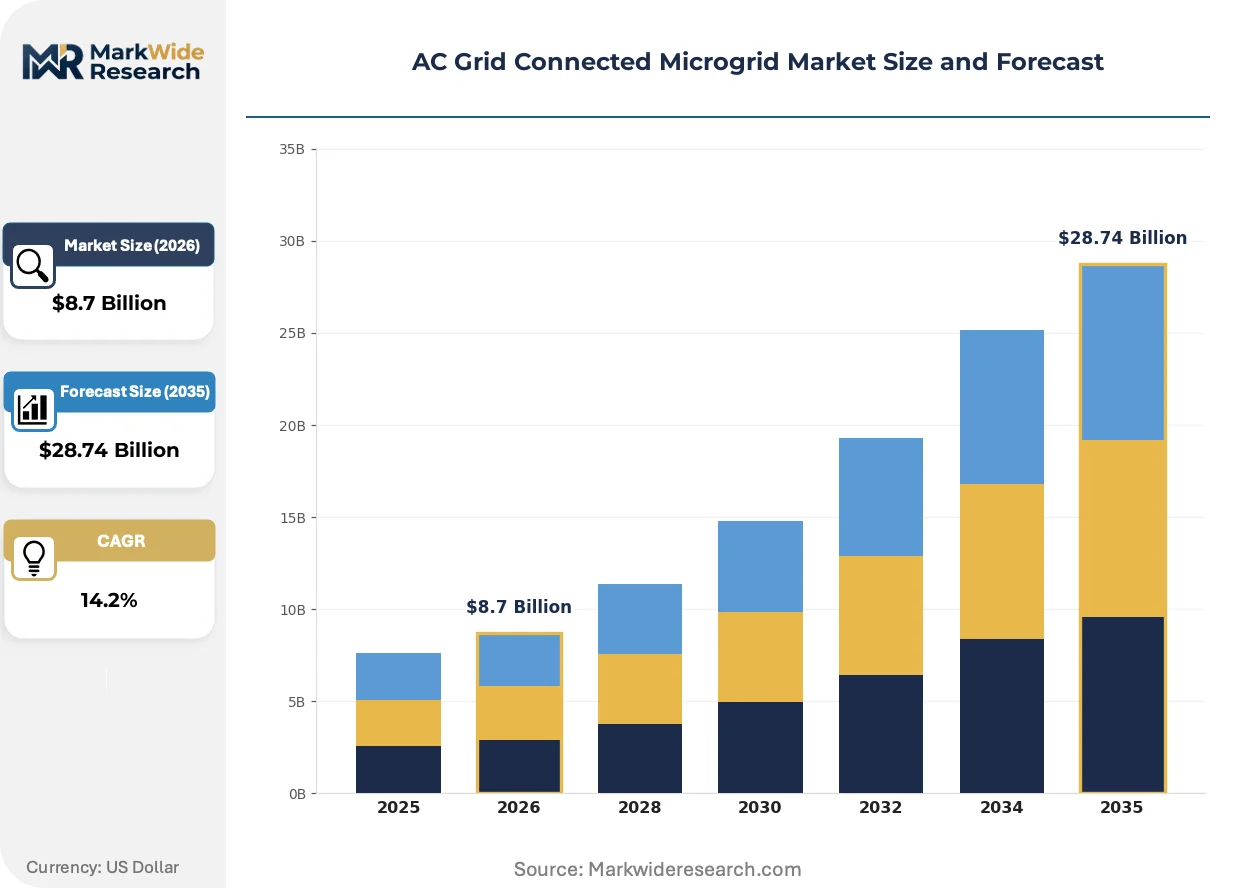
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Microgrid Type: Remote, Urban, Campus, Industrial, Commercial, Military Energy Source: Solar, Wind, Diesel Generator, Battery Storage, Hydroelectric, Fuel Cells End User: Utilities, Data Centers, Educational Institutions, Military Bases, Commercial Complexes, Municipal Facilities Deployment Model: Grid-Tied, Islanded, Hybrid, Peer-to-Peer, Community, Virtual |
| Companies Covered | Siemens, Schneider Electric, ABB, Hitachi Energy, General Electric, Eaton, Emerson, Tesla, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Grid Connected Microgrid Market Trends and Innovations
Solid-state transformer architectures and silicon carbide switching devices are compressing converter footprints while enabling direct medium-voltage connection. These hardware advances synchronize with software-defined energy management platforms that optimize across multiple revenue streams.
Silicon carbide MOSFETs operating at 20+ kHz switching frequencies enable compact, liquid-cooled power conversion stages. Data center operators in Texas and Arizona are specifying these units for 480V direct-to-bus architectures. Higher efficiency and reduced thermal management footprint are displacing conventional IGBT-based designs in new procurement specifications.
Germany's BNetzA has proposed amendments to VDE-AR-N 4110 technical connection rules requiring dynamic grid support across all voltage levels. Industrial microgrids above 1 MW must demonstrate fault ride-through and reactive power capability under specified voltage dip profiles. Manufacturers serving the German market are pre-certifying hardware to accelerated timelines ahead of formal adoption.
Energy-as-a-service contracting models separate asset ownership from operational responsibility. Military bases and municipal governments in California and New York favor performance-guaranteed arrangements over capital purchases. This financing structure transfers technology risk to vendors while locking in long-term operational expenditure commitments.
AC Grid Connected Microgrid Market Segmentation
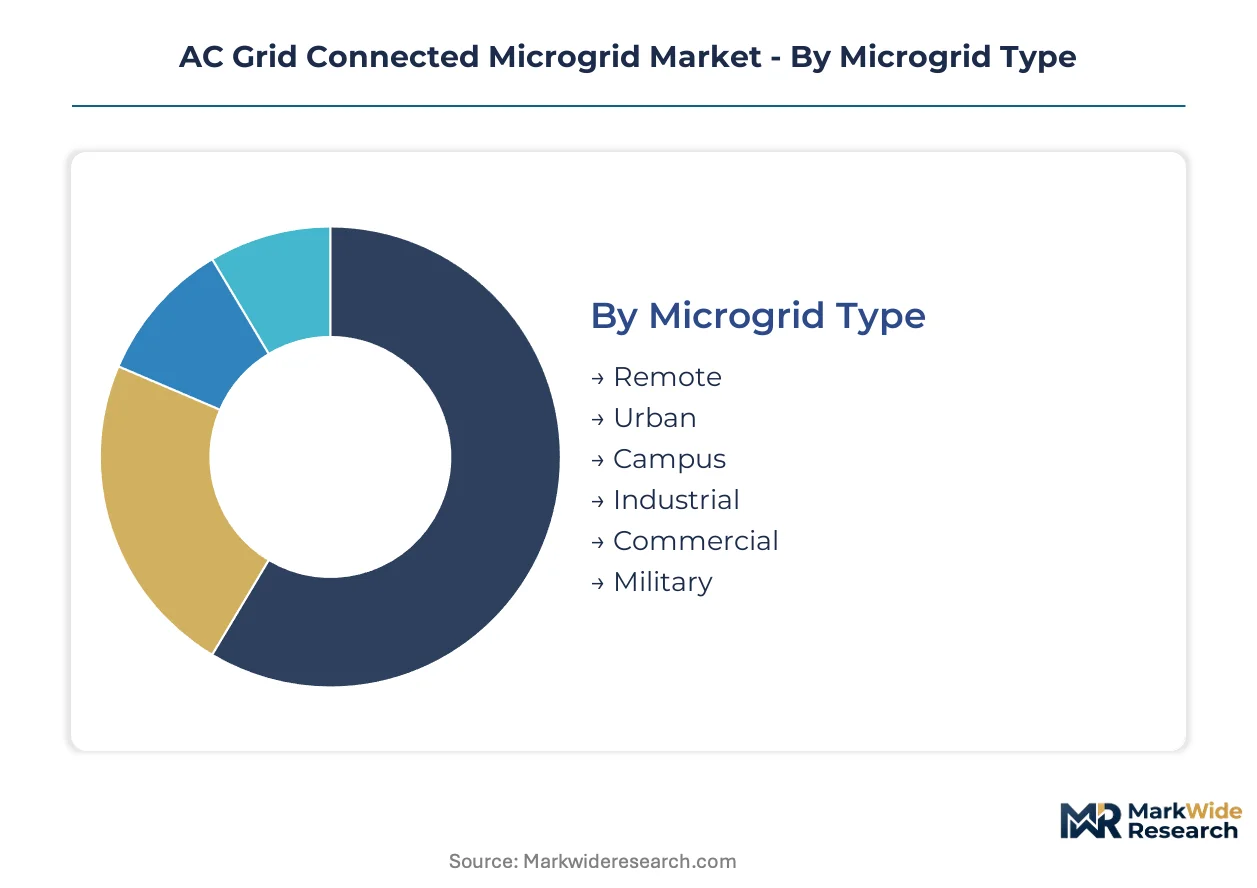
Segmentation in AC grid connected microgrids reveals how technical specifications and procurement models diverge across facility types and regulatory environments. Each dimension exposes distinct margin structures, certification requirements, and vendor competitive dynamics that reshape deployment strategies.
Microgrid Type:
Campus and industrial configurations face the strongest substitution pressure from natural gas reciprocating engines and turbine peakers in wholesale capacity markets, while remote installations contend with standalone diesel-battery hybrids.
- Campus:University and corporate deployments integrate combined heat and power with solar-battery stacks. Procurement concentrates in California and Massachusetts where state emissions mandates accelerate electrification retrofits.
- Industrial:Heavy manufacturing loads demand sub-cycle islanding and voltage sag ride-through. Texas petrochemical corridors and German Ruhr industrial zones prioritize IEEE 1547-2018 and VDE-AR-N 4110 certification compliance.
- Remote:Mining and resource extraction operations in Western Australia and Chilean Atacama rely on solar-diesel hybrids with limited grid interconnection.
- Urban:Dense metropolitan districts in Tokyo and Singapore deploy compact medium-voltage architectures with solid-state transformer integration.
- Commercial:Retail and office complexes in Phoenix and Dubai prioritize peak shaving and demand charge reduction through automated dispatch.
- Military:US Department of Defense installations mandate cyber-secure, N+1 redundant architectures with anti-islanding protection per MIL-STD-1399.
Industrial microgrids retain volume leadership; campus configurations hold the steepest expansion curve.
Energy Source:
Cost tier stratification separates lithium-ion battery hybrids from legacy diesel backup, with fuel cells occupying an intermediate position dependent on hydrogen infrastructure maturity.
- Battery Storage:Lithium iron phosphate and nickel-manganese-cobalt chemistries dominate four-hour duration configurations. Data center operators in Northern Virginia and Frankfurt specify liquid-cooled racks with predictive thermal management.
- Solar:Bifacial modules with tracking systems integrate directly at 1500V DC bus architectures. Indian industrial parks under open access regulations favor direct power purchase agreements with solar-plus-storage developers.
- Diesel Generator:Reciprocating engines persist in backup-only roles where emissions regulations permit limited runtime hours.
- Wind:Small-scale turbines supplement solar in coastal Texas and Danish island communities with complementary generation profiles.
- Fuel Cells:Proton exchange membrane systems gain traction at South Korean semiconductor fabs with captive hydrogen supply chains.
- Hydroelectric:Run-of-river microturbines serve Alpine industrial facilities in Switzerland and Austrian mountain corridors.
Battery storage commands the premium cost tier; solar hybrids are climbing the fastest in new project announcements.
End User:
Application-specific requirements fragment procurement specifications, with data centers demanding the most stringent uptime guarantees and military bases imposing cybersecurity hardening.
- Data Centers:Hyperscale operators require Tier III and Tier IV uptime certification with seamless islanding. Northern Virginia's Loudoun County and Phoenix's Mesa districts anchor procurement volumes for multi-hundred-megawatt campus developments.
- Military Bases:US Army and Navy installations prioritize operational technology isolation and electromagnetic pulse hardening. California's Camp Pendleton and Texas's Fort Hood represent flagship deployment sites.
- Utilities:Distribution system operators in Germany and Japan deploy microgrids as non-wires alternatives to substation upgrades.
- Educational Institutions:University microgrids in New York and Massachusetts integrate research platforms with live grid laboratories.
- Commercial Complexes:Mixed-use developments in Singapore and Sydney optimize across retail, hospitality, and office load profiles.
- Municipal Facilities:City-owned emergency operations centers in Florida and Louisiana prioritize hurricane resilience with extended islanding duration.
Data centers retain volume leadership; military bases hold the steepest expansion curve.
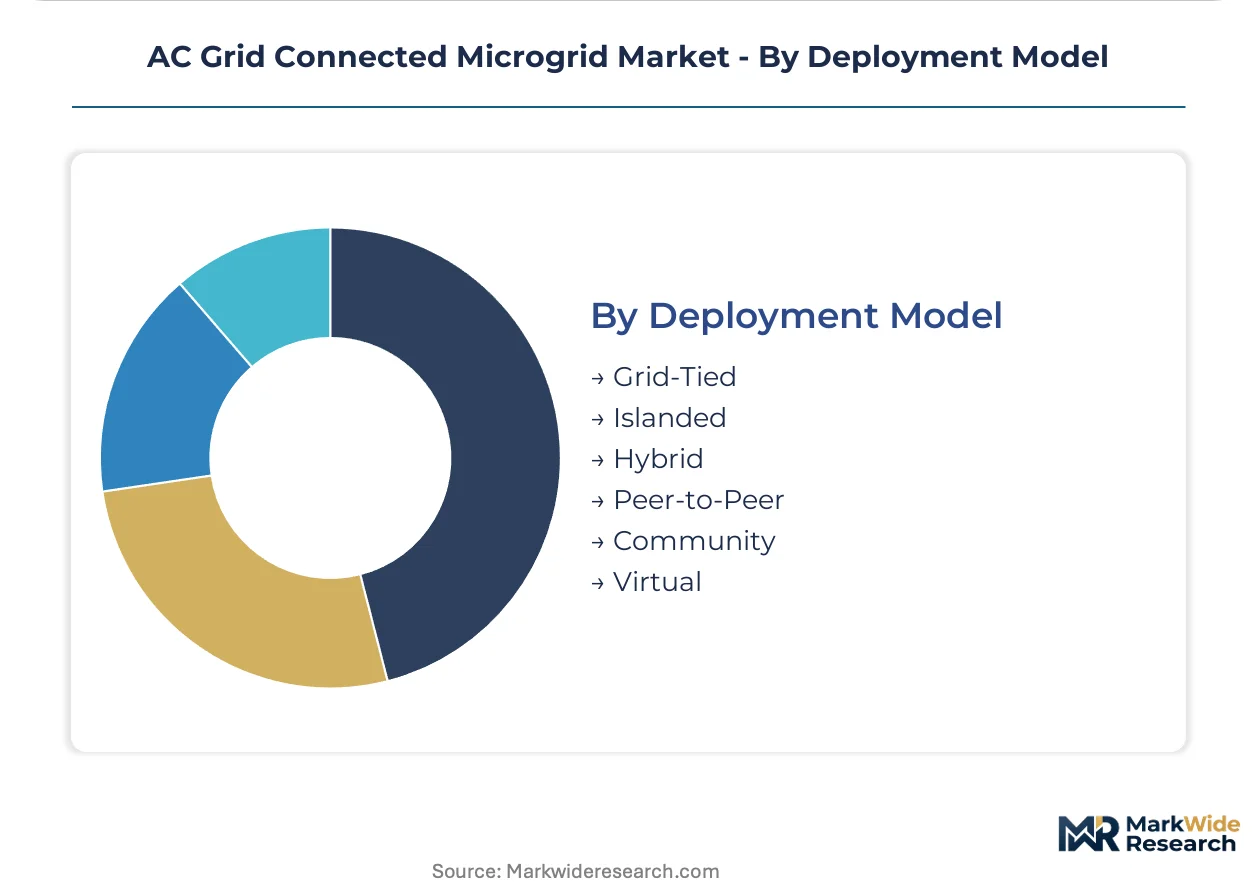
Deployment Model:
Customer type and financing structure determine whether asset ownership remains with the host facility or transfers to energy-as-a-service providers.
- Grid-Tied:Synchronized operation with utility frequency and voltage enables wholesale market participation. FERC Order 2222 aggregation rules in the United States unlock capacity market revenue streams for campus and industrial assets.
- Hybrid:Seamless transition between grid-connected and islanded states requires grid-forming inverter capability. German industrial parks under BNetzA grid codes mandate synthetic inertia provision in upcoming technical revisions.
- Islanded:Standalone systems serve remote mining and resource extraction with no utility interconnection.
- Peer-to-Peer:Blockchain-enabled energy trading pilots operate in Brooklyn and Australian suburban neighborhoods.
- Community:Shared solar and storage assets serve multiple residential and small commercial accounts under single interconnection agreements.
- Virtual:Aggregated distributed resources without geographic colocation participate as single market entities in regional transmission organization markets.
Grid-tied deployments retain volume leadership; hybrid architectures hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in power conversion hardware favor manufacturing economies with integrated rare earth processing. Germany and Japan maintain trade surpluses in high-voltage switching equipment. The United States and India run structural deficits, importing silicon carbide substrates and magnet materials from Asian suppliers.
United States
Data center construction in Northern Virginia and Phoenix drives procurement of grid-forming inverters with sub-cycle islanding. FERC Order 2222 enables distributed energy resource aggregation for wholesale market participation. Texas petrochemical corridors prioritize IEEE 1547-2018 certification for industrial microgrids.
Germany
Industrial parks in the Ruhr zone demand synthetic inertia provision under evolving BNetzA grid codes. The country's national energy regulator mandates dynamic grid support capabilities for medium-voltage connections. Bavarian manufacturing clusters pre-certify hardware ahead of formal VDE-AR-N 4110 adoption.
Japan
Tokyo's dense metropolitan districts deploy compact medium-voltage architectures with solid-state transformer integration. METI promotes utility modernization programs prioritizing resilient distributed energy architectures. Osaka-Kansai industrial zones anchor procurement for semiconductor fab microgrids.
India
The Delhi-Mumbai Industrial Corridor lacks reliable grid infrastructure, accelerating open access renewable microgrid development. State-level regulations permit direct power purchase agreements with solar-plus-storage developers. Bengaluru-Chennai manufacturing belts attract captive power investments from automotive and electronics suppliers.
Australia
Mining operations in Western Australia rely on solar-diesel hybrids with limited grid interconnection. The country's national energy regulator oversees grid connection standards for remote resource extraction sites. Chilean Atacama operations source similar equipment, creating regional procurement patterns across southern hemisphere mining corridors.
AC Grid Connected Microgrid Market Competitive Landscape
Concentration sits with integrated hardware-software stack providers over component specialists. The vendor base spans three tiers: multinational electrical conglomerates with digital twin platforms, specialized power conversion houses with silicon carbide expertise, and regional system integrators with local certification relationships. Siemens, Schneider Electric, and ABB anchor the top tier through utility-scale project execution. Competitive moves center on grid-forming inverter certification acceleration and energy-as-a-service financing structures.
Among European-based electrical conglomerates, Siemens and ABB represent the integrated platform archetype, combining high-voltage switching hardware with digital energy management layers. Schneider Electric occupies a position bridging European utility markets and North American campus deployments. Tesla exemplifies the silicon carbide power electronics specialist, with liquid-cooled conversion stages specified by hyperscale data center operators in Texas and Arizona. These three anchors demonstrate how vendor positioning splits between utility-grade certification depth and data center responsiveness speed.
| Leading Market Players |
|---|
| Siemens |
| Schneider Electric |
| ABB |
| Hitachi Energy |
| General Electric |
| Eaton |
| Emerson |
| Tesla |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at silicon carbide foundries in China and South Korea shapes both component availability and price floors for power conversion hardware. Scale economies in lithium-ion cell manufacturing compress battery pack costs while concentrating procurement leverage among hyperscale data center operators.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing with tiered performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming inverter certification grades from basic IEEE 1547 compliance tiers. Cost compression in standard-tier hardware is intensifying because Chinese power module suppliers are expanding 650V silicon carbide capacity. Campus microgrid developers exhibit highest price sensitivity due to municipal budget constraints, while military procurement shows lowest sensitivity given mission-critical specifications.
Supply Chain Analysis
Inventory cycles for IGBT and silicon carbide MOSFET modules now extend eighteen to twenty-four months following pandemic-era fab capacity constraints. Manufacturing concentrates in China, Germany, and Japan for high-voltage switching equipment, with rare earth magnet processing anchored in Chinese inner Mongolia facilities. Converter assembly draws from copper winding suppliers in Chile and Australian lithium hydroxide refiners. Single-source vulnerability persists for neodymium-dysprosium alloys processed through Chinese state-owned enterprises. Distribution runs through authorized system integrators with regional certification relationships rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models creates white-space opportunities as energy-as-a-service financing separates asset ownership from operational responsibility. Data center resiliency mandates and military cybersecurity specifications are spawning niche vendor ecosystems faster than consolidation can absorb them.
For Market Incumbents: Secure grid-forming inverter certification acceleration ahead of BNetzA synthetic inertia mandates. Lock in long-term service contracts with Texas petrochemical corridors to defend against natural gas peaker substitution. Prioritize backward integration into silicon carbide substrate supply through Korean or Japanese wafer partnerships. For New Entrants and Emerging Players: Software-defined energy management layers represent the most under-served capability gap where incumbents bundle hardware-heavy stacks. Target Indian industrial corridor electrification under state-level open access regulations. Lead with predictive dispatch algorithms and automated frequency response rather than converter hardware. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among energy-as-a-service providers with performance-guaranteed military and municipal contracts. Five-to-ten year viability favors vendors with simultaneous UL 1741 SA and VDE-AR-N 4110 pre-certification. Watch for BNetzA grid code finalization as inflection signal for mandatory capability procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification Acceleration | Early UL 1741 SA and IEEE 1547.1 compliance positions vendors for German BNetzA synthetic inertia mandates. |
| Energy-as-a-Service Platform Launch | Performance-guaranteed contracting transfers technology risk from California municipal governments to vendor balance sheets. |
| Silicon Carbide Supply Agreement | Captive wafer supply from Korean foundries insulates against Chinese rare earth processing concentration. |
| Military Cybersecurity Hardening Program | MIL-STD-1399 compliance opens US Army and Navy installation procurement with N+1 redundancy requirements. |
| Vehicle-to-Grid Integration Partnership | Bidirectional EV charging convergence creates aggregated storage capacity for Texas ERCOT frequency response markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork combined with secondary validation from FERC filings, EIA project databases, IEA distributed energy reports, and manufacturer certification disclosures. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate tracking.
Across the analysis window, volume and value outputs reflect segmentation by microgrid type, energy source pairing, end-user application, and deployment model. CAGRs were derived from capacity installation trajectories and equipment cost curves. Forecast inputs incorporated IEEE 1547-2018 adoption timelines and state renewable portfolio mandate acceleration in California, Texas, and New York.
Forecasts assume regulatory continuity in FERC Order 2222 implementation and German BNetzA grid code evolution; material policy shifts would require re-modeling. Commodity price volatility in copper and rare earth concentrates, plus interconnection queue congestion in California and Texas, represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Smart Grid Communications Market
Smart Grid
Smart Grid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Europe Microgrid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Network Market