
 Global Electric Power Distribution Automation Systems Market | 2026-2036
Global Electric Power Distribution Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Power Distribution Automation Systems Market Intelligence
The European Union's Green Deal is expanding the imperative for utilities to modernize distribution networks for higher renewable energy penetration. Siemens leverages its extensive portfolio in grid software and automation to capture this transition. Schneider Electric competes on its EcoStruxure platform, offering integrated solutions for energy management. GE Vernova positions its grid solutions to support decarbonization efforts across North America and Europe.
Electric power distribution automation systems are integrated hardware and software solutions for real-time monitoring, control, and optimization of electricity distribution networks. These systems use protocols like DNP3 to enhance grid reliability and operational efficiency. Supervisory Control And Data Acquisition (SCADA) systems form the foundational layer of automation for most utilities. Within the component segment, demand for Intelligent Electronic Devices (IEDs) supports advanced fault detection and service restoration functions.
Regulatory frameworks like FERC orders in the United States and the EU's Corporate Sustainability Reporting Directive (CSRD) mandate greater grid resilience and transparency. In China, policies from the MEE supporting dual carbon goals push for smarter, more efficient distribution. These regulations directly shape investment priorities for electric utilities. The critical decision for system vendors is how to align product roadmaps with evolving cybersecurity and interoperability standards.
Market Dynamics
The imperative to integrate intermittent renewable energy sources and manage bidirectional power flows from electric vehicles is the central force shaping the distribution automation market. This transition compels electric utilities to move beyond legacy systems toward more intelligent, responsive grid management solutions.
Growth Catalysts
- Grid Modernization Mandates:The EU Green Deal and China's dual carbon goals are creating regulatory pressure on utilities to invest in automation technologies that enhance grid efficiency and support higher renewable energy penetration.
- Intelligent Device Proliferation:The widespread deployment of Intelligent Electronic Devices (IEDs) provides the granular data and control capabilities necessary for advanced functions like automated fault detection, isolation, and service restoration (FADIR).
- Electrification of Transport:Growing electric vehicle adoption necessitates advanced distribution management systems to manage new, dynamic charging loads and prevent localized grid overloads, particularly in dense urban areas.
Market Restraints
- High Capital Investment:The substantial upfront cost of overhauling legacy SCADA systems and deploying new hardware across vast distribution networks presents a significant financial barrier for many smaller utilities and municipalities.
- Interoperability and Standardization:A lack of universal communication standards between devices from different vendors creates integration challenges, locking utilities into specific ecosystems and increasing long-term operational complexity.
- Legacy Infrastructure Constraints:Aging grid components, such as transformers and circuit breakers, often lack the digital interfaces required for modern automation, forcing costly and disruptive replacement cycles to enable full system benefits.
Strategic Opportunities
- Grid-Edge Analytics:The convergence of operational technology with AI and machine learning offers opportunities for new software solutions that provide predictive analytics for asset health, load forecasting, and network optimization.
- DER Management Systems:The rise of Distributed Energy Resources (DERs) creates a market for specialized platforms that can aggregate, control, and dispatch energy from sources like rooftop solar and battery storage.
- Cybersecurity Services:As grid connectivity expands, a significant opportunity emerges for specialized cybersecurity firms to offer services and solutions tailored to protecting critical distribution automation infrastructure from evolving threats.
Industry Challenges
- Workforce Skills Gap:A persistent shortage of power systems engineers and data scientists with expertise in modern grid automation and operational technology (OT) cybersecurity hampers implementation and maintenance efforts for utilities.
- Data Integration Complexity:Integrating massive volumes of real-time data from thousands of sensors and IEDs into a unified, actionable view for grid operators remains a major technical and architectural challenge.
- Regulatory Compliance Lag:Evolving cybersecurity and data privacy regulations, such as the EU's CSRD, create a complex and shifting compliance landscape that vendors and utilities must navigate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Power Distribution Automation Systems Market |
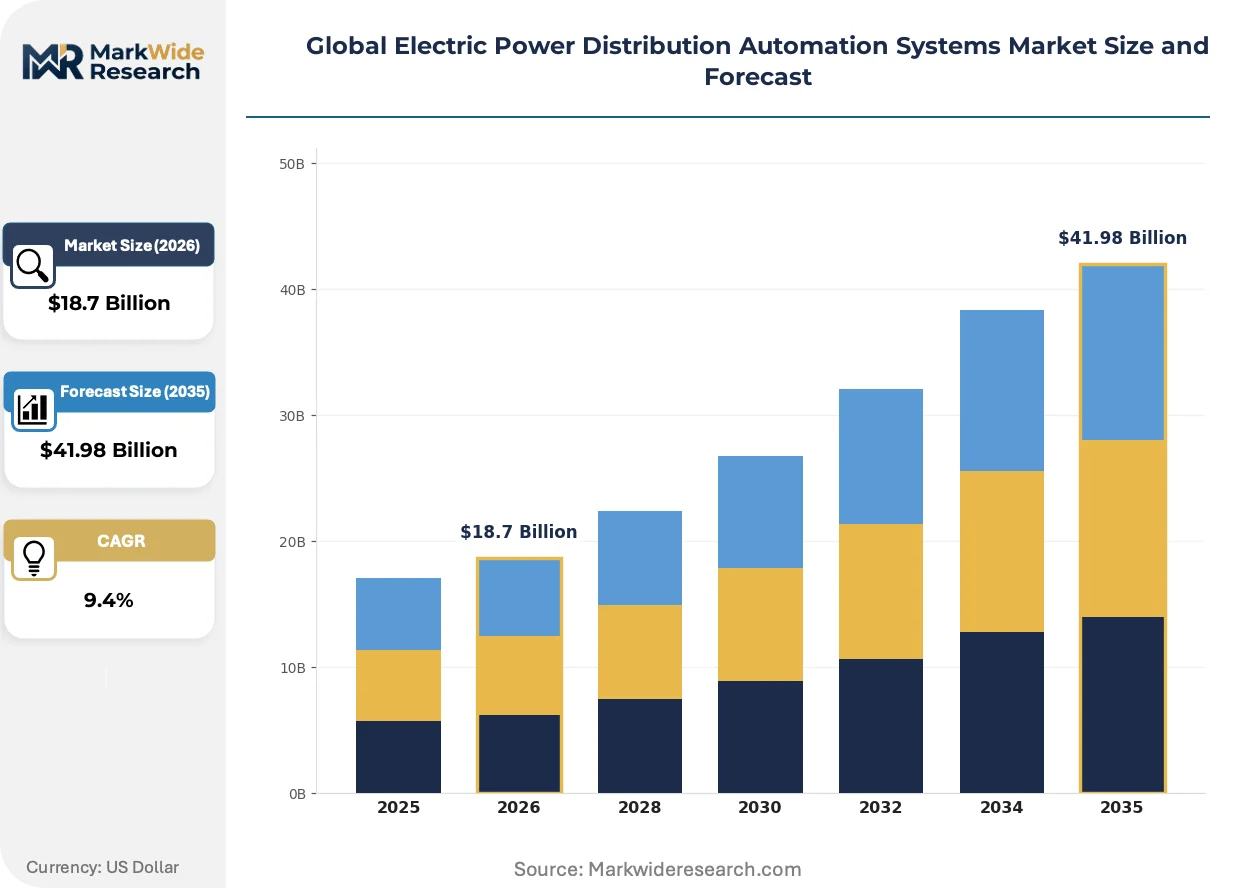
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
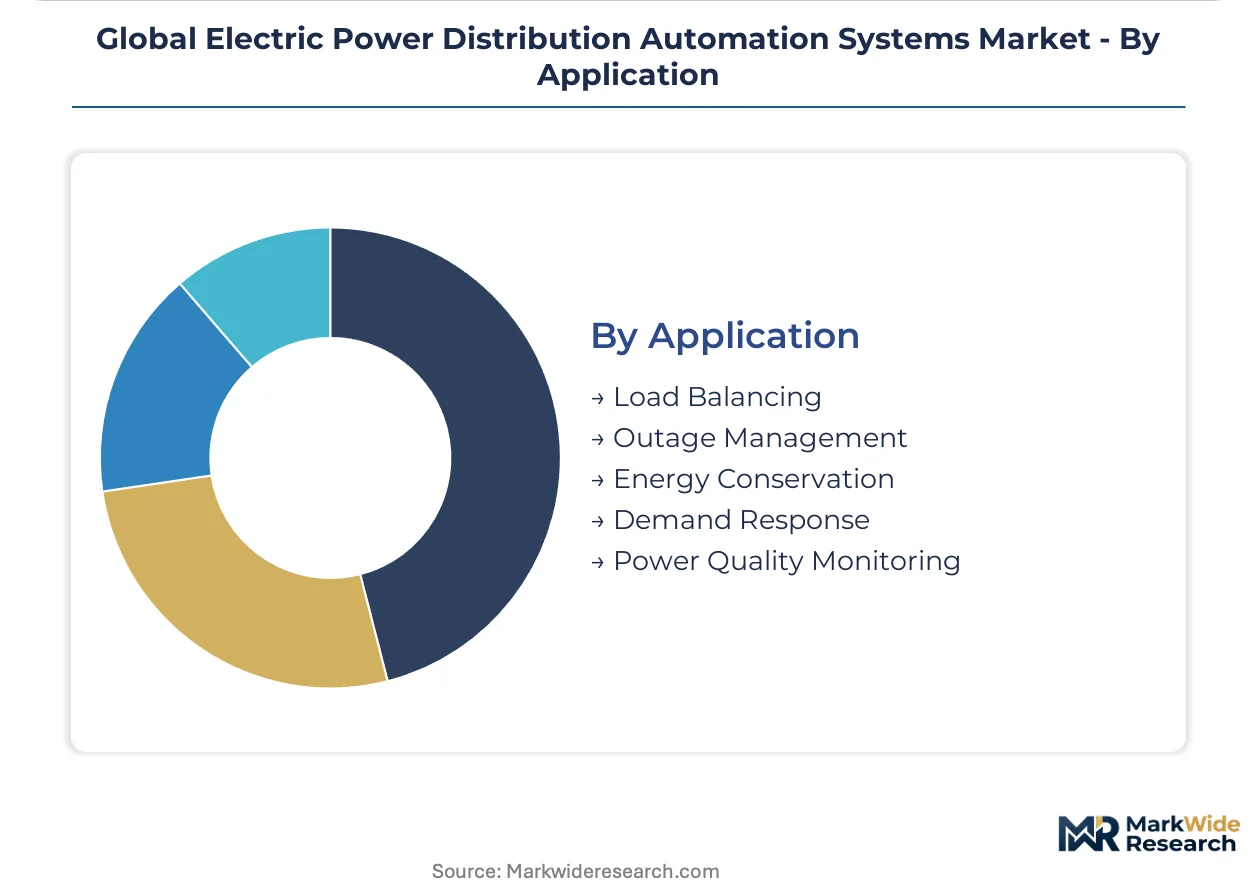
| Segmentation | System Type: Supervisory Control And Data Acquisition, Fault Detection Isolation And Service Restoration, Volt/VAR Optimization, Distribution Management System Component: Remote Terminal Units, Intelligent Electronic Devices, Communication Modules, Controllers, Sensors End User: Electric Utilities, Independent Power Producers, Microgrid Operators, Smart Grid Developers Application: Load Balancing, Outage Management, Energy Conservation, Demand Response, Power Quality Monitoring |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, GE Vernova, Hitachi Energy Ltd., General Electric Company, Itron, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Power Distribution Automation Systems Market Strategic Shifts & Innovations
The operational paradigm of electricity distribution is shifting from centralized command to decentralized, autonomous control. This evolution is driven by the need for faster response times and greater resilience at the grid's edge, where generation and consumption are becoming increasingly intertwined.
Edge computing hardware is a key technological development. These devices process critical operational data locally at substations or even on utility poles, rather than sending it back to a central control center. Electric utilities are adopting this technology to reduce latency for time-sensitive applications. This technology is expanding into functions traditionally handled by central SCADA systems, enabling more autonomous and rapid fault response.
In the United States, FERC Order No. 2222 is reshaping market structures. The directive requires regional grid operators to allow aggregations of Distributed Energy Resources (DERs) to participate in wholesale energy markets. This change is forcing distribution utilities to upgrade their automation capabilities to manage and monetize the bidirectional energy flows from these aggregated assets, directly impacting investment in advanced distribution management systems.
A notable shift in purchasing behavior involves utilities transitioning from one-time capital expenditures on perpetual software licenses to operational spending on subscription-based models. The traditional model of large, infrequent software purchases is being displaced by Software-as-a-Service (SaaS) platforms for grid management. This trend is most prominent in Europe and North America, where utilities favor the financial flexibility and continuous innovation cycles offered by subscriptions.
Global Electric Power Distribution Automation Systems Market Segmentation

The Global Electric Power Distribution Automation Systems Market is diverse, reflecting varied requirements for grid modernization across different regions and operational scales. Understanding these distinct segments is essential for vendors to align product development with specific utility needs and regulatory mandates.
System Type:
This system type segment illustrates the spectrum from foundational grid control platforms to highly specialized automation functions. Utilities assess existing infrastructure against desired operational improvements.
- Supervisory Control And Data Acquisition:These systems form the central backbone for monitoring and controlling grid assets across vast networks. Demand concentrates in China, where extensive national grid upgrades require robust centralized management.
- Fault Detection Isolation And Service Restoration:FADIR systems automatically identify faults, isolate affected sections, and restore power to healthy segments, enhancing grid resilience. Adoption accelerates in North America due to mandates for improved reliability.
- Volt/VAR Optimization:These systems manage voltage levels and reactive power flow to reduce line losses and improve overall energy efficiency.
- Distribution Management System:DMS platforms integrate various grid functions, providing operators with comprehensive tools for planning, operating, and optimizing the distribution network.
Leading the category by volume: Supervisory Control And Data Acquisition. Growing fastest: Fault Detection Isolation And Service Restoration.
Component:
Component selection depends heavily on the specific application and the level of intelligence required within the distribution network. This influences overall system capability and deployment costs.
- Intelligent Electronic Devices:IEDs are microprocessor-based controllers providing protection, control, monitoring, and automation functions for electrical equipment. Their proliferation supports advanced fault detection functions in European grids.
- Communication Modules:These components facilitate data exchange between field devices and central control systems, enabling real-time monitoring and remote operation. Demand is high in the United States for integrating distributed energy resources.
- Remote Terminal Units:RTUs acquire data, connecting physical equipment to SCADA systems and converting sensor inputs into digital data.
- Controllers:Controllers execute automation logic and manage local grid operations, interfacing between IEDs and higher-level systems.
- Sensors:Sensors measure electrical parameters like voltage, current, and temperature, providing critical data for grid monitoring.
Intelligent Electronic Devices lead in technological advancement, while Communication Modules are expanding most quickly.
End User:
The end-user segment differentiates demand based on the operational models and regulatory environments of various electricity providers. Each operator type has distinct investment priorities.
- Electric Utilities:These traditional operators of transmission and distribution networks invest heavily in automation for regulatory compliance and service reliability. The EU Green Deal mandates grid modernization for these entities.
- Microgrid Operators:These entities manage localized energy grids, requiring specialized automation for integrating diverse distributed energy resources. Their numbers are expanding rapidly in regions like California.
- Independent Power Producers:IPPs generate and sell electricity, often needing automation to manage their power plant's connection to the main grid.
- Smart Grid Developers:These companies design and implement advanced grid technologies, deploying automation solutions as part of broader smart grid projects.
Electric Utilities represent the largest customer base, with Microgrid Operators demonstrating the steepest expansion trajectory.
Application:
The application segment highlights diverse operational challenges and strategic goals addressed by distribution automation systems. Each application targets specific areas for improvement.
- Outage Management:These applications minimize outage duration and impact through automated fault detection, isolation, and service restoration. Grid resilience initiatives in North America drive investment.
- Demand Response:DR applications enable utilities to manage peak loads by incentivizing consumers to shift electricity consumption. This is relevant with increasing electric vehicle adoption in Europe.
- Load Balancing:Load balancing applications optimize power flow across the network to prevent overloads and ensure efficient electricity distribution.
- Energy Conservation:These applications use automation to identify and implement strategies for reducing energy consumption and improving grid efficiency.
- Power Quality Monitoring:PQ monitoring systems detect and analyze disturbances in the electrical supply, helping utilities maintain stable power delivery.
Outage Management holds the largest share of deployments, while Demand Response applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's rapid urbanization and extensive grid modernization initiatives drive significant investment in electric power distribution automation. This focus aligns with China's dual carbon goals, compelling utilities to enhance grid efficiency and renewable energy integration. The city's role as a financial and industrial hub necessitates a resilient and intelligent power infrastructure to support its economic growth.
United States
United States utilities prioritize grid resilience and reliability, driven by FERC orders mandating advanced distribution management systems. These regulations push for greater integration of distributed energy resources into the grid. California's energy market, particularly around Silicon Valley, sees high demand for DER management and grid-edge analytics.
China
China's national grid upgrades and dual carbon goals accelerate demand for Supervisory Control And Data Acquisition systems. Policies from the Ministry of Ecology and Environment (MEE) mandate smarter, more efficient distribution networks. Beijing's state-owned utilities are investing heavily in automation to manage vast urban power demands and renewable integration.
Germany
Germany's energy transition, spurred by the EU Green Deal, necessitates advanced distribution automation for renewable energy integration. The Corporate Sustainability Reporting Directive (CSRD) influences utility investment in transparent and resilient grid infrastructure. Munich's industrial region demonstrates strong adoption of Intelligent Electronic Devices for enhanced grid control.
India
India's burgeoning industrial growth and electrification efforts generate strong demand for modern distribution automation systems. The country's Central Electricity Authority (CEA) promotes grid modernization initiatives to reduce transmission and distribution losses. Bangalore's tech hub and surrounding industrial zones are driving pilot projects for smart grid solutions.
Global Electric Power Distribution Automation Systems Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution stack, offering integrated hardware and software platforms. The market exhibits a tiered consolidation, with established industrial conglomerates dominating high-value segments. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
On the premium-tier vector, Siemens AG, a German-based industrial conglomerate, exemplifies a comprehensive solution provider leveraging its extensive grid software portfolio for automation. Schneider Electric SE, a French-based multinational, occupies a strong position through its integrated EcoStruxure platform, emphasizing energy management and digital transformation. GE Vernova LLC, a US-based entity, anchors efforts to support decarbonization across North America and Europe with its advanced grid solutions, representing another major player in the high-value segment for utilities seeking full-spectrum capabilities.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| GE Vernova |
| Hitachi Energy Ltd. |
| General Electric Company |
| Itron |
| Mitsubishi Electric Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-backed software specialists often drive pricing discipline by focusing on recurring revenue models and specialized feature sets. This approach influences both software development cycles and hardware integration partnerships, shaping market entry and competitive dynamics.
Pricing Analysis
Price tied to grid uptime and efficiency improvements anchors the value proposition for distribution automation systems. Subscription-based SaaS platforms represent the dominant pricing model, particularly for software-centric solutions. Differentiation stems from customization levels for specific utility infrastructure and bundled after-sales service packages, driving higher value. Pricing softness reflects high upfront capital investment requirements for smaller municipal utilities, making them more price-sensitive.
Supply Chain Analysis
Domestic-content mandates in China and the United States reshape sourcing for critical grid components. Supply concentration for Intelligent Electronic Devices (IEDs) and specialized communication modules centers in China and Germany. Raw material dependencies include rare earth elements for sensors and advanced semiconductors for controllers. Single-source vulnerability for highly specialized IEDs presents a structural supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently a vertical-integration race, with players pursuing deeper integration into grid-edge analytics and distributed energy resource management. This strategy captures more value across the evolving energy ecosystem.
For Market Incumbents: Deploy platform consolidation strategies to integrate diverse hardware and software offerings. This move counters the threat from specialized software startups offering niche solutions for grid-edge applications. Investment in AI/ML research for predictive maintenance and advanced fault detection is a critical lever. Channel control through strong partnerships with utility system integrators reinforces market position. For New Entrants and Emerging Players: System integrators and specialized software developers should target microgrid automation and DER management platforms. This white space offers opportunities in regions like California, where DER penetration is high. A go-to-market angle leveraging subscription-based SaaS models for smaller municipal utilities provides market access. Focus on interoperability standards to ease integration with existing utility infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized software providers in Europe, where energy transition mandates are strict. Long-term viability hinges on companies that can manage complex data integration across diverse grid assets. Acquisition targets include niche cybersecurity firms and grid-edge analytics startups. The signal to watch is the acceleration of large-scale utility modernization projects in emerging economies.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Consolidation | Streamlines product offerings and improves integration capabilities for utility customers. |
| AI/ML R&D Investment | Enhances predictive maintenance and optimizes grid operations, reducing outages. |
| Subscription Model Expansion | Provides financial flexibility for utilities and ensures continuous revenue streams for vendors. |
| Cybersecurity Service Development | Protects critical grid infrastructure from evolving digital threats, building trust. |
| DER Management System Focus | Captures growth from increasing renewable energy and electric vehicle integration. |
Research Approach
Document review covered utility annual reports, regulatory filings, and technical standards, complemented by interviews with utility planning engineers, distribution network operators, IED manufacturers, and software architects. Secondary sources included FERC orders, EU Green Deal documents, MEE policies, and company whitepapers. Bottom-up data collection from market participants was triangulated with top-down market sizing.
Historical adoption rates and expert panel input provided a cross-reference for market projections across the analysis window. Segmentation dimensions modeled included system type, component, end-user, application, and regional regulatory mandates. Compound annual growth rates were derived from historical trends and anticipated regulatory impacts. Renewable energy penetration rates and EV charging infrastructure buildout served as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and rapid shifts in global economic policy. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Major cybersecurity breaches or significant supply chain disruptions could revise these projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Global Power Distribution Component Market
Power Distribution
Distribution Panel Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Distribution Board Market
Power Distribution
Power Distribution Cables Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
AI in Energy Distribution Market