
 Saudi Arabia Smart Grid Network Market | 2026-2036
Saudi Arabia Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Smart Grid Network Market Analytics
Project finance structures tied to long-term power purchase agreements are reshaping competitive entry in Saudi Arabia's smart grid sector. Saudi Electricity Company SJSC leverages its integrated generation-to-retail footprint to dominate transmission infrastructure deployment. ABB Ltd anchors its position through specialized high-voltage direct current integration capabilities for renewable interconnection. Schneider Electric SE differentiates via end-to-end digital energy management platforms tailored to Middle Eastern grid conditions.
A smart grid network constitutes an digitally enhanced electrical distribution system incorporating two-way communication protocols, automated control systems, and real-time data analytics operating across transmission voltages from 132 kV to 380 kV, designed to optimize power flow, reduce outage duration, and accommodate distributed generation sources. Advanced Metering Infrastructure leads technology deployment as utilities prioritize consumption visibility and demand-side load balancing. Grid Automation represents the fastest-growing application segment driven by substation digitization and fault self-healing requirements. Network Management services capture concentrated margin pools where system integration complexity requires specialized engineering expertise.
The Saudi Electricity and Cogeneration Regulatory Authority and the National Renewable Energy Program framework shape mandatory interconnection standards and smart meter rollout timelines for grid participants. SFDA oversight of electrical equipment safety certification and SASO smart device conformity requirements determine product market access pathways. Stakeholders must monitor evolving regulatory mandates around cybersecurity protocols and data localization as these will determine vendor qualification criteria and procurement eligibility.
Market Dynamics
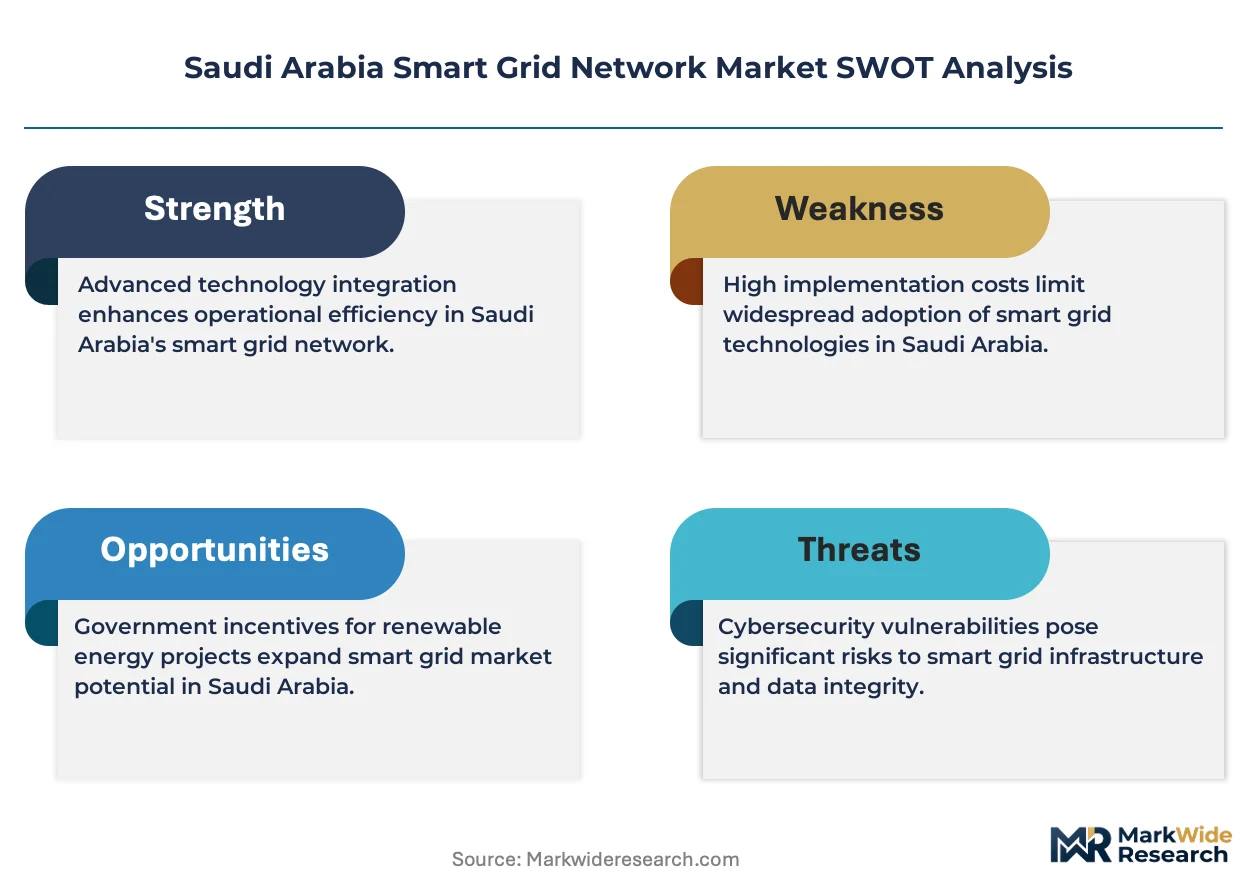
Utility-scale renewable integration under the National Renewable Energy Program is forcing rapid grid modernization across Saudi Arabia's transmission backbone. This structural pressure concentrates procurement in high-voltage automation systems capable of bidirectional power flow management.
Growth Catalysts
- ECRA Interconnection Mandates:Saudi Electricity and Cogeneration Regulatory Authority standards compel distributed generation compatibility, accelerating substation digitization investments.
- Industrial Load Centers:Petrochemical and desalination facilities in the Eastern Province drive demand for real-time demand response systems and automated voltage regulation.
- NEOM Smart City Development:Greenfield urban infrastructure projects embed native smart grid architecture without legacy retrofit constraints.
Market Restraints
- Copper and Rare Earth Input Volatility:Transformer core materials and permanent magnet dependencies expose procurement budgets to commodity price swings.
- European Component Concentration:High-voltage switchgear and protection relay supply chains cluster with German and Swiss specialty manufacturers.
- Cybersecurity Certification Friction:SFDA and National Cybersecurity Authority dual compliance timelines extend product qualification cycles.
Strategic Opportunities
- Tabuk and Northern Borders Electrification:Underpenetrated mining and logistics corridors require greenfield distribution automation deployment.
- Artificial Intelligence Convergence:Machine learning algorithms layered atop SCADA systems enable predictive load forecasting and anomaly detection.
- Performance-Based Service Contracts:Outcome-linked maintenance agreements replace traditional hardware procurement in Saudi Electricity Company tenders.
Industry Challenges
- Substation Engineering Talent Scarcity:Specialized protection and control system expertise remains concentrated with aging utility workforces.
- Legacy IEC 61850 Migration Complexity:Brownfield integration with proprietary communication protocols demands costly protocol gateway deployment.
- SASO Conformity Testing Bottlenecks:Smart meter and sensor certification queues at Saudi Standards, Metrology and Quality Organization facilities delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Smart Grid Network Market |
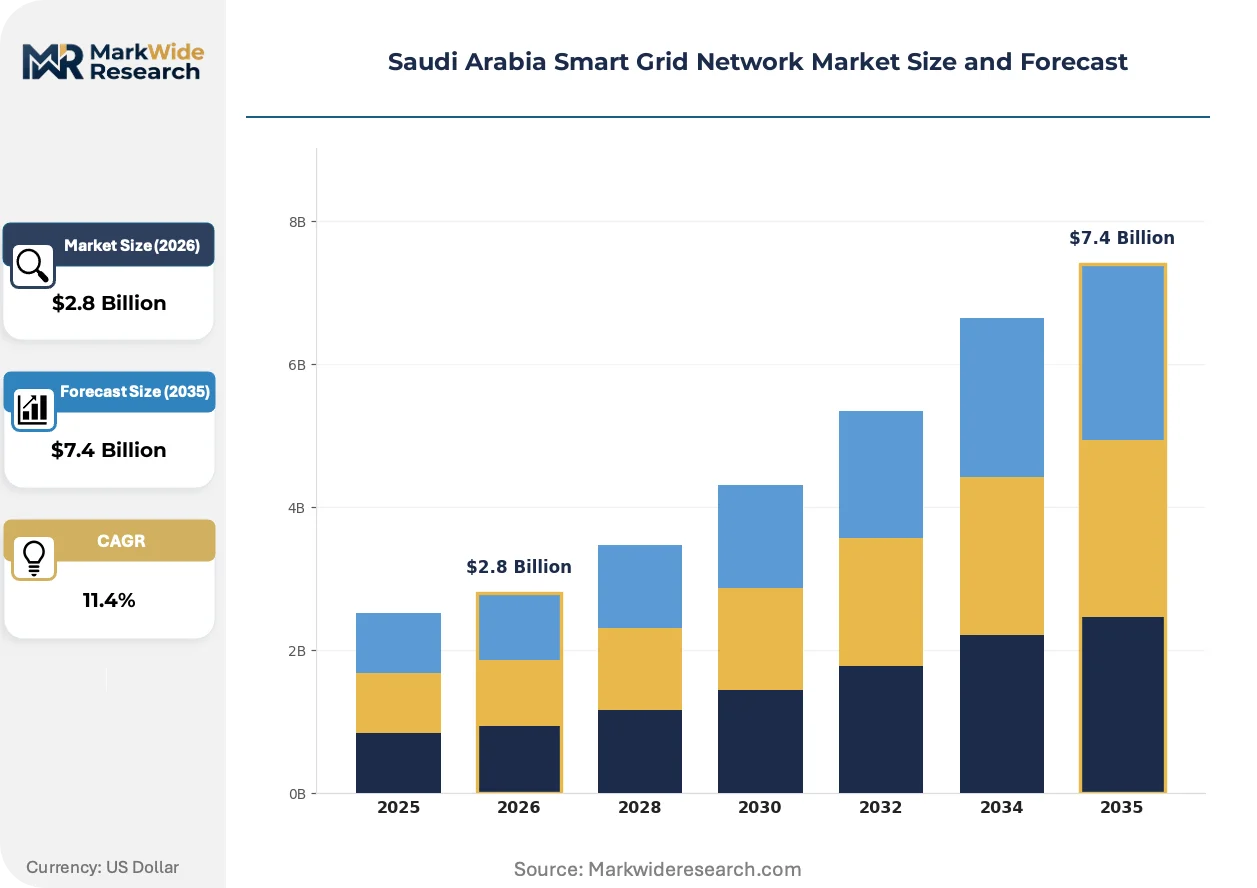
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Smart Sensors, Network Management Application: Electric Utility, Renewable Integration, Smart Metering, Grid Automation End User: Residential Customers, Commercial Establishments, Industrial Sector, Government Entities Service Type: Installation, Maintenance, Consulting, Integration |
| Companies Covered | Honeywell International Inc, Saudi Electricity Company SJSC, General Electric Company, Cisco Systems, Inc, Eaton Corporation plc, ABB Ltd, Schneider Electric SE, Itron Inc, Siemens Energy AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Smart Grid Network Market Evolving Landscape
Digital twin technology and edge computing architectures are redefining how Saudi grid operators manage asset performance. These capabilities compress response times from minutes to milliseconds.
Digital substation architecture is migrating from copper-wired protection schemes to fiber-optic process bus implementations. Saudi Electricity Company pilots this transition at 380 kV interconnection points. The technology is migrating from pilot validation to standardized procurement specifications, collapsing traditional relay panel footprints by two-thirds.
SFDA cybersecurity protocols and National Cybersecurity Authority critical infrastructure mandates now require encrypted device authentication and localized data storage. Industrial consequence includes mandatory hardware security module integration in all new automation deployments. Grid automation vendors are responding by pre-certifying product lines to Saudi-specific encryption standards before tender submission.
Asset-as-a-service contracting now dominates Saudi Electricity Company procurement for meter management and communication infrastructure. Traditional capital expenditure purchase models give way to decade-long availability guarantees with penalty clauses. This shift is most visible in Riyadh metropolitan rollouts where operational expenditure budgeting aligns with municipal fiscal cycles.
Saudi Arabia Smart Grid Network Market Segmentation
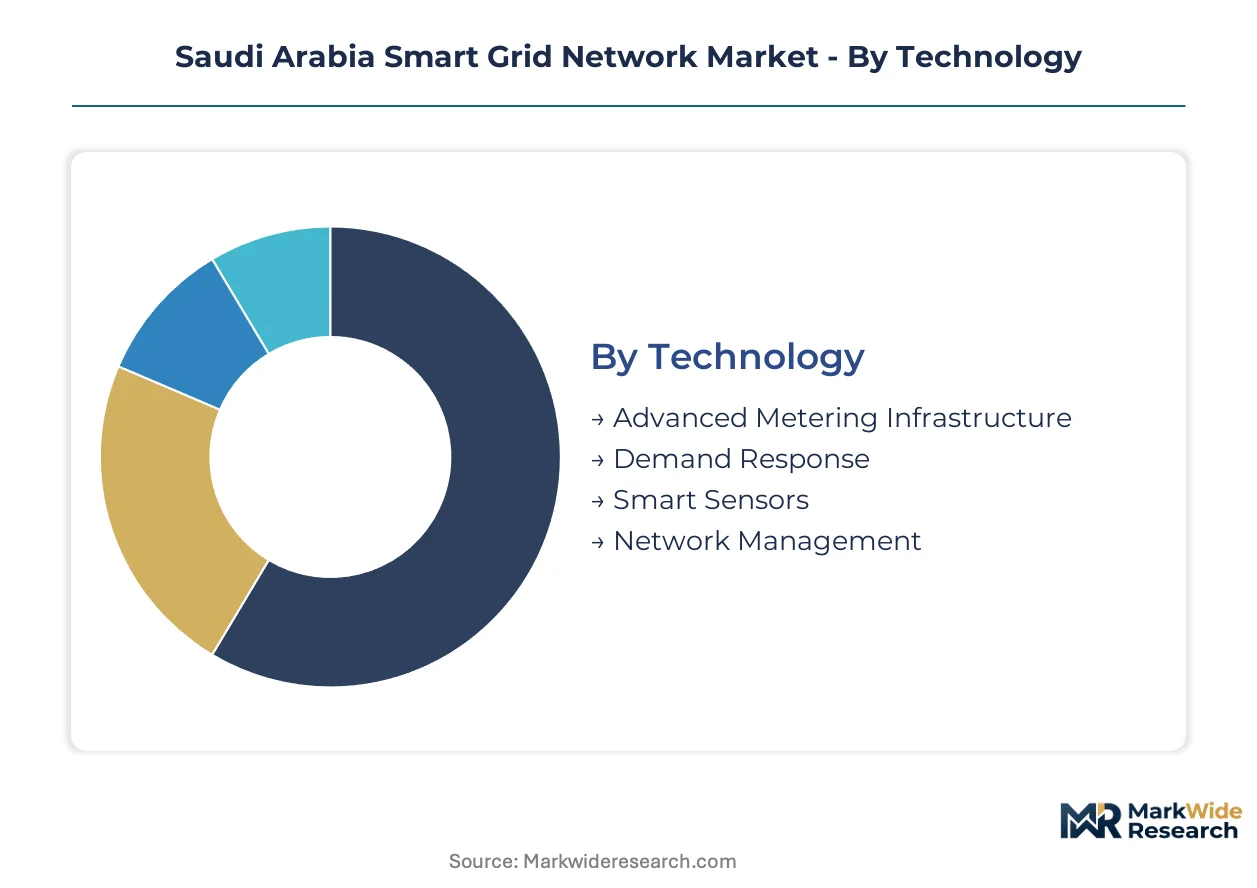
Segmentation of Saudi Arabia's smart grid network market reveals how procurement priorities diverge across technical capabilities, operational use cases, and institutional buyer profiles. Each dimension carries distinct vendor qualification requirements and margin structures that shape competitive positioning.
Technology:
Mature metering systems anchor current deployment volumes while emerging sensor networks capture modernization budgets.
- Advanced Metering Infrastructure:Two-way communication-enabled meter networks with integrated data concentrators and head-end systems. Deployment concentrates in Riyadh metropolitan distribution zones where Saudi Electricity Company prioritizes consumption visibility and tamper detection.
- Smart Sensors:Distributed temperature, current, and vibration monitoring devices with edge analytics capabilities. Demand clusters along 380 kV renewable interconnection corridors where real-time thermal monitoring prevents conductor overloading during bidirectional power flows.
- Demand Response:Automated load curtailment platforms enabling utility-controlled peak shaving.
- Network Management:SCADA-integrated control systems for outage detection and restoration optimization.
Advanced Metering Infrastructure handles the majority of throughput; Smart Sensors is the fastest mover on share.
Application:
Application segments span legacy utility operations through greenfield renewable infrastructure with divergent integration complexity.
- Grid Automation:Substation protection, control, and monitoring systems with IEC 61850 protocol compliance. Procurement accelerates at 132 kV and 380 kV interconnection points where ECRA mandates fault self-healing capabilities and automated sectionalizing.
- Renewable Integration:Inverter control, frequency regulation, and power quality management for variable generation sources. Deployment concentrates in Tabuk and Northern Borders regions where National Renewable Energy Program utility-scale solar and wind projects require grid-forming inverter capabilities.
- Electric Utility:Transmission and distribution infrastructure owned and operated by incumbent utilities.
- Smart Metering:Consumer-facing metering deployments with integrated communication modules.
Grid Automation commands the largest procurement envelopes; Renewable Integration is climbing the fastest as project pipelines mature.
End User:
End user categories reflect divergent load profiles, technical sophistication, and contracting authority within Saudi Arabia's electricity sector.
- Industrial Sector:Petrochemical complexes, desalination plants, and mining operations with high-voltage substations and captive generation. Demand concentrates in Eastern Province industrial cities where Jubail and Yanbu facilities require real-time power quality monitoring and automated voltage regulation for sensitive process loads.
- Government Entities:Municipal utilities, military installations, and public infrastructure operators with dedicated distribution networks. Procurement accelerates for NEOM and Red Sea Project developments where greenfield smart city specifications mandate native digital grid architecture without legacy retrofit constraints.
- Residential Customers:Single-family and multi-unit dwellings served by distribution utilities.
- Commercial Establishments:Retail, hospitality, and office buildings with sub-metering requirements.
The Industrial Sector generates the highest per-site revenue; Government Entities are gaining share fastest through megaproject development.
Service Type:
Service offerings span capital-intensive installation through recurring revenue maintenance and high-margin consulting engagements.
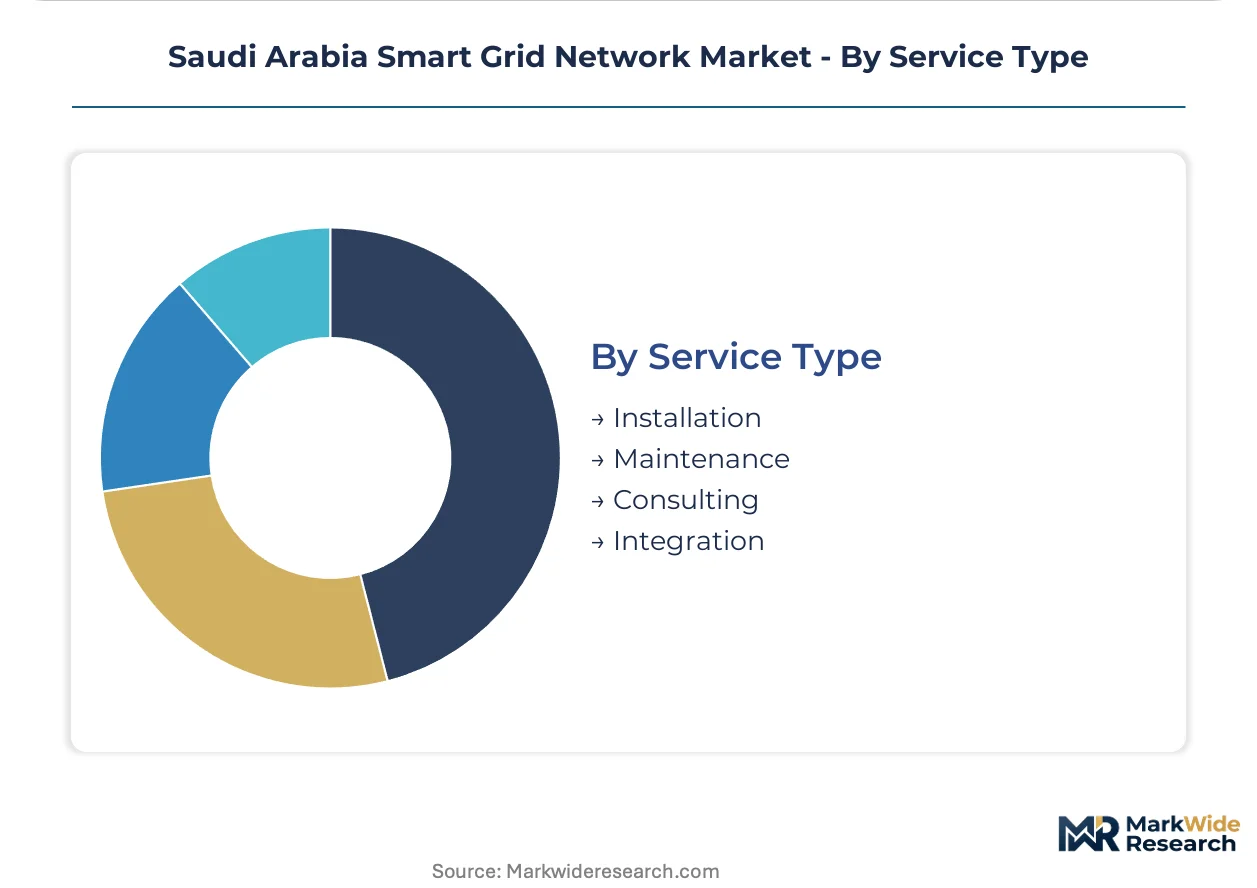
- Integration:System interoperability engineering, protocol gateway deployment, and multi-vendor platform consolidation. Demand concentrates where brownfield substations require IEC 61850 migration from proprietary communication schemes.
- Consulting:Grid modernization roadmapping, cybersecurity architecture design, and regulatory compliance advisory. Procurement rises around SFDA and National Cybersecurity Authority dual certification requirements where specialized expertise shortens qualification timelines.
- Installation:Physical deployment of meters, sensors, and automation hardware.
- Maintenance:Scheduled and corrective service for deployed infrastructure.
Integration captures concentrated margin pools; Consulting is expanding most quickly as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National Renewable Energy Program targets and ECRA interconnection mandates are redistributing smart grid procurement across Saudi Arabia's major economic zones. Regional deployment patterns reflect divergent load profiles, industrial density, and greenfield development opportunities.
Riyadh
The capital region concentrates Advanced Metering Infrastructure deployment where Saudi Electricity Company prioritizes consumption visibility across 3.5 million service points. ECRA smart meter rollout timelines accelerate procurement of two-way communication networks and tamper-detection systems. Riyadh metropolitan distribution zones absorb the majority of residential-facing grid automation investments.
Eastern Province
Petrochemical complexes at Jubail and Yanbu generate concentrated demand for real-time power quality monitoring and automated voltage regulation. Industrial load centers require high-reliability substation protection systems capable of isolating sensitive process equipment during grid disturbances. The region's desalination facilities anchor procurement of fault self-healing automation at 132 kV interconnection points.
Western Region
Jeddah and Mecca load centers drive transmission reinforcement projects linking Red Sea coastal demand with central generation assets. Hajj seasonal demand spikes necessitate demand response platforms with automated load curtailment capabilities. The region's commercial density supports pilot deployments of edge-computing network management systems.
Tabuk and Northern Borders
Utility-scale solar and wind projects under National Renewable Energy Program mandates require greenfield grid-forming inverter capabilities and 380 kV automation infrastructure. Mining and logistics corridors in underpenetrated areas present first-mover opportunities for distribution automation vendors. NEOM development specifications embed native digital substation architecture without legacy protocol migration constraints.
Saudi Arabia Smart Grid Network Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Saudi Arabia's smart grid procurement landscape. Saudi Electricity Company leverages its integrated generation-to-retail footprint to dominate transmission infrastructure deployment and influence vendor qualification standards. The market structures around three archetypes: integrated utility operators, high-voltage equipment specialists, and digital platform providers. Competitive moves concentrate on strategic partnerships for localization compliance and technology licensing for IEC 61850 protocol integration.
Among the integrated utility tier, Saudi Electricity Company anchors procurement authority through decade-long service contracts and captive distribution networks. Within the high-voltage equipment specialist tier, ABB Ltd and Siemens Energy AG exemplify vendors competing on renewable interconnection capabilities and digital substation expertise. Schneider Electric SE occupies a position bridging equipment supply and end-to-end energy management platforms. These three represent distinct competitive vectors: utility-captive deployment, specialized high-voltage integration, and software-layer differentiation.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Saudi Electricity Company SJSC |
| General Electric Company |
| Cisco Systems, Inc |
| Eaton Corporation plc |
| ABB Ltd |
| Schneider Electric SE |
| Itron Inc |
| Siemens Energy AG |
| Others |
Value Network & Pricing Analysis
German and Swiss high-voltage switchgear manufacturers anchor upstream supply for Saudi grid automation, concentrating margin capture in protection relay and circuit breaker tiers where ECRA certification requirements create vendor lock-in effects. Copper and rare earth magnet price volatility feeds directly into transformer procurement budgets, compressing margins for system integrators bidding on fixed-price substation contracts.
Pricing Analysis
Certification level (SASO/SFDA dual-grade) creates the primary spread between qualified and unqualified vendor tiers. Project-based fixed-price contracting dominates Saudi Electricity Company tenders, with price differentiation resting on cybersecurity compliance depth and localized service bundling. Cost compression in mid-tier automation hardware is intensifying because European component concentration limits sourcing alternatives. Industrial end-users in Jubail and Yanbu exhibit lowest price sensitivity due to process-critical uptime requirements, while municipal utilities in Riyadh face strict operational expenditure constraints.
Supply Chain Analysis
Contract manufacturing for smart meters and communication modules concentrates with Taiwanese and South Korean EMS providers serving as primary production capacity holders. Semiconductor fabrication for power management ICs draws from Taiwan, South Korea, and Germany, while transformer core steel sources from Japan and South Korea. Single-source vulnerability in 380 kV gas-insulated switchgear creates structural exposure to German and Swiss supplier lead times. Distribution runs through Saudi Electricity Company-controlled procurement channels with pre-qualified vendor lists determining market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's smart grid network market represents a high-growth disruption driven by National Renewable Energy Program mandates forcing bidirectional power flow infrastructure at utility scale. The convergence of greenfield smart city development and brownfield IEC 61850 migration creates bifurcated opportunity architectures for differentiated competitive positioning.
For Market Incumbents: Pre-empt emerging AI-native grid analytics vendors by embedding machine learning capabilities into existing SCADA deployments before predictive maintenance contracts become standard tender requirements. Deepen backward integration into cybersecurity hardware modules to capture margin pools currently flowing to specialized HSM suppliers and accelerate SFDA pre-certification cycles. For New Entrants and Emerging Players: Establish a beachhead in Tabuk and Northern Borders distribution automation where greenfield mining corridor electrification lacks incumbent vendor relationships. Target performance-based service contracts for meter management infrastructure where Saudi Electricity Company procurement is shifting from capital expenditure to availability-guarantee models, using localized joint ventures to satisfy SASO conformity testing proximity requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European high-voltage equipment specialists seeking Gulf market expansion platforms through Saudi distribution partnerships. Five-to-ten year viability hinges on regulatory compliance capability depth rather than hardware differentiation alone. Monitor National Cybersecurity Authority protocol evolution as the critical signal for vendor qualification barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Protocol Migration | Brownfield substation digitization unlocks recurring integration service revenue from Saudi Electricity Company legacy assets. |
| Cybersecurity Pre-Certification | SFDA and National Cybersecurity Authority dual compliance shortens tender qualification timelines against unprepared competitors. |
| Asset-as-a-Service Contracting | Decade-long availability guarantees align vendor economics with Saudi Electricity Company operational expenditure budgeting cycles. |
| AI-Enabled Predictive Maintenance | Machine learning overlay on SCADA systems captures high-margin consulting engagements around outage prevention outcomes. |
| Greenfield Smart City Partnerships | NEOM and Red Sea Project native digital architecture specifications bypass legacy protocol migration costs entirely. |
Research Methodology
The analysis maps Advanced Metering Infrastructure, Grid Automation, Renewable Integration, and Network Management services, each validated through utility planning officers, EPC contractors, grid operators, and protection system engineers. Primary interviews with Saudi Electricity Company procurement leads and secondary validation through ECRA regulatory filings, SASO certification databases, and National Renewable Energy Program project registries anchored segmentation sizing. Bottom-up deployment tracking across Riyadh, Eastern Province, and Tabuk regions triangulated against top-down utility capital expenditure disclosures.
Assumptions around ECRA interconnection mandate enforcement timelines and National Cybernergy Program project completion rates were held fixed across baseline scenarios, with renewable capacity addition trajectories and copper price bands varied in sensitivity testing. Segmentation dimensions modeled include technology tier, application complexity, end-user load profile, and service type contractual structure. CAGRs were derived from deployment run-rate analysis against utility-stated rollout timelines, incorporating grid automation hardware delivery cycles and smart meter installation capacity constraints.
Sensitivities concentrate around SFDA cybersecurity protocol evolution timelines and SASO testing facility throughput bottlenecks that could compress or extend commercialization windows. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity input price stability. Quarterly review of ECRA mandate publication updates and National Cybersecurity Authority technical specification releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Microgrid Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Grid Network Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Smart Grid Market
Smart Grid
Automated Demand Response Management Systems Market