
 South Africa Smart Grid Network Market | 2026-2036
South Africa Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Smart Grid Network Market Insights
Buyer concentration among South African municipal utilities is expanding as Eskom Holdings SOC Ltd consolidates procurement authority across metropolitan distributors. General Electric Company leverages its digital energy portfolio to anchor large-scale grid modernization tenders. Siemens AG competes through localized manufacturing partnerships that sustain cost advantages in hardware deployment.
The South Africa Smart Grid Network comprises digitally controlled electricity transmission and distribution systems integrating two-way communication, advanced sensors, and automated control algorithms to optimize power flow and reliability. These networks employ IEC 61850 protocol standards for substation automation and real-time data exchange between grid assets. Advanced Metering Infrastructure leads technology adoption due to prepaid electricity penetration and revenue protection priorities. Grid Automation commands premium margins within the Application Area dimension because utilities prioritize fault detection and self-healing capabilities over basic monitoring. Hardware Devices dominates the Solution Type category, though Software Solutions is gaining traction as utilities shift toward cloud-based asset management platforms.
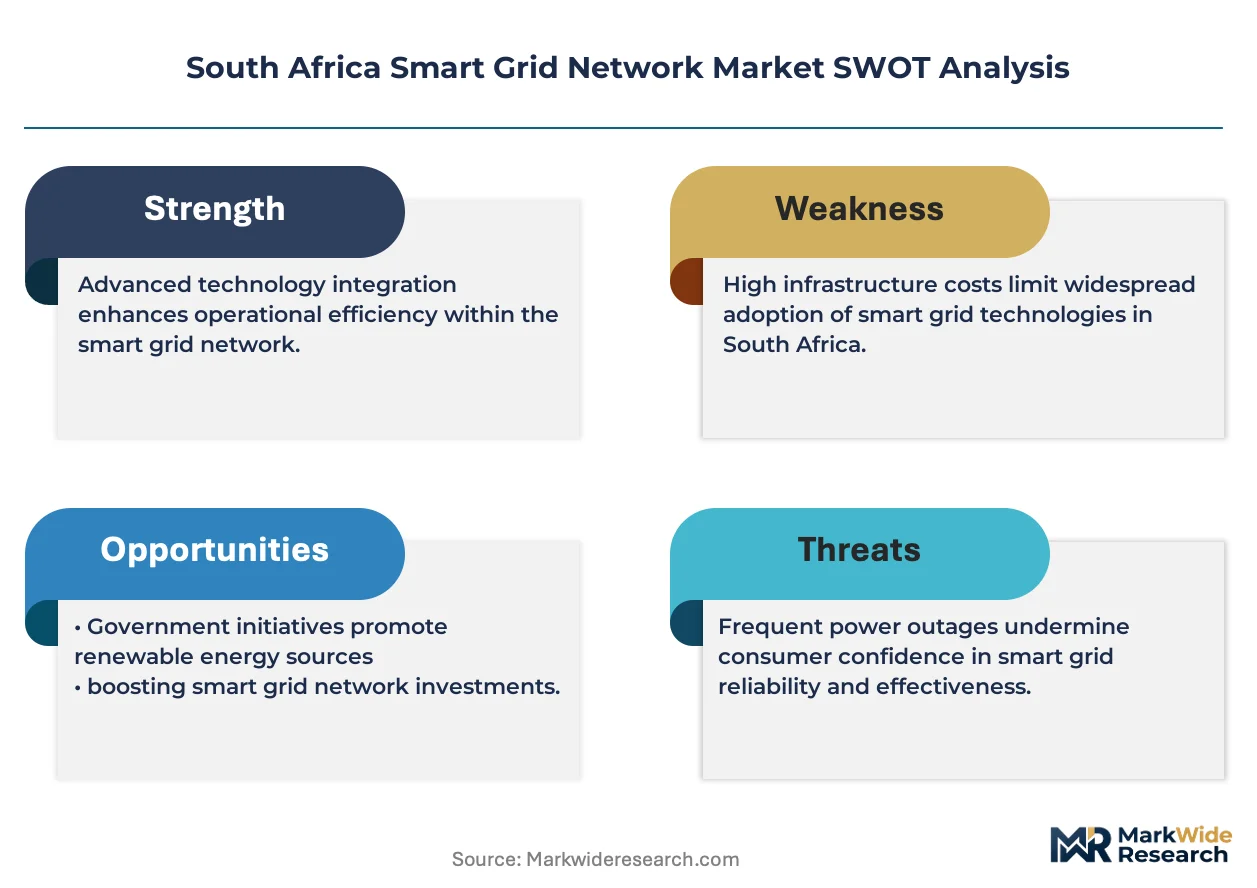
NERSA governs tariff structures and licensing frameworks that directly determine smart grid investment recovery periods for distribution utilities. SABS enforces equipment interoperability standards that shape procurement specifications and vendor qualification criteria. The country's central energy regulator also coordinates with the Department of Mineral Resources and Energy on integrated resource plan compliance timelines. Stakeholders must monitor how NERSA's pending distributed generation tariff methodology revision alters the business case behind behind-the-meter smart grid investments.
Market Dynamics
Eskom's unbundling into generation, transmission, and distribution entities is restructuring procurement authority across South Africa's electricity value chain. Municipal distributors now face direct accountability for revenue collection, accelerating technology deployment decisions.
Growth Catalysts
- NERSA Distributed Generation Licensing:Reformed licensing frameworks enable commercial and industrial facilities to connect rooftop solar and battery storage to municipal grids. Behind-the-meter installations require smart inverters and bi-directional metering infrastructure.
- Load Shedding Frequency:Persistent rotational power cuts drive demand for automated demand response systems and microgrid controllers among mining operations and manufacturing clusters in Mpumalanga and Limpopo provinces.
- Prepaid Electricity Normalization:Municipal utilities in Gauteng and Western Cape provinces prioritize revenue protection through tamper-resistant smart meters with remote disconnect capabilities.
Market Restraints
- Import Dependency for Semiconductors:Communication modules and power electronics rely on Asian supply chains, exposing deployment timelines to shipping volatility and currency depreciation against the US dollar.
- Municipal Fiscal Constraints:Ratepayer arrears exceeding 30 days in multiple metros compress capital budgets available for AMI rollout, forcing reliance on vendor financing arrangements with extended payback periods.
- Skills Concentration:Certified protection engineers and SCADA specialists cluster in Johannesburg and Cape Town, leaving secondary cities dependent on fly-in contractors for commissioning and maintenance.
Strategic Opportunities
- Eastern Cape Industrial Zones:Coega and East London automotive manufacturing hubs lack advanced grid infrastructure, creating first-mover advantage for integrated microgrid-as-a-service providers.
- Green Hydrogen Corridors:Northern Cape renewable energy zones require high-voltage direct current interconnections and grid-forming inverters to support electrolyzer loads, opening specialized hardware procurement.
- Cloud-Based Asset Management:Municipal utilities are migrating from on-premise SCADA to software-as-a-service platforms, enabling predictive maintenance without dedicated IT infrastructure investment.
Industry Challenges
- Legacy Meter Integration:Electromechanical meter estates in townships and informal settlements resist seamless AMI overlay, requiring dual-communication-path architectures that complicate vendor interoperability.
- Cybersecurity Certification Delays:SABS has not finalized standards for cryptographic modules in distribution automation devices, freezing procurement specifications for critical substation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Smart Grid Network Market |
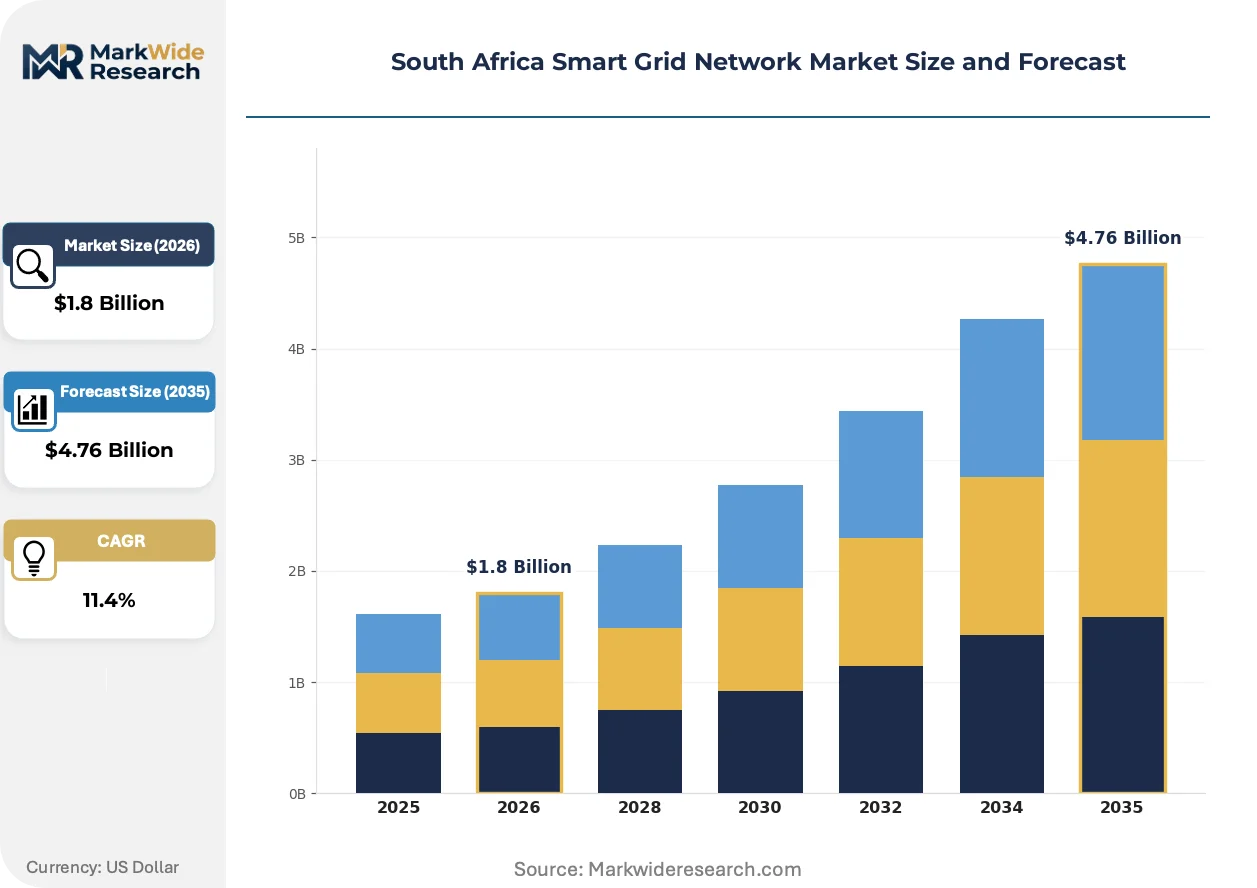
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Advanced Metering Infrastructure, Demand Response, Distribution Management Systems, Smart Sensors Application Area: Energy Management, Renewable Integration, Grid Automation, Load Balancing End User Type: Utilities, Industrial Sector, Commercial Buildings, Residential Users Solution Type: Software Solutions, Hardware Devices, Consulting Services, Maintenance Services |
| Companies Covered | Honeywell International Inc, General Electric Company, Eskom Holdings SOC Ltd, Itron Inc, Schneider Electric SE, Siemens AG, ABB Ltd, Landis+Gyr AG, Cisco Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Smart Grid Network Market Trends and Innovations
Digital substation architectures are displacing conventional copper-wired control systems across South African transmission infrastructure. IEC 61850 protocol adoption is compressing commissioning timelines while enabling remote diagnostics.
Artificial intelligence-based fault detection is automating outage response across metropolitan distribution networks. City Power Johannesburg and eThekwini Municipality deploy machine learning algorithms on feeder data to isolate cable faults within 500 milliseconds. Automated switching reduces customer minutes interrupted and defers capital-intensive line reinforcement.
NERSA's pending distributed generation tariff methodology revision is restructuring revenue models for municipal distributors. The framework will mandate time-of-use pricing and network access charges for embedded generators. Commercial and industrial facilities in Tshwane and Nelson Mandela Bay metros are pre-emptively installing interval meters and power quality monitors to capture export compensation accurately.
Outcome-based service contracts are displacing traditional equipment procurement in Eskom's transmission division. Performance guarantees covering availability and mean time to repair now determine vendor selection for substation automation packages. Maintenance responsibility shifts to OEMs, compressing utility staffing requirements while raising supplier working capital demands.
South Africa Smart Grid Network Market Segmentation
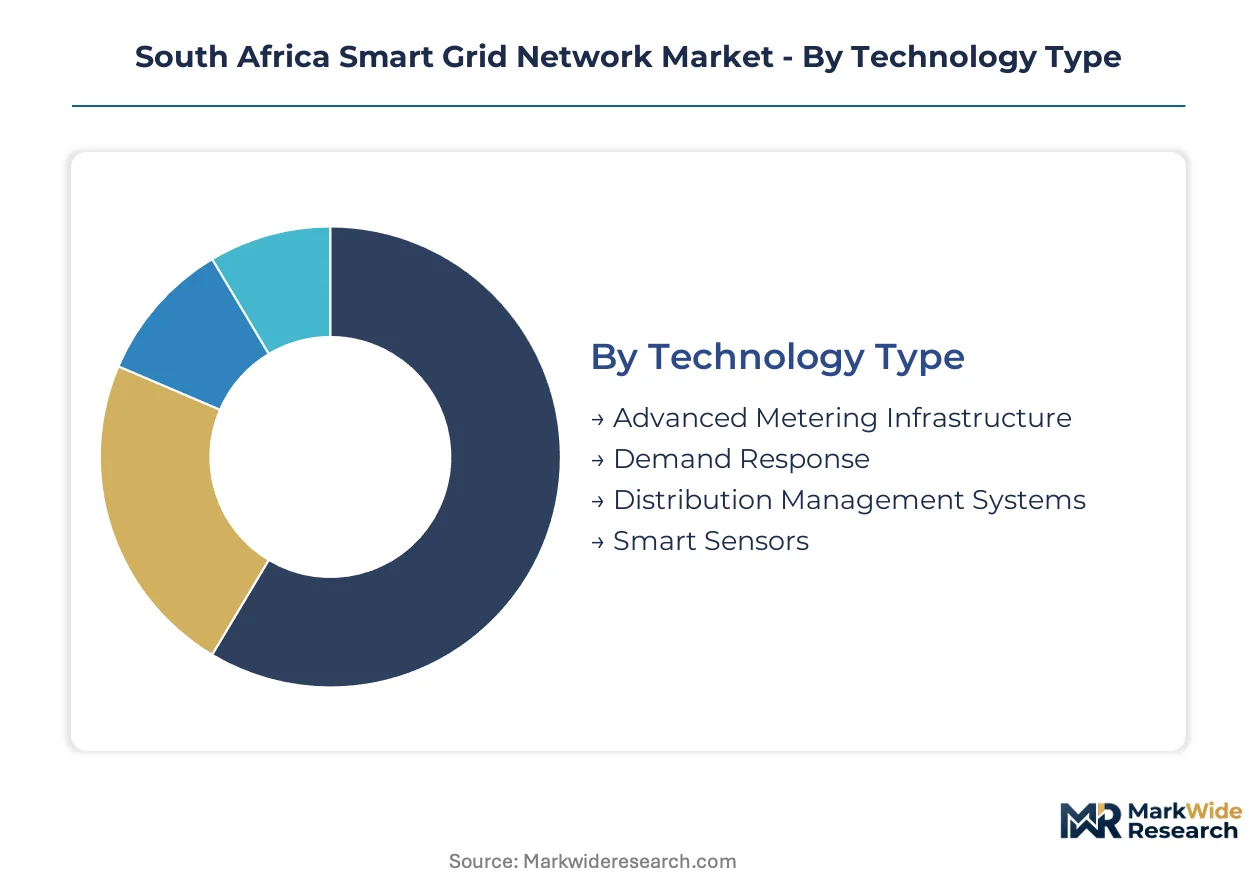
Smart grid procurement in South Africa fragments across four distinct dimensions that determine vendor selection criteria and contract structures. Technology type dictates protocol requirements and integration complexity. Application area shapes performance guarantees and revenue recovery mechanisms.
Technology Type:
Capital intensity varies sharply across these segments, with field-deployed hardware requiring substantially higher upfront investment than software-layer platforms.
- Advanced Metering Infrastructure:Tamper-resistant smart meters with bi-directional communication modules enable prepaid electricity normalization and remote disconnect capabilities. Municipal utilities in Gauteng province prioritize AMI rollouts to address revenue leakage in township distribution networks.
- Distribution Management Systems:SCADA-integrated platforms provide real-time feeder monitoring and outage management through centralized control centers. City Power Johannesburg and eThekwini Municipality anchor demand as they modernize legacy copper-wired control architectures.
- Demand Response:Automated load curtailment systems integrate with industrial process controls to enable rotational shedding compliance.
- Smart Sensors:IEC 61850-compliant devices monitor transformer health and cable temperature across substation networks.
Advanced Metering Infrastructure absorbs the bulk of installed capacity; Distribution Management Systems is expanding most quickly.
Application Area:
Margin profiles diverge based on whether deployments prioritize basic monitoring or autonomous fault response capabilities.
- Grid Automation:Self-healing networks deploy fault detection algorithms and automated switching to isolate cable failures within 500 milliseconds. Mining operations in Mpumalanga and Limpopo provinces drive procurement as load shedding frequency disrupts extraction schedules.
- Renewable Integration:Grid-forming inverters and power quality monitors manage bi-directional flows from rooftop solar and battery storage. Commercial facilities in Tshwane and Nelson Mandela Bay metros pre-emptively install interval metering ahead of NERSA's distributed generation tariff revision.
- Energy Management:Enterprise platforms optimize consumption patterns through interval data analytics and peak demand forecasting.
- Load Balancing:Dynamic phase switching and capacitor bank control stabilize voltage across radial distribution feeders.
Grid Automation commands premium pricing; Renewable Integration is climbing the fastest as licensing reforms accelerate behind-the-meter deployment.
End User Type:
Procurement authority concentrates differently across these customer categories, with municipal utilities consolidating tender specifications while industrial buyers pursue direct vendor relationships.
- Utilities:Eskom's unbundled transmission and distribution entities drive large-scale substation automation tenders with outcome-based performance contracts. Procurement specifications emphasize IEC 61850 interoperability and SABS certification compliance.
- Industrial Sector:Mining and automotive manufacturers deploy microgrid controllers and automated demand response to maintain production continuity during rotational power cuts. Coega and East London industrial zones lack advanced infrastructure, creating first-mover opportunities.
- Commercial Buildings:Retail and office complexes install smart metering to capture time-of-use pricing advantages under pending tariff reforms.
- Residential Users:Prepaid meter penetration dominates township and informal settlement electrification programs.
Utilities absorb the bulk of installed capacity; Industrial Sector is expanding most quickly as energy security concerns override capital constraints.
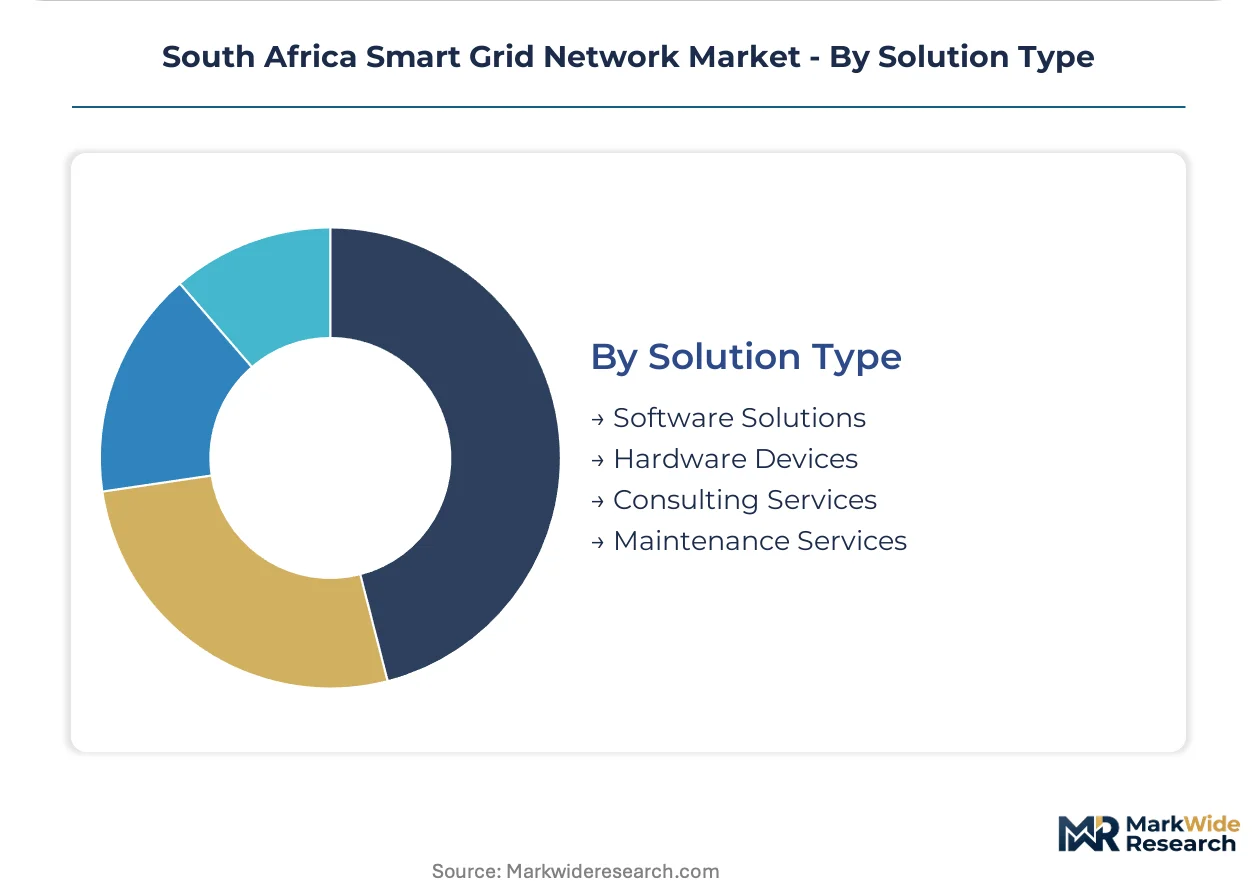
Solution Type:
Revenue recognition timelines stretch longest for hardware-intensive engagements, while recurring software subscriptions compress payback periods for municipal distributors facing fiscal pressure.
- Hardware Devices:Communication modules, protection relays, and smart meter endpoints constitute the physical layer of grid modernization. Import dependency for semiconductors exposes deployment timelines to shipping volatility and rand depreciation against the US dollar.
- Software Solutions:Cloud-based asset management platforms enable predictive maintenance without dedicated IT infrastructure investment. Municipal utilities migrate from on-premise SCADA to software-as-a-service models to reduce staffing requirements.
- Consulting Services:System integrators design multi-vendor architectures that reconcile legacy electromechanical estates with digital overlay networks.
- Maintenance Services:Performance-based contracts shift outage response accountability to OEMs, compressing utility technical staffing while raising supplier working capital demands.
Hardware Devices dominates current procurement value; Software Solutions is gaining share fastest as utilities prioritize operational expenditure over capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart grid investment concentrates in Gauteng province, where Johannesburg and Pretoria anchor the bulk of advanced metering infrastructure rollouts. Municipal utilities drive procurement decisions, with Eskom's unbundling restructuring authority across generation, transmission, and distribution entities. Provincial demand patterns reflect revenue protection priorities and load shedding frequency rather than uniform national deployment.
Gauteng
City Power Johannesburg and Tshwane Municipality deploy automated demand response systems to manage rotational power cuts. NERSA's pending distributed generation tariff revision mandates time-of-use pricing for commercial facilities. The Johannesburg-Pretoria corridor leads AMI penetration as prepaid electricity normalization accelerates smart meter procurement.
Western Cape
Cape Town's municipal distributor prioritizes tamper-resistant smart meters with remote disconnect capabilities in informal settlements. SABS equipment interoperability standards shape procurement specifications for vendor qualification. The Atlantis industrial zone attracts microgrid-as-a-service providers seeking first-mover positioning.
KwaZulu-Natal
eThekwini Municipality modernizes legacy copper-wired control architectures through SCADA-integrated distribution management platforms. The country's central energy regulator coordinates integrated resource plan compliance timelines with provincial distributors. Durban's manufacturing clusters install power quality monitors ahead of bi-directional metering requirements.
Mpumalanga
Mining operations deploy grid automation and self-healing networks to isolate cable faults within 500 milliseconds. Load shedding frequency disrupts extraction schedules, forcing capital deployment into automated switching systems. The Witbank-Middelburg coal belt anchors industrial demand response procurement.
Northern Cape
Renewable energy zones require high-voltage direct current interconnections and grid-forming inverters for electrolyzer loads. Green hydrogen corridors open specialized hardware procurement for utility-scale solar and wind integration. The Upington-Kimberley axis concentrates grid-edge investment for behind-the-meter battery storage.
South Africa Smart Grid Network Market Competitive Landscape
European producers anchor one tier; North American specialists hold differentiated positions in software and automation platforms. The vendor base fragments across hardware-intensive metering incumbents and cloud-native platform entrants. Three archetypes dominate: integrated industrial conglomerates with localized manufacturing partnerships; pure-play metering specialists with prepaid electricity expertise; and networking equipment providers pivoting into grid cybersecurity. Competitive moves concentrate on strategic partnerships for local content compliance and outcome-based service contracts that shift maintenance accountability to OEMs.
Within the integrated industrial tier, General Electric Company and Siemens AG exemplify divergent geographic positioning strategies. Honeywell International Inc occupies a position bridging automation hardware and enterprise software layers. These three anchors represent how procurement consolidation among municipal utilities favors vendors with established SABS certification pathways and demonstrated IEC 61850 interoperability. Local presence through manufacturing partnerships or system integration capabilities increasingly determines tender eligibility as Eskom's unbundled entities issue outcome-based performance contracts.
| Leading Market Players |
|---|
| Honeywell International Inc |
| General Electric Company |
| Eskom Holdings SOC Ltd |
| Itron Inc |
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd |
| Landis+Gyr AG |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
Copper price volatility on the London Metal Exchange cascades through South African smart grid procurement, compressing margins on hardware-intensive deployments while amplifying the cost advantage of software-centric service models. Municipal utilities facing fiscal pressure shift toward subscription-based asset management platforms that decouple upfront capital exposure from commodity-linked equipment costs.
Pricing Analysis
Volume concentrates in standardized AMI endpoints while margins pool in customized grid automation packages with performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified substation hardware from basic smart meter commodities. Cost compression in the hardware tier intensifies because rand depreciation against the US dollar inflates import-dependent semiconductor costs. Industrial mining operations show least price sensitivity due to production continuity premiums, while municipal distributors in secondary cities exhibit acute budget constraint responsiveness.
Supply Chain Analysis
Freight cost spikes on Asia-South Africa shipping lanes compound lead time uncertainty for communication modules and power electronics sourced from China, Taiwan, and South Korea. Manufacturing draws from concentrated Asian semiconductor foundries while final assembly rests on localized partnerships in Gauteng industrial zones. Single-source vulnerability around proprietary firmware in protection relays exposes deployment schedules to vendor-specific production bottlenecks. Distribution runs through municipal tender processes with extended vendor financing arrangements substituting for constrained public capital budgets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as Eskom's unbundling concentrates procurement authority among fewer municipal distributors with technical qualification requirements that exclude marginal vendors.
For Market Incumbents: Anchor market position through backward integration into local SABS certification laboratories that accelerate vendor qualification timelines. Deepen manufacturing partnerships in the Johannesburg-Pretoria corridor to satisfy local content thresholds in municipal tenders. Cloud-native platform entrants threaten traditional hardware margins; preemptive software-as-a-service bundling preserves account control. For New Entrants and Emerging Players: System integration specialists offer the fastest channel to revenue without capital-intensive manufacturing footprint. Eastern Cape industrial zones present underpenetrated white space where Coega and East London automotive hubs lack established vendor relationships. Green hydrogen corridor development in Northern Cape creates specialized procurement windows for grid-forming inverter expertise absent from incumbent portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-layer specialists with recurring revenue streams in Gauteng and Western Cape metros. Municipal fiscal compression forces asset divestitures among overleveraged hardware vendors. Long-term viability centers on vendors capturing cloud migration spend as utilities abandon on-premise SCADA infrastructure. Watch NERSA distributed generation tariff implementation as the inflection signal for behind-the-meter investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Local Manufacturing Partnership | SABS certification pathways satisfy municipal tender local content requirements. |
| Cloud Platform Migration | Software-as-a-service models reduce municipal IT infrastructure capital burdens. |
| IEC 61850 Interoperability Investment | Protocol compliance unlocks Eskom transmission division outcome-based contracts. |
| Cybersecurity Certification Pipeline | SABS cryptographic module standards pending for substation automation procurement. |
| Microgrid-as-a-Service Launch | Coega and East London industrial zones lack advanced grid infrastructure coverage. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, and grid operators underwrites the qualitative findings on procurement decision criteria. Secondary validation draws from NERSA regulatory filings, Eskom integrated report disclosures, and municipal tender documentation. Bottom-up segment sizing triangulates against top-down energy sector investment forecasts across the analysis window.
Comparable historical investment cycles in transmission and distribution modernization anchor the projection framework. Modeled dimensions span technology type, application area, end user category, and solution architecture throughout the forecast period. CAGRs derive from segment-level deployment trajectories informed by municipal capital budget allocations and licensing reform implementation velocity.
Caveats apply where NERSA tariff methodology revisions or municipal fiscal distress could materially shift the outlook. Forecasts reflect assumptions around rand exchange rate stability and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Data Management Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Power Grid Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Microgrid Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Europe Microgrid Market
Smart Grid
North America Smart Grid Market
Smart Grid
North America Microgrid Market
Smart Grid
Microgrid Controller Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Grid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Europe Automated Demand Response Market