
 Global Smart Grid Security Market | 2026-2036
Global Smart Grid Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Grid Security Market Foresight
The EU Green Deal is recalibrating procurement priorities for European electric utilities by embedding cybersecurity into clean energy transition mandates. Cisco Systems leverages its networking heritage to dominate edge-computing security architectures for grid operators. Siemens anchors its position through deep vertical integration into industrial control systems and substation automation. IBM competes by combining AI-driven threat intelligence with utility-specific consulting frameworks.
Smart grid security encompasses hardware, software, and services that protect generation, transmission, and distribution systems from cyber-physical attacks, typically employing IEC 62351 cryptographic standards and real-time anomaly detection protocols to ensure continuity of electricity supply. Encryption technologies and identity access management solutions command premium pricing as utilities face escalating ransomware exposure across advanced metering infrastructure. Cloud-based deployment modes are gaining share fastest among independent system operators seeking elastic compute for threat analytics without capital-intensive on-premise buildouts. Demand response management use cases require specialized security stacks that segment operational technology networks from enterprise IT environments.
The Federal Energy Regulatory Commission in the United States mandates Critical Infrastructure Protection standards that compel North American utilities to maintain audited cybersecurity postures across bulk electric systems. EMEA markets face parallel compliance pressure through the NIS2 Directive and IEC 62559 framework harmonization. Japan's METI issues sector-specific guidelines for smart meter security that shape procurement specifications for domestic and export markets. Stakeholders must weigh the trade-off between cloud agility and hybrid architectures as regulatory jurisdictions diverge on data sovereignty requirements for critical energy infrastructure.
Market Dynamics
Grid digitization is forcing electric utilities to rebuild security architectures around real-time operational technology monitoring rather than periodic enterprise IT audits. The convergence of distributed energy resources and advanced metering infrastructure multiplies attack surfaces faster than legacy protection frameworks can adapt.
Growth Catalysts
- NIS2 Directive compliance deadlines:European utilities must upgrade cybersecurity postures for critical energy infrastructure by mandated timelines, accelerating procurement of intrusion detection systems and encryption technologies.
- Smart meter deployment waves:Japan's METI guidelines shape domestic and export market specifications, creating standardized security requirements that reduce procurement friction for compliant vendors.
- Ransomware exposure escalation:Electric utilities face targeted attacks on advanced metering infrastructure, driving premium pricing for identity access management and network segmentation solutions.
Market Restraints
- Specialized talent scarcity:Cybersecurity professionals with combined IT and operational technology expertise command compensation premiums that strain utility OPEX budgets.
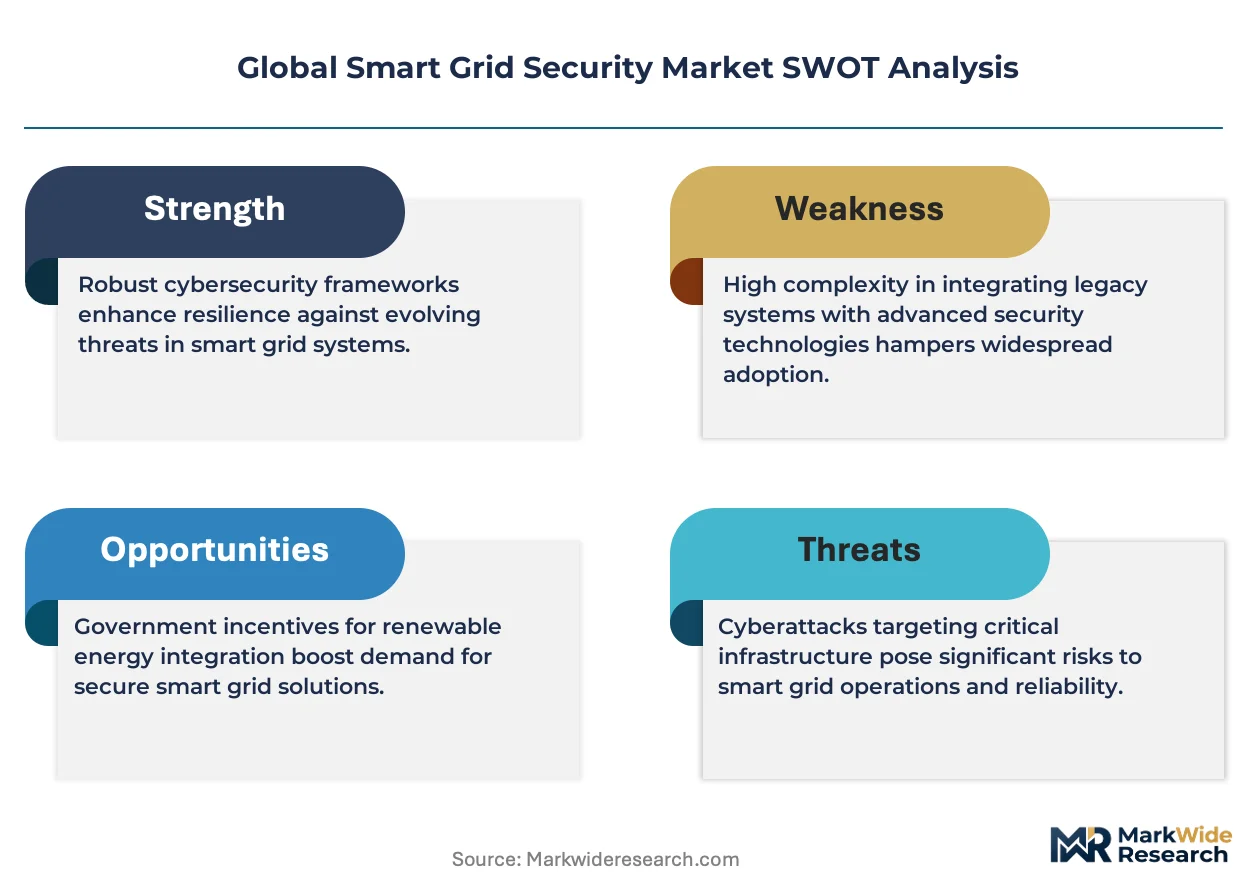
- Legacy system integration friction:Decades-old supervisory control and data acquisition protocols lack native encryption, requiring expensive gateway retrofits.
- Regulatory fragmentation across jurisdictions:Divergent data sovereignty requirements between FERC-mandated US bulk electric systems and EU cloud deployment preferences complicate vendor product strategies.
Strategic Opportunities
- Cloud-based deployment elasticity:Independent system operators seek threat analytics without capital-intensive on-premise buildouts, favoring subscription security service models.
- Demand response management security stacks:Specialized segmentation between operational technology networks and enterprise IT environments addresses emerging distributed energy resource integration risks.
- EU Green Deal cybersecurity embedding:Clean energy transition mandates recalibrate procurement priorities to treat grid security as integral to renewable infrastructure rather than bolt-on compliance.
Industry Challenges
- IEC 62351 implementation complexity:Cryptographic standard adoption across heterogeneous substation automation equipment requires extensive interoperability testing.
- Operational technology security skill gaps:Utilities struggle to staff security operations centers with personnel fluent in both industrial control systems and modern threat intelligence platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Grid Security Market |
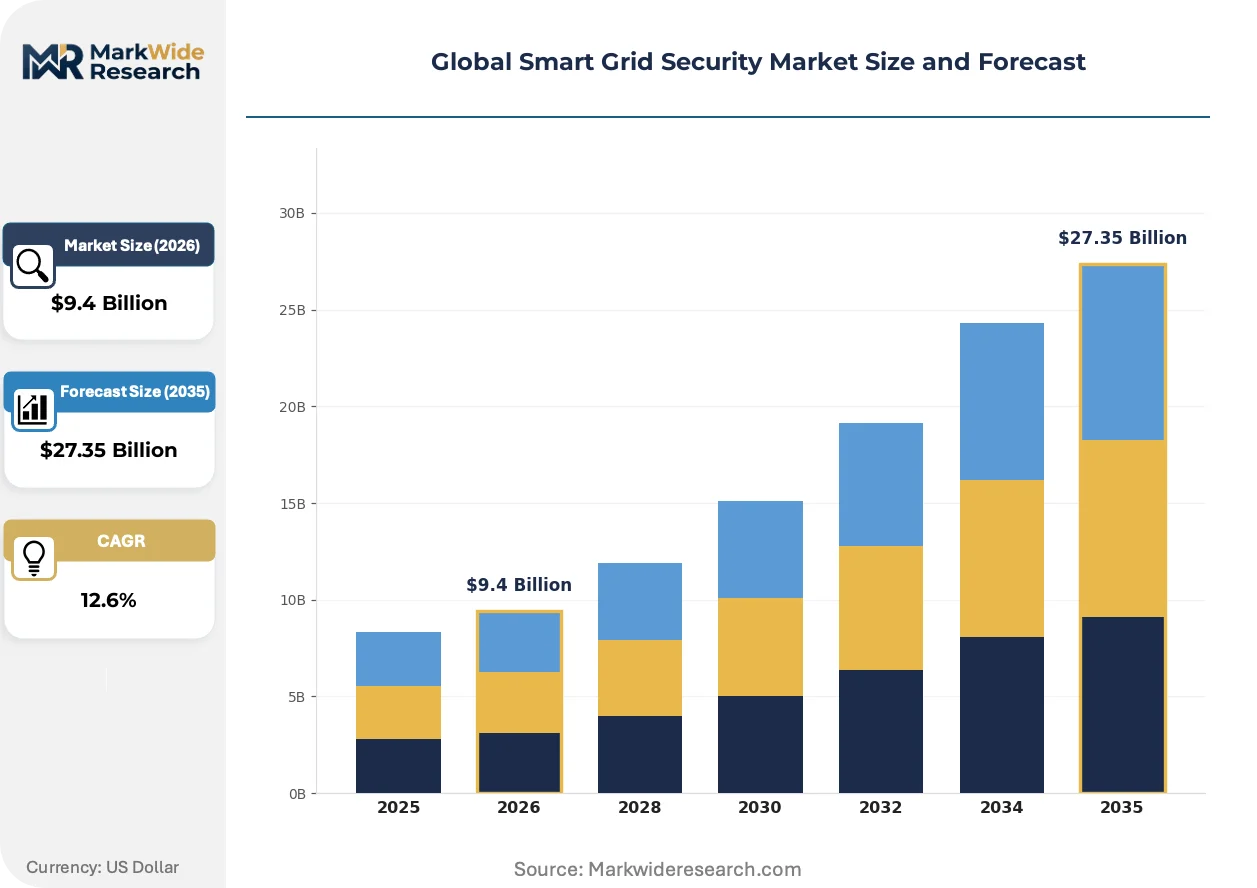
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $27.35 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Intrusion Detection Systems, Security Information & Event Management, Firewalls, Encryption Technologies, Identity & Access Management Deployment Mode: Cloud-Based, On-Premise, Hybrid, Edge Computing Use Case: Advanced Metering Infrastructure Security, Demand Response Management, Distributed Energy Resource Management, Grid Monitoring & Control Customer Type: Electric Utility Providers, Independent System Operators, Transmission Operators, Microgrid Operators |
| Companies Covered | BAE Systems, Cisco Systems, IBM, Lockheed Martin Corporation, Siemens, Honeywell International, Broadcom, Oracle Corporation, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Grid Security Market Shifts & Advancements
Artificial intelligence is reshaping how utilities detect anomalous grid behavior, compressing response times from hours to milliseconds. Edge computing architectures and zero-trust network models are displacing perimeter-based security as the dominant design paradigm.
AI-driven anomaly detection is expanding into substation automation and distribution feeder monitoring. Mid-sized municipal utilities in Germany and Japan are adopting these platforms fastest, drawn by reduced false-positive rates compared to signature-based systems. The technology is expanding into predictive maintenance workflows, creating unified platforms that merge cybersecurity and asset reliability functions.
The EU AI Act imposes risk-classification requirements on automated decision systems in critical infrastructure. Grid operators deploying machine learning for load balancing or fault isolation must now document algorithmic transparency and human oversight protocols. German transmission system operators are responding by segregating AI-enhanced security tools into standalone audit trails.
Utility procurement teams now specify outcome-based security service level agreements rather than perpetual software licenses. Managed security service providers capture growing share among independent system operators seeking 24/7 monitoring without internal security operations center buildouts. This pattern is most visible in US independent system operator territories where FERC audit requirements demand continuous compliance documentation.
Global Smart Grid Security Market Segmentation
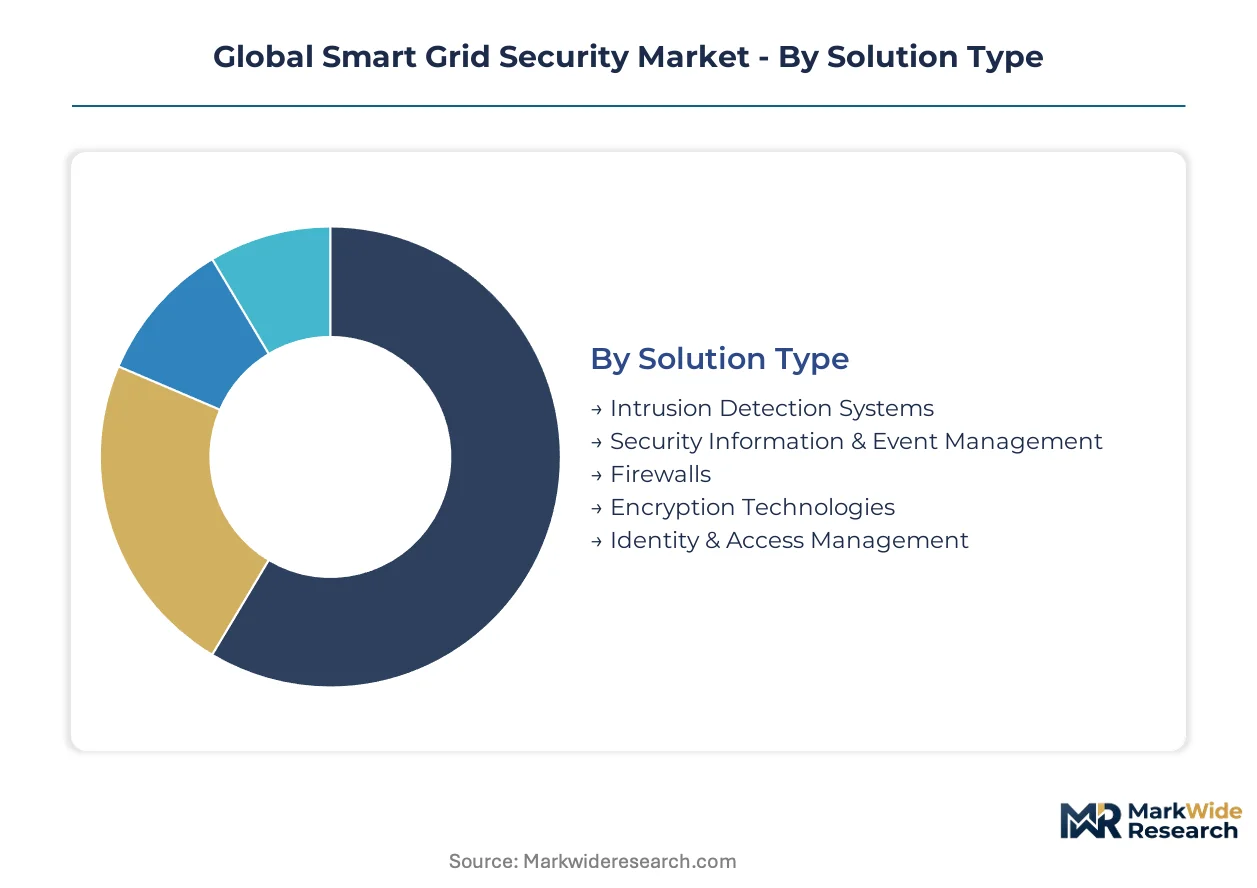
Smart grid security procurement varies sharply by infrastructure vintage and operational technology maturity. Utilities segment investments across solution architectures, deployment models, application contexts, and operational roles to match regulatory mandates against legacy system constraints.
Solution Type:
Customization ranges from standardized network appliances to bespoke cryptographic implementations tailored to substation automation protocols.
- Encryption Technologies:IEC 62351-compliant cryptographic modules protect data integrity across generation, transmission, and distribution systems. German transmission system operators and US bulk electric utilities drive demand as FERC and NIS2 Directive mandates harden data protection requirements for critical energy infrastructure.
- Intrusion Detection Systems:Real-time anomaly detection platforms monitor operational technology networks for cyber-physical attack signatures. Japanese utilities under METI guidelines prioritize these systems for smart meter backhaul networks, while European operators deploy them for distributed energy resource integration points.
- Identity & Access Management:Multi-factor authentication and privileged access controls for industrial control environments.
- Security Information & Event Management:Centralized log aggregation and correlation for cross-domain threat visibility.
- Firewalls:Protocol-aware network segmentation between IT and OT environments.
Leading the category by volume: Encryption Technologies. Growing fastest: Intrusion Detection Systems.
Deployment Mode:
Cost tier stratification separates capital-intensive on-premise builds from operational expenditure-friendly subscription models.
- Cloud-Based:Elastic compute for threat analytics delivered via subscription without data center construction. Independent system operators in the United States favor this model to satisfy FERC audit requirements while avoiding security operations center buildout costs.
- Edge Computing:Distributed processing architectures reduce latency for real-time grid control decisions. Siemens and Cisco Systems compete intensely here for substation automation deployments across Germany and Japan.
- Hybrid:Segregated workloads split sensitive operational data on-premise with analytics in cloud environments.
- On-Premise:Air-gapped installations for critical infrastructure operators with strict data sovereignty requirements.
Cloud-Based deployments capture the steepest expansion trajectory as independent system operators prioritize operational flexibility. Edge Computing maintains premium pricing for latency-sensitive applications.
Use Case:
Application maturity determines whether security stacks are retrofitted onto existing systems or designed into greenfield infrastructure.
- Advanced Metering Infrastructure Security:End-to-end protection for smart meter communications spanning residential premises to utility data centers. Japan's nationwide deployment under METI guidelines and Germany's rollout create concentrated demand for tamper-resistant modules and secure backhaul protocols.
- Distributed Energy Resource Management:Security frameworks for solar, storage, and electric vehicle integration at distribution grid edge. US utilities in California and Texas lead adoption as renewable penetration climbs and attack surfaces multiply.
- Demand Response Management:Segmentation protocols isolating operational technology load control systems from enterprise IT networks.
- Grid Monitoring & Control:Protection for supervisory control and data acquisition systems and wide-area situational awareness platforms.
Advanced Metering Infrastructure Security dominates current procurement volumes. Distributed Energy Resource Management is expanding most quickly as clean energy transition accelerates.
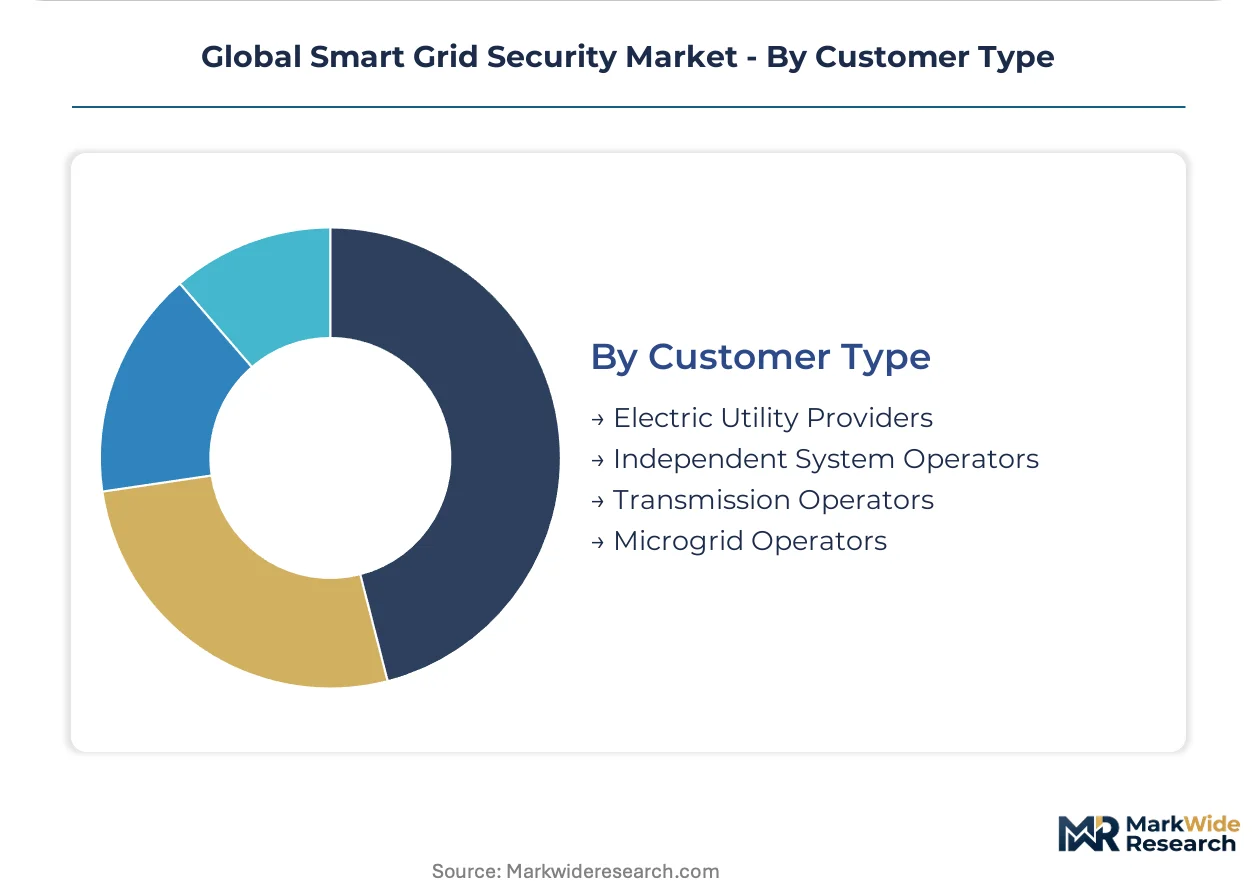
Customer Type:
Customer scale and regulatory exposure shape procurement sophistication and contract structures.
- Electric Utility Providers:Vertically integrated generation, transmission, and distribution operators with comprehensive NERC CIP or NIS2 compliance obligations. US investor-owned utilities and European national champions represent the largest contract values for end-to-end security platform deployments.
- Independent System Operators:Regional grid coordinators managing wholesale electricity markets and transmission reliability. These entities in Texas, California, and the Mid-Atlantic drive cloud-based security service adoption through outcome-based service level agreements.
- Transmission Operators:High-voltage network specialists with critical infrastructure protection mandates.
- Microgrid Operators:Campus, military, and industrial facilities with islanding capabilities and specialized segmentation requirements.
Electric Utility Providers lead by contract value. Independent System Operators are gaining share fastest through managed security service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American smart grid security procurement as Texas utilities fortify independent system operator infrastructure against escalating cyber-physical threats. European demand concentrates in German industrial corridors where transmission operators retrofit substation automation with IEC 62351 cryptographic modules. Japanese metropolitan clusters drive standardization through METI-mandated smart meter security specifications.
United States
Independent system operators in Texas and California accelerate cloud-based security service adoption to satisfy FERC audit requirements without capital-intensive security operations center buildouts. The Federal Energy Regulatory Commission mandates Critical Infrastructure Protection standards across bulk electric systems. Houston and Austin clusters host the densest concentration of utility cybersecurity procurement teams.
Germany
Transmission system operators prioritize IEC 62351-compliant encryption for substation automation as NIS2 Directive deadlines approach. The EU Green Deal embeds cybersecurity into clean energy transition mandates. North Rhine-Westphalia and Bavaria industrial corridors concentrate demand response management security stack deployments.
Japan
Utilities under METI guidelines standardize intrusion detection systems for smart meter backhaul networks. The Ministry of Economy, Trade and Industry issues sector-specific security specifications shaping domestic and export procurement. Tokyo and Osaka metropolitan areas drive advanced metering infrastructure security deployment at scale.
United Kingdom
Distribution network operators segment operational technology networks from enterprise IT environments under NIS2 harmonization pressure. The National Cyber Security Centre collaborates with energy regulators on critical infrastructure protection frameworks. London and Southeast England clusters concentrate managed security service provider relationships.
India
State electricity boards pilot encryption technologies for advanced metering infrastructure as renewable integration accelerates. The Central Electricity Authority issues cybersecurity guidelines for power sector critical infrastructure. Maharashtra and Gujarat industrial corridors host early distributed energy resource management security deployments.
Global Smart Grid Security Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with industrial control systems heritage. Market concentration remains moderate with clear tiering between full-platform providers and specialized cybersecurity vendors. Two strategic archetypes dominate: networking infrastructure specialists leveraging edge-computing architectures, and industrial automation incumbents with deep substation protocol expertise. Competitive moves center on strategic partnerships for AI-driven threat intelligence and geographic expansion through localized compliance certification.
Among diversified technology conglomerates, Siemens and General Electric occupy positions exemplifying industrial automation incumbency, while Cisco Systems represents the networking infrastructure specialist archetype. These three anchors demonstrate how competitive positioning stratifies between protocol-native industrial control expertise and cloud-native security service delivery. Each sits within distinct procurement channels—Siemens and General Electric through long-cycle substation retrofit relationships, Cisco through independent system operator cloud migration contracts.
| Leading Market Players |
|---|
| BAE Systems |
| Cisco Systems |
| IBM |
| Lockheed Martin Corporation |
| Siemens |
| Honeywell International |
| Broadcom |
| Oracle Corporation |
| General Electric Company |
| Others |
Supply & Pricing Matrix
The EU Green Deal gates qualified supply and premium-tier pricing access for smart grid security vendors, mandating IEC 62351 cryptographic compliance and NIS2 Directive alignment as non-negotiable entry requirements for European utility procurement. Utilities in Germany and Japan pay substantial premiums for certified encryption modules and intrusion detection systems that satisfy these environmental-cybersecurity fusion mandates, while uncertified competitors face automatic disqualification regardless of price competitiveness.
Pricing Analysis
Outcome-based security service level agreements anchor pricing structures, with independent system operators contracting for guaranteed uptime and threat response latency rather than perpetual software licenses. Subscription tiers stratify across premium, standard, and economy levels based on IEC 62351 certification grade and after-sales monitoring intensity. Cost compression in the economy tier intensifies because cloud-native entrants are undercutting legacy on-premise vendors. Municipal utilities in Japan exhibit highest price sensitivity due to constrained public budgets, while German transmission system operators show least sensitivity given NIS2 compliance penalties for underinvestment.
Supply Chain Analysis
IEC 62351 and FERC CIP certification requirements gate component sourcing, with qualified cryptographic module suppliers concentrated in Germany, the United States, and Japan. Hardware production draws from Taiwan for semiconductor components, South Korea for memory modules, and domestic foundries in Germany and Japan for classified operational technology chips. Single-source vulnerability runs through Taiwan-based foundries serving the encryption chipset layer. Distribution runs through authorized systems integrators with substation automation expertise rather than open channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play. NIS2 Directive compliance deadlines are forcing weaker players without certified product portfolios into distressed exits or acquisition targets.
For Market Incumbents: Acquire specialized AI-driven threat intelligence assets to fortify against cloud-native security challengers entering through managed service channels. Siemens and Cisco Systems should deepen backward integration into IEC 62351 cryptographic chipset design to capture margin from qualified supply scarcity. Certification investment in emerging economies creates channel control before local champions mature. For New Entrants and Emerging Players: Cloud-based managed security service delivery offers the lowest friction entry path for penetrating US independent system operator territories where FERC audit requirements favor subscription models over capital builds. Municipal utilities in India and mid-sized grid operators in Texas represent the most penetrable buyer segments given limited incumbent relationship lock-in. Partner with established systems integrators possessing utility security clearances rather than building direct sales infrastructure. For Investors and Strategic Acquirers: METI guideline revision announcements are the leading indicator that Japanese smart meter security procurement waves will accelerate, signaling acquisition timing for intrusion detection specialists with compliant product portfolios. The 5-10 year viability window favors vendors combining industrial control systems heritage with cloud-native delivery architecture. Target acquisition profile: mid-cap encryption technology firms with IEC 62351 certification and existing German utility relationships. Watch for EU AI Act enforcement actions against non-compliant automated grid decision systems as the inflection signal for AI-security consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | AI-driven threat intelligence assets address the operational technology security skill gap FERC auditors now flag. |
| Certification Investment | IEC 62351 compliance unlocks NIS2 Directive procurement windows in German transmission operator retrofit programs. |
| Platform Integration | Unified cybersecurity-asset reliability platforms merge Siemens substation automation with IBM consulting frameworks. |
| Strategic Partnership | Cisco Systems leverages networking heritage through independent system operator cloud migration alliances. |
| Geographic Expansion | METI guideline alignment opens Japanese smart meter backhaul markets for intrusion detection system vendors. |
Research Methodology
Multi-period observation of encryption technology procurement volumes, intrusion detection system deployment rates, and utility cybersecurity budget allocations anchored the trend analysis, supplemented by interviews with utility chief information security officers, substation automation engineers, independent system operator planning directors, and managed security service provider account executives. Secondary validation drew from FERC CIP compliance filings, NIS2 Directive implementation guidance, METI smart meter security specifications, IEC 62351 standard documentation, and EIA grid modernization expenditure surveys. Bottom-up utility procurement tracking and top-down market sizing triangulated volume estimates.
Input-output matrices mapped solution type demand against deployment mode capacity constraints, customer type budget cycles, and use case regulatory urgency across the projection horizon. Segmentation dimensions modeled include solution architecture, deployment model, application context, and operational role alongside geographic regulatory framework clusters. CAGRs were derived from utility capital expenditure trajectories and cybersecurity OPEX conversion trends. Forecast inputs incorporated ransomware incident frequency reporting and distributed energy resource integration timelines.
The model holds under stable NIS2 and FERC enforcement intensity; deviation in EU AI Act risk-classification implementation or METI guideline acceleration would shift demand timing. Forecasts reflect documented assumptions about utility digitization pacing and certification adoption curves. A model refresh is warranted upon material change in critical infrastructure protection penalty structures or cryptographic standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
UK Smart Grid Network Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Grid Network Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
North America Smart Grid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Power Grid Market
Smart Grid
Smart Energy Switch Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market