
 China Semiconductor Market | 2026-2036
China Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
China Semiconductor Market Intelligence
China's state-backed investment in new foundry capacity is rebalancing the domestic supply chain away from reliance on foreign fabrication. Semiconductor Manufacturing International Corporation (SMIC) anchors the country's logic chip manufacturing capabilities. Yangtze Memory Technologies Corp. (YMTC) specializes in NAND memory, competing on density and cost. Meanwhile, HiSilicon designs advanced SoCs for the consumer electronics space.
The China semiconductor industry encompasses the design and fabrication of integrated circuits on silicon wafers. These devices, often built using advanced FinFET technology, serve as the core processing and memory components for all modern electronics. Memory chips, including those from domestic producers, are critical for expanding data centers and AI processing workloads. The automotive end-user segment shows high demand for specialized logic chips to manage in-vehicle infotainment and driver-assistance systems.
The Ministry of Industry and Information Technology (MIIT) heavily influences market direction through strategic funding and national self-sufficiency targets. Concurrently, compliance with GB standards is mandatory for market access, ensuring product quality and interoperability. China's 'dual carbon goals' are also beginning to shape manufacturing processes toward greater energy efficiency. Future success for chipmakers will depend on navigating geopolitical trade restrictions while scaling up advanced process nodes.
Market Dynamics
The central structural force shaping the China semiconductor market is the state-directed pursuit of technological self-sufficiency. This national strategy, orchestrated by entities like the MIIT, aims to build a resilient domestic supply chain, from design to fabrication, insulated from external geopolitical pressures.
Growth Catalysts
- Automotive Electrification:The rapid transition to electric vehicles and advanced driver-assistance systems creates substantial demand for power management ICs, microcontrollers, and specialized logic chips, pulling new domestic capacity online.
- National Industrial Policy:Directives from the Ministry of Industry and Information Technology (MIIT) provide targeted funding, tax incentives, and market access preferences for domestic chip designers and manufacturers to reduce import dependency.
- Regional Manufacturing Clusters:The high concentration of consumer electronics and automotive manufacturing in the Yangtze River Delta creates a dense ecosystem of demand, talent, and supply chain partners for local semiconductor firms.
Market Restraints
- Advanced Lithography Access:Geopolitical trade controls severely restrict China's access to the extreme ultraviolet (EUV) lithography equipment required to manufacture process nodes at 7nm and below, capping domestic logic capabilities.
- EDA Tool Dependency:The domestic industry remains highly dependent on foreign-supplied electronic design automation (EDA) software, creating a critical vulnerability in the chip design phase of the value chain.
- Intellectual Property Barriers:Accessing and licensing foundational processor architectures and interface IP from foreign entities is increasingly difficult, constraining the design of globally competitive, high-performance SoCs.
Strategic Opportunities
- Compound Semiconductors:There is a significant opportunity to lead in third-generation semiconductors like Gallium Nitride (GaN) and Silicon Carbide (SiC), which are critical for high-efficiency power electronics in EVs and 5G infrastructure.
- Domestic AI Acceleration:The massive internal market for AI training and inference in data centers and edge devices presents a captive demand for developing specialized domestic AI accelerator chips and high-bandwidth memory.
- Energy Efficiency Mandates:China's 'dual carbon goals' create a policy-driven opportunity for foundries to innovate in green manufacturing processes and for designers to develop ultra-low-power chips for IoT and mobile devices.
Industry Challenges
- Specialized Talent Scarcity:A severe shortage of experienced integrated circuit engineers, process technicians, and fab managers constrains the operational ramp-up of new foundry capacity and slows advanced R&D initiatives.
- High Capital Intensity:The immense capital expenditure needed to construct and equip new wafer fabrication facilities, particularly for advanced nodes, poses a significant financial challenge even with state support.
- Compliance and Standardization:Adhering to mandatory GB standards for domestic market access while also aligning with international norms for export products creates a complex compliance burden for Chinese chipmakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Semiconductor Market |
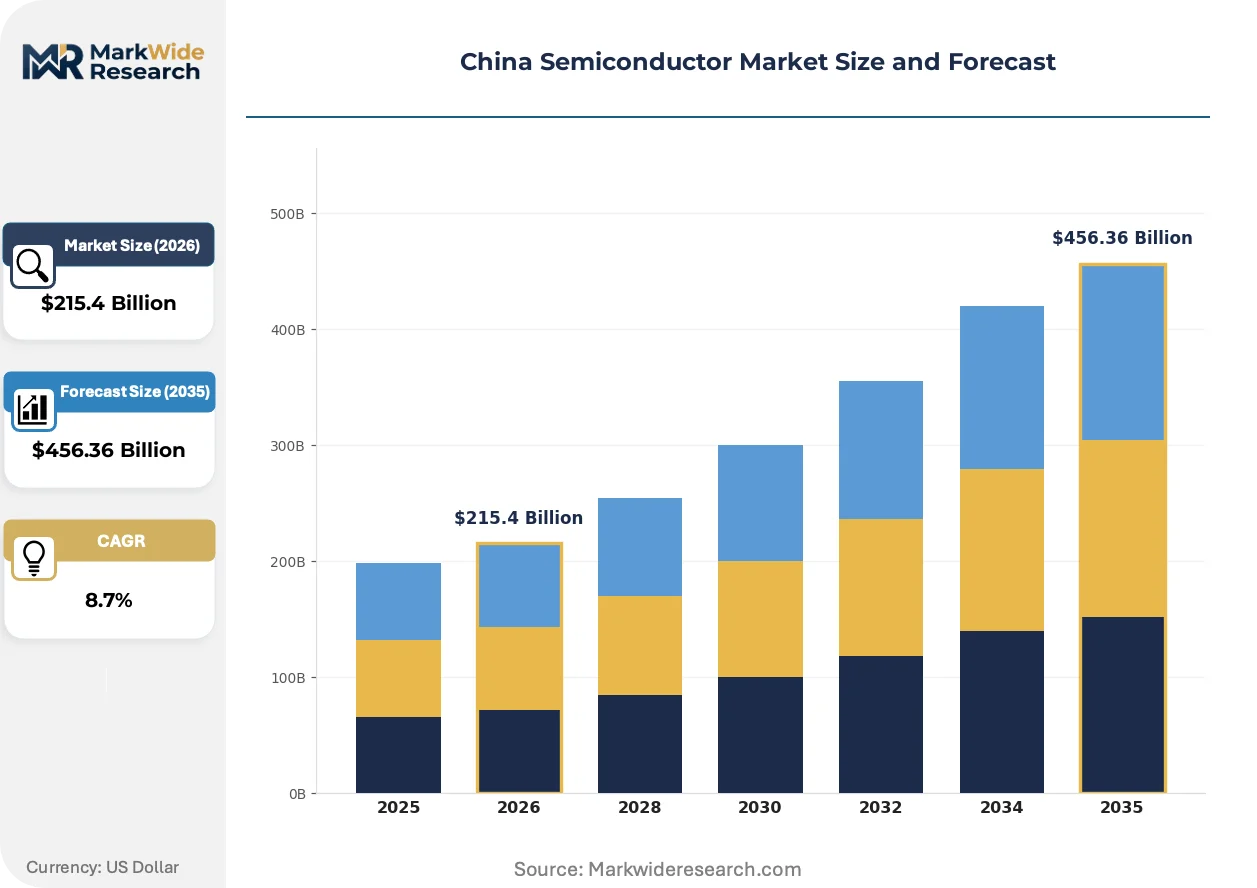
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $456.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Memory Chips, Analog Chips, Logic Chips End User: Consumer Electronics, Automotive, Industrial, Telecommunications Technology: FinFET, CMOS, BiCMOS, GaN Application: AI Processing, Data Centers, IoT Devices, Mobile Communication |
| Companies Covered | HiSilicon, NAURA Technology Group, Semiconductor Manufacturing International Corporation (SMIC), GigaDevice Semiconductor, UNISOC, Yangtze Memory Technologies Corp. (YMTC), Changxin Memory Technologies (CXMT), Montage Technology, Hua Hong Semiconductor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Semiconductor Market Strategic Shifts & Innovations
The market is defined by a dual-track strategy, simultaneously scaling up mature process nodes for industrial and automotive needs while pursuing breakthroughs in advanced packaging and new materials to circumvent leading-edge fabrication bottlenecks.
Advanced Packaging and Heterogeneous Integration
Chiplet technology enables the assembly of multiple smaller, specialized semiconductor dies into a single, highly functional package. High-performance computing and data center applications are the primary adopters of this modular design approach to overcome the physical limits of monolithic chip design. This heterogeneous integration strategy is unifying disparate process nodes and functional blocks, allowing designers to mix and match optimal technologies while improving overall system yield and performance.
MIIT's Domestic Production Mandates
The Ministry of Industry and Information Technology (MIIT) has implemented a comprehensive industrial policy aimed at accelerating domestic semiconductor production and capabilities. This national strategy directs significant state-backed funding and offers market access preferences to local foundries, design houses, and equipment suppliers. The logic and memory segments are most affected, compelling OEMs to reconfigure supply chains and prioritize domestic sourcing to align with national self-sufficiency objectives.
Application-Specific Co-Design
A notable demand-side shift is the move toward co-designing application-specific standard products (ASSPs) directly between end-users and domestic chip designers. Automotive and industrial equipment manufacturers are increasingly engaging with fabless semiconductor firms to develop custom silicon that optimizes performance and secures long-term supply. This collaborative development model is most visible within the automotive electronics sector, particularly in the Yangtze River Delta's manufacturing ecosystem.
China Semiconductor Market Segmentation
Understanding the China semiconductor market through precise segmentation reveals critical shifts in demand and technological priorities. This granular view helps stakeholders identify specific growth vectors and navigate the complex interplay between domestic innovation and national strategic objectives. Market segmentation highlights where investment is most impactful.
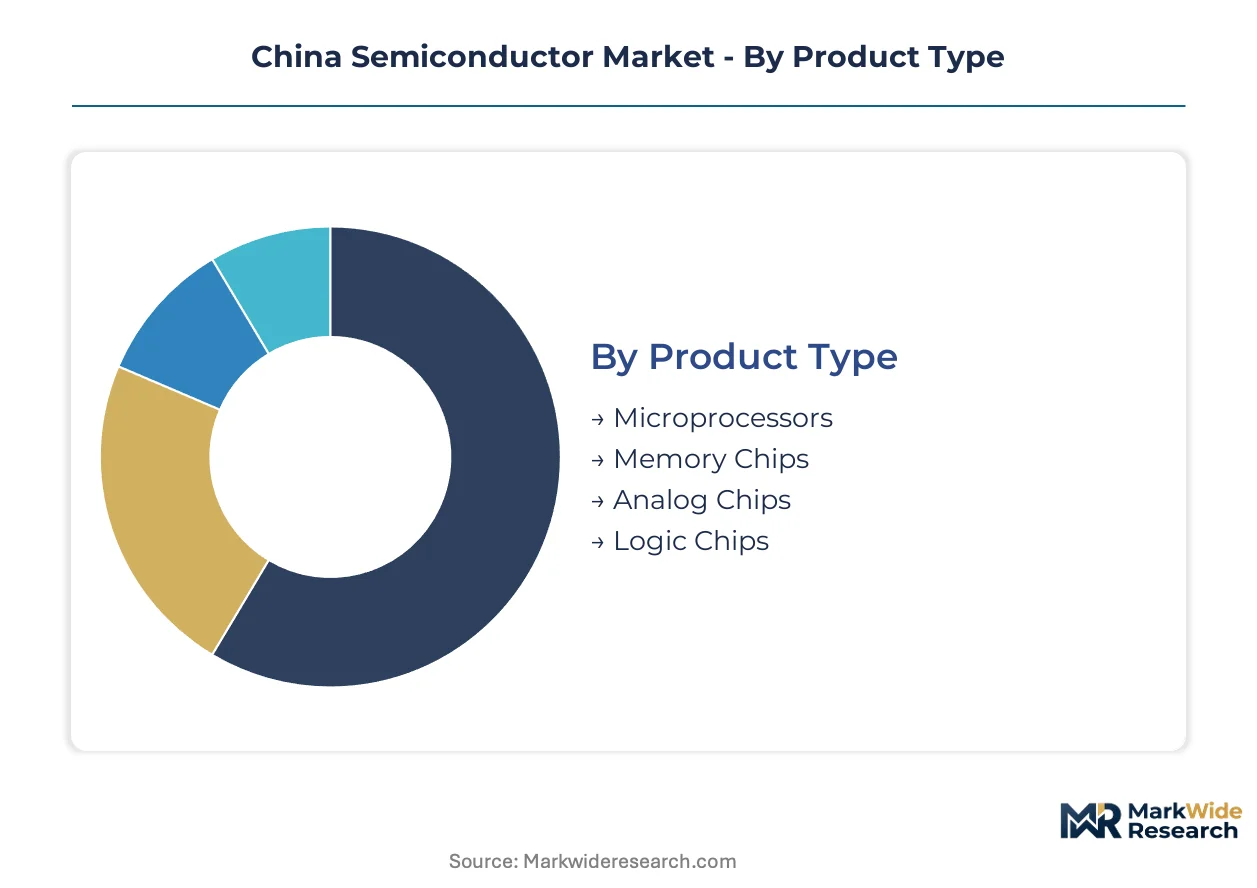
Product Type:
The upgrade cycle for semiconductor products in China is accelerating, driven by performance demands across new applications and the push for domestic alternatives. This dynamic environment influences both design and manufacturing priorities within the domestic supply chain.
- Logic Chips:These complex integrated circuits perform processing functions, serving as the digital brain for electronic devices. Demand concentrates in the Yangtze River Delta's electronics manufacturing clusters, driven by the need for advanced computation in consumer electronics and industrial automation.
- Memory Chips:Essential for data storage and retrieval, memory chips include DRAM and NAND flash technologies. Expanding data centers and AI processing workloads create substantial demand for high-bandwidth memory within China, supporting strategic digital infrastructure.
- Microprocessors:These central processing units execute instructions for general-purpose computing tasks. Domestic efforts aim to reduce reliance on foreign designs for embedded systems and personal computing platforms.
- Analog Chips:Analog integrated circuits manage real-world signals like sound, light, and temperature, converting them for digital processing. The automotive sector requires increasing volumes of precise analog components for power management and sensor interfaces.
Logic Chips sits at the top of the volume ranking, with Memory Chips climbing the fastest.
End User:
Application-specific demand shapes the China semiconductor market, with different end-user segments requiring distinct chip architectures and performance characteristics. This varied application landscape influences investment in specialized foundries and design houses.
- Automotive:This segment includes semiconductors for electric vehicles, advanced driver-assistance systems (ADAS), and in-vehicle infotainment. The rapid electrification trend in China creates substantial demand for power management ICs and microcontrollers, supporting domestic EV production targets.
- Industrial:Semiconductors in this sector power factory automation, robotics, and industrial control systems, requiring high reliability and long lifecycles. China's industrial modernization initiatives drive demand for robust embedded processors and power semiconductors.
- Consumer Electronics:This broad category encompasses chips for smartphones, smart home devices, and personal computing. Domestic design houses like HiSilicon serve this segment with advanced SoCs, aiming for self-sufficiency in high-volume devices.
- Telecommunications:Chips for 5G infrastructure, base stations, and network equipment fall into this segment. China's extensive 5G rollout and ongoing network upgrades sustain demand for high-frequency and high-performance communication ICs.
The Automotive segment commands significant strategic attention, while Industrial applications are demonstrating substantial growth potential.
Technology:
The maturity level of semiconductor manufacturing technologies varies across China's domestic industry, reflecting both foundational capabilities and strategic investments in next-generation processes. This technological spectrum guides R&D priorities and capacity expansion efforts.
- FinFET:FinFET (Fin Field-Effect Transistor) is a 3D transistor structure enabling smaller, more efficient chips at advanced process nodes (e.g., 14nm, 7nm). Domestic foundries like SMIC are actively developing FinFET capabilities to reduce reliance on foreign advanced fabrication.
- GaN:Gallium Nitride (GaN) is a wide-bandgap compound semiconductor material offering superior power efficiency and high-frequency operation. China's dual carbon goals and 5G infrastructure build-out are propelling demand for GaN power electronics in EVs and telecommunications.
- CMOS:Complementary Metal-Oxide-Semiconductor (CMOS) remains the foundational technology for most integrated circuits, known for low power consumption. It underpins a vast array of digital and analog chip designs across mature nodes.
- BiCMOS:Bipolar-CMOS (BiCMOS) technology combines the high speed of bipolar transistors with the low power of CMOS. This hybrid approach is often employed in specific analog and mixed-signal applications requiring both high current and digital control.
CMOS technology remains foundational for mass production, though GaN shows the steepest expansion trajectory for high-performance applications.
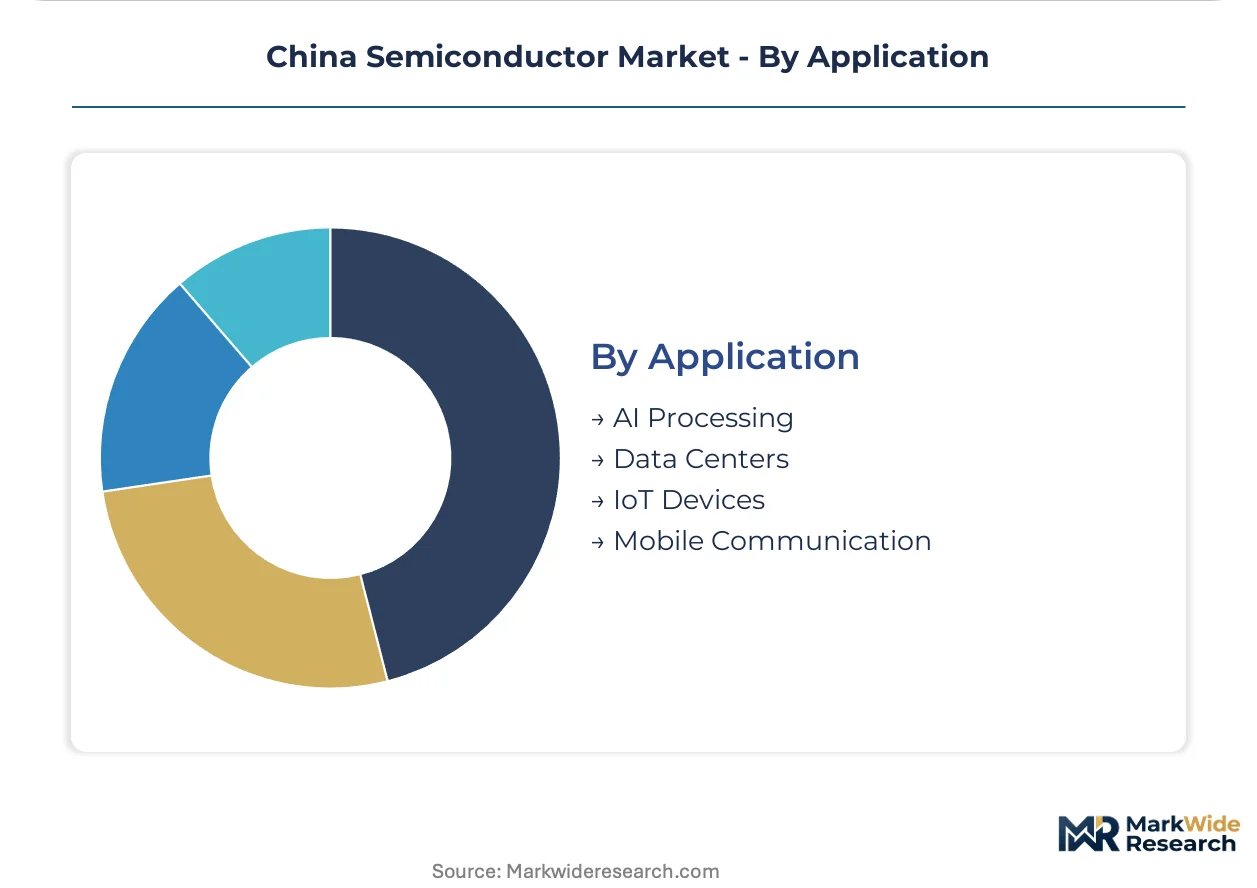
Application:
The cost structure for semiconductor applications in China is heavily influenced by the complexity and volume requirements of different end-uses. This differentiation drives specific design optimizations and manufacturing strategies to meet price-performance targets.
- AI Processing:This segment involves specialized chips designed to accelerate artificial intelligence workloads, including neural network training and inference. China's massive internal market for AI in data centers and edge devices creates captive demand for domestic AI accelerator chips.
- Data Centers:Semiconductors for data centers include high-performance CPUs, GPUs, and specialized memory, essential for cloud computing and enterprise storage. The ongoing expansion of digital infrastructure across China fuels demand for robust, high-throughput components.
- IoT Devices:Chips for the Internet of Things emphasize low power consumption, small form factors, and integrated connectivity. China's focus on smart cities and industrial IoT drives demand for energy-efficient microcontrollers and sensors.
- Mobile Communication:This application covers semiconductors for smartphones, tablets, and other portable communication devices. The domestic market requires advanced SoCs and RF components to support evolving mobile standards and user experiences.
AI Processing applications are attracting significant strategic investment, while IoT Devices are expanding rapidly across diverse sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Internal strategic objectives heavily influence the China semiconductor market, where domestic policies create unique conditions for supply chain development. This environment encourages a rebalancing of production within China's borders, driven by national self-sufficiency goals rather than external market forces. The Ministry of Industry and Information Technology (MIIT) directives guide this internal migration.
Yangtze River Delta
Demand for advanced computation in consumer electronics and industrial automation drives significant semiconductor activity here. MIIT policies strongly promote domestic production and technological independence within this region. Manufacturing clusters in Shanghai, Suzhou, and Nanjing benefit from targeted funding and infrastructure support.
Pearl River Delta
Consumer electronics and telecommunications infrastructure create substantial demand for integrated circuits in this area. Compliance with GB standards is mandatory for market access, ensuring product quality and interoperability. Shenzhen and Guangzhou anchor a dense ecosystem of design houses and manufacturing facilities.
Beijing-Tianjin-Hebei
AI processing workloads and expanding data centers generate a captive demand for specialized chips in this northern cluster. China's dual carbon goals are beginning to shape manufacturing processes toward greater energy efficiency. Beijing and Tianjin serve as key hubs for AI research and development, attracting significant investment.
Sichuan-Chongqing
Automotive electronics and industrial modernization initiatives are fueling semiconductor demand across this southwestern region. Local government incentives actively support high-tech manufacturing and talent development. Chengdu and Chongqing are emerging as critical centers for automotive chip design and production.
China Semiconductor Market Key Industry Players
Domestic Chinese producers anchor one tier of the market, focusing on scaling mature process nodes for industrial and automotive needs. Foreign-affiliated specialists hold positions in advanced technology areas where access remains feasible. The competitive structure is tiered, featuring state-backed foundries, specialized fabless design houses, and memory manufacturers. Capacity expansion and strategic partnerships within China represent dominant competitive moves.
Within the state-backed foundry archetype, Semiconductor Manufacturing International Corporation (SMIC) anchors the country's logic chip manufacturing capabilities. Yangtze Memory Technologies Corp. (YMTC) represents the memory specialist tier, competing on density and cost for NAND memory products. HiSilicon, a prominent fabless design house, exemplifies the domestic design strength for advanced SoCs in consumer electronics.
| Leading Market Players |
|---|
| HiSilicon |
| NAURA Technology Group |
| Semiconductor Manufacturing International Corporation (SMIC) |
| GigaDevice Semiconductor |
| UNISOC |
| Yangtze Memory Technologies Corp. (YMTC) |
| Changxin Memory Technologies (CXMT) |
| Montage Technology |
| Hua Hong Semiconductor |
| Others |
Cost & Logistics Intelligence
Mandated domestic sourcing, driven by MIIT policies, reshapes the China semiconductor supply chain, increasing internal competition and influencing pricing power for locally produced components.
Pricing Analysis
Direct-to-OEM discount structures dominate pricing for high-volume semiconductor components in China. Pricing stratifies across performance tiers, with advanced logic chips commanding premiums based on process node and IP integration. Price differentiation drivers include compliance with mandatory GB standards and the level of customization for specific end-user applications. Pricing softness reflects intense domestic competition in mature process nodes and the ongoing push for self-sufficiency. Consumer electronics manufacturers demonstrate the highest price sensitivity, while automotive OEMs prioritize long-term supply stability and quality over immediate cost savings.
Supply Chain Analysis
Compliance with mandatory GB standards serves as a critical gating factor for market access, influencing supply chain configuration. Semiconductor supply for China draws from domestic foundries like SMIC and YMTC, alongside foreign suppliers from Taiwan and South Korea for advanced nodes. Raw material dependencies include specialized process chemicals and critical manufacturing equipment, such as advanced lithography tools. Geopolitical trade restrictions introduce a structural risk, limiting access to leading-edge fabrication technology. Distribution for many high-volume integrated circuits runs through direct channels to major domestic OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's semiconductor market functions as a regulatory compounder, with MIIT's national self-sufficiency targets driving sustained investment and demand across the domestic value chain.
For Market Incumbents: Deepen R&D investments in advanced packaging and heterogeneous integration techniques to circumvent leading-edge fabrication bottlenecks. Expand capacity in mature process nodes, particularly for power management ICs and microcontrollers, to meet robust automotive demand. Geopolitical trade restrictions represent a named threat requiring a focus on domestic tool and material sourcing. Invest in specialized talent development programs to mitigate the severe scarcity of experienced engineers.
For New Entrants and Emerging Players: Online design platforms and co-design partnerships offer a viable go-to-market angle for specialized silicon. Target white-space opportunities in compound semiconductors like GaN and SiC, which are critical for high-efficiency power electronics in EVs. The industrial automation segment presents the most penetrable application area for robust embedded processors and power semiconductors. Focus on developing specialized AI accelerator chips for edge devices, leveraging the massive internal market demand.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic fabless design houses specializing in application-specific standard products (ASSPs) for high-growth segments. The long-term viability of this market is anchored by sustained state backing and its role in critical national digital infrastructure. Acquisition targets should prioritize firms with strong intellectual property in advanced packaging or unique materials science capabilities. A shift in MIIT funding allocation towards specific technology areas serves as a key signal to watch for inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mature Nodes | Increases domestic supply resilience for industrial and automotive applications, reducing import dependency. |
| Green Manufacturing Transition | Aligns with China's dual carbon goals, improving energy efficiency across fabrication facilities. |
| Strategic Partnership with Domestic OEMs | Secures long-term demand and co-development opportunities for application-specific chips. |
| Acquisition of Advanced Packaging Specialists | Enhances capabilities to overcome leading-edge fabrication constraints via heterogeneous integration. |
| Product Launch: Specialized AI Accelerators | Captures internal demand for AI processing in data centers and edge devices, supporting national AI strategy. |
Research Approach
Multiple input streams — primary interviews, government policy documents, and company financial reports — were reconciled to construct a comprehensive view of the China semiconductor market. This involved combining insights from fab managers, design engineers, MIIT policy advisors, and automotive OEM procurement leads. Secondary validation utilized trade association publications, academic research papers, and relevant industry databases. A rigorous process of bottom-up data aggregation and top-down market sizing ensured accuracy.
The data-stream reconciliation informed an analytical framework that modeled market dynamics across the analysis window. Segmentation dimensions modeled included product type, end-user segment, technology node, application, and regional manufacturing cluster. Compound annual growth rates were derived from historical trends and projected market dynamics, factoring in key inputs such as electric vehicle production targets and MIIT investment directives. This approach provided robust quantitative projections.
The model assumes a particular technology adoption path; alternative pathways for advanced lithography access would alter the outlook. Forecasts reflect assumptions regarding the continued implementation of national industrial policies and the pace of domestic technological advancement. A model refresh is warranted upon material change in geopolitical trade restrictions or domestic talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Germanium Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Gaas Wafer Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Smartphone Battery Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
North America Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market