
 North America Battery Manufacturing Equipment Market | 2026-2036
North America Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Battery Manufacturing Equipment Market Analytics
Automotive OEM buyer concentration is expanding as Ford, General Motors, and Tesla scale in-house cell production across Michigan, Tennessee, and Texas corridors. Applied Materials leverages its thin-film deposition expertise to anchor electrode coating equipment supply. AM Batteries competes through dry-electrode processing technology that eliminates solvent-based manufacturing steps. Anovion positions its synthetic graphite anode materials to sustain North American cathode-active material supply chains.
Battery manufacturing equipment encompasses the specialized machinery, automation systems, and process control technologies used to fabricate electrochemical cells from raw materials through formation cycling, with typical line throughput measured in cells per minute and coating precision tolerances below two micrometers. This equipment enables mass production of lithium-ion and emerging solid-state batteries for electric vehicles, grid storage, and consumer electronics applications. Assembly Machines dominate capital expenditure budgets due to the complexity of stacking, winding, and tab welding operations that determine cell performance consistency. Solid-State technology represents the fastest-growing equipment category as manufacturers retool for sulfide and oxide electrolyte handling requirements. Testing Equipment commands premium pricing because formation cycling and aging protocols account for substantial floor space and energy consumption in gigafactory layouts.
The US Inflation Reduction Act, EPA industrial emissions standards, and OSHA machine safety regulations collectively shape equipment procurement by mandating domestic content thresholds, clean energy compliance, and worker protection protocols that increase automation intensity. NHTSA battery safety standards and DOE manufacturing grants further direct R&D investment toward next-generation formation and inspection systems. Stakeholders must monitor how IRA credit phase-out schedules interact with state-level permitting timelines to calibrate capacity expansion decisions.
Market Dynamics
Automotive OEM captive cell production is compressing equipment procurement cycles across Michigan, Tennessee, and Texas factory corridors, forcing suppliers to align R&D roadmaps with IRA domestic content phase-in schedules rather than traditional automotive development timelines.
Growth Catalysts
- US Inflation Reduction Act:Domestic content thresholds redirect capital flows toward electrode coating and formation equipment manufactured within qualifying North American supply chains.
- Solid-state electrolyte handling:Sulfide and oxide electrolyte processing requirements create demand for new dry-room infrastructure and inert atmosphere systems.
- Tesla, Ford, and General Motors:Vertical integration strategies across Texas, Michigan, and Tennessee corridors concentrate multi-billion-dollar equipment orders with preferred suppliers.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress cell manufacturer margins and delay equipment purchase commitments.
- Asian electrode coating equipment:Supply concentration in South Korea and Japan creates delivery bottlenecks for North American gigafactory ramp schedules.
- OSHA machine safety compliance:Worker protection protocol upgrades extend equipment commissioning timelines and inflate automation integration costs.
Strategic Opportunities
- Mexico border manufacturing zones:Nearshoring incentives under USMCA provisions enable tariff-advantaged equipment component sourcing for Texas and Arizona factory clusters.
- Grid-scale stationary storage:Utility procurement mandates in California and Texas expand addressable demand beyond automotive cell production.
- Dry-electrode processing:Solvent elimination technologies converge with EPA industrial emissions standards to create first-mover advantages for equipment retrofit markets.
Industry Challenges
- Electrochemical engineering talent:Shortages of formation cycling specialists and coating process engineers constrain gigafactory staffing at Michigan and Tennessee greenfield sites.
- NHTSA battery safety certification:Extended validation protocols for thermal runaway containment systems delay production line qualification.
- Legacy automotive equipment integration:Mismatch between traditional stamping plant automation architectures and lithium-ion cell manufacturing data requirements creates retrofit complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Battery Manufacturing Equipment Market |
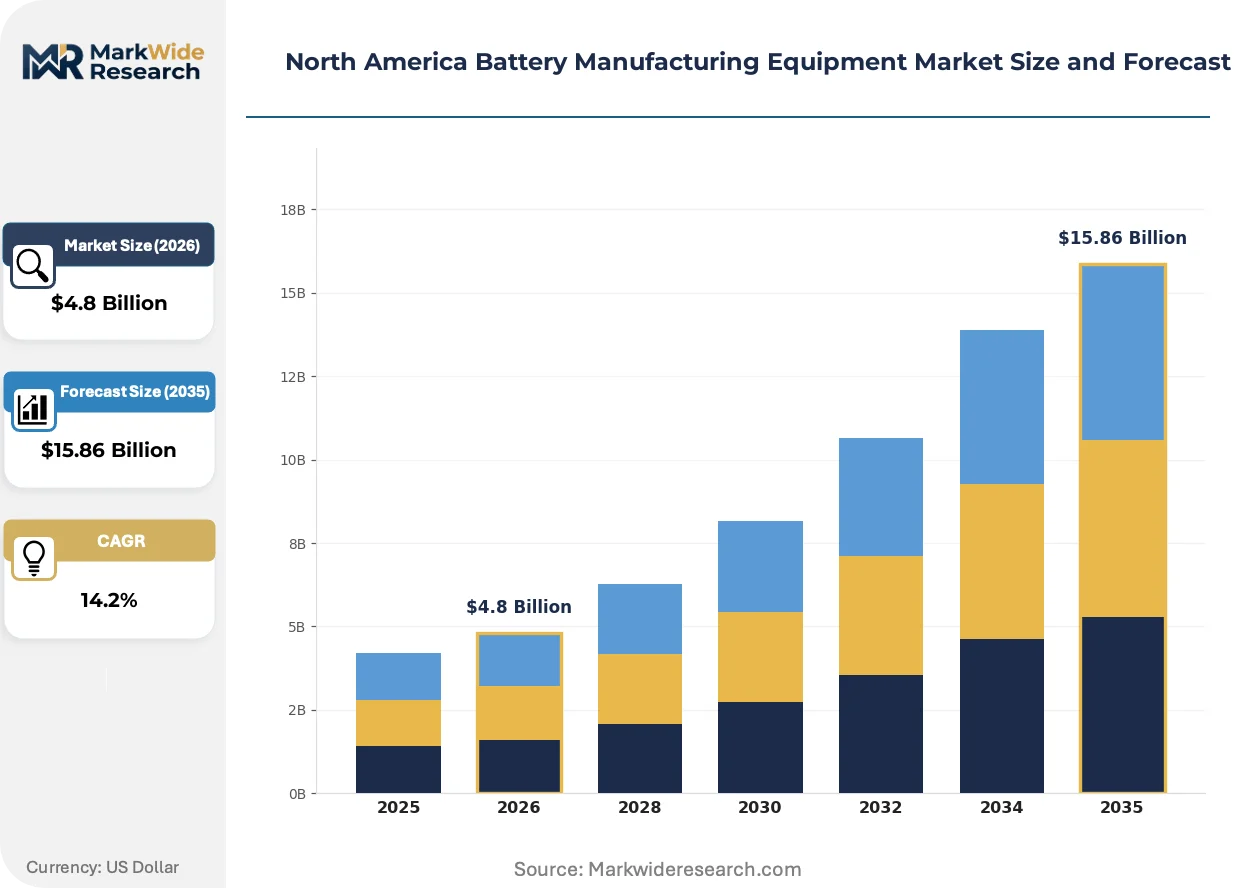
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Machines, Testing Equipment, Material Handling, Battery Management Systems End User: Automotive Manufacturers, Consumer Electronics, Renewable Energy, Industrial Applications Technology: Lithium-Ion, Nickel-Cadmium, Solid-State, Lead-Acid Installation Type: On-site, Off-site, Modular, Custom-built |
| Companies Covered | Applied Materials, AM Batteries, Intecells, Mac Engineering & Equipment, BM-Rosendahl, Anaphite, Anovion, NEI Corporation, Mitsubishi Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Battery Manufacturing Equipment Market Evolving Landscape
Equipment architecture is pivoting toward modular, reconfigurable production lines that accommodate chemistry transitions without full line replacement, reflecting uncertainty around solid-state commercialization timing.
Dry-electrode calendaring is converging with roll-to-roll manufacturing architectures to eliminate solvent recovery systems and reduce factory footprint requirements. Automotive OEMs in Michigan and Tennessee are piloting these systems at 10 MWh annual throughput scales. The structural consequence is compressing electrode production CAPEX by removing drying ovens and NMP solvent handling infrastructure from greenfield designs.
The US Inflation Reduction Act's domestic content bonus credits are mandating North American sourcing thresholds for electrode active materials and separator films. Equipment vendors must certify that coating and winding machinery contains sufficient US-manufactured steel and control systems to qualify cell producers for tax credits. Formation and aging equipment categories face the steepest compliance redesigns due to embedded semiconductor content from Asian suppliers.
Automotive OEM procurement teams are consolidating equipment contracts under single-source framework agreements with multiyear service commitments, displacing the previous project-by-project bidding model. Tier 1 cell manufacturers in Texas and Tennessee corridors now bundle electrode coating, assembly, and formation equipment under unified performance guarantees. This concentration is most visible in Ford's BlueOval SK joint venture, where equipment vendors assume uptime risk across entire production modules.
North America Battery Manufacturing Equipment Market Segmentation
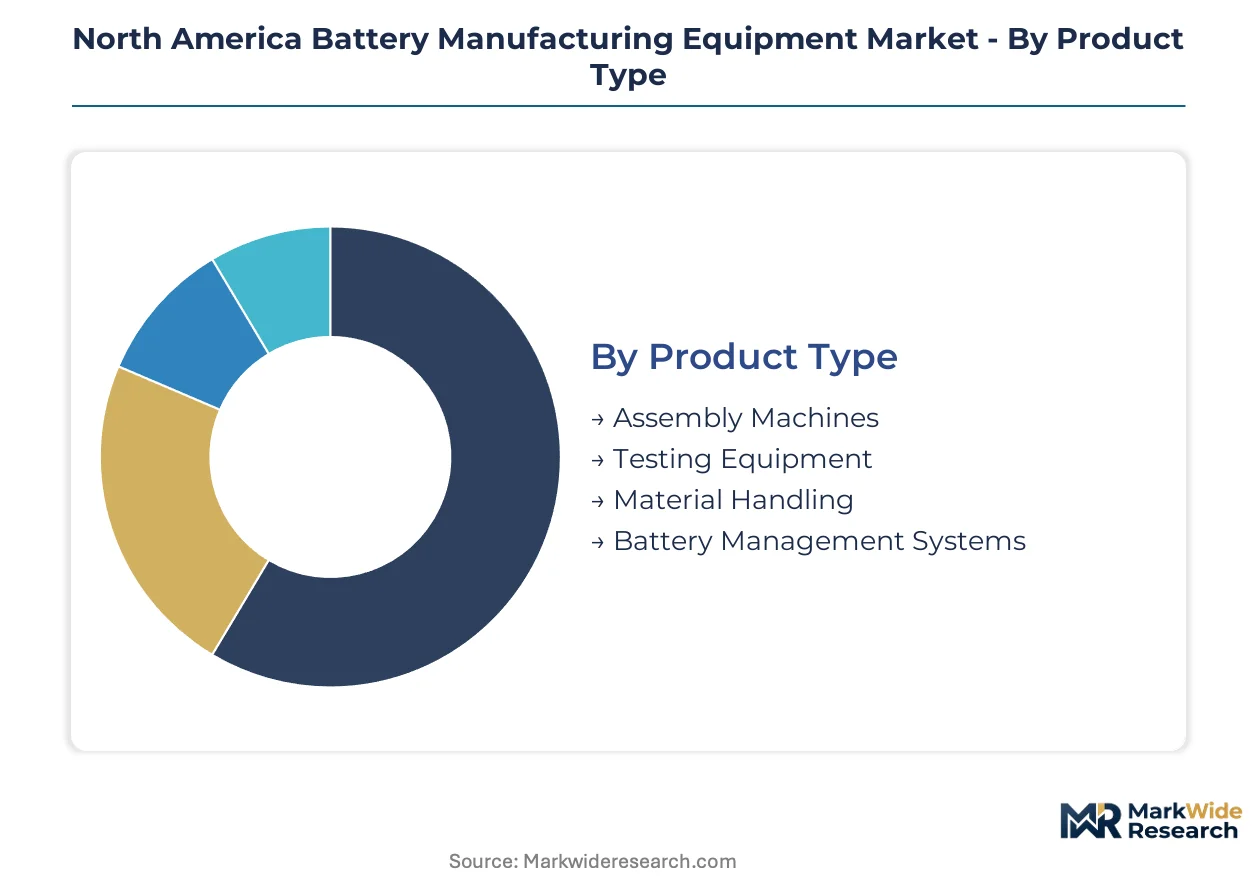
Equipment procurement patterns diverge sharply across chemistry platforms and factory configurations. Each segmentation axis reveals distinct capital allocation priorities that reshape supplier competitive positioning.
Product Type:
Precision and throughput specifications define equipment category economics, with coating tolerances and cycle times determining factory layout decisions.
- Assembly Machines:Stacking, winding, and tab welding systems operate at sub-micrometer precision thresholds. Ford's BlueOval SK joint venture in Tennessee and Tesla's Texas gigafactory concentrate multi-line orders with uptime-guarantee contracts.
- Testing Equipment:Formation cycling and aging protocols consume substantial floor space and energy loads. IRA domestic content requirements are forcing semiconductor supply chain redesigns for control systems.
- Material Handling:Dry-room conveyor and robotic transfer systems maintain electrolyte contamination thresholds.
- Battery Management Systems:Formation data analytics and predictive maintenance modules integrate with MES platforms.
Assembly Machines lead on scale; Testing Equipment leads on momentum.
End User:
Customer capital cycles and qualification timelines create divergent procurement rhythms across application sectors.
- Automotive Manufacturers:Ford, General Motors, and Tesla captive cell production compresses equipment delivery schedules. Michigan and Tennessee factory corridors account for concentrated order flows under framework agreements.
- Consumer Electronics:Smartphone and laptop cell producers prioritize compact line footprints and rapid chemistry切换 capability.
- Renewable Energy:Utility-scale storage procurement mandates in California and Texas expand formation equipment demand beyond automotive specifications.
- Industrial Applications:Forklift and stationary power systems require modified thermal management protocols.
Automotive Manufacturers dominate capital deployment; Renewable Energy climbs fastest.
Technology:
Chemistry platform selection dictates dry-room infrastructure, atmosphere control, and handling equipment requirements.
- Lithium-Ion:NMC and LFP electrode coating systems anchor current equipment revenue. Roll-to-roll architectures with solvent recovery dominate Michigan and Tennessee greenfield designs.
- Solid-State:Sulfide and oxide electrolyte processing demands inert atmosphere systems and moisture-free handling. Equipment vendors are retooling for unproven commercialization timelines.
- Nickel-Cadmium:Legacy industrial battery production maintains specialized formation equipment.
- Lead-Aid:Mature grid storage and automotive starter battery lines require distinct paste mixing and formation infrastructure.
Lithium-Ion commands installed base; Solid-State shows steepest expansion trajectory.
Installation Type:
Factory deployment models reflect capital risk allocation between OEMs and equipment vendors.
- On-site:Permanent installation with embedded utility infrastructure dominates gigafactory layouts in Texas and Tennessee corridors.
- Off-site:Pre-commissioned module fabrication accelerates ramp schedules for greenfield sites facing permitting delays.
- Modular:Reconfigurable line segments accommodate chemistry transitions without full replacement. Equipment architecture pivots toward this flexibility given solid-state uncertainty.
- Custom-built:Purpose-designed systems for novel cell formats or proprietary stacking methods.
On-site retains volume concentration; Modular gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical engineering talent concentrates in Michigan, Tennessee, and Texas factory corridors where automotive OEMs are scaling captive cell production. Equipment procurement cycles compress as IRA domestic content phase-in schedules override traditional automotive development timelines.
United States
Ford, General Motors, and Tesla drive equipment demand through vertical integration strategies across Michigan, Tennessee, and Texas. The US Inflation Reduction Act mandates domestic content thresholds for electrode coating and formation machinery. Detroit and Nashville metro areas anchor concentrated gigafactory construction with multi-billion-dollar equipment orders.
Canada
Critical mineral processing and precursor material refining expand equipment demand in Ontario and Quebec mining corridors. Health Canada and Environment and Climate Change Canada administer industrial emissions standards affecting dry-room infrastructure specifications. The Greater Toronto Area attracts electrode material equipment suppliers serving cross-border automotive supply chains.
Mexico
Nearshoring incentives under USMCA provisions enable tariff-advantaged equipment component sourcing for Texas and Arizona factory clusters. The Secretariat of Economy coordinates manufacturing investment promotion with USMCA compliance frameworks. Nuevo León and Baja California border zones concentrate maquiladora operations supplying precision machining for coating and winding systems.
North America Battery Manufacturing Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across electrode coating, assembly, and formation equipment categories. The vendor base organizes around three strategic archetypes: thin-film deposition specialists leveraging semiconductor heritage, dry-electrode processing innovators eliminating solvent steps, and materials-science players anchoring anode and cathode supply chains. Dominant competitive moves include framework agreements with uptime guarantees and modular line architectures accommodating chemistry transitions.
Within the deposition-specialist tier, Applied Materials exemplifies equipment vendors transitioning semiconductor expertise into battery electrode manufacturing. AM Batteries occupies a position among dry-electrode innovators targeting solvent-elimination retrofits. Anovion anchors the materials-integrated archetype, representing suppliers positioning synthetic graphite anode materials to sustain North American cathode-active material supply chains.
| Leading Market Players |
|---|
| Applied Materials |
| AM Batteries |
| Intecells |
| Mac Engineering & Equipment |
| BM-Rosendahl |
| Anaphite |
| Anovion |
| NEI Corporation |
| Mitsubishi Chemical Group |
| Others |
Value Network & Pricing Analysis
Equipment tier divergence between IRA-compliant domestic machinery and imported Asian systems manifests in both capital expenditure premiums and supply chain qualification complexity. Formation equipment with North American-sourced semiconductors commands substantial price premiums over Korean and Japanese alternatives, while electrode coating systems face extended lead times due to control system certification requirements.
Pricing Analysis
Capacity additions in Tennessee and Texas are reshaping price floors for assembly and formation equipment as Ford, General Motors, and Tesla consolidate procurement under framework agreements with uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in standard-tier electrode coating systems is intensifying because Asian suppliers are absorbing tariff exposure to maintain market access. Automotive OEMs show lowest price sensitivity due to IRA credit eligibility requirements, while independent cell manufacturers face acute margin pressure from raw material volatility.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for electrode coating and formation equipment, displacing traditional distributor networks in Michigan and Tennessee corridors. Semiconductor control systems draw from South Korea, Japan, and Taiwan, while precision steel components source from Germany and domestic US mills. Single-source vulnerability concentrates in advanced deposition equipment where Applied Materials and select Asian vendors dominate technical specifications. Distribution runs through equipment vendors with embedded service teams rather than third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America battery manufacturing equipment market functions as a geographic-arbitrage play where Mexico border zones under USMCA provisions offer 15-25% landed cost advantages versus direct Asian imports for Texas and Arizona factory clusters.
For Market Incumbents: Acquire dry-electrode processing capabilities to defend against solvent-elimination retrofits that AM Batteries is commercializing. Secure captive semiconductor supply chains through partnerships with Texas Instruments or Analog Devices to satisfy IRA domestic content thresholds. Lock in multi-year service contracts with Ford and General Motors to create switching costs before solid-state equipment refresh cycles begin. For New Entrants and Emerging Players: The US Inflation Reduction Act in the United States opens a window for equipment vendors offering modular, chemistry-flexible production lines that accommodate uncertain solid-state commercialization timing. Target grid-scale stationary storage applications in California and Texas where utility procurement mandates expand addressable demand beyond automotive specifications. Lead with EPA emissions compliance guarantees to differentiate from incumbent solvent-based system providers. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play dry-electrode equipment specialists and Mexico-based precision machining operations serving USMCA-compliant supply chains. Five-to-ten-year viability hinges on successful navigation of solid-state electrolyte handling transitions and IRA credit phase-out schedules. Monitor NHTSA battery safety certification timelines as the critical inflection signal for formation equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | IRA domestic content requirements force control system supply chain redesigns for electrode coating equipment. |
| Modular Production Line Architecture | Reconfigurable segments accommodate chemistry transitions without full line replacement amid solid-state uncertainty. |
| Mexico Border Zone Manufacturing Footprint | USMCA provisions enable tariff-advantaged component sourcing for Texas and Arizona gigafactory clusters. |
| Dry-Electrode Processing Technology Licensing | Solvent elimination converges with EPA emissions standards to create retrofit market first-mover advantages. |
| Framework Agreement Consolidation | Single-source contracts with uptime guarantees displace project-by-project bidding at Ford and General Motors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to calibrate equipment demand forecasts against actual gigafactory construction timelines. Primary discussions with electrode coating process engineers, formation equipment procurement leads at automotive OEMs, dry-room infrastructure specialists, and IRA compliance officers at cell manufacturers were cross-referenced with secondary validation from SEC equipment vendor filings, DOE manufacturing grant disclosures, USMCA customs data, and NHTSA battery safety dockets. Bottom-up line-by-line capacity builds were triangulated against top-down automotive electrification penetration assumptions.
Historical reference periods anchored the projection horizon to pre-IRA and post-IRA implementation phases, enabling isolation of policy-driven demand inflections. The analytical framework modeled segmentation across equipment type, end-user sector, battery chemistry platform, and installation configuration, with additional dimensioning by domestic content qualification tier. CAGRs were derived from equipment vendor order backlogs, gigafactory permitting timelines, and automotive OEM electrification commitments. Forecast inputs incorporated IRA credit phase-out schedules, solid-state commercialization probability assessments, and electrochemical engineering labor availability constraints.
Revisions become necessary when NHTSA battery safety certification protocols extend beyond baseline assumptions, when lithium carbonate price volatility compresses cell manufacturer capital commitments, or when Asian electrode coating equipment delivery bottlenecks intensify. Forecasts reflect documented assumptions regarding IRA domestic content threshold enforcement and solid-state electrolyte handling equipment readiness. Periodic stress-testing of base assumptions against actual gigafactory ramp schedules and equipment commissioning timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Vacuum Chambers Market