
 Europe Automotive Semiconductor Market | 2026-2036
Europe Automotive Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Semiconductor Market Insights
Modular system-on-chip bundling is realigning how Tier-1 suppliers select semiconductor partners across European vehicle programs. Infineon Technologies leverages captive fab capacity in Dresden to sustain power-device supply commitments to Volkswagen Group and BMW. NXP Semiconductors anchors its position through domain-architecture specialization in gateway and zonal controllers. STMicroelectronics competes aggressively on silicon-carbide MOSFETs for traction inverters, differentiating against incumbent IGBT portfolios.
Europe automotive semiconductors comprise integrated circuits and discrete devices engineered to operate across temperature ranges from minus 40°C to 150°C, fabricated on 90-nanometer to 40-nanometer process nodes for reliability in engine-bay and chassis locations. Their primary purpose is to execute real-time control, sensing, and power-conversion functions that enable electronic subsystems in modern vehicles. Power ICs for electrified drivetrains command the dominant margin pool as OEMs shift voltage architectures toward 800-volt platforms. Mixed-signal technology bridges the gap between analog sensor inputs and digital processing cores, occupying a structurally critical tier where few European suppliers maintain full in-house capability. Sensor ICs for battery-management systems represent the fastest-growing product category as cell-monitoring precision becomes a competitive differentiator in electric-vehicle range claims.
EU Green Deal benchmarks enforced by the European Commission are mandating fleet-average CO2 reductions that directly translate into higher semiconductor content per vehicle for powertrain electrification. ECE R10 electromagnetic-compatibility regulations shape product-design requirements for all automotive electronics sold within the European Economic Area. REACH chemical-substance restrictions constrain material choices in semiconductor packaging and substrate metallization. Stakeholders must monitor how the EU AI Act's risk-classification framework applies to autonomous-vehicle perception chips, as compliance timelines will determine which suppliers retain design-win access to European OEM roadmaps.
Market Dynamics
The shift from distributed electronic control units to centralized domain architectures is compressing supplier tiers and redistributing margin pools across the European automotive semiconductor value chain. This consolidation dynamic favors chipmakers with captive manufacturing and software-integrated hardware portfolios.
Growth Catalysts
- EU Green Deal fleet-emission mandates:Binding CO2 reduction targets force powertrain electrification, multiplying semiconductor content per vehicle for traction inverters and battery management systems.
- 800-volt platform proliferation:Premium OEM drivetrain roadmaps specify silicon-carbide power devices that outperform silicon IGBTs in efficiency and thermal performance.
- Germany's automotive corridor concentration:Stuttgart-to-Munich procurement clusters create dense design-win ecosystems where Tier-1 suppliers co-locate application engineering teams.
Market Restraints
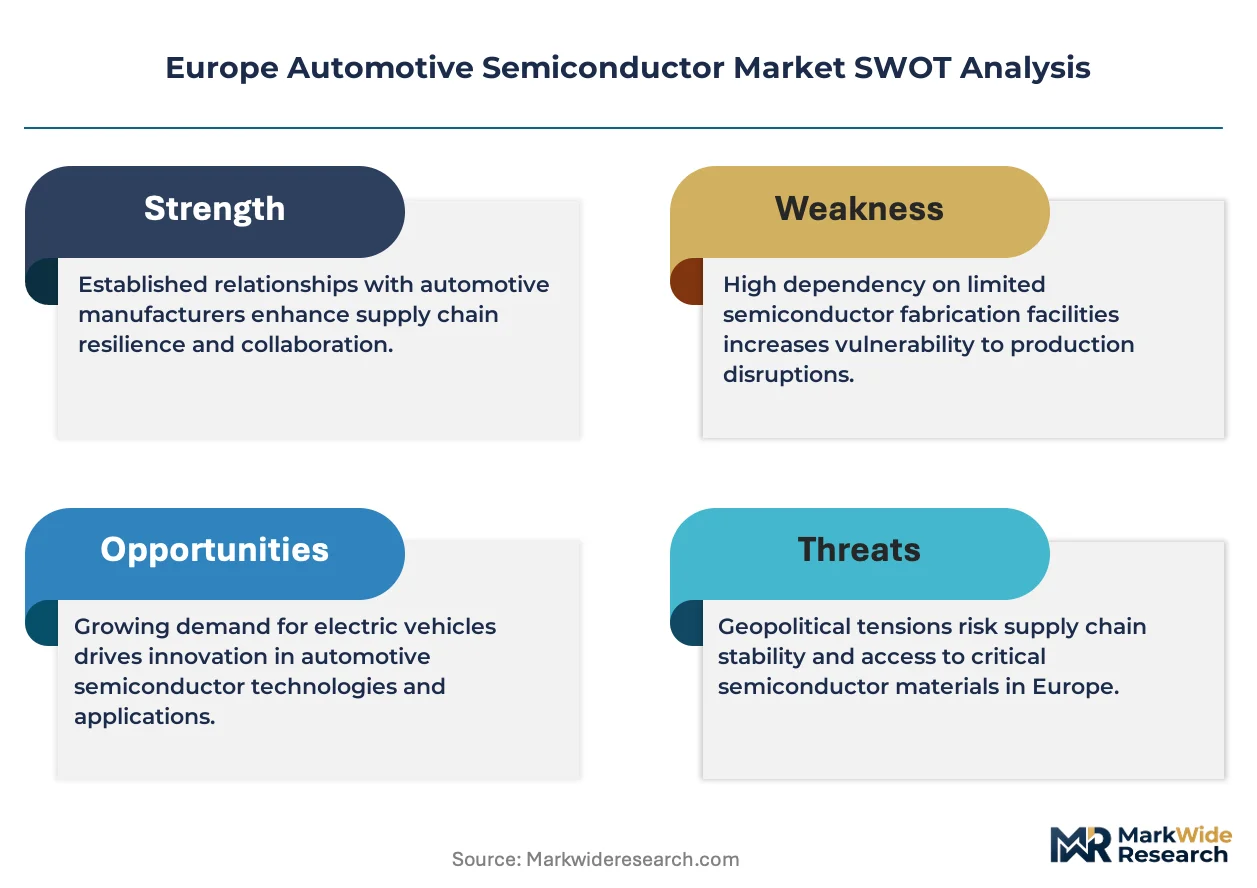
- 300mm wafer fabrication scarcity:European automotive-qualified foundry capacity concentrates at Infineon's Dresden campus and STMicroelectronics' Crolles facility, creating single-source exposure.
- Neon and palladium supply concentration:Semiconductor lithography gases and substrate metallization materials depend on Ukrainian and Russian supply corridors subject to geopolitical disruption.
- Functional safety certification bottlenecks:ISO 26262 ASIL-D qualification timelines for new process nodes extend 18-24 months, freezing out fabless entrants without existing automotive track records.
Strategic Opportunities
- Eastern European manufacturing expansion:Hungary and Romania offer cost-competitive backend assembly and test capacity within EU regulatory jurisdiction.
- EU AI Act autonomous-vehicle provisions:Risk-classification frameworks for perception chips create compliance-based moats for early-mover suppliers with established safety documentation.
- Zonal controller consolidation:Gateway-to-zone architecture transitions enable mixed-signal specialists to capture socket share previously fragmented across multiple discrete devices.
Industry Challenges
- Automotive-grade analog design expertise scarcity:Mixed-signal engineering talent pools have atrophied as consumer electronics absorbed university graduates, forcing chipmakers to poach from each other or retrain internally.
- Legacy vehicle platform coexistence:12-volt electrical architectures persist in mass-market segments, forcing dual-voltage semiconductor portfolio maintenance that fragments R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Semiconductor Market |
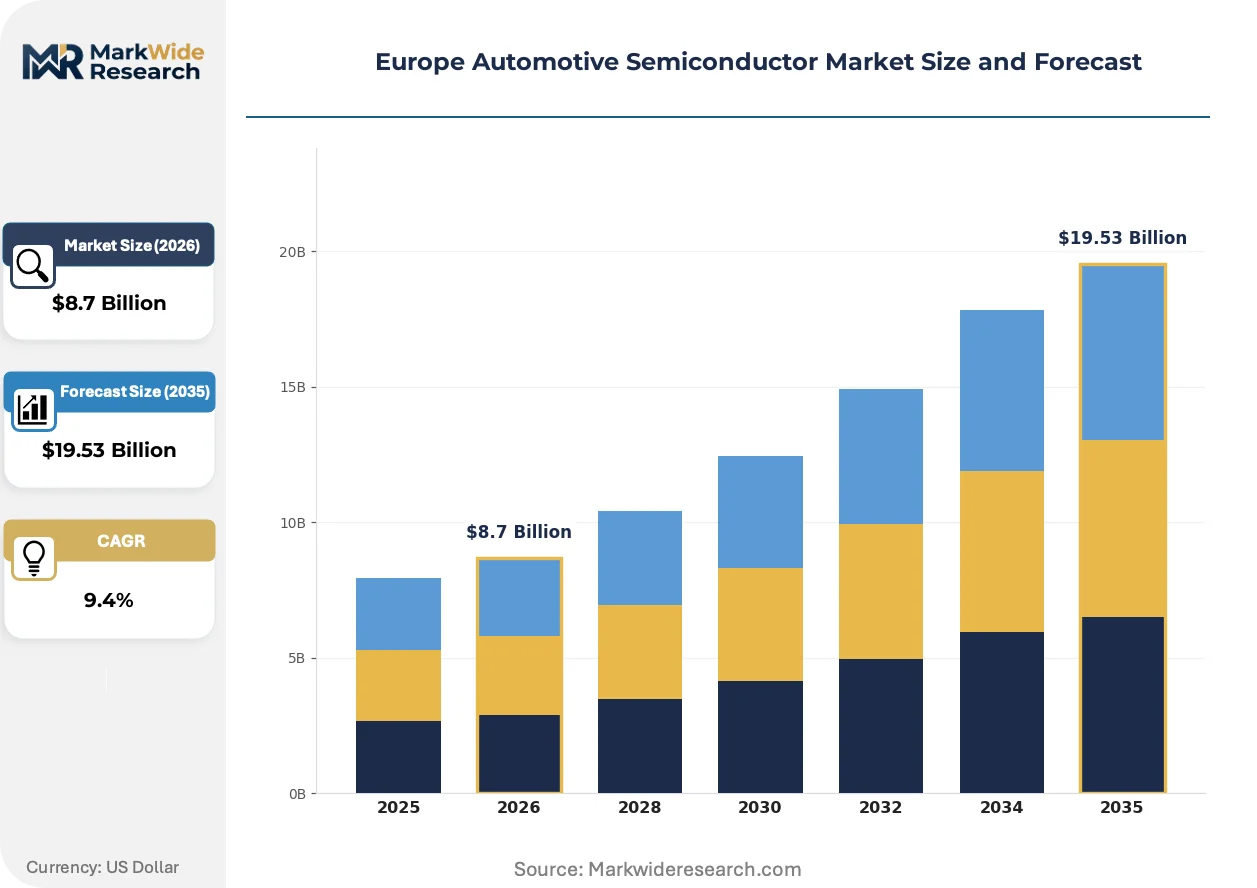
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Power ICs, Sensor ICs, Application Processors Technology: Analog, Digital, Mixed-Signal, Embedded Systems End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles Application: Infotainment, Powertrain, Safety Systems, Body Electronics |
| Companies Covered | NXP Semiconductors, Infineon Technologies, STMicroelectronics, Robert Bosch, Texas Instruments, Renesas Electronics, ON Semiconductor, Analog Devices, ROHM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Semiconductor Market Trends and Innovations
Silicon-carbide power semiconductors and domain-centralized computing architectures are converging to redefine thermal management, packaging density, and software-hardware integration requirements across European vehicle programs.
Silicon-carbide MOSFET technology is integrating into traction inverters and onboard chargers as OEMs specify 800-volt electrical architectures for premium electric vehicles. Volkswagen Group and BMW procurement teams now mandate silicon-carbide for high-performance drivetrain variants, compressing the timeline for silicon IGBT phase-out in applications above 400 volts. This transition is integrating thermal management and power semiconductor design into unified engineering workflows that were previously siloed.
EU AI Act risk-classification frameworks are mandating documentation and audit trails for autonomous-vehicle perception chips before market authorization. The European Commission's enforcement timeline pressures chipmakers to establish safety-case methodologies that satisfy both automotive functional-safety and AI-specific transparency requirements. Perception semiconductor suppliers face the steepest compliance burden as their products fall under high-risk system classifications with mandatory third-party conformity assessment.
Automotive procurement teams are consolidating semiconductor supplier rosters from fifteen-plus vendors to six-to-eight strategic partners per vehicle program. Tier-1 suppliers including Bosch, Continental, and ZF Group now demand multi-year volume commitments and joint roadmap planning in exchange for design-win access. This concentration is most visible in Germany's automotive corridor, where procurement chiefs at Volkswagen Group, BMW, and Mercedes-Benz coordinate qualification timelines to synchronize model-year launches.
Europe Automotive Semiconductor Market Segmentation
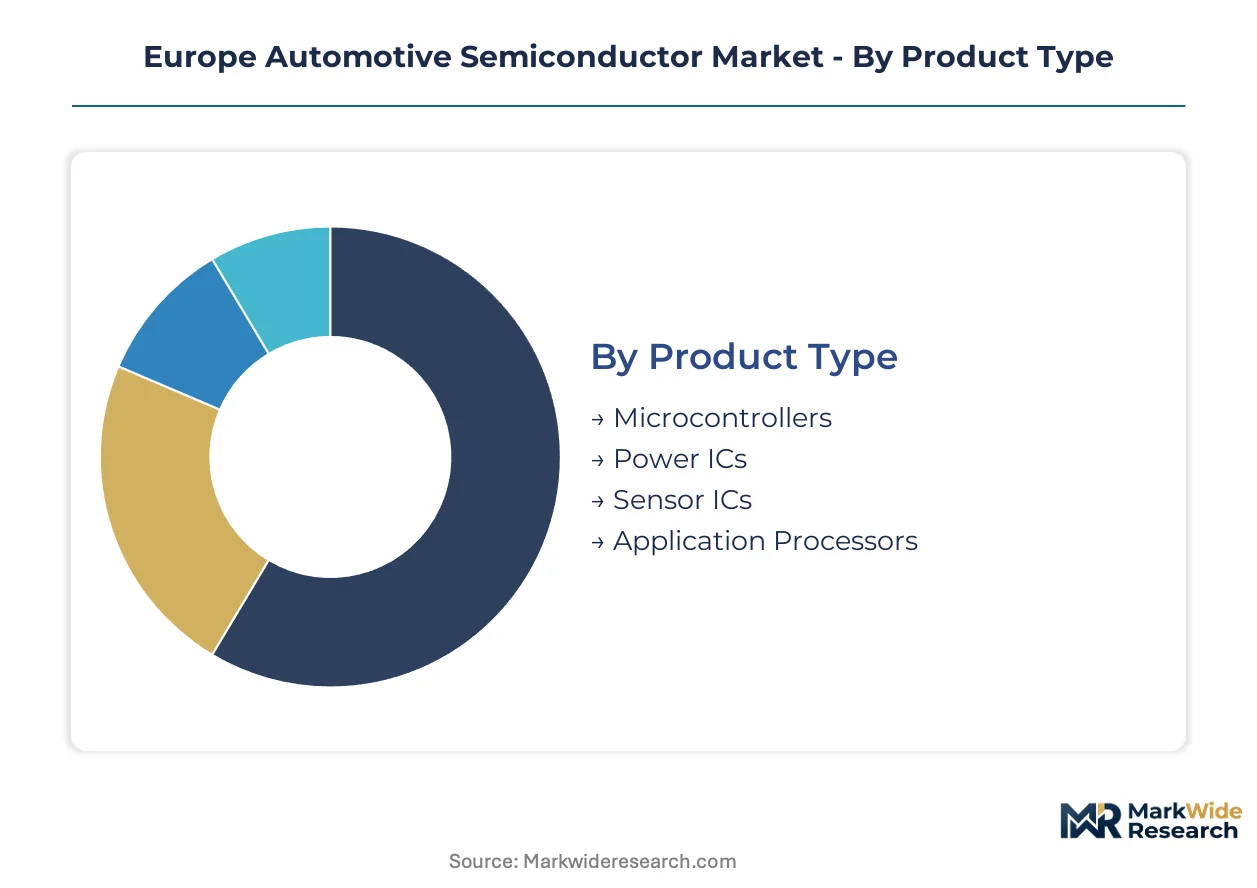
Semiconductor procurement across Europe's automotive corridor follows sharply divergent specification paths depending on vehicle program voltage architecture and safety-criticality tier. Tier-1 suppliers now bundle discrete functions into consolidated chipsets, collapsing traditional category boundaries while elevating mixed-signal integration requirements.
Product Type:
Standardization dominates high-volume microcontroller sockets while customization intensifies for powertrain-specific power ICs demanding thermal co-design with OEM engineering teams.
- Microcontrollers:Real-time control units fabricated on 40-nanometer automotive-qualified nodes execute engine management and chassis functions across minus 40°C to 150°C operating windows. Demand concentrates in Stuttgart-to-Munich procurement clusters where Volkswagen Group and BMW specify ASIL-D safety ratings for domain-controller integration.
- Power ICs:Traction inverter and onboard charger semiconductors manage voltage conversion across 400-volt to 800-volt platform architectures. German OEM procurement mandates silicon-carbide MOSFETs for premium drivetrain variants, displacing incumbent IGBT portfolios in high-performance applications.
- Sensor ICs:Battery-management system monitors providing cell-level voltage and temperature telemetry.
- Application Processors:Infotainment and cockpit domain compute engines with graphics acceleration.
Most installed capacity flows through Microcontrollers. Expansion is steepest in Power ICs.
Technology:
Cost tier separation distinguishes commodity digital logic from premium mixed-signal integration where European supplier capability gaps create procurement bottlenecks.
- Analog:Continuous signal conditioning circuits for sensor interfaces and power regulation. Design engineering talent scarcity across European universities forces chipmakers to poach internally or retrain, constraining supplier expansion timelines.
- Digital:Binary logic cores for protocol processing and compute acceleration. Volume procurement concentrates in Germany's automotive corridor with qualification timelines synchronized to model-year launches.
- Mixed-Signal:Bridging architectures combining analog front-ends with digital processing cores.
- Embedded Systems:Software-hardware integrated solutions with functional safety certification.
Margin concentration sits with Mixed-Signal. Volume scale favors Digital.
End User:
Application maturity separates established passenger vehicle programs from emerging autonomous vehicle qualification pathways shaped by EU AI Act risk classifications.
- Passenger Vehicles:Mass-market and premium light-duty programs with 12-volt legacy architectures coexisting alongside 48-volt mild-hybrid transitions. Dual-voltage portfolio maintenance fragments R&D allocation across European Tier-1 suppliers.
- Electric Vehicles:Battery-electric and plug-in hybrid platforms specifying 800-volt electrical architectures. EU Green Deal fleet-emission mandates multiply semiconductor content per vehicle for traction inverters and battery management systems.
- Commercial Vehicles:Heavy-duty truck and bus electrification programs.
- Autonomous Vehicles:Perception and decision-compute platforms requiring AI Act documentation trails.
Revenue scale peaks in Passenger Vehicles. Climbing the fastest is Electric Vehicles.
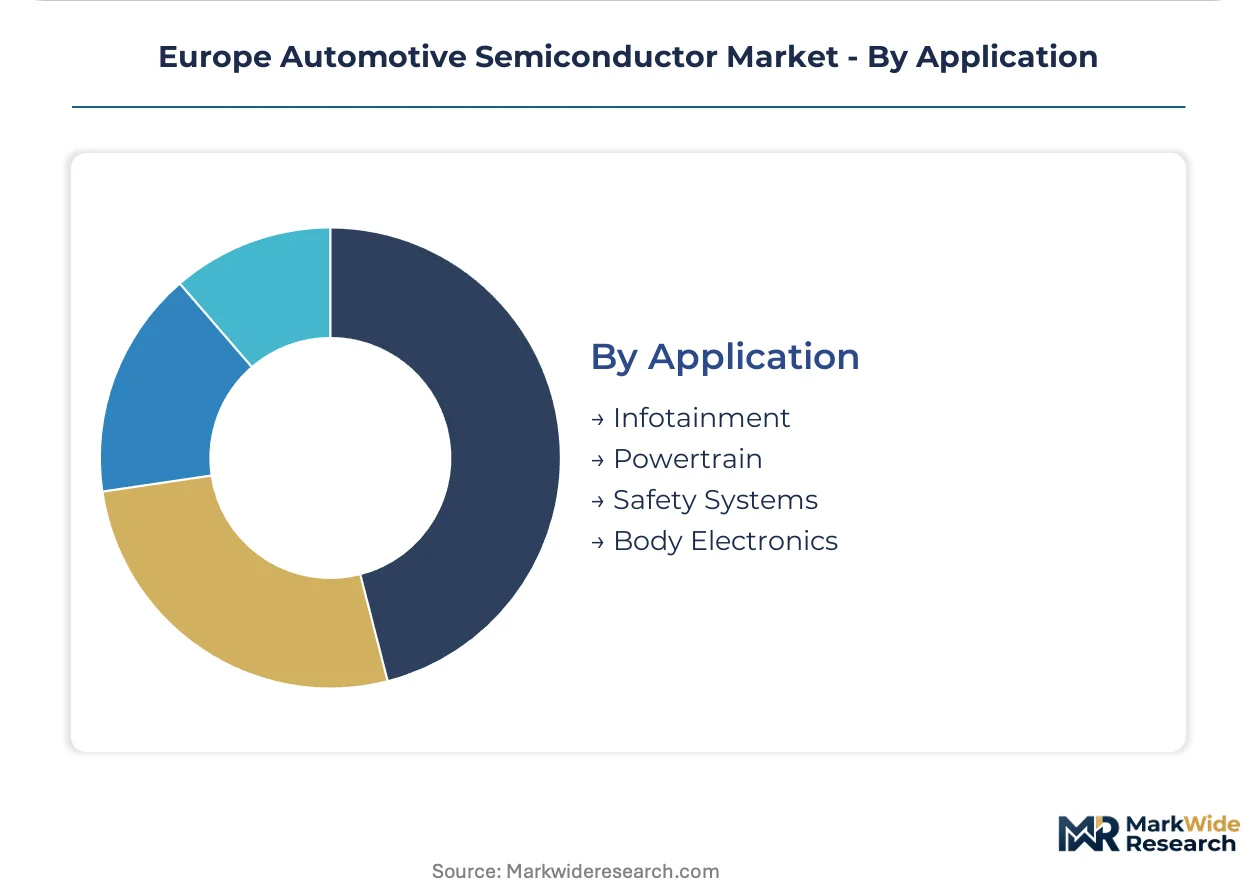
Application:
Supply concentration varies by functional safety tier, with ASIL-D safety systems demanding captive manufacturing and infotainment permitting fabless sourcing flexibility.
- Powertrain:Engine control, transmission management, and electrified drivetrain electronics. Silicon-carbide device integration into traction inverters compresses IGBT phase-out timelines above 400 volts.
- Safety Systems:Airbag deployment, anti-lock braking, and advanced driver-assistance compute. ISO 26262 ASIL-D qualification timelines extend 18-24 months for new process nodes, freezing out entrants without automotive track records.
- Infotainment:Cabin entertainment and connectivity modules.
- Body Electronics:Lighting, climate, and convenience subsystem controllers.
Qualification rigidity is tightest in Safety Systems. Sourcing flexibility is broadest in Infotainment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive semiconductor manufacturing in Europe traces its industrial lineage to post-war German engineering clusters that pioneered electronic fuel injection and chassis control systems. These foundations established the continent's dominance in powertrain-grade silicon and functional safety certification.
Germany
Volkswagen Group and BMW procurement teams specify silicon-carbide MOSFETs for 800-volt drivetrain variants. KBA vehicle-type approval requirements mandate electromagnetic compatibility testing under ECE R10. The Stuttgart-to-Munich corridor concentrates Tier-1 supplier engineering offices alongside captive fab capacity at Dresden.
France
Renault Group electrification roadmaps drive demand for battery-management sensor ICs with cell-level precision. ANSM and CNIL oversight extends to AI-enabled perception systems under EU AI Act risk classifications. The Île-de-France region hosts application engineering centers for gateway and zonal controller development.
Italy
Stellantis platform consolidation programs compress supplier rosters for microcontroller sockets. REACH chemical-substance restrictions constrain packaging material choices for power devices. Turin and Milan engineering clusters coordinate mixed-signal qualification timelines with German OEM launch cycles.
Netherlands
ASML lithography equipment anchors wafer fabrication supply chains serving automotive-qualified nodes. ECHA enforcement of SVHC candidate lists shapes substrate metallization specifications. Eindhoven's Brainport region concentrates semiconductor equipment and automotive application engineering talent.
United Kingdom
Jaguar Land Rover electrification commitments multiply semiconductor content per vehicle for traction inverters. The UK's departure from EU regulatory alignment creates parallel conformity assessment pathways for automotive electronics. Midlands engineering clusters maintain legacy powertrain expertise alongside battery-electric transitions.
Europe Automotive Semiconductor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across captive manufacturing and functional safety certification dimensions. The European automotive semiconductor structure consolidates around three dominant chipmakers with in-house fabrication, while fabless specialists occupy narrower application niches. IDM archetypes with captive fabs compete against mixed-signal specialists and power-device pure-plays. Competitive moves center on multi-year volume commitments with German OEMs and joint roadmap planning for 800-volt platform launches.
Within the integrated device manufacturer tier, Infineon Technologies AG and STMicroelectronics N.V. represent the captive-fabrication archetype, while NXP Semiconductors anchors the domain-architecture specialization vector. These entities occupy positions defined by manufacturing depth and safety-certification track records rather than product-specific claims.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| Robert Bosch |
| Texas Instruments |
| Renesas Electronics |
| ON Semiconductor |
| Analog Devices |
| ROHM |
| Others |
Pricing and Supply Chain Analysis
Mixed-signal engineering talent concentration in Germany's automotive corridor creates labor-cost differentials that widen pricing-tier spreads between captive-fabrication IDMs and fabless specialists. Dresden-based captive capacity commands premium pricing for ASIL-D qualified devices, while Eastern European backend assembly enables cost-competitive tiering for non-safety-critical sockets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes procurement negotiations, with ASIL-D certification grade and volume scale as primary differentiation drivers. Cost compression in economy-tier microcontrollers intensifies as Chinese foundries expand automotive-qualified capacity. Tier-1 suppliers exhibit highest price sensitivity for infotainment application processors, while powertrain divisions accept premiums for silicon-carbide thermal performance.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany operate hub-and-spoke patterns feeding just-in-sequence lines at Stuttgart and Munich assembly plants. Front-end wafer fabrication concentrates in Germany, France, and Italy, drawing from neon gas supplies in Ukraine and palladium metallization from Russian corridors. Single-source vulnerability at 300mm automotive-qualified foundries creates structural risk. Distribution runs through Tier-1 supplier consignment inventory at OEM campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe automotive semiconductors function as a stable compounder, with EU Green Deal fleet-emission mandates ensuring steady content-per-vehicle expansion regardless of macroeconomic cycles.
For Market Incumbents: Anchor market position through captive fab capacity additions in Dresden and Crolles, locking in multi-year volume commitments with Volkswagen Group and BMW. Defend against emerging silicon-carbide pure-plays by accelerating IGBT phase-out roadmaps. Prioritize ISO 26262 certification investment for 40-nanometer process nodes to freeze out fabless entrants lacking automotive track records. For New Entrants and Emerging Players: Capture white-space in battery-management sensor ICs where cell-monitoring precision demands outstrip incumbent capacity. Hungary and Romania backend assembly offers the most penetrable geographic entry point within EU regulatory jurisdiction. Pursue joint development agreements with Stellantis platform consolidation programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mixed-signal specialists with automotive analog design expertise but lacking captive fabrication. Five-to-ten year viability hinges on domain-architecture consolidation trends favoring software-integrated hardware portfolios. Watch silicon-carbide device yield rates at new 200mm substrates as the inflection signal for manufacturing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Capacity Expansion | Infineon and STMicroelectronics ramp Dresden and Crolles fabs to meet BMW 800-volt platform demand. |
| Domain Controller Integration | NXP consolidates gateway and zonal compute sockets previously fragmented across fifteen-plus vendors. |
| Eastern European Backend Migration | Bosch and Continental shift assembly-test operations to Hungary and Romania for cost positioning. |
| EU AI Act Compliance Investment | Perception chip suppliers establish safety-case methodologies for high-risk autonomous vehicle classifications. |
| Multi-Year Volume Commitments | German OEM procurement teams demand joint roadmap planning in exchange for design-win access. |
Research Methodology
Coverage spans Germany, France, Italy, the Netherlands, and the United Kingdom, with primary inputs from each market's automotive engineering clusters. The analysis combines structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, and semiconductor application engineering leads with secondary validation from vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and EU regulatory filings. Bottom-up content-per-vehicle modeling triangulates against top-down market sizing.
Granularity-level framing segments the market by vehicle class, propulsion architecture, content per vehicle, and OEM tier across the analysis window. CAGRs derive from regression analysis against EU fleet-emission trajectory enforcement and 800-volt platform rollout schedules. Semiconductor supplier revenue recognition patterns and foundry utilization rates inform capacity-constrained scenario testing.
Geopolitical supply disruption, foundry yield shortfalls at new process nodes, and EU AI Act enforcement delays are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Discrete Semiconductor Market
Semiconductors
Semiconductor IP Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Logic Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Europe Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Semiconductor Clock Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
North America Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
Semiconductor in Military and Aerospace Market