
 High Voltage Electric Heater Market | 2026-2036
High Voltage Electric Heater Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Electric Heater Market Foresight
The split between premium and commodity tiers is shifting along thermal efficiency thresholds and OEM certification requirements. BorgWarner Inc. leverages its power electronics integration to anchor the premium tier for EV battery conditioning. Eberspächer Gruppe GmbH & Co. KG specializes in compact modular designs that compete aggressively in cost-sensitive commercial vehicle applications. Continental AG dominates system-level thermal management by extending its sensor and control portfolio into heater assemblies.
High voltage electric heaters convert electrical energy at 400V–800V into thermal output through resistive or positive temperature coefficient elements, with power densities reaching 5–7 kW per liter for automotive cabin and battery warming applications. The automotive sector leads volume demand as OEMs replace PTC heaters with advanced induction and microwave technologies to reduce energy draw from traction batteries. Convection heaters occupy the mature industrial baseline, while radiant and infrared configurations capture margin pools in precision manufacturing environments where targeted heating minimizes thermal waste.
The EPA tailpipe standards and NHTSA fuel economy mandates in the US, alongside REACH chemical compliance and the EU F-Gas Regulation in Europe, compel manufacturers to eliminate fluorinated greenhouse gases and validate material safety across heater supply chains. China's SAMR enforces GB standards for high voltage electrical safety in passenger vehicles, creating a three-pillar compliance architecture that shapes product design and market access decisions. Stakeholders must monitor how battery-electric platform voltages migrate toward 800V architectures, as this transition will redefine heater efficiency benchmarks and supplier qualification criteria.
Market Dynamics
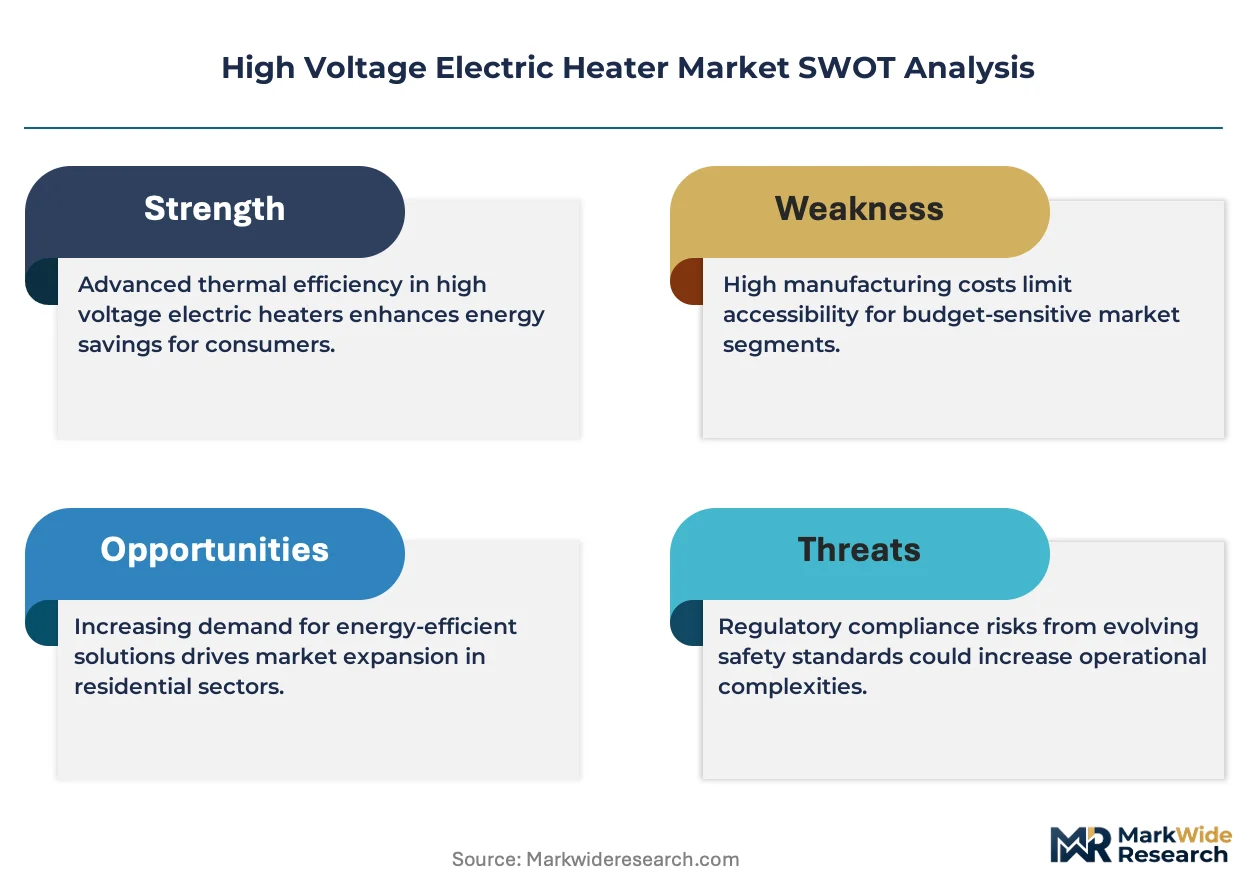
The migration from 400V to 800V electric vehicle architectures is compressing heater efficiency benchmarks and forcing suppliers to redesign thermal management subsystems around higher voltage tolerances and faster heating response curves.
Growth Catalysts
- China's dual carbon goals:National mandates to peak carbon emissions before 2030 and achieve neutrality by 2060 are accelerating the phase-out of fossil fuel cabin heating in favor of electrified systems across passenger and commercial vehicle platforms.
- Battery thermal management demand:Electric vehicle OEMs are integrating high voltage heaters directly into battery conditioning loops to maintain optimal operating temperatures during fast-charging events and cold-weather operation.
- EU F-Gas Regulation:The progressive ban on fluorinated greenhouse gases in mobile air conditioning systems is eliminating refrigerant-based heating alternatives and channeling investment toward resistive and induction-based electric heating technologies.
Market Restraints
- Raw material cost volatility:Price swings in copper windings and rare-earth magnetic materials for induction heater cores are compressing margins for manufacturers without long-term supply agreements or backward integration into component production.
- Supply concentration risk:Power semiconductor fabrication for heater control modules concentrates in Taiwan and South Korea, creating vulnerability to geopolitical disruption or capacity constraints during demand surges.
- Technical limitation:Resistive PTC elements face inherent efficiency ceilings near 95%, leaving limited headroom for differentiation against emerging microwave and induction alternatives that promise superior energy conversion rates.
Strategic Opportunities
- Commercial vehicle electrification:Bus and heavy-duty truck fleets in Germany and the Netherlands are retrofitting depot-based charging infrastructure with integrated high voltage heating systems for overnight battery conditioning and cabin pre-warming.
- Induction-microwave convergence:Hybrid heating architectures that combine electromagnetic induction for rapid initial warming with microwave distribution for uniform cabin heat are opening patent white space outside established PTC licensing networks.
- US IRA manufacturing incentives:Domestic content requirements and production tax credits under the Inflation Reduction Act are attracting heater assembly investments to Michigan and Tennessee to serve North American EV battery plants.
Industry Challenges
- Functional safety certification:ISO 26262 automotive safety integrity level validation for high voltage heater control software is extending product development cycles by 12-18 months and requiring specialized embedded systems engineering talent.
- Legacy thermal system integration:OEMs must reconcile 800V heater designs with existing 400V HVAC ducting, coolant routing, and cabin control interfaces without complete platform redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Electric Heater Market |
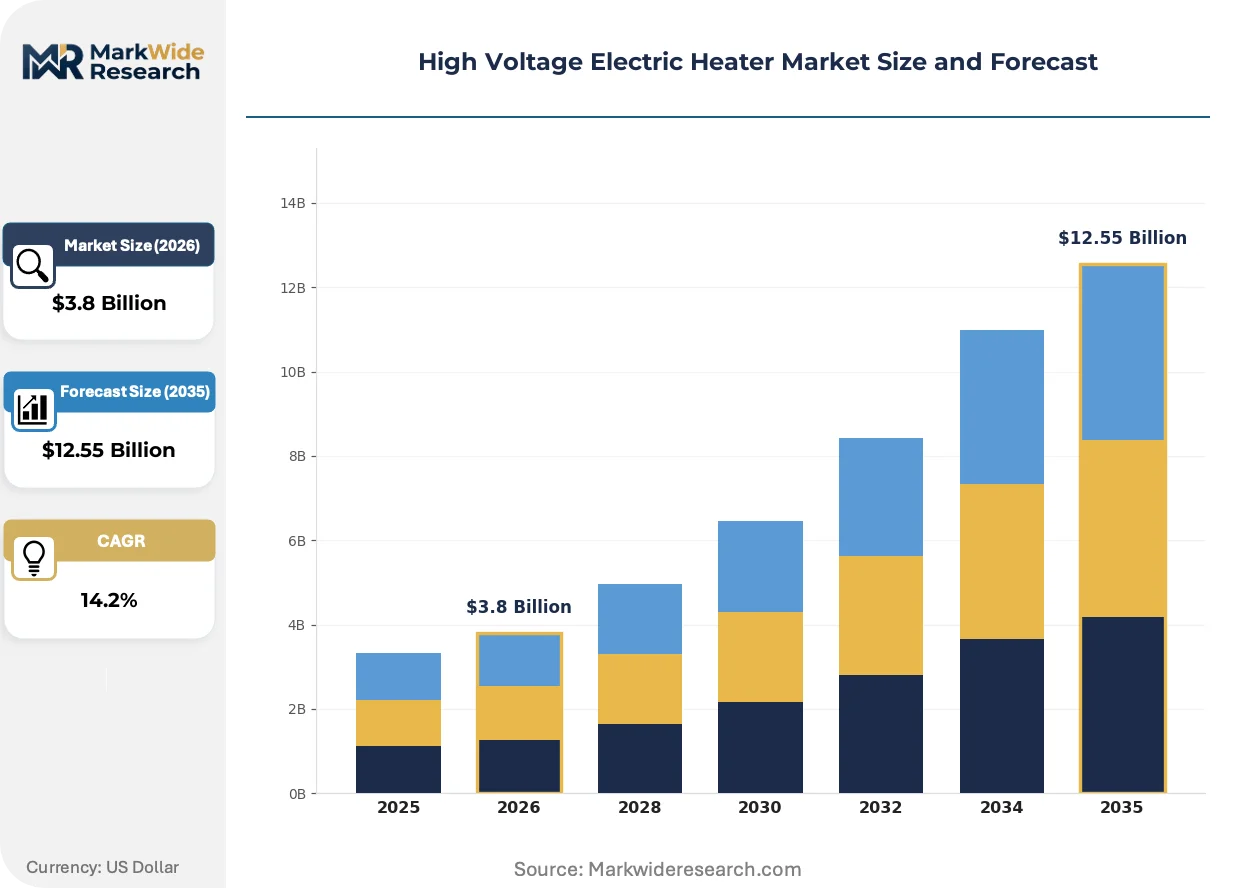
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiant Heaters, Convection Heaters, Infrared Heaters, Induction Heaters End User: Industrial Equipment, Commercial Applications, Residential Heating, Automotive Sector Installation: Wall-Mounted, Floor-Mounted, Portable, Embedded Technology: Electric Resistance, Thermal Oil, Microwave, PTC Heating |
| Companies Covered | BorgWarner Inc., Eberspächer Gruppe GmbH & Co. KG, Continental AG, LG Electronics, Webasto SE, Mitsubishi Heavy Industries Ltd., MAHLE GmbH, DBK Group, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Electric Heater Market Shifts & Advancements
Heater technology trajectories are converging on energy efficiency maximization and platform voltage standardization, with suppliers racing to secure qualification slots on next-generation electric vehicle thermal architectures before design locks occur.
Silicon carbide power electronics are unifying heater control and traction inverter functions into consolidated thermal-electrical modules. Tier-1 suppliers in Germany's automotive corridor are adopting these integrated architectures to reduce wiring harness complexity and packaging volume. This unification is compressing the supplier base by disqualifying pure-play heater manufacturers lacking power electronics capabilities.
REACH chemical compliance and the EU F-Gas Regulation are mandating full material disclosure and fluorinated gas elimination across heater supply chains. Manufacturers must now validate solder alloys, potting compounds, and conformal coatings against restricted substance lists. Battery-electric vehicle platforms with integrated thermal management are experiencing the steepest compliance cost escalation as they combine high voltage electrical, coolant, and refrigerant circuits.
Fleet procurement departments are consolidating heater specifications across multiple vehicle programs to extract volume pricing and simplify service part logistics. This concentration is displacing bespoke heater designs tailored to individual OEM platforms in favor of modular product families with configurable thermal output and voltage ratings. The shift is most visible in China's commercial vehicle sector, where state-owned fleet operators are standardizing on three heater suppliers for their entire electrified bus and truck portfolios.
High Voltage Electric Heater Market Segmentation
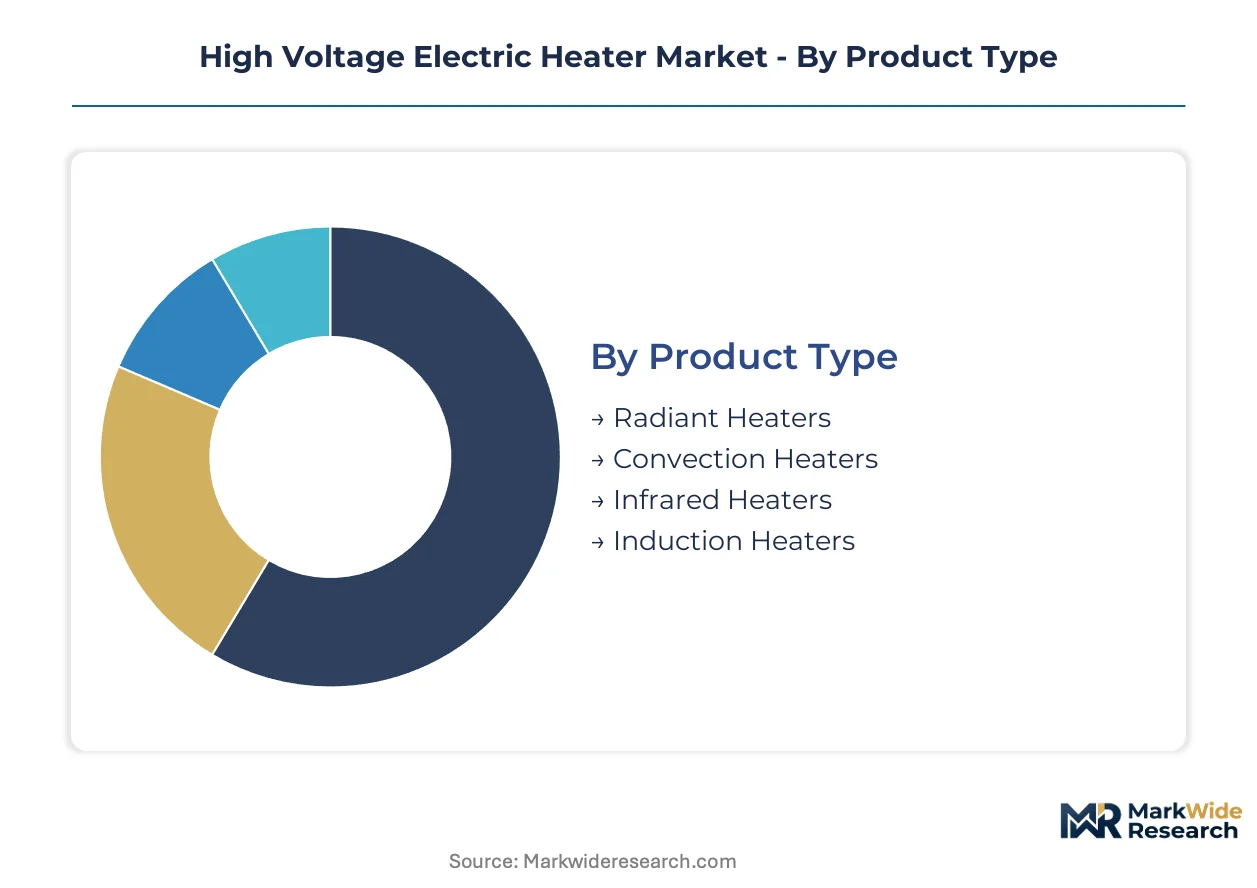
Segmentation in the high voltage electric heater market reveals how thermal output specifications, voltage tolerances, and integration depth vary sharply across application contexts. Product design priorities diverge between automotive battery conditioning systems requiring millisecond response curves and industrial process heating demanding steady-state thermal stability.
Product Type:
Customization intensity spans from standardized convection cores for warehouse heating to bespoke induction coil geometries for precision manufacturing cells.
- Induction Heaters:Electromagnetic field generation through copper coil assemblies converts electrical energy to thermal output without resistive element contact. Automotive OEMs in Germany's manufacturing corridor specify these for battery warming loops where rapid temperature ramp rates protect lithium-ion cells during fast-charging protocols.
- Radiant Heaters:Infrared-emitting surfaces distribute thermal energy through electromagnetic radiation rather than convective air movement. Precision electronics assembly lines in Japan's industrial clusters deploy radiant configurations to localize heating on component solder zones while maintaining ambient temperature stability across cleanroom environments.
- Convection Heaters:Resistive elements warm ambient air through forced or natural circulation patterns. Baseline industrial heating applications in legacy manufacturing facilities favor these units for their straightforward installation and minimal control system requirements.
- Infrared Heaters:Quartz or ceramic emitters generate targeted thermal wavelengths for surface heating applications. Paint curing operations in automotive assembly plants specify infrared arrays to accelerate coating polymerization without heating entire vehicle bodies.
Most installed capacity flows through convection heaters. Expansion is steepest in induction heaters.
End User:
Volume concentration tilts toward automotive platforms while margin capture concentrates in specialized industrial equipment.
- Automotive Sector:Cabin comfort and battery thermal management systems integrate 400V–800V heaters directly into electric vehicle architectures. China's SAMR-enforced GB standards for high voltage electrical safety mandate specific isolation distances and fault protection protocols that shape heater housing designs for domestic OEM platforms.
- Industrial Equipment:Process heating for chemical reactors, plastic extrusion lines, and metal treatment baths demands precise temperature control across extended duty cycles. German chemical manufacturers specify heaters with SIL-rated safety systems for exothermic reaction containment.
- Commercial Applications:Retail spaces, hospitality venues, and healthcare facilities require zoned heating with occupancy-based control integration. Building management system compatibility drives specification decisions for commercial installations.
- Residential Heating:Single-family and multi-unit dwellings employ high voltage heaters primarily in cold-climate regions where heat pump efficiency degrades. Grid capacity constraints in rural distribution networks limit deployment scalability.
Automotive applications command the highest unit values. Industrial equipment delivers the most stable replacement demand cycles.
Installation:
Mounting configuration determines thermal distribution patterns and maintenance accessibility trade-offs across facility types.
- Embedded:Heater elements integrate directly into equipment structures or building fabric without exposed housings. Battery pack manufacturers in South Korea specify embedded heaters laminated between cell arrays to minimize thermal gradient formation across high-capacity modules.
- Wall-Mounted:Vertical surface installation maximizes floor space utilization in compact commercial kitchens and cleanroom environments. Swiss pharmaceutical facilities specify wall-mounted radiant panels to maintain laminar airflow patterns.
- Floor-Mounted:Ground-level positioning supports heavy-duty industrial units with substantial thermal mass. Steel foundries in India's manufacturing belt deploy floor-mounted convection banks for preheating ladles and molds.
- Portable:Mobile configurations with integrated power connection and control systems serve temporary heating requirements. Construction site applications in Canada's northern territories use portable units for concrete curing during winter pours.
Embedded installations dominate new platform development. Portable configurations show the strongest demand elasticity to seasonal temperature variation.
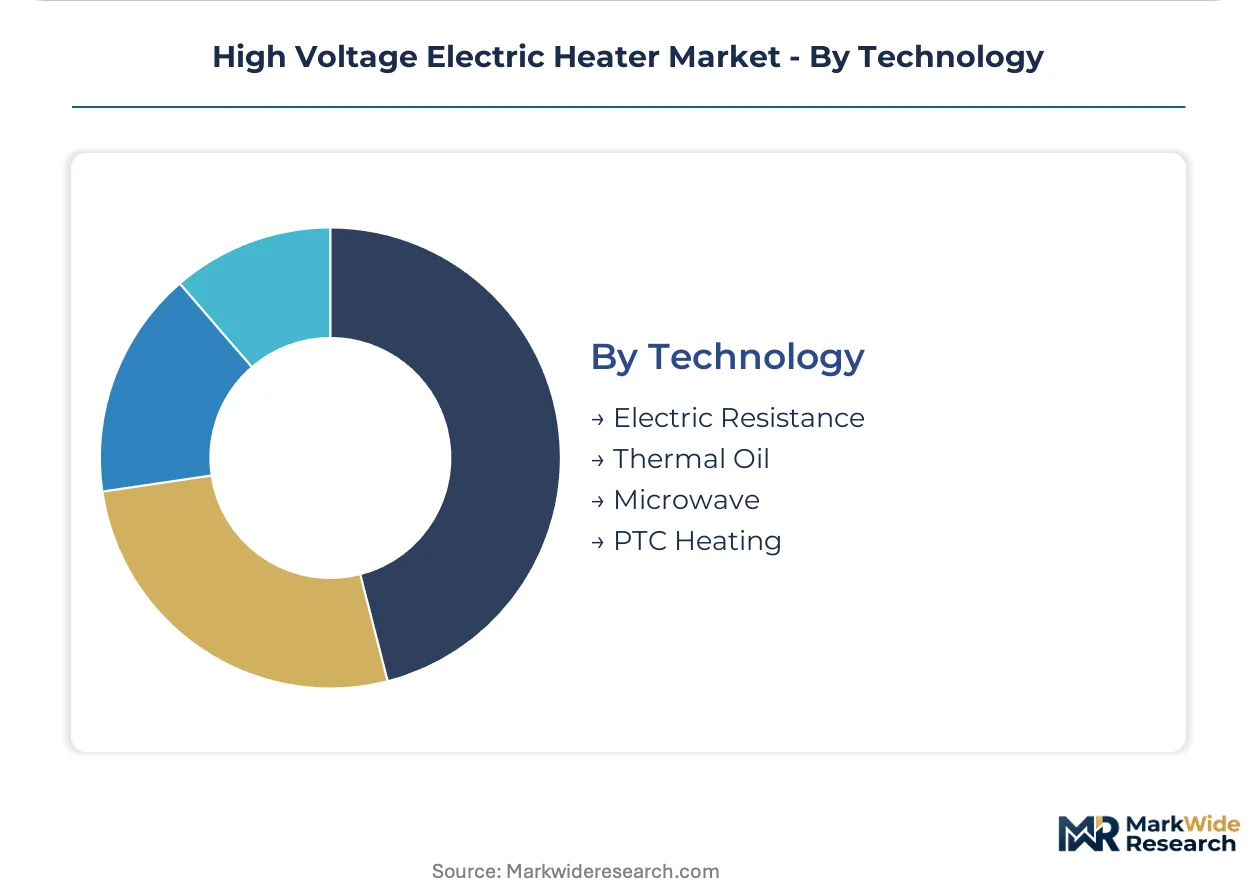
Technology:
Energy conversion efficiency and control precision separate mature resistive approaches from emerging electromagnetic alternatives.
- Microwave:Dielectric heating through electromagnetic field excitation of polar molecules enables volumetric thermal penetration rather than surface-limited conduction. Food processing facilities in the Netherlands pilot microwave heating for pasteurization lines where rapid uniform warming preserves nutritional profiles.
- PTC Heating:Positive temperature coefficient ceramic elements self-limit current draw as resistance increases at elevated temperatures. Automotive cabin heaters in cold-climate markets favor PTC technology for inherent safety against thermal runaway without external control circuitry.
- Electric Resistance:Nichrome or similar alloy conductors generate thermal output through Joule heating. Baseline industrial applications continue specifying resistive elements for capital cost minimization despite efficiency limitations.
- Thermal Oil:Indirect heating through circulating heat transfer fluids enables precise temperature distribution across extended process loops. Chemical synthesis operations requiring tight thermal uniformity specify thermal oil systems.
Electric resistance retains the largest installed base. Microwave technology is gaining share fastest in precision processing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor generates concentrated demand for battery thermal management systems, while China's dual carbon policy framework accelerates electrification timelines across its commercial vehicle fleet.
China
SAMR-enforced GB standards for high voltage electrical safety are reshaping heater housing designs for domestic OEM platforms. The dual carbon goals mandate peak emissions before 2030 and carbon neutrality by 2060, eliminating fossil fuel cabin heating in favor of electrified systems. State-owned fleet operators in Beijing and Shanghai are standardizing on three heater suppliers for their entire electrified bus and truck portfolios.
Germany
OEMs across Bavaria and Baden-Württemberg are integrating high voltage heaters into next-generation EV platforms. The EU F-Gas Regulation progressively bans fluorinated greenhouse gases in mobile air conditioning, channeling investment toward resistive and induction-based electric heating technologies. Stuttgart's automotive corridor hosts Tier-1 suppliers adopting silicon carbide power electronics to unify heater control and traction inverter functions.
United States
EPA tailpipe standards and NHTSA fuel economy mandates compel manufacturers to validate material safety across heater supply chains. The Inflation Reduction Act's domestic content requirements and production tax credits are attracting heater assembly investments to Michigan and Tennessee. Detroit's EV battery plants are qualifying suppliers for 800V thermal management subsystems.
South Korea
Battery pack manufacturers specify embedded heaters laminated between cell arrays to minimize thermal gradient formation across high-capacity modules. The country's national automotive regulator enforces high voltage electrical isolation standards for passenger vehicle platforms. Seoul's industrial cluster is concentrating power semiconductor fabrication for heater control modules.
Japan
Precision electronics assembly lines deploy radiant heater configurations to localize heating on component solder zones while maintaining ambient temperature stability. METI guidelines shape industrial energy efficiency standards for process heating equipment. Nagoya's manufacturing belt is piloting hybrid heating architectures that combine electromagnetic induction with microwave distribution.
High Voltage Electric Heater Market Competitive Landscape
Top-tier vendors anchor the premium tier for EV battery conditioning, while compact modular specialists compete aggressively in cost-sensitive commercial vehicle applications. The market exhibits tiered concentration around power electronics integration capability, thermal efficiency thresholds, and OEM certification requirements. Three archetypes dominate: integrated thermal-electrical module suppliers, compact modular design specialists, and system-level thermal management providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers race to secure qualification slots before design locks occur.
Among Germany-based fabricators, BorgWarner Inc. and Eberspächer Gruppe GmbH & Co. KG exemplify divergent strategic positioning within the automotive thermal management space. BorgWarner occupies a position representing the premium-tier vector through power electronics integration, while Eberspächer sits within the compact modular tier serving cost-sensitive applications. Continental AG anchors the system-level thermal management archetype by extending control portfolios into heater assemblies. LG Electronics represents the Asia-Pacific challenger archetype competing on scale and electronics manufacturing depth.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Eberspächer Gruppe GmbH & Co. KG |
| Continental AG |
| LG Electronics |
| Webasto SE |
| Mitsubishi Heavy Industries Ltd. |
| MAHLE GmbH |
| DBK Group |
| Valeo SA |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ISO 26262-validated automotive modules and baseline industrial units manifests in divergent pricing floors and supply chain sourcing strategies. Premium-tier suppliers in Germany command pricing power through captive silicon carbide fabrication, while commodity producers in China compete on copper winding costs and standardized PTC element volumes.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for power semiconductor control modules. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-integrated automotive systems from silicon-based commercial vehicle units and basic resistive industrial cores. Cost compression in the commodity tier is intensifying because Chinese manufacturers are expanding induction coil production for domestic EV platforms. Fleet procurement departments at European commercial vehicle operators exhibit the highest price sensitivity, while German OEM platform engineering teams prioritize thermal response performance over unit cost.
Supply Chain Analysis
ISO 26262 certification gating restricts qualified supplier pools to Tier 1 manufacturers with embedded systems engineering capabilities. Power semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while copper winding and magnetic core production anchors in China and Germany. Heater assembly draws from rare-earth magnetic materials, silicon carbide wafers, and high-temperature solder alloys. Single-source vulnerability in 800V-rated power electronics creates exposure to geopolitical disruption or foundry capacity constraints. Distribution runs through OEM direct procurement for automotive applications and industrial distributor networks for commercial heating equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high voltage electric heater market functions as a stable compounder, with EV platform thermal standardization driving predictable replacement demand and technology upgrade cycles.
For Market Incumbents: Deepen backward integration into silicon carbide power electronics to defend margin position against emerging induction-microwave hybrid entrants. Secure long-term supply agreements with Taiwanese foundries to mitigate semiconductor concentration risk. Prioritize ISO 26262 certification investment for 800V architectures before OEM design locks occur.
For New Entrants and Emerging Players: Commercial vehicle fleet operators in the Netherlands and Germany represent an underserved buyer archetype with standardized procurement specifications and limited incumbent loyalty. Target depot-based charging infrastructure providers with modular battery conditioning systems. Pursue white-label manufacturing partnerships with established automotive Tier 2 suppliers to bypass OEM qualification barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where power electronics capabilities overlap with thermal management expertise but remain housed in separate corporate structures. The 5-10 year viability window favors platform-agnostic suppliers with voltage-flexible architectures. Acquisition targets should demonstrate qualification slots on multiple OEM 800V programs. Watch for inflection when Chinese state-owned fleet operators consolidate heater specifications across bus and truck portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Unifies heater control and traction inverter functions, reducing wiring harness complexity for German OEMs. |
| ISO 26262 Certification Investment | Opens qualification slots on next-generation 800V EV platforms before design locks occur. |
| Backward Integration into Magnetic Cores | Captures rare-earth supply chain margin and insulates against raw material price volatility. |
| Commercial Vehicle Fleet Partnership | Locks in volume offtake from Netherlands and Germany depot electrification programs. |
| Induction-Microwave Hybrid Patent Development | Creates intellectual property white space outside established PTC licensing networks. |
Research Methodology
Multiple input streams — OEM platform engineering interviews, Tier 1 supplier procurement discussions, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged thermal management directors at German and Chinese automotive manufacturers, power electronics procurement leads at battery pack producers, and fleet operations managers at European commercial vehicle operators. Secondary validation drew from EPA tailpipe standard filings, SAMR GB standard publications, EU F-Gas Regulation implementation reports, and vehicle production registration databases. Bottom-up unit demand modeling and top-down market sizing triangulated volume and value outputs.
Data-stream reconciliation across product type, voltage architecture, end-use application, and regional regulatory cluster informed the analytical framework. Segmentation dimensions modeled included heater technology, installation configuration, and OEM tier positioning. CAGRs were derived from slope analysis of adoption curves and technology substitution rates. Key forecast inputs incorporated 800V platform migration timelines and EU F-Gas phase-out schedules.
Underlying measurement precision varies by segment; automotive battery thermal management carries tighter precision than industrial process heating due to visible OEM platform commitments. Forecasts reflect assumptions regarding EV penetration rates, semiconductor foundry capacity expansion, and regulatory enforcement consistency. Deviation in 800V architecture adoption speed or rare-earth supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Portable Fan Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Modular Contactor Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Central Vacuum Receivers Market