
 Metal Complex Dyes Market | 2026-2036
Metal Complex Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Complex Dyes Market Analytics
Color matching and shade prediction software is expanding as a service layer that dye suppliers bundle with bulk pigment contracts. Huntsman Corporation leverages its digital color management platform to lock in long-term textile mill relationships. BASF SE sustains R&D intensity in metal complex chemistries through captive synthesis of chromium-cobalt complexes. Clariant AG anchors its position in leather finishing by controlling distribution networks across European tannery clusters.
Metal complex dyes are synthetic colorants formed by coordinating transition metal ions, typically chromium or cobalt, with organic ligands to produce complexes exhibiting exceptional lightfastness and thermal stability above 200°C. These dyes serve primarily to color substrates where conventional azo or anthraquinone dyes fail to meet durability requirements, notably in automotive leather and high-performance polyester textiles. Azo dyes still occupy the largest volume share across metal complex formulations, though reactive dyes are gaining share in cotton-rich technical textiles where wash-fastness specifications tighten. Leather applications command the strongest margin pools due to the complexity of substrate-specific shade matching and the premium pricing power held by specialized dye houses.
REACH in the European Union and EPA regulations in the United States both restrict hexavalent chromium content in consumer-facing dyed articles, forcing reformulation toward trivalent complex alternatives. India's BIS certification requirements for imported dye intermediates add compliance costs that favor domestic manufacturers with established testing relationships. CHT Group and Rudolf GmbH compete partly on regulatory pre-certification, maintaining dossiers that accelerate customer approval timelines. Stakeholders must monitor how the EU Green Deal's expanding chemical hazard classifications will recategorize cobalt-based complexes before committing to multi-year capacity expansions.
Market Dynamics
REACH compliance in the European Union is forcing tanneries and textile mills to abandon hexavalent chromium formulations entirely, compressing the reformulation timeline for metal complex dye suppliers while simultaneously opening premium pricing tiers for pre-certified alternatives.
Growth Catalysts
- Automotive Leather Upholstery:Luxury vehicle manufacturers in Italy and Turkey are expanding specifications for metal complex dyes in dashboard and seating applications, creating sustained demand pull for high-fastness formulations.
- REACH-Driven Reformulation Mandates:The European Union's chemical hazard classifications are accelerating substitution of legacy chromium chemistries with trivalent complex alternatives, benefiting compliant suppliers.
- Surat and Tiruppur Textile Clusters:Export-oriented dye houses in these Indian manufacturing hubs are scaling specialty metal complex consumption to meet international buyer durability specifications.
Market Restraints
- Cobalt and Chromium Feedstock Volatility:Transition metal prices fluctuate with mining output concentrated in the Democratic Republic of Congo and Kazakhstan, compressing formulation margins unpredictably.
- Specialized Synthesis Capacity Concentration:Captive production of chromium-cobalt complexes remains concentrated among integrated chemical majors, limiting toll manufacturing options for mid-scale dye houses.
- Reactive Dye Substitution in Cotton-Rich Technical Textiles:Wash-fastness improvements in fiber-reactive chemistries are displacing metal complex alternatives in select apparel and home textile segments.
Strategic Opportunities
- Digital Color Management Convergence:Bundling shade prediction software with bulk pigment contracts is overtaking traditional specification selling, locking in multi-year textile mill relationships through integrated service layers.
- EU Green Deal Chemical Hazard Expansion:Upcoming reclassification of cobalt-based complexes will favor early movers with pre-submitted regulatory dossiers and accelerated customer approval timelines.
- India BIS Certification Localization:Domestic manufacturers with established testing relationships are capturing import substitution opportunities as certification requirements add compliance costs for foreign dye intermediate suppliers.
Industry Challenges
- Substrate-Specific Shade Matching Expertise:Leather finishing applications require specialized colorimetric skills that concentrate among aging technician pools in European tannery clusters, constraining quality consistency.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA, REACH, and BIS pre-approvals extend product launch cycles by 18-24 months, freezing working capital in pending regulatory reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Complex Dyes Market |
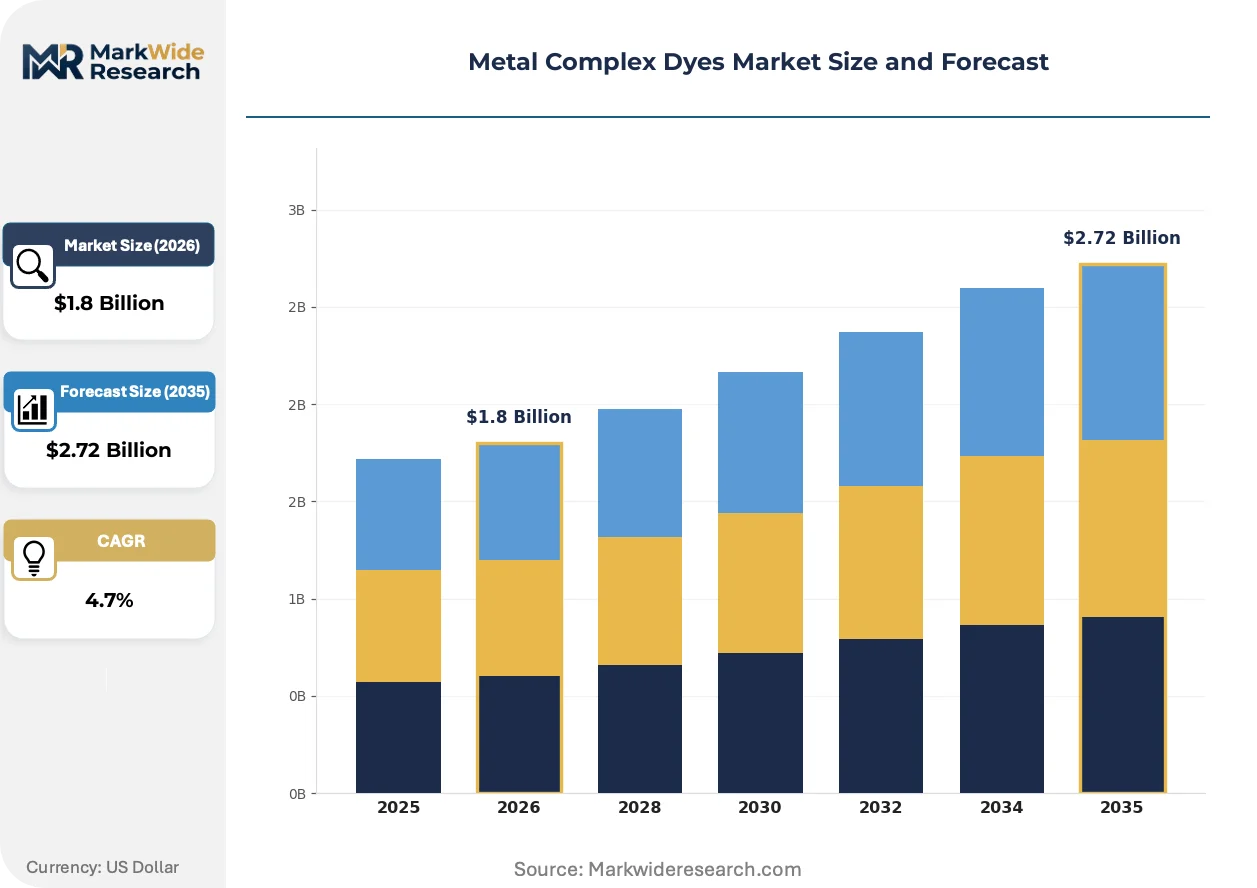
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Dyes, Non-Azo Dyes, Reactive Dyes, Direct Dyes Application: Textiles, Paints, Plastics, Leather End User: Textile Manufacturers, Paint Producers, Plastics Industry, Leather Goods Form: Powder, Liquid, Granule, Paste |
| Companies Covered | Huntsman Corporation, BASF SE, Clariant AG, DyStar, Archroma, Suzhou Sunway Dyes & Chemicals, Kolor Jet Chemical, CHT Group, Rudolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Complex Dyes Market Evolving Landscape
Formulation science and digital specification tools are converging to compress the traditional dye procurement cycle, while regulatory hazard reclassifications simultaneously threaten incumbent chemistries and reward pre-certified alternatives.
Water-based metal complex dispersions with sub-micron particle stability are overtaking solvent-borne systems in automotive leather coating lines. Tier-1 seating suppliers in Germany and the Czech Republic have completed validation trials for these low-VOC alternatives. The technology is overtaking incumbent solvent systems by eliminating thermal drying stages and reducing workplace exposure compliance costs.
ECHA's ongoing evaluation of cobalt salts under REACH substance evaluation is forcing reformulation roadmaps across the European leather finishing sector. Tanneries in Northern Italy and Spain are accelerating trivalent chromium complex adoption to preempt authorization listing consequences. Small and mid-scale dye houses without captive synthesis capabilities face the steepest compliance cost escalation.
Specification selling through color matching software subscriptions is displacing traditional commission-based dyestuff distribution in South Asian textile export clusters. Mills in Surat now contract directly with platform-integrated suppliers, bypassing regional chemical traders. Tiruppur-based polyester processors have compressed their supplier bases by 40 percent through this channel consolidation.
Metal Complex Dyes Market Segmentation
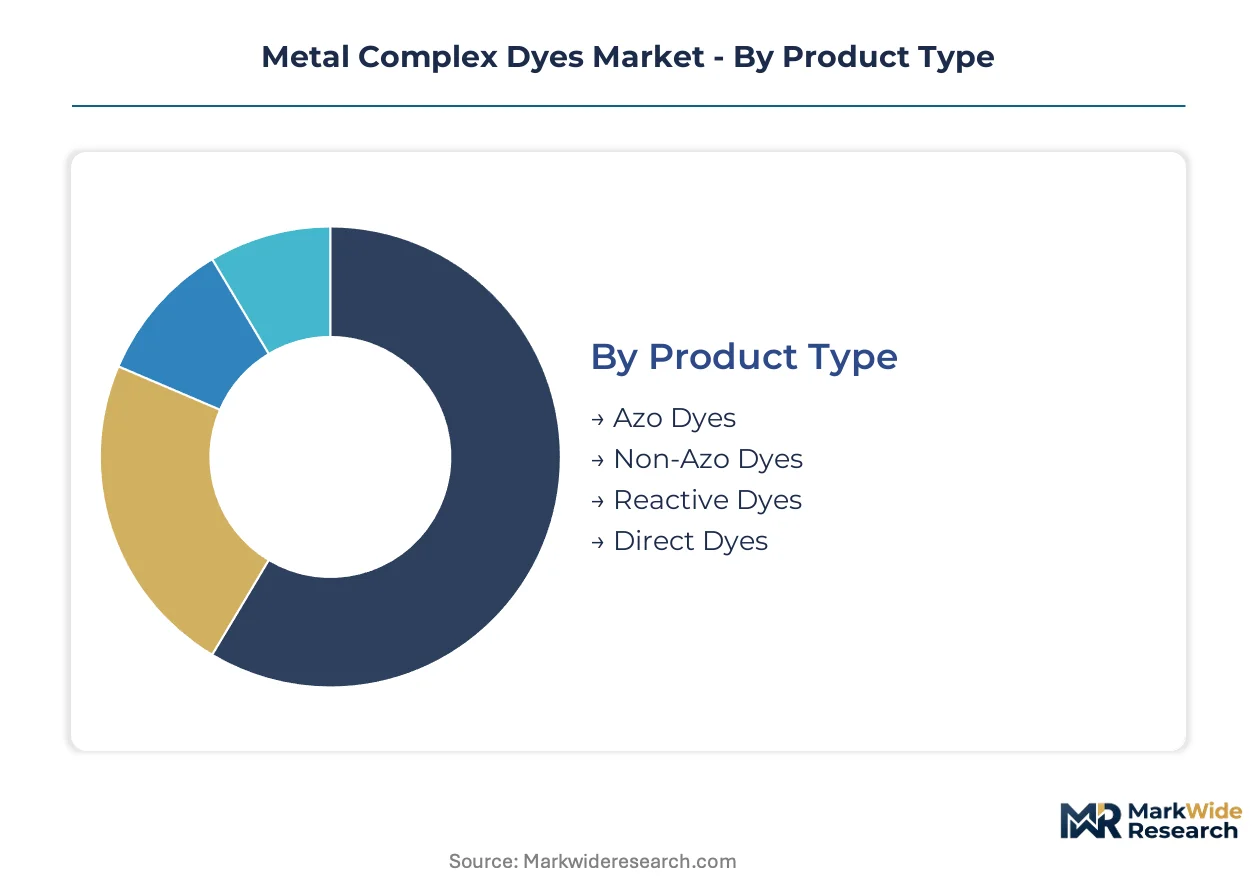
Metal complex dye procurement splits across formulation chemistry, substrate compatibility, and delivery format, with each axis carrying distinct regulatory and technical certification burdens that reshape supplier-customer contracting.
Product Type:
REACH pre-certification requirements in the European Union fall heaviest on chromium-bearing formulations, while azo-based complexes face separate restriction protocols under ECHA substance evaluation.
- Azo Dyes:These metal-chelated azo structures coordinate chromium or cobalt ions with azo ligands to achieve thermal stability above 200°C. Demand concentrates in automotive leather finishing across Italian and Turkish tannery clusters, where ECHA-compliant trivalent chromium alternatives command premium contract tiers against hexavalent legacy formulations.
- Reactive Dyes:Fiber-reactive metal complexes form covalent bonds with cellulose substrates, delivering wash-fastness specifications that meet international buyer requirements. Tiruppur-based cotton processors are scaling these chemistries for technical textile exports, displacing conventional metal complex alternatives in select apparel segments.
- Non-Azo Dyes:Anthraquinone and phthalocyanine-based metal complexes serving polyester coloration where lightfastness specifications exceed azo capabilities.
- Direct Dyes:Water-soluble metal complex variants for cotton and viscose substrates requiring simplified application protocols without intermediate diazotization steps.
Azo dyes sit at the top of the volume ranking, with reactive dyes climbing the fastest.
Application:
Margin structures diverge sharply by substrate complexity, with leather commanding the widest spreads due to shade-matching expertise requirements.
- Leather:Automotive upholstery specifications from German and Czech Tier-1 seating suppliers drive consumption of high-fastness chromium-cobalt complexes. Northern Italian tanneries are completing validation trials for water-based dispersions that eliminate solvent-borne thermal drying stages.
- Textiles:Polyester and technical fabric coloration in Surat and Tiruppur clusters scales specialty metal complex consumption for export durability requirements. Specification selling through digital color management platforms is consolidating mill supplier bases.
- Paints:Industrial coating applications requiring thermal stability and exterior durability for architectural and automotive refinish segments.
- Plastics:Polymer masterbatch integration where migration resistance and heat stability during extrusion processing are critical performance parameters.
Leather captures the highest margin tier, while textiles expands most quickly by volume.
End User:
Procurement sophistication separates integrated chemical majors from toll-dependent dye houses across customer categories.
- Textile Manufacturers:Export-oriented dye houses in Surat now contract directly with platform-integrated suppliers, bypassing regional chemical traders through bundled shade prediction software subscriptions.
- Leather Goods:High-end automotive upholstery manufacturers in Italy and Turkey are expanding procurement specifications for metal complex dyes, creating sustained demand pull for pre-certified formulations.
- Paint Producers:Industrial coating formulators requiring batch-to-batch consistency and regulatory dossier support for architectural applications.
- Plastics Industry:Masterbatch compounders integrating metal complex colorants into polymer systems for automotive interior and consumer durable applications.
Leather goods sits at the top of the value concentration ranking, with textile manufacturers gaining share fastest through channel consolidation.
Form:
Workplace exposure compliance costs and VOC regulations are accelerating format transitions across manufacturing geographies.
- Liquid:Water-based dispersions with sub-micron particle stability are overtaking solvent-borne systems in German and Czech automotive leather coating lines, eliminating thermal drying stages and reducing workplace exposure compliance costs.
- Powder:Standard solid format for bulk textile dyeing operations where dissolution equipment and dust containment infrastructure are established.
- Paste:Pre-dispersed concentrates for leather finishing applications requiring precise viscosity control and minimized batch variation.
- Granule:Low-dust handling format for automated dosing systems in high-volume textile processing facilities.
Powder remains the volume leader, with liquid formats expanding most quickly on regulatory substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium formulation demand for automotive leather applications, while India scales volume through export-oriented textile clusters serving international buyers.
Germany
Tier-1 automotive seating suppliers in Bavaria and Baden-Württemberg validate water-based metal complex dispersions for dashboard and upholstery specifications. ECHA's REACH substance evaluation accelerates trivalent chromium adoption across Northern Italian tannery supply chains serving German OEMs. Stuttgart-based leather finishing operations compress supplier bases through integrated digital color management platforms.
Italy
Luxury vehicle manufacturers in Piedmont and Lombardy expand procurement specifications for high-fastness chromium-cobalt complexes in interior applications. The EU Green Deal's expanding chemical hazard classifications drive pre-certification investments among compliant dye houses. Tuscan tannery clusters complete validation trials for low-VOC water-based systems eliminating thermal drying stages.
Turkey
Automotive upholstery manufacturers in Bursa and Istanbul scale metal complex dye consumption for European OEM supply contracts. The country's alignment with EU REACH frameworks through the Customs Union accelerates hexavalent chromium phase-out timelines. Izmir-based leather processing facilities adopt trivalent complex alternatives to maintain export market access.
India
Textile export houses in Surat and Tiruppur scale specialty metal complex consumption for international buyer durability specifications. BIS certification requirements for imported dye intermediates favor domestic manufacturers with established testing relationships. Gujarat-based dye houses capture import substitution opportunities as compliance costs rise for foreign suppliers.
United States
EPA restrictions on hexavalent chromium content in consumer-facing articles force reformulation toward trivalent complex alternatives across industrial coating applications. Automotive refinish segments in Michigan and Ohio require thermal stability specifications that metal complex chemistries satisfy. Southeast-based textile processors evaluate digital color management platforms to compress specification cycles.
Metal Complex Dyes Market Competitive Landscape
Top-tier vendors anchor premium leather finishing and automotive upholstery segments, while mid-scale dye houses compete on regulatory pre-certification speed and regional distribution density. Captive synthesis capabilities for chromium-cobalt complexes concentrate among integrated chemical majors, limiting toll manufacturing options for smaller competitors. Two strategic archetypes dominate: vertically integrated formulators controlling upstream metal complex production, and platform-integrated suppliers bundling digital color services with bulk pigment contracts. Capacity expansion in India and strategic partnerships for REACH dossier sharing represent the dominant competitive vectors.
Within the integrated chemical major tier, BASF SE and Clariant AG exemplify archetypes combining captive synthesis with distribution network control across European tannery clusters. Huntsman Corporation occupies a position representing the digital service convergence archetype, where shade prediction software subscriptions lock in multi-year textile mill relationships. These three entities illustrate how competitive positioning splits between upstream chemical control and downstream platform integration.
| Leading Market Players |
|---|
| Huntsman Corporation |
| BASF SE |
| Clariant AG |
| DyStar |
| Archroma |
| Suzhou Sunway Dyes & Chemicals |
| Kolor Jet Chemical |
| CHT Group |
| Rudolf GmbH |
| Others |
Value Network & Pricing Analysis
Chromium and cobalt feedstock costs originating from Kazakh mining operations and DRC extraction sites cascade through formulation pricing tiers, with trivalent complex alternatives commanding premium spreads over legacy hexavalent chemistries as REACH compliance deadlines compress substitution timelines.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade metal complex dyes, while European tanneries absorb premium-mid-economy pricing differentiation based on ECHA pre-certification status. Price differentiation separates REACH-compliant trivalent chromium formulations from legacy hexavalent alternatives, with certification grade and volume scale as primary drivers. Pricing pressure stems from reactive dye substitution in cotton-rich technical textiles, compressing margins in mid-tier segments. Small and mid-scale dye houses exhibit highest price sensitivity due to captive synthesis gaps, while integrated chemical majors with in-house metal complex production maintain pricing power.
Supply Chain Analysis
Dual-sourcing requirements from German and Italian automotive seating suppliers mandate multi-supplier qualification for chromium-cobalt complex feedstocks, forcing dye houses to maintain parallel relationships with BASF SE and Clariant AG alongside regional toll manufacturers. Geographic supply concentration centers on Germany, India, and China for finished formulations, with raw material dependencies on Kazakhstan for chromium and the DRC for cobalt. Single-source vulnerability in transition metal mining feeds commodity price volatility into formulation costs. Distribution runs through platform-integrated suppliers bundling digital color services with bulk pigment contracts in Surat and Tiruppur clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU REACH compliance costs and India's BIS certification localization creates geographic differentiation opportunities for formulation sourcing and captive synthesis investments.
For Market Incumbents: Extend captive synthesis capabilities for trivalent chromium complexes to preempt authorization listing consequences from ECHA substance evaluation. Deepen backward integration into cobalt feedstock sourcing to hedge DRC supply volatility. Lock in multi-year textile mill relationships through bundled shade prediction software subscriptions before platform consolidation completes. For New Entrants and Emerging Players: REACH in the European Union opens a window for pre-certified trivalent chromium alternatives as hexavalent phase-out accelerates across Northern Italian and Spanish tannery clusters. Target water-based dispersion formats for automotive leather coating lines in Germany and the Czech Republic where validation trials are completing. Pursue direct-to-mill digital platform integration in Surat and Tiruppur to bypass regional chemical traders. For Investors and Strategic Acquirers: Consolidation pressure builds where small and mid-scale dye houses lack captive synthesis capabilities and face steepest REACH compliance cost escalation. Five-to-ten year viability favors integrated formulators with upstream metal complex production and pre-submitted regulatory dossiers. Watch ECHA's cobalt salts evaluation timeline as inflection indicator for reformulation roadmap investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Complex Synthesis | Captive production of chromium-cobalt complexes insulates margin pressure from DRC and Kazakhstan feedstock volatility. |
| REACH Pre-Certification Investment | Early dossier submission accelerates customer approval timelines as ECHA substance evaluation tightens. |
| Digital Color Platform Integration | Shade prediction software subscriptions lock in multi-year textile mill relationships through bundled service layers. |
| Water-Based Dispersion Scale-Up | Low-VOC alternatives eliminate thermal drying stages in German and Czech automotive leather coating lines. |
| India BIS Certification Localization | Domestic testing relationships capture import substitution as compliance costs rise for foreign dye intermediate suppliers. |
Research Methodology
Bottom-up textile and leather end-use modeling reconciled against top-down metal complex dye production tracking forms the analytical core of this study. Primary interviews with tannery technical directors, textile mill procurement leads, automotive seating supplier quality managers, and dye house R&D heads combined with secondary validation from ECHA substance evaluation databases, REACH registration dossiers, Indian BIS certification records, and customs trade data. Top-down and bottom-up triangulation cross-checks volume assumptions against capacity utilization rates at major formulation facilities.
Input-output matrices map chromium and cobalt feedstock flows through captive synthesis and toll manufacturing channels across the projection horizon. Segmentation dimensions include formulation chemistry type, substrate compatibility, delivery format, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections across automotive leather, technical textiles, industrial coatings, and polymer masterbatch applications. Industry-specific forecast inputs incorporate REACH authorization timelines and BIS certification rollout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA cobalt reclassification acceleration or DRC supply disruption scenarios. Deviation in transition metal price volatility or multi-jurisdiction certification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Colorants Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Hair Colorants Market