
 Precious Metals Wire Market | 2026-2036
Precious Metals Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Precious Metals Wire Market Insights
Specialty metals distribution is fragmenting as regional traders and direct mill relationships displace traditional consolidated channels in precious metals wire procurement. Johnson Matthey PLC leverages its integrated refining-to-wire capabilities to control premium alloy specifications for aerospace and medical clients. Fresnillo plc anchors its position through captive silver concentrate supply that feeds downstream wire drawing operations in Mexico. Sibanye Stillwater competes on platinum group metal volumes, sustaining long-term offtake agreements with European automotive catalyst wire fabricators.
Precious metals wire consists of drawn filaments from gold, silver, platinum, or palladium, typically manufactured to diameters below 500 micrometers via multi-pass drawing with intermediate annealing to achieve precise conductivity, corrosion resistance, and biocompatibility parameters. Gold wire dominates bonding wire applications in semiconductor packaging where oxide-free surfaces and consistent elongation properties are critical. Platinum wire represents the fastest-growing product category as catheter ablation and neuromodulation device manufacturers specify higher noble metal content for implantable leads. Electronics applications command the deepest margin pools, particularly in high-frequency connectors and hermetic sealing where silver wire substitutes face reliability constraints.
REACH registration requirements in the European Union mandate full supply chain disclosure for imported precious metals wire, while the FDA enforces biocompatibility testing under ISO 10993 for medical-grade platinum and gold wire implants. China's GB standards for electrical contact materials and the EPA's hazardous waste tracking rules for spent catalyst recovery both shape regional competitive access. Stakeholders must monitor how dual carbon goals in Beijing and evolving EU critical raw materials lists recalibrate sourcing priorities for palladium and platinum feedstock.
Market Dynamics
Medical device manufacturers are consolidating platinum wire specifications for neuromodulation implants, forcing suppliers to certify purity traceability from mine to finished filament. This demand compression is restructuring procurement relationships and accelerating captive refining investments among wire fabricators.
Growth Catalysts
- ISO 10993 biocompatibility mandates:FDA enforcement of implant-grade testing protocols is expanding addressable demand for medical platinum wire in catheter ablation systems.
- Semiconductor packaging miniaturization:Die-shrink roadmaps in advanced logic chips are extending gold bonding wire specifications below 15 micrometer diameters.
- China's dual carbon targets:Domestic palladium recovery from spent automotive catalysts is redirecting secondary feedstock toward wire drawing operations in Jiangsu province.
Market Restraints
- Palladium price volatility:Automotive demand fluctuations and Russian supply uncertainty are compressing margin stability for catalyst wire fabricators.
- Concentrated primary supply:South African platinum group metal mining dominates feedstock availability, exposing downstream wire producers to concentrated geopolitical risk.
- Copper-silver composite substitution:High-frequency connector manufacturers are qualifying lower-noble-content alloys for non-hermetic applications.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic semiconductor packaging incentives are creating captive demand for gold bonding wire fabrication within the subcontinent.
- Neuromodulation device expansion:Spinal cord stimulation and deep brain therapy systems are specifying platinum-iridium wire for improved charge delivery longevity.
- EU Critical Raw Materials Act:Strategic stockpiling mandates for platinum group metals are generating preferential offtake terms for certified sustainable wire suppliers.
Industry Challenges
- Multi-stage annealing expertise:Precious metals wire drawing requires specialized thermal processing knowledge that is scarce in emerging fabrication hubs.
- REACH documentation timelines:Full supply chain disclosure requirements for imported wire are extending qualification cycles by 8-14 months for European medical device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precious Metals Wire Market |
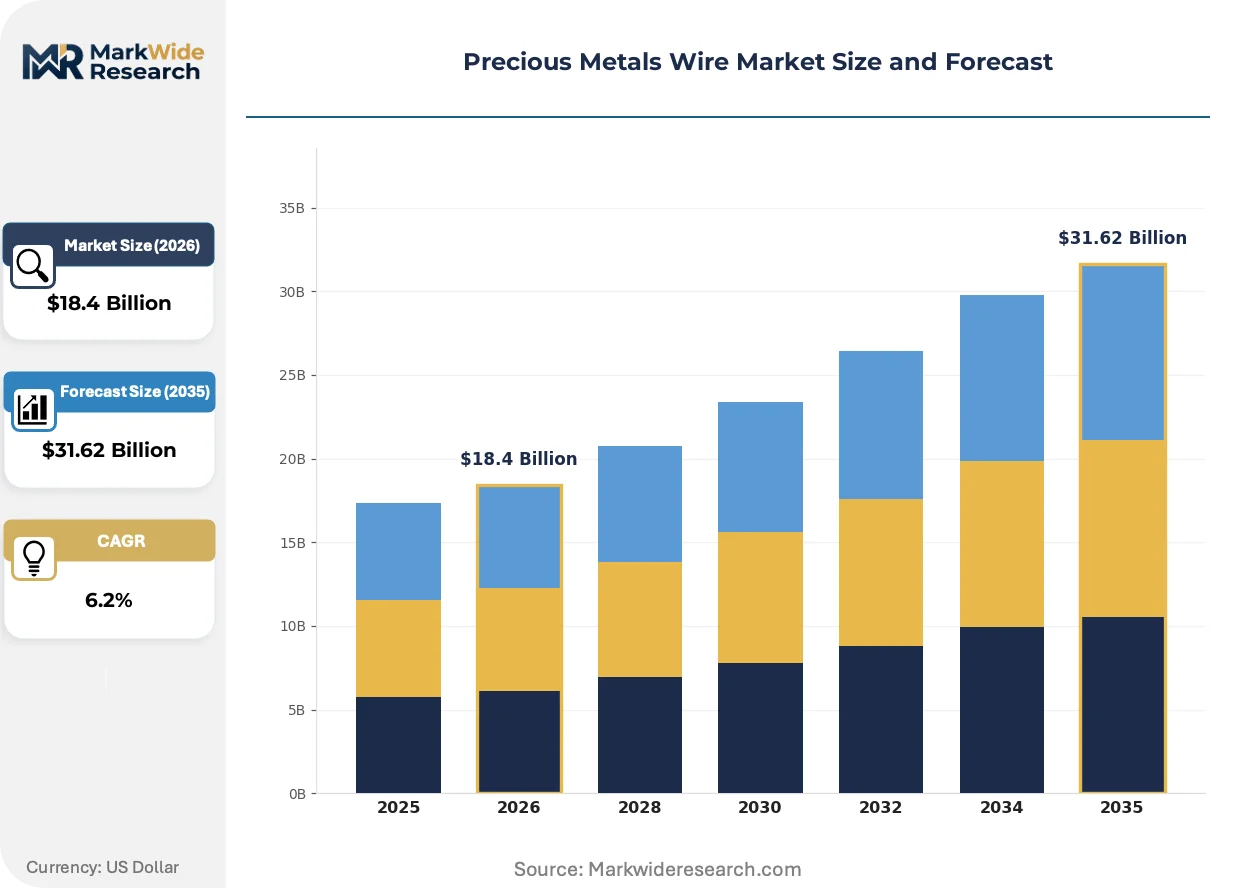
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold Wire, Silver Wire, Platinum Wire, Palladium Wire Application: Jewelry Manufacturing, Electronics, Aerospace Components, Medical Devices End User: Manufacturers, Retailers, Jewelers, Contractors Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Johnson Matthey PLC, Fresnillo plc, Sibanye Stillwater, Anglo American Platinum, Impala Platinum Holdings Limited, Pan American Silver Corp., Wheaton Precious Metals Corp., Newmont Corporation, Barrick Gold Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precious Metals Wire Market Trends and Innovations
Laser-assisted wire drawing and additive manufacturing of precious metal feedstock are compressing traditional process boundaries. These techniques are enabling geometries and alloy combinations that conventional multi-pass drawing cannot achieve.
Ultrafine laser-assisted drawing is collapsing the diameter threshold for platinum-iridium catheter wire. Boston Scientific and Medtronic procurement teams are qualifying 25-micrometer filaments for next-generation neuromodulation leads. This capability is collapsing the distinction between wire and thin-film deposition for implantable electrodes.
REACH registration deadlines are tightening supply chain documentation requirements for imported precious metals wire into the European Union. ECHA enforcement of full substance identity disclosure is disqualifying traders without smelter-level traceability. Medical device wire categories face the steepest compliance burden, with OEMs shifting toward vertically integrated suppliers holding certified refining assets.
Direct mill relationships are displacing traditional specialty metals distributors in high-specification wire procurement. Aerospace and medical OEMs are establishing long-term offtake agreements with Johnson Matthey and similar integrated producers, bypassing inventory-heavy traders. This pattern is most visible in Germany and Switzerland, where hermetic sealing and implantable device manufacturers prioritize certified provenance over spot market flexibility.
Precious Metals Wire Market Segmentation
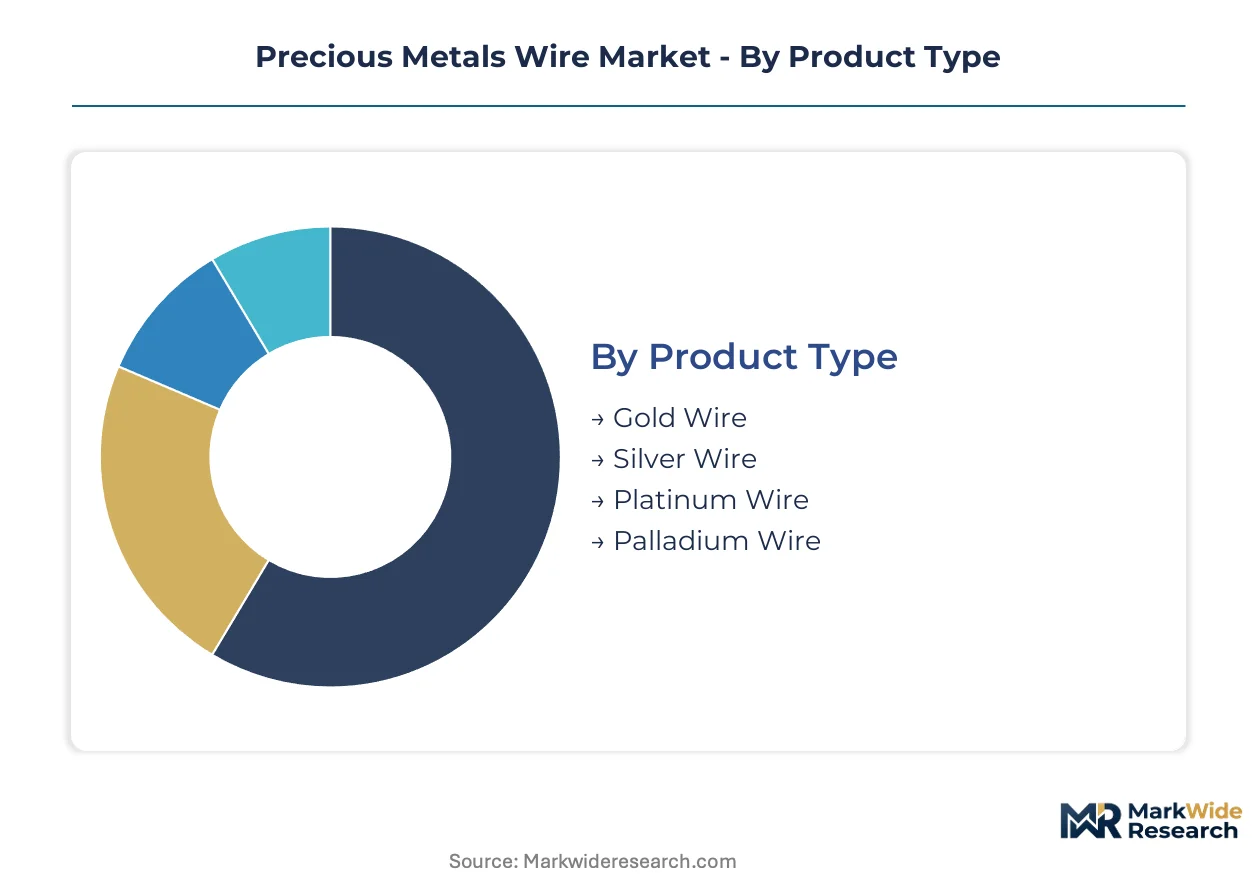
Precious metals wire segmentation reveals how technical specifications and purity requirements fragment procurement relationships across end-use industries. Each category shapes supplier qualification protocols and margin structures differently.
Product Type:
After-sales service intensity varies sharply by metal type, with medical-grade platinum requiring certified traceability support that gold bonding wire suppliers rarely match.
- Gold Wire:Drawn filaments with oxide-free surfaces serve semiconductor packaging where consistent elongation properties are critical. Die-shrink roadmaps in advanced logic chips are extending specifications below 15 micrometer diameters, compressing tolerance windows for wire bonders in Taiwan and South Korea.
- Platinum Wire:Noble metal content exceeding 99.95% purity enables catheter ablation and neuromodulation implant applications. Boston Scientific and Medtronic procurement teams are qualifying 25-micrometer filaments for next-generation leads, with FDA ISO 10993 biocompatibility mandates expanding addressable demand.
- Silver Wire:High-conductivity filaments dominate electrical contact materials under China's GB standards, though copper-silver composite substitution is pressuring non-hermetic applications.
- Palladium Wire:Automotive catalyst wire fabricators in Germany sustain long-term offtake agreements, but Russian supply uncertainty and price volatility are compressing margin stability.
Gold wire holds the largest share; momentum sits with platinum wire.
Application:
Cost tier stratification separates aerospace and medical applications commanding certified provenance premiums from jewelry manufacturing sensitive to spot price fluctuations.
- Electronics:Hermetic sealing and high-frequency connectors represent the deepest margin pools, particularly where silver wire substitutes face reliability constraints under FCC emission standards.
- Medical Devices:Implantable leads and catheter systems require full supply chain disclosure under REACH, with OEMs shifting toward vertically integrated suppliers holding certified refining assets.
- Jewelry Manufacturing:Spot market flexibility dominates procurement, with domestic fabrication scaling wire consumption in China.
- Aerospace Components:Long-term offtake agreements with integrated producers bypass inventory-heavy traders, prioritizing certified provenance in Germany and Switzerland.
Electronics holds the largest share; medical devices are expanding most quickly.
End User:
Volume concentration among medical device manufacturers is restructuring procurement relationships, while retailer demand fragments across spot market channels.
- Manufacturers:Medical device OEMs consolidate platinum wire specifications, forcing suppliers to certify purity traceability from mine to finished filament and accelerating captive refining investments.
- Jewelers:China's domestic jewelry production scales wire consumption with preference for traders offering mill-direct relationships.
- Retailers:Spot market flexibility prioritizes inventory turnover over certified provenance, concentrating in lower-specification silver and gold wire categories.
- Contractors:Project-based demand for electrical installation wire operates through wholesale channels with limited technical specification requirements.
Manufacturers hold the largest share; momentum sits with jewelers in China.
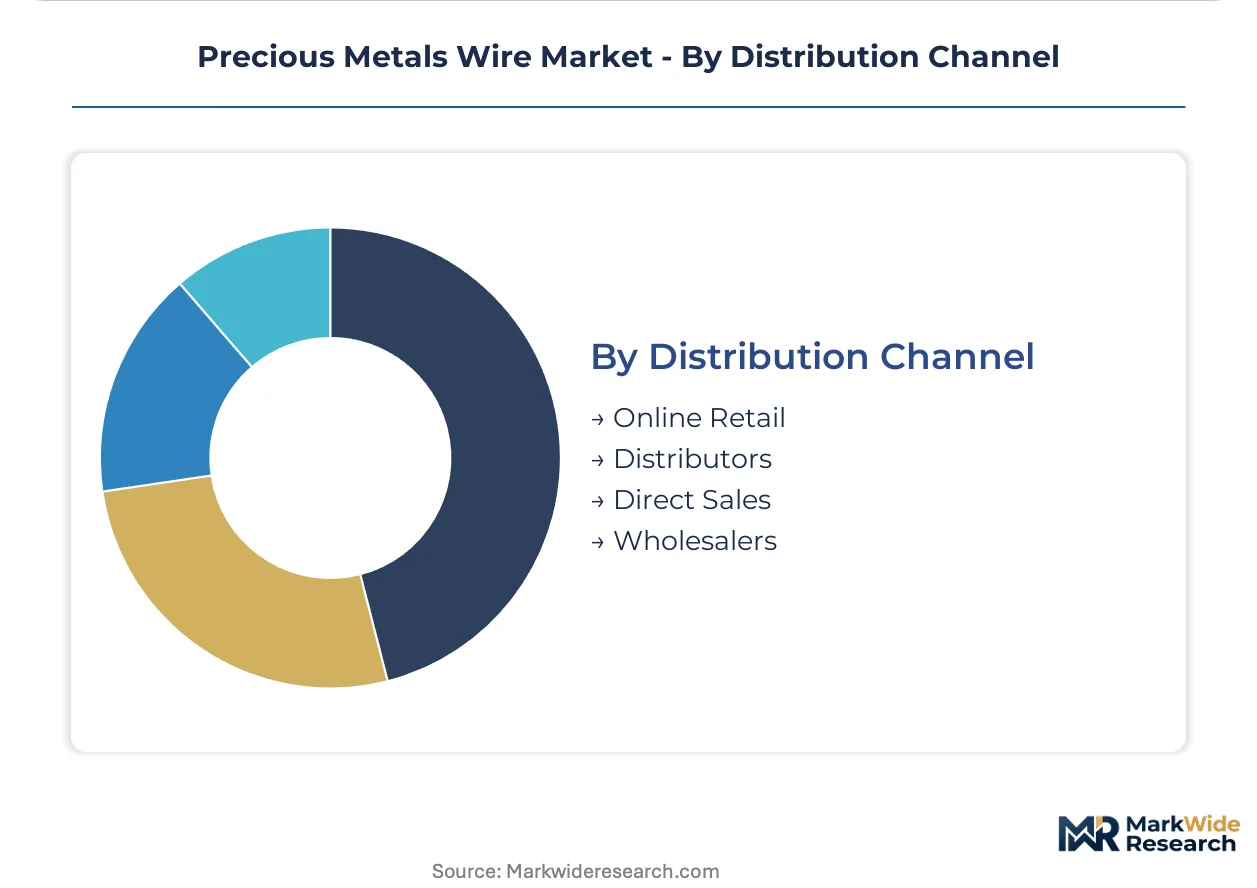
Distribution Channel:
Customer type fragmentation separates aerospace and medical OEMs demanding direct mill relationships from jewelry retailers tolerating inventory-heavy trader intermediaries.
- Direct Sales:Integrated producers like Johnson Matthey leverage refining-to-wire capabilities to control premium alloy specifications, bypassing distributors for aerospace and medical clients in Germany and Switzerland.
- Distributors:Traditional specialty metals channels face displacement as regional traders and direct mill relationships capture high-specification procurement.
- Online Retail:Spot market flexibility for lower-purity silver and gold wire serves jewelry manufacturing with limited traceability requirements.
- Wholesalers:Volume aggregation for electrical contact materials operates under China's GB standards with compressed documentation burdens.
Direct sales holds the largest share; distributors are losing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites European precious metals refining throughput, while the Yangtze River Delta's Shanghai-Ningbo port complex anchors Asia-Pacific wire fabrication volume.
China
Jiangsu province wire drawing operations scale palladium recovery from spent automotive catalysts under Beijing's dual carbon targets. MIIT's GB standards for electrical contact materials tighten purity specifications for silver wire used in domestic semiconductor packaging. The Suzhou-Wuxi corridor concentrates multi-pass drawing facilities serving medical device OEMs qualifying platinum-iridium filaments.
Germany
Hermetic sealing manufacturers in Baden-Württemberg sustain long-term offtake agreements with integrated platinum group metal refiners. ECHA's REACH enforcement mandates full supply chain disclosure for imported wire, disqualifying traders lacking smelter-level traceability. The Stuttgart industrial cluster hosts catheter ablation system fabricators specifying 25-micrometer platinum wire for neuromodulation leads.
United States
FDA's ISO 10993 biocompatibility mandates expand addressable demand for medical-grade platinum and gold wire implants. Boston Scientific and Medtronic procurement teams in Minnesota and Massachusetts qualify ultrafine filaments for next-generation neuromodulation systems. The EPA's hazardous waste tracking rules shape spent catalyst recovery economics for palladium feedstock.
Switzerland
Swissmedic's medical device regulations align with EU MDR requirements, creating dual-compliance pressure for implantable wire suppliers. The Zurich-Basel corridor concentrates aerospace hermetic sealing specialists prioritizing certified provenance over spot market flexibility. Johnson Matthey's integrated refining-to-wire capabilities serve this premium-tier demand through direct mill relationships.
South Africa
Platinum group metal mining concentration exposes downstream wire producers to concentrated geopolitical risk in the Bushveld Complex. Sibanye Stillwater's offtake agreements with European automotive catalyst wire fabricators sustain long-term volume commitments. The country's national mining regulator shapes export licensing timelines for refined feedstock.
Precious Metals Wire Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The precious metals wire market structures around integrated refiners with captive drawing capabilities, independent wire fabricators sourcing spot feedstock, and trading intermediaries facing displacement. Three archetypes dominate: vertically integrated precious metals conglomerates controlling mine-to-wire value chains; specialized wire drawing houses with annealing expertise; and regional distributors losing share to direct mill relationships. Competitive moves concentrate on backward integration into refining assets and long-term offtake contracting with medical device OEMs.
Among UK-based integrated producers, Johnson Matthey PLC exemplifies the refining-to-wire archetype through its control of premium alloy specifications. Fresnillo plc anchors the captive concentrate supply model, with its Mexican silver mining operations feeding downstream drawing operations. Sibanye Stillwater occupies a position on the platinum group metal volume vector, sustaining European automotive catalyst relationships. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| Johnson Matthey PLC |
| Fresnillo plc |
| Sibanye Stillwater |
| Anglo American Platinum |
| Impala Platinum Holdings Limited |
| Pan American Silver Corp. |
| Wheaton Precious Metals Corp. |
| Newmont Corporation |
| Barrick Gold Corporation |
| Others |
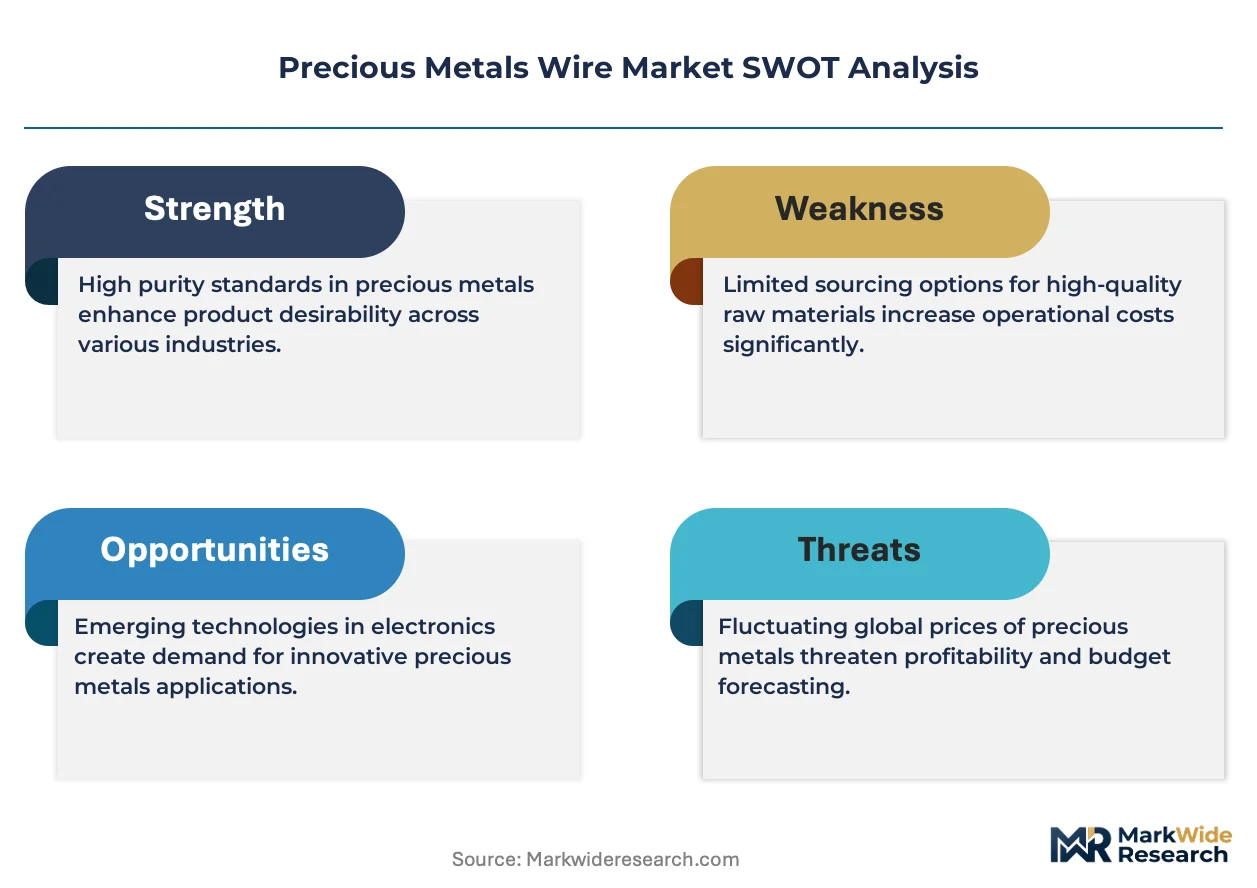
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp pipeline corridor shapes cost dynamics for European precious metals wire buyers, with freight differentials amplifying price spreads between integrated refiners and spot-market traders while REACH compliance burdens concentrate purchasing power among certified provenance suppliers.
Pricing Analysis
Volume-discount tiering structures separate aerospace and medical OEMs locking in long-term offtake agreements from jewelry manufacturers transacting on spot markets. Certification grade under ISO 10993 and REACH traceability tiers command substantial premiums over standard commercial purity. Pricing pressure stems from palladium feedstock volatility and Russian supply uncertainty compressing catalyst wire margins. Medical device manufacturers exhibit lowest price sensitivity due to regulatory-mandated provenance requirements, while jewelry fabricators prioritize spot flexibility.
Supply Chain Analysis
Export-control regimes on advanced refining technologies limit technology transfer to emerging wire fabrication hubs, constraining capacity expansion outside established corridors. Primary supply concentrates in South Africa, Russia, and Zimbabwe for platinum group metals, with secondary recovery scaling in China and Germany. Feedstock draws from Bushveld Complex mining, spent automotive catalyst recovery, and silver concentrate from Mexican operations. Single-source vulnerability runs through South African platinum mining concentration. Distribution runs through direct mill relationships displacing traditional specialty metals traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: ISO 10993 and REACH compliance create switching costs that lock medical device OEMs into qualified supplier relationships.
For Market Incumbents: Harden captive refining positions through backward integration into smelter assets in South Africa or Mexico, insulating against feedstock volatility while accelerating REACH documentation capabilities to capture European medical device procurement. Copper-silver composite substitution in non-hermetic electronics threatens margin pools; respond by deepening annealing expertise for ultrafine platinum-iridium specifications below 25 micrometers. For New Entrants and Emerging Players: Build out secondary palladium recovery operations in Jiangsu province serving domestic Chinese semiconductor packaging demand under MIIT's GB standards. India's PLI scheme for electronics manufacturing presents the most penetrable geography, with gold bonding wire fabrication for domestic packaging facilities offering qualified entry. Pursue hospital system partnerships with neuromodulation device OEMs seeking dual-source security for implantable lead supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with stranded wire drawing assets lacking medical-grade certification infrastructure. Long-term viability centers on platinum group metal exposure through the automotive electrification transition and medical implant expansion. Watch for EU Critical Raw Materials Act stockpiling mandates as inflection signal for preferential offtake terms.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Refining Investment | Backward integration into Bushveld Complex assets secures platinum feedstock for medical wire specifications. |
| REACH Certification Acceleration | Full supply chain documentation capabilities capture European medical device OEM procurement shifting from traders. |
| Ultrafine Drawing Capability | Laser-assisted 25-micrometer platinum-iridium production qualifies suppliers for Boston Scientific and Medtronic leads. |
| Secondary Feedstock Recovery | Palladium recovery from spent automotive catalysts in Jiangsu aligns with Beijing's dual carbon targets. |
| Direct Mill Relationship Expansion | Long-term offtake agreements with aerospace hermetic sealing manufacturers in Germany bypass distributor intermediaries. |
Research Methodology
The analysis maps gold bonding wire, platinum medical filaments, silver electrical contacts, and palladium catalyst wire segments, each validated through procurement directors at medical device OEMs, precious metals traders, wire drawing facility managers, and regulatory affairs specialists. Primary interviews with hospital purchasing committees and semiconductor packaging engineers combined with secondary validation from FDA 510(k) filings, ECHA REACH registration databases, MIIT GB standard publications, and SEC 10-K disclosures from integrated producers. Bottom-up fabrication capacity estimates triangulated against top-down end-use demand modeling.
Assumptions held fixed include REACH enforcement timelines, ISO 10993 biocompatibility mandate scope, and South African mining export licensing patterns; variables tested included palladium price volatility bands and Chinese dual carbon target implementation intensity. Segmentation dimensions modeled encompass metal type purity tiers, application-specific certification requirements, end-user procurement consolidation patterns, and distribution channel displacement trajectories. CAGRs derived from elasticity-adjusted demand projections across semiconductor packaging miniaturization roadmaps and neuromodulation device expansion curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed palladium recovery consortiums or sudden REACH documentation requirement suspensions would shift outcomes. Material shifts in South African platinum mining labor relations or EU Critical Raw Materials Act stockpiling implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Galvanized Steel Wire Market
Metals
Aluminum Slugs Market
Metals
Base Metals Market
Metals
Amorphous Metal Cores Market
Metals
Aluminum Ingots Market
Metals
Ferrite Market
Metals
Global Duplex Stainless Steel Market
Metals
Steel Long Products Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Copper and Copper Alloy Powder Market
Metals
Global Bronze Market
Metals
North America Aluminum Casting Market
Metals
HSLA Steel Plate Market
Metals
Metallurgical Silicon Market
Metals
Aluminum Sheet Market
Metals
Steel Sheet for Home Appliances Market