
 High Carbon Bearing Steel Market | 2026-2036
High Carbon Bearing Steel Market Size, Share, and Industry Trends Forecast 2026-2036
High Carbon Bearing Steel Market Foresight
Market Context
The split between vacuum-degassed premium grades and standard air-melted commodity grades is expanding as electric vehicle OEMs enforce sub-10ppm oxygen specifications for drivetrain bearings. SKF Group leverages its captive steelmaking through Ovako to sustain supply security for aerospace-qualified heats. Timken Company anchors North American demand through integrated steel-bar production in Canton, Ohio. China Baowu Steel Group Corp. Ltd. dominates tonnage supply across Asia with scale advantages in continuous casting of JIS SUJ2 equivalents.
Technical Definition and Segment Structure
High carbon bearing steel refers to hypereutectoid chromium-alloyed steels containing approximately 1% carbon and 1.5% chromium, engineered for through-hardening to 60-65 HRC and exceptional rolling-contact fatigue resistance in anti-friction bearings. Vacuum arc remelting or electroslag remelting eliminates macro-inclusions that initiate subsurface-initiated spalling in high-cycle applications. The grade dimension shows AISI 52100 maintaining volume leadership while JIS SUJ2 captures margin pools in Japanese and Korean automotive supply chains. The application dimension reveals bearings commanding the largest value share, with gears representing the fastest-expanding segment as wind turbine OEMs specify case-carburizable variants from the same melt source.
Regulatory Framework
China's SAMR enforces GB/T 18254 cleanliness standards that now align with SKF's internal MQ specifications, forcing domestic mills to adopt ladle furnace plus vacuum degassing sequences. The EU's F-Gas Regulation indirectly shapes bearing steel demand by accelerating magnetic bearing adoption in heat pumps, creating dual-grade sourcing requirements for hybrid mechanical-magnetic systems. Stakeholders must monitor evolving carbon border adjustment mechanisms as European bearing manufacturers evaluate Scope 3 emissions from Chinese and Indian steel suppliers.
Market Dynamics
The automotive electrification wave is compressing oxygen specifications for bearing steels from 15ppm to sub-10ppm thresholds, forcing mills to retool ladle metallurgy sequences and bifurcating the supply base into vacuum-capable and air-melted tiers.
Growth Catalysts
- EV drivetrain specifications:Electric vehicle OEMs mandate vacuum-degassed grades for motor bearings, pulling capacity upgrades across Asian and European melt shops.
- China's GB/T 18254 revisions:SAMR-mandated inclusion cleanliness alignment with SKF MQ specifications accelerates domestic ladle furnace investments.
- Wind turbine gear demand:Case-carburizable variants from bearing steel melt sources capture expanding orders from offshore wind OEMs.
Market Restraints
- Scrap cost volatility:Bearing steel production depends on high-grade ferrous scrap priced to volatile export flows from North American shredders.
- Chinese supply concentration:Jiangsu and Shandong provinces control 60%+ of Asian bearing steel tonnage, creating single-geography disruption exposure.
- Magnetic bearing substitution:EU F-Gas Regulation acceleration of magnetic bearing adoption in heat pumps displaces mechanical bearing demand in HVAC compressors.
Strategic Opportunities
- Indian bearing manufacturing:Underpenetrated domestic automotive and railway sectors offer white space for vacuum-degassed grade localization.
- Hybrid mechanical-magnetic systems:Dual-grade sourcing requirements emerge as OEMs combine magnetic levitation with mechanical backup bearings.
- Carbon border adjustment positioning:European mills with electric arc furnace routes can capture premium positioning ahead of EU CBAM implementation on imported steel.
Industry Challenges
- Vacuum metallurgy skill scarcity:Ladle furnace and degassing operation expertise concentrates in aging workforces at Japanese and European specialty mills.
- Aerospace certification timelines:AS9100 and customer-specific heat qualification cycles extend 18-24 months, freezing new entrant capacity from premium segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Carbon Bearing Steel Market |
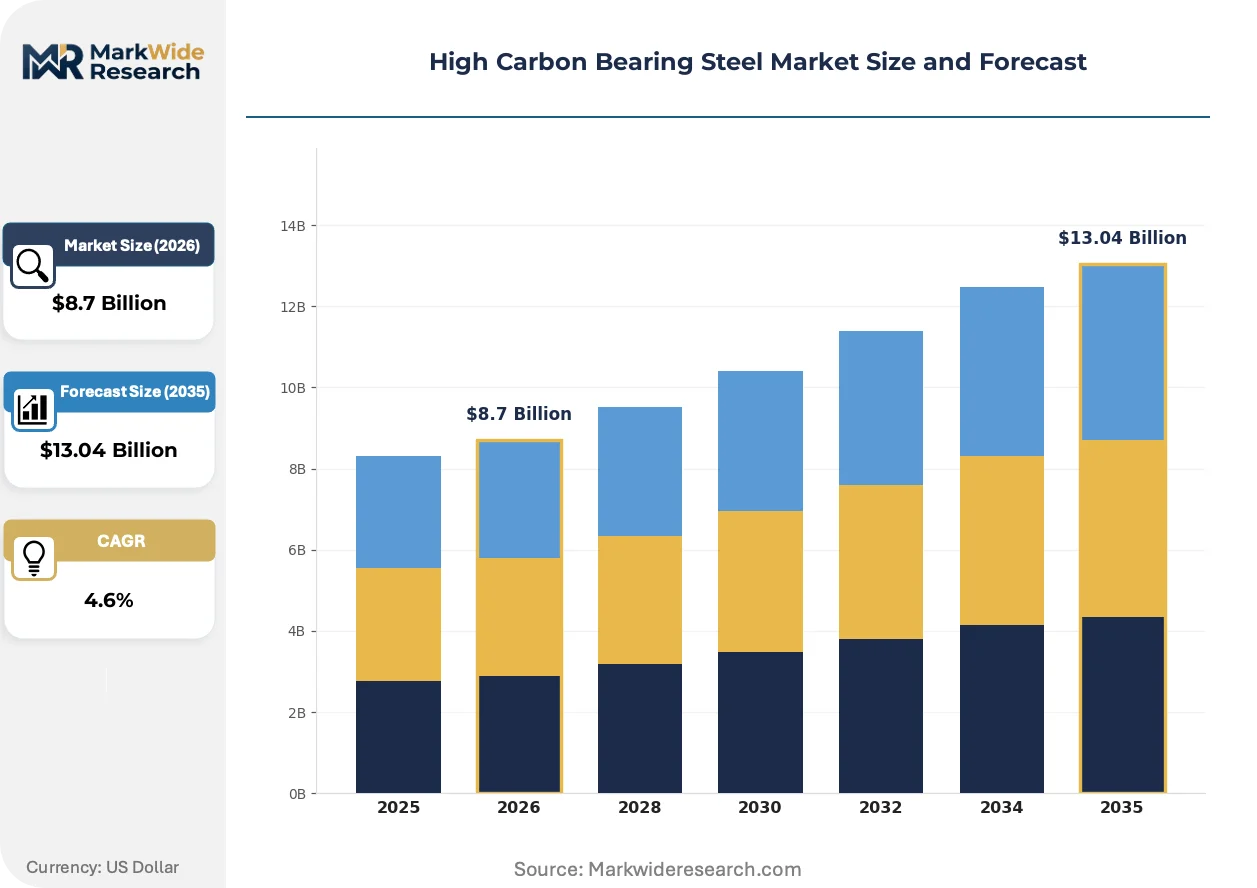
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive, Aerospace, Machinery, Heavy Equipment Grade: EN31, AISI 52100, JIS SUJ2, Oil Quenched Application: Bearings, Gears, Shafts, Rollers End User: OEMs, Aftermarket Providers, Industrial Manufacturers, Maintenance Units |
| Companies Covered | NTN Corporation, Timken Company, SKF Group, MinebeaMitsumi Inc., Nachi-Fujikoshi Corp., NSK Ltd., JTEKT Corporation, China Baowu Steel Group Corp. Ltd., Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Carbon Bearing Steel Market Shifts & Advancements
Digital melt control and predictive inclusion mapping are compressing the gap between commodity air-melted grades and premium vacuum-degassed offerings, reshaping how mills segment their product hierarchies.
Advanced ladle stirring with electromagnetic argon injection is converging with real-time ultrasonic inclusion detection to enable inline quality certification. Mid-tier mills in China and India adopt these hybrid systems to bridge the vacuum-capability gap without full VIM/VAR investment. The technology is converging with traditional continuous casting to produce near-premium grades at 40% lower capital intensity.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants accelerates magnetic bearing penetration in heat pump compressors. Mechanical bearing OEMs respond by specifying hybrid designs requiring both case-carburizable gear steel and through-hardened bearing grades from unified melt sources. German and Italian heat pump manufacturers now dual-source mechanical and magnetic bearing suppliers to hedge technology transition risk.
Automotive OEMs consolidate bearing procurement through single-source frame contracts with mill-direct supply, bypassing traditional distributor channels. Tier-1 suppliers in Germany, Japan, and South Korea negotiate annual volume commitments with steelmakers for qualified heats with locked chemistry ranges. This concentration is most visible in electric drivetrain programs where sub-10ppm oxygen specifications eliminate spot-market sourcing flexibility entirely.
High Carbon Bearing Steel Market Segmentation
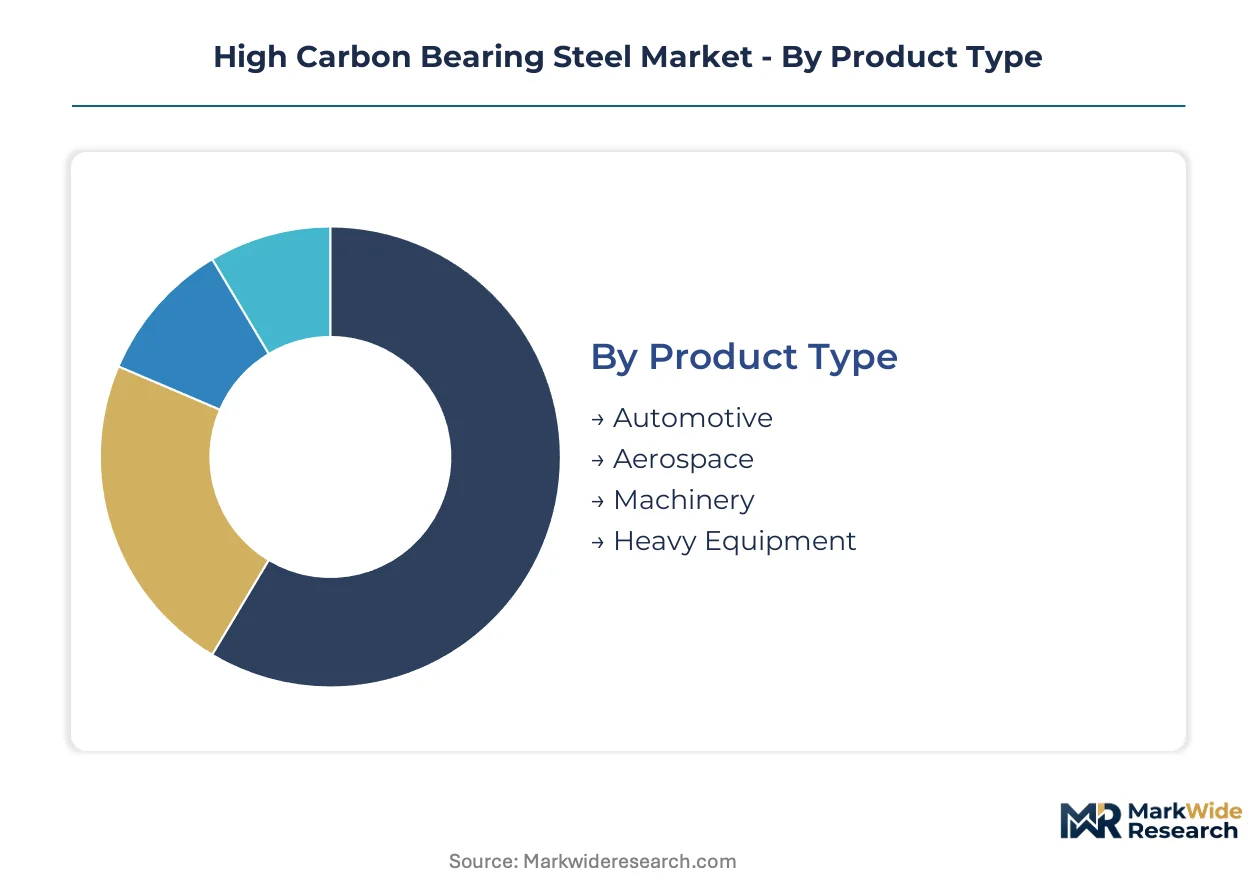
Segmentation in high carbon bearing steel reveals how specification tiers fragment procurement power across end-use industries. Grade purity requirements diverge sharply between electric drivetrain OEMs and commodity machinery rebuilders, reshaping how mills allocate vacuum-capable capacity.
Product Type:
Supply concentration among vacuum-degassed producers tilts negotiating leverage toward automotive and aerospace buyers who lock multi-year heats.
- Automotive:Electric drivetrain OEMs enforce sub-10ppm oxygen specifications for motor and gearbox bearings, forcing dedicated ladle metallurgy sequences at qualified mills. Procurement concentrates in Jiangsu and Shandong province clusters serving domestic EV production and Korean export programs.
- Aerospace:AS9100-certified heats require vacuum arc remelting or electroslag remelting to eliminate macro-inclusions that trigger subsurface spalling in high-cycle landing gear and engine applications. SKF's Ovako captive supply and Timken's Canton facility anchor qualified North American and European capacity.
- Machinery:Standard air-melted grades satisfy general industrial bearing replacement cycles with less stringent inclusion controls.
- Heavy Equipment:Mining and construction OEMs prioritize through-hardened durability over vacuum processing for large-bore slewing bearings.
Today's leader: Automotive. Tomorrow's challenger: Aerospace.
Grade:
Cost tier stratification separates premium vacuum-refined grades from commodity continuous-cast offerings, with chemistry-locked contracts commanding 40% mill-direct premiums.
- EN31:British Standard hypereutectoid chromium alloy with 1% carbon content serves legacy industrial machinery and aftermarket rebuild markets. Demand clusters in Indian bearing manufacturing hubs where BIS certification aligns with export machinery specifications.
- AISI 52100:North American volume leader specified for through-hardening to 62-65 HRC in anti-friction bearings. Timken's integrated Canton steel-bar production and Chinese continuous-cast equivalents compete on oxygen specification tiers rather than base chemistry.
- JIS SUJ2:Japanese Industrial Standard variant dominates Korean and Southeast Asian automotive supply chains with SKF MQ-equivalent cleanliness protocols.
- Oil Quenched:Distortion-controlled processing variant specified for large-section bearings where water quenching risks cracking.
Volume concentration: AISI 52100. Margin expansion: JIS SUJ2.
Application:
Application-driven metallurgy requirements determine whether mills route heats through vacuum degassing or standard ladle treatment.
- Bearings:Rolling-contact fatigue resistance demands controlled carbide distribution and inclusion cleanliness below 15ppm oxygen for standard grades, sub-10ppm for EV motor applications. Wind turbine main shaft bearings now specify case-carburizable variants from bearing steel melt sources.
- Gears:Case-carburizable processing from unified bearing steel heats captures fastest-expanding demand from offshore wind OEMs specifying surface hardness gradients with core toughness.
- Shafts:Through-hardened or induction-hardened variants serve power transmission with less stringent inclusion controls than rolling-element applications.
- Rollers:Cylindrical and spherical roller specifications prioritize dimensional stability over vacuum processing for non-critical machinery segments.
Core revenue pool: Bearings. Steepest expansion trajectory: Gears.
End User:
Customer type determines contract structure, with OEM frame agreements displacing spot-market flexibility for qualified heats.
- OEMs:Automotive and wind turbine manufacturers negotiate annual volume commitments with locked chemistry ranges, bypassing traditional distributor channels entirely for electric drivetrain programs.
- Aftermarket Providers:Distributor networks source mixed-grade inventories from spot markets, accepting wider oxygen specification bands for industrial machinery rebuild applications.
- Industrial Manufacturers:Bearing OEMs in Germany, Japan, and South Korea dual-source mechanical and magnetic bearing suppliers to hedge EU F-Gas Regulation transition risks.
- Maintenance Units:Railway and heavy equipment rebuild operations prioritize availability over vacuum certification for non-critical replacement cycles.
Contract power: OEMs. Volume flexibility: Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgy workforces cluster in Germany's Ruhr Valley, Japan's Chubu region, and China's Jiangsu province, anchoring the three dominant supply basins for vacuum-degassed bearing grades.
China
Domestic EV manufacturers BYD and NIO source sub-10ppm oxygen specifications for drivetrain bearings from mills in Jiangsu and Shandong provinces. SAMR's GB/T 18254 revisions force ladle furnace upgrades across Baowu Steel and regional specialty producers. Xuzhou's bearing manufacturing cluster now supplies qualified heats for both domestic automotive programs and Korean export contracts.
Germany
Schaeffler and SKF operations in Bavaria and Baden-Württemberg specify vacuum-degassed grades for European EV drivetrain programs. The EU's F-Gas Regulation accelerates magnetic bearing adoption in heat pumps, creating dual-grade sourcing requirements for hybrid mechanical-magnetic systems. Dortmund's specialty steel corridor maintains electroslag remelting capacity for aerospace-qualified heats.
Japan
NSK, JTEKT, and Nachi-Fujikoshi anchor demand for JIS SUJ2 variants with SKF MQ-equivalent cleanliness protocols. METI's carbon neutrality roadmaps pressure mills to adopt hydrogen-reduction pilot programs for bearing steel production. Nagoya's Chubu steel basin concentrates vacuum arc remelting expertise for automotive and precision machinery applications.
United States
Timken's integrated Canton, Ohio facility produces AISI 52100 steel bars for North American automotive and aerospace programs. NHTSA fuel economy standards indirectly shape bearing specifications through drivetrain efficiency requirements. Ohio's Mahoning Valley steel corridor retains specialized workforce capacity for vacuum degassing operations.
India
Underpenetrated domestic automotive and railway sectors offer expansion vectors for vacuum-degassed grade localization. BIS certification requirements for EN31 bearing steel align with export machinery specifications. Pune and Chennai manufacturing clusters develop sourcing relationships with specialty mills for qualified heats.
High Carbon Bearing Steel Market Competitive Landscape
Top-tier vendors anchor vacuum-capable supply, while air-melted commodity producers serve industrial replacement cycles. The market structure splits between integrated steelmakers with captive bearing operations and independent specialty mills. Three archetypes dominate: Japanese precision specialists, Chinese scale-driven producers, and European quality-focused integrated players. Competitive moves concentrate on ladle metallurgy upgrades and multi-year OEM frame contracts that lock chemistry ranges.
Within the integrated-tier archetype, Timken Company and SKF Group exemplify backward control over steel-bar production. China Baowu Steel Group Corp. Ltd. occupies the scale-driven position across Asian tonnage supply. These three entities represent the spectrum from North American vertical integration to European quality certification to Chinese continuous-casting scale.
| Leading Market Players |
|---|
| NTN Corporation |
| Timken Company |
| SKF Group |
| MinebeaMitsumi Inc. |
| Nachi-Fujikoshi Corp. |
| NSK Ltd. |
| JTEKT Corporation |
| China Baowu Steel Group Corp. Ltd. |
| Schaeffler Group |
| Others |
Supply & Pricing Matrix
High-grade ferrous scrap prices from North American shredders feed directly into vacuum-degassed grade premiums, transmitting volatility from commodity markets through to mill-direct contract negotiations with automotive OEMs. This input-cost channel splits procurement into chemistry-locked long-term agreements for qualified heats versus spot-market flexibility for standard grades.
Pricing Analysis
Mill-direct contracts bundle vacuum-degassed steel bars with locked oxygen specifications and certified heat traceability, while distributor channels unbundle standard grades with wider chemistry bands. Price differentiation hinges on SKF MQ-equivalent cleanliness certification and annual volume commitment scale, with sub-10ppm oxygen thresholds commanding substantial premiums over air-melted alternatives. Pricing pressure stems from Chinese continuous-casting scale advantages compressing margins on JIS SUJ2 equivalents. Aftermarket rebuilders exhibit highest price sensitivity, whereas EV drivetrain OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Specialized ladle furnace operators in Germany's Ruhr Valley, Japan's Chubu region, and China's Jiangsu province anchor vacuum-metallurgy capacity for premium grade production. Raw material sourcing draws from high-grade ferrous scrap flows, chromium alloy additions, and ladle refractories subject to export restrictions. Single-geography concentration in Jiangsu and Shandong provinces creates disruption exposure from regional logistics constraints or SAMR enforcement actions. Distribution runs through integrated steel-bar production facilities for OEM frame contracts, with independent specialty mills serving spot-market distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High carbon bearing steel functions as a stable compounder anchored by irreplaceable material specifications in rolling-contact fatigue applications across electrified drivetrains and precision machinery. Automotive electrification mandates create durable demand pull for vacuum-capable capacity.
For Market Incumbents: To counter Chinese scale-driven compression on JIS SUJ2 equivalents, defend premium positioning through AS9100-certified heat qualification investments and captive ladle metallurgy upgrades in Canton or Dortmund corridors. Lock multi-year frame contracts with EV drivetrain OEMs to freeze out spot-market competitors from qualified supply pools.
For New Entrants and Emerging Players: Indian railway maintenance units represent an underserved buyer archetype demanding vacuum-degassed grade localization without existing mill-direct relationships. Target Pune and Chennai manufacturing clusters with BIS-certified EN31 variants and technical service partnerships to bridge certification gaps.
For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum arc remelting expertise concentrates in aging workforces at Japanese and European specialty mills. Long-term viability favors integrated players with backward steelmaking control and OEM qualification depth. Watch SAMR enforcement intensity on GB/T 18254 compliance as inflection signal for Chinese domestic capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Ladle Metallurgy Upgrade | Vacuum degassing adoption aligns mill output with SKF MQ specifications for EV bearing contracts. |
| AS9100 Heat Qualification | Aerospace certification opens premium segments with 18-24 month entry barriers for competitors. |
| Backward Steelmaking Integration | Captive bar production secures chemistry control and eliminates distributor margin extraction. |
| Indian Localization Partnership | BIS-certified EN31 supply captures railway and automotive white space in underpenetrated regions. |
| Hybrid Bearing Steel Development | Dual-grade sourcing for mechanical-magnetic systems hedges EU F-Gas Regulation displacement risk. |
Research Methodology
Bottom-up automotive and wind turbine demand modeling reconciled against top-down melt shop capacity tracking forms the analytical core of this study. Primary interviews with ladle furnace operators, bearing OEM procurement directors, and SAMR regulatory specialists combined with secondary validation from SEC filings, customs trade data, and JIS/GB standard documentation. Steel industry association reports and EAF production disclosures provided supply-side triangulation against end-use consumption patterns.
Input-output matrices map vacuum-degassed grade allocation across EV drivetrain, aerospace, and industrial machinery segments throughout the projection horizon. Segmentation dimensions include oxygen specification tier, grade variant, application type, and end-user contract structure. CAGRs derive from rolling-contact fatigue demand elasticity and ladle metallurgy capacity expansion trajectories. Forecast inputs incorporate SAMR enforcement timelines on GB/T 18254 revisions and EU F-Gas Regulation phasedown schedules.
Underlying measurement precision varies by segment; vacuum-degassed automotive grades carry tighter precision than air-melted industrial replacement categories due to visible OEM contract data. Forecasts reflect documented assumptions on scrap cost trajectories and certification timeline stability. Material deviation in SAMR enforcement intensity or magnetic bearing substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Electrolytic Iron Market
Metals
Global Titanium Metal Market
Metals
GCC Aluminium Cans Market
Metals
Rolled Steel Motor Market
Metals
Nickel Market
Metals
Nickel Oxide Target Market
Metals
Vietnam Aluminum Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Chrome Metal Powder Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Europe Metal Casting Market
Metals
North America Aluminium Powder Market
Metals
Expanded Metal Foils Market
Metals
Lanthanum Market
Metals
Battery Metals Market
Metals
Smelting Chemicals Market