
 Australia Dead Sea Mud Cosmetics Market | 2026-2036
Australia Dead Sea Mud Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Dead Sea Mud Cosmetics Market Insights
Premium mineral-grade formulations is reorganizing the Australia Dead Sea Mud Cosmetics Market as consumers prioritize authenticated Dead Sea sourcing claims. Ahava Dead Sea Laboratories leverages its vertically integrated supply chain from the Dead Sea basin to maintain batch consistency. Lush Retail Ltd differentiates through ethical sourcing narratives and in-store product education. Kawar Cosmetics anchors its position via therapeutic-grade positioning aligned with Australian spa professional channels.
Dead Sea mud cosmetics comprise topical preparations formulated with mineral-rich sediment harvested from the Dead Sea, typically containing magnesium, calcium, potassium, and bromide compounds in concentrations exceeding standard marine clays, designed for dermal detoxification, exfoliation, and moisture retention. Facial masks command the dominant margin pool due to higher per-unit pricing and repeat purchase frequency among individual consumers. Spa treatments represent the fastest-growing application segment as Australian wellness centers integrate Dead Sea protocols into premium service menus. Online retailers increasingly capture volume from regional consumers beyond Melbourne and Sydney metro corridors.
TGA cosmetic ingredient regulations govern safety substantiation and labeling requirements for mineral-based topical products entering the Australian market. The ACCC monitors misleading therapeutic claims, compelling brands to distinguish between cosmetic and medical positioning. ISO 16128 natural origin standards shape formulation transparency expectations among ingredient-conscious buyers. Stakeholders must track evolving state-level environmental assessments for imported mineral raw materials.
Market Dynamics
TGA cosmetic ingredient regulations are compressing formulation timelines while authenticated Dead Sea sourcing claims command price premiums, forcing brands to restructure supply chain documentation and mineral traceability protocols.
Growth Catalysts
- ISO 16128 natural origin standards:Australian ingredient-conscious buyers now demand batch-level transparency, compelling brands to invest in mineral authentication technologies and third-party certification.
- Professional spa channels:New South Wales and Victoria wellness centers are integrating Dead Sea protocols into premium service menus, creating recurring B2B demand for therapeutic-grade formulations.
- Clean-label mineral extraction:Advancements in low-impact harvesting methods from the Dead Sea basin are reducing environmental compliance costs and accelerating product registration timelines with Australian regulators.
Market Restraints
- Dead Sea basin supply concentration:Mineral sediment harvesting remains geographically captive to Jordan and Israel, exposing Australian importers to geopolitical logistics disruptions and currency volatility.
- ACCC therapeutic claim enforcement:The regulator's strict distinction between cosmetic and medical positioning limits marketing language and compresses allowable efficacy messaging.
- Marine clay substitutes:Bentonite and kaolin formulations from domestic Australian sources offer lower landed costs for price-sensitive consumers in regional markets.
Strategic Opportunities
- Queensland and Western Australia regional expansion:Online retailers are capturing volume from consumers beyond Melbourne and Sydney metro corridors, reducing channel concentration risk.
- Men's grooming application pivot:Male-specific Dead Sea mud cleansers and beard masks represent an underdeveloped segment with minimal dedicated SKUs from incumbent brands.
- TGA streamlined cosmetic notification:Recent regulatory pathway simplifications for mineral-based topicals are reducing time-to-market for innovative formulations.
Industry Challenges
- Mineral authentication chemist talent scarcity:Specialized expertise in Dead Sea mineral fingerprinting and isotopic analysis is concentrated among a handful of Australian contract laboratories.
- State-level environmental assessment fragmentation:Imported mineral raw materials face inconsistent clearance protocols across New South Wales, Victoria, and Queensland biosecurity frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Dead Sea Mud Cosmetics Market |
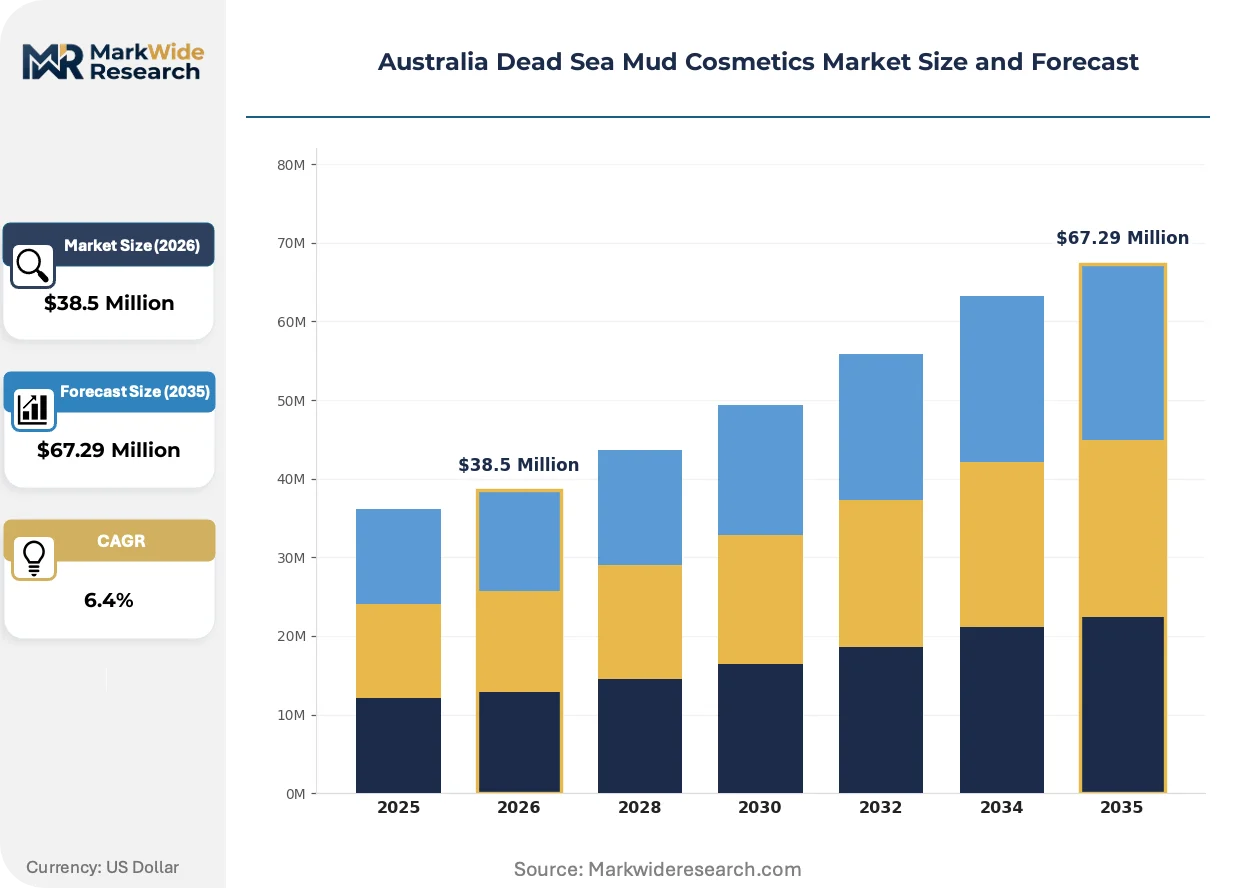
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $67.29 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Masks, Body Scrubs, Cleansers, Moisturizers Application: Skincare, Haircare, Spa Treatments, Therapeutic Use End User: Individuals, Therapists, Salons, Spa Centers Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Ahava Dead Sea Laboratories, Kawar Cosmetics, Aroma Dead Sea, SABON, AVANI Supreme Inc, Lush Retail Ltd, Asutra, H&B Health and Beauty, Biscol Investments Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Dead Sea Mud Cosmetics Market Trends and Innovations
Formulation science and regulatory transparency are converging to reshape how Dead Sea mud products reach Australian consumers, with traceability technologies and channel restructuring dominating capital allocation decisions.
Blockchain-enabled mineral provenance tracking is supplanting paper-based chain-of-custody documentation among premium Australian brands. Sydney and Melbourne headquartered companies are adopting distributed ledger systems to verify Dead Sea basin extraction batches. This technology is compressing competitor differentiation cycles and raising barriers for brands lacking authenticated sourcing narratives.
TGA cosmetic ingredient safety substantiation requirements are tightening labeling precision for magnesium, calcium, and bromide concentration disclosures. The regulation is forcing reformulation of legacy products and accelerating investment in third-party analytical testing. Professional spa channels face the steepest compliance adaptation costs due to bulk treatment protocol standardization needs.
Direct-to-consumer subscription models are disrupting traditional pharmacy and department store distribution for facial mask repeat purchases. Australian millennials in urban centers are shifting toward automated replenishment services with personalized skin-type matching. This behavioral pivot is most pronounced in Victoria, where digital-native brands are capturing trial-to-loyalty conversion at higher rates than conventional retail.
Australia Dead Sea Mud Cosmetics Market Segmentation
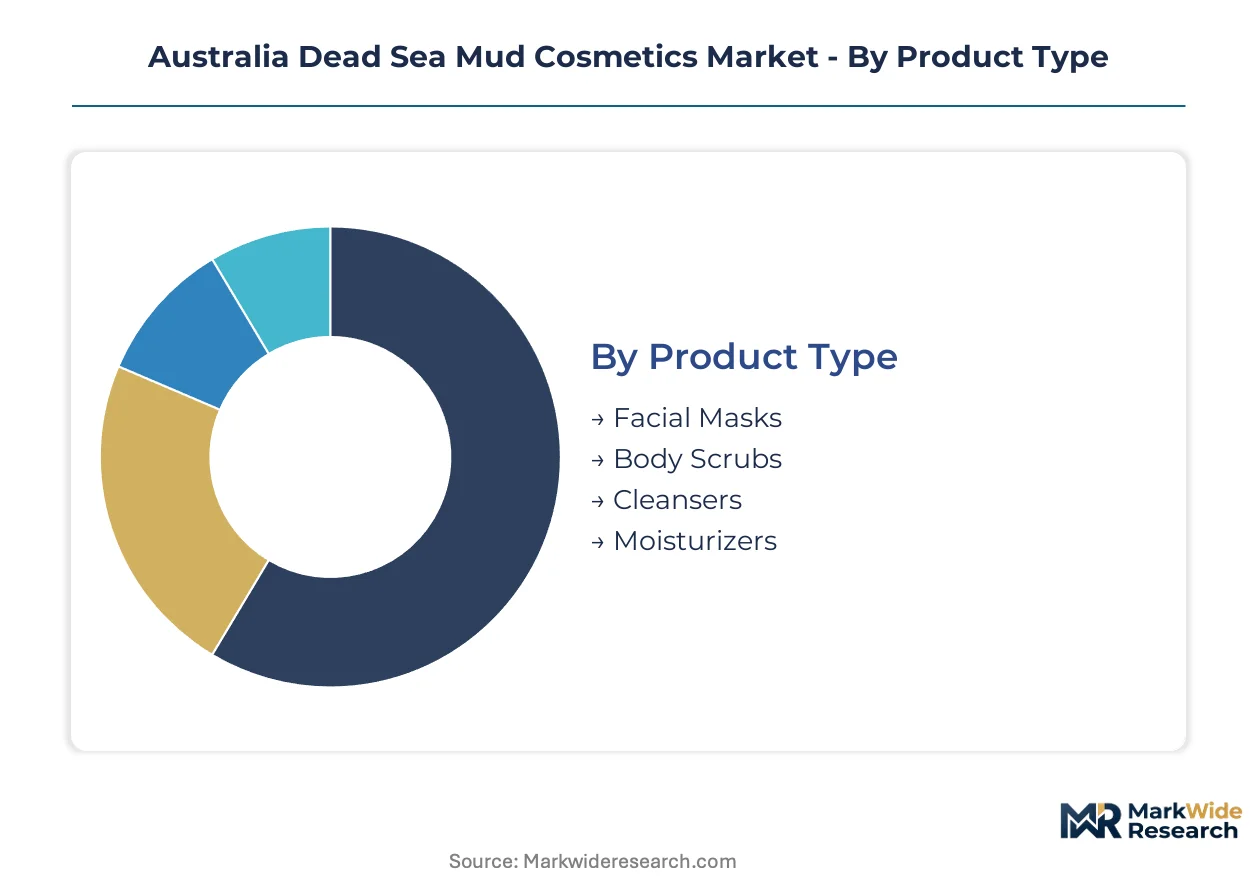
Segmentation in the Australia Dead Sea Mud Cosmetics Market reveals distinct margin architectures across product formats and channel structures. Therapeutic positioning and professional service integration create pricing power variations that reshape competitive strategy for mineral-based formulations.
Product Type:
Margin pools concentrate in treatment-intensive formats where mineral concentration and application time justify premium positioning. Facial masks capture the highest per-unit economics due to repeat purchase frequency and authenticated sourcing narratives.
- Facial Masks:Concentrated mineral formulations designed for dermal detoxification and exfoliation, typically containing elevated magnesium and calcium compounds. Demand clusters among urban millennials in Sydney and Melbourne who prioritize authenticated Dead Sea sourcing claims and subscription replenishment models.
- Body Scrubs:Coarse-grain sediment preparations blended with carrier oils for full-body exfoliation protocols. Spa centers across New South Wales and Victoria drive volume through premium service menu integration, though per-unit pricing trails facial treatments.
- Cleansers:Lower-viscosity daily-use formulations with reduced mineral load for routine skin maintenance. Price-sensitive consumers in regional Queensland markets favor these entry-level formats.
- Moisturizers:Emulsion-based products combining Dead Sea minerals with humectant compounds for post-treatment hydration. Limited SKU availability from incumbent brands constrains segment development.
The dominant share belongs to Facial Masks, while Body Scrubs are expanding most quickly through professional channel adoption.
Application:
Volume distribution across applications reflects the tension between individual consumption rituals and institutional service protocols. Therapeutic positioning commands regulatory scrutiny but enables pricing premiums unavailable to cosmetic-only claims.
- Skincare:Broad consumer-facing category encompassing daily cleansing, masking, and moisturizing routines. Individual purchasers in Melbourne and Sydney metro corridors sustain the volume base through direct-to-consumer and specialty retail channels.
- Spa Treatments:Professional service applications including full-body mud wraps and hydrotherapy protocols. Wellness centers across Victoria and New South Wales are integrating Dead Sea protocols into premium service menus, creating recurring B2B demand for bulk therapeutic-grade formulations.
- Haircare:Scalp treatment and mineral-enriched shampoo applications with limited market penetration. Few dedicated SKUs from established brands constrain segment visibility.
- Therapeutic Use:Positioning aligned with dermatological or wellness outcomes requiring TGA compliance rigor. ACCC enforcement of cosmetic-medical claim boundaries limits marketing language and compresses allowable efficacy messaging.
Skincare retains the largest volume position, yet Spa Treatments demonstrate the steepest expansion trajectory as professional channels scale.
End User:
Procurement patterns diverge sharply between individual buyers seeking authenticated sourcing and institutional purchasers prioritizing bulk consistency and protocol standardization.
- Individuals:Direct consumers purchasing for personal use through retail and digital channels. Australian millennials demonstrate elevated trial-to-loyalty conversion when mineral provenance documentation is transparent.
- Spa Centers:Institutional buyers integrating Dead Sea treatments into service menus. These operators demand batch consistency and bulk pricing structures that reshape supplier relationship dynamics.
- Therapists:Licensed practitioners prescribing treatments in clinical or wellness contexts. TGA cosmetic notification requirements influence procurement criteria and product selection.
- Salons:Beauty service providers with narrower treatment focus than full-service spa centers. Price sensitivity runs higher due to compressed service margins.
Individuals command the greatest absolute volume, though Spa Centers are gaining share fastest through professional channel consolidation.
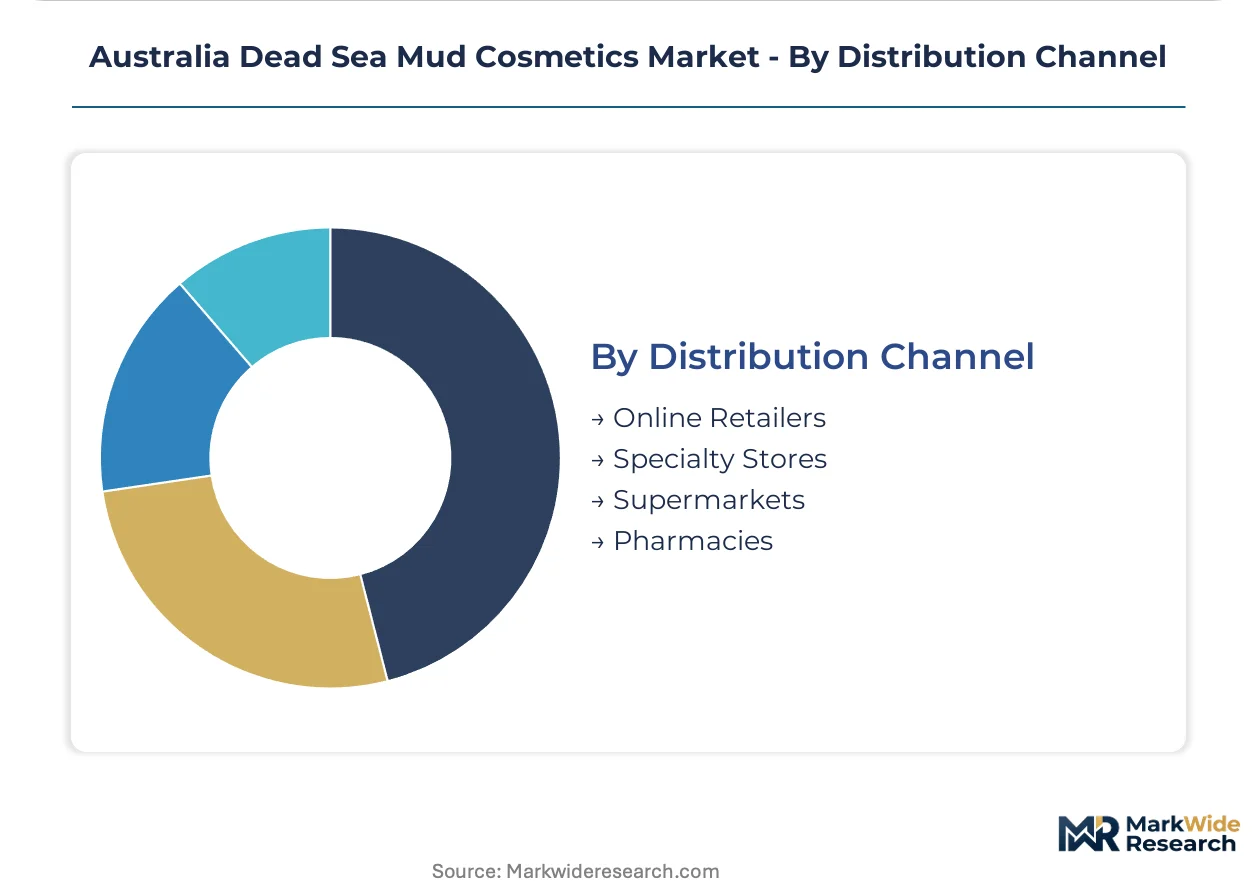
Distribution Channel:
Channel economics reflect the geographic dispersion of demand beyond Melbourne and Sydney corridors and the operational cost structures of mineral authentication.
- Online Retailers:Digital-native platforms capturing volume from regional consumers beyond metro corridors. Subscription models and personalized skin-type matching drive repeat purchase economics in Victoria.
- Specialty Stores:Beauty-focused retailers with in-store product education capabilities. Lush Retail Ltd and comparable operators leverage ethical sourcing narratives to justify premium positioning.
- Pharmacies:Regulated retail environments where TGA compliance signals credibility. Therapeutic-grade formulations achieve placement advantages in this channel.
- Supermarkets:Mass-market retail with limited SKU depth and compressed margins. Domestic marine clay substitutes compete aggressively on landed cost.
Online Retailers hold the dominant position, while Specialty Stores are climbing the fastest through experiential retail investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel and Jordan export Dead Sea mineral sediment to Australian formulators through consolidated shipping corridors. Sydney and Melbourne importers manage batch authentication and TGA notification compliance before distribution to spa networks and digital channels.
New South Wales
Sydney's wellness centers drive professional spa demand for therapeutic-grade mud formulations. TGA cosmetic ingredient regulations govern safety substantiation for mineral-based topicals entering through Port Botany. North Sydney and Bondi Beach clusters concentrate premium facial mask consumption among urban millennials.
Victoria
Melbourne's digital-native brands capture trial-to-loyalty conversion through subscription replenishment models. The state's biosecurity framework applies environmental assessment protocols to imported mineral raw materials. St Kilda and South Yarra spa districts integrate Dead Sea protocols into premium service menus.
Queensland
Gold Coast tourism operators source bulk formulations for resort spa treatments. State-level environmental clearance requirements create inconsistent import timelines compared to southern jurisdictions. Brisbane's online retailers capture volume from regional consumers beyond metro corridors.
Western Australia
Perth's geographic isolation drives e-commerce penetration for authenticated Dead Sea products. The state's biosecurity administration applies distinct mineral import inspection protocols. Fremantle-based distributors serve mining-sector professionals with elevated disposable income profiles.
South Australia
Adelaide's boutique spa sector generates concentrated demand for small-batch therapeutic formulations. Local regulators align with TGA baseline standards while maintaining separate cosmetic notification databases. Barossa Valley wellness tourism operators experiment with Dead Sea mud pairing in vineyard retreat settings.
Australia Dead Sea Mud Cosmetics Market Competitive Landscape
Listed leaders compete with private specialists across authenticated sourcing narratives and channel control dimensions. The vendor base clusters around vertically integrated Dead Sea basin operators, ethical sourcing storytellers, and therapeutic-grade formulators serving professional channels. Three archetypes dominate: basin-captive producers with captive mineral supply, retail-experiential brands with in-store education capabilities, and B2B specialists aligned with spa professional networks. Competitive moves concentrate on supply chain documentation investments and direct-to-consumer subscription infrastructure.
Within the therapeutic-grade tier, Ahava Dead Sea Laboratories and Kawar Cosmetics exemplify basin-captive positioning through upstream mineral control. Lush Retail Ltd anchors the experiential retail archetype with ethical sourcing narratives and in-store product education. These three entities represent the dominant strategic configurations through which Australian market access is contested.
| Leading Market Players |
|---|
| Ahava Dead Sea Laboratories |
| Kawar Cosmetics |
| Aroma Dead Sea |
| SABON |
| AVANI Supreme Inc |
| Lush Retail Ltd |
| Asutra |
| H&B Health and Beauty |
| Biscol Investments Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Australian spa distributors and Dead Sea basin extractors lock in mineral supply access while anchoring price visibility across volatile currency corridors. These contracts insulate professional channel buyers from spot-market fluctuations in Jordanian and Israeli export pricing, though TGA compliance costs remain unhedged.
Pricing Analysis
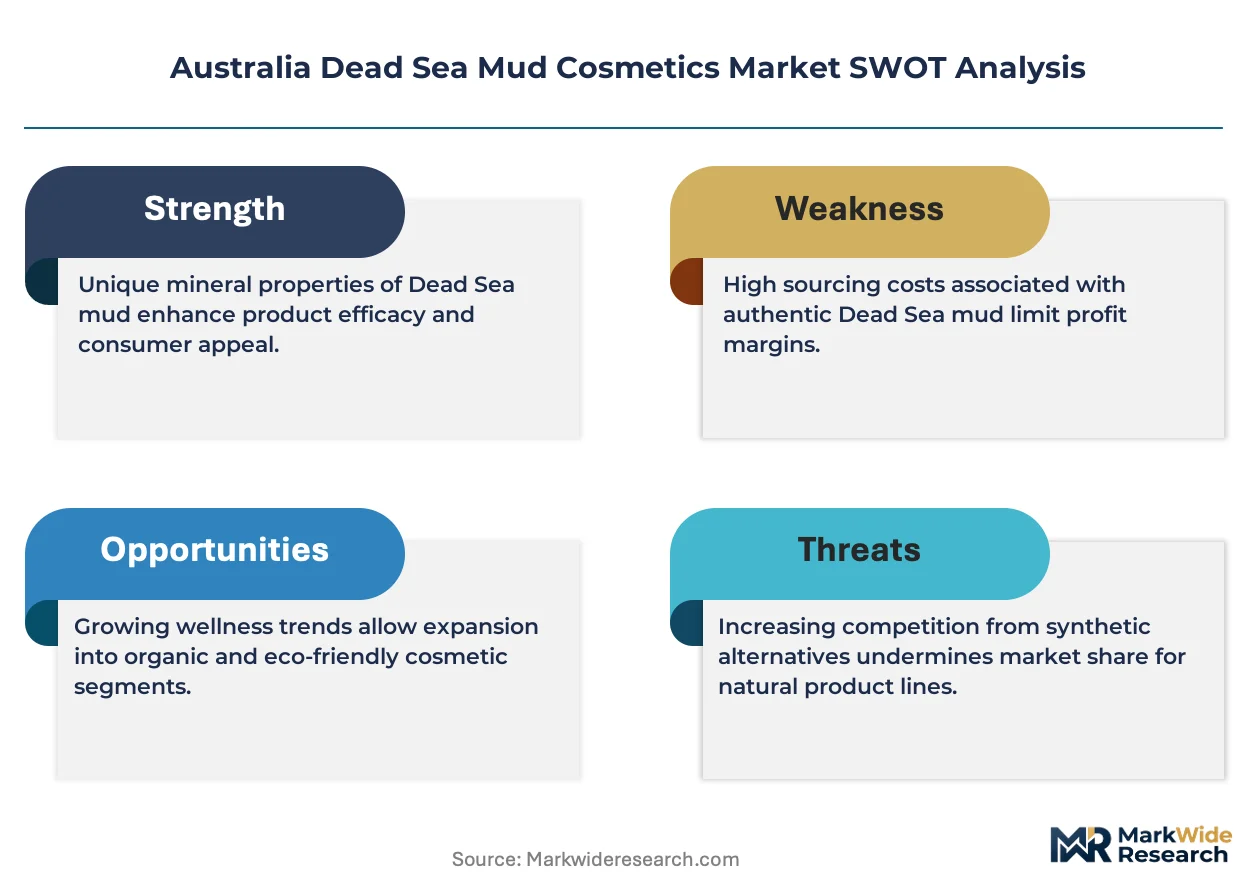
Current-generation blockchain-authenticated formulations command substantial premiums over prior-generation paper-documented batches, while next-generation isotopic fingerprinting technologies threaten to compress margins on legacy products. Three-tier pricing structure across premium, standard, and economy levels stratifies by mineral concentration grade and ISO 16128 certification tier. Cost compression in economy-tier cleansers is intensifying because domestic bentonite substitutes compete aggressively on landed cost. Regional Queensland consumers exhibit highest price sensitivity, whereas Sydney spa centers demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Inventory lead times for authenticated Dead Sea sediment stretch to 12-16 weeks due to batch-level mineral testing and biosecurity clearance protocols. Geographic supply concentrates in Jordan and Israel, with secondary consolidation points in Singapore and Dubai for Australian-bound shipments. Raw material dependencies encompass magnesium-rich mud extract, calcium-dense sediment layers, and bromide-stabilized carrier compounds. Single-source vulnerability from Dead Sea basin geopolitical exposure threatens continuity. Distribution runs through Port Botany and Port Melbourne for spa network fulfillment, with direct-to-consumer channels bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Dead Sea Mud Cosmetics Market represents an early-cycle expansion story, with professional spa protocol adoption in Victoria and New South Wales driving penetration beyond historical cosmetic-only positioning.
For Market Incumbents: Fortify authenticated sourcing documentation through blockchain-enabled provenance systems to defend against clean-label competitors. Invest in captive supply relationships with Dead Sea basin extractors to secure batch consistency for spa center contracts. TGA cosmetic notification pathway simplifications create urgency to lock in therapeutic-grade positioning before regulatory arbitrage narrows.
For New Entrants and Emerging Players: Anchor in Queensland and Western Australia regional markets where online retail penetration lags metro saturation. Target men's grooming applications with dedicated beard mask and cleanser SKUs, an underdeveloped segment with minimal incumbent presence. Deploy subscription replenishment models with personalized skin-type matching to capture trial-to-loyalty conversion.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated Dead Sea basin operators with upstream mineral control and established TGA compliance infrastructure. Long-term viability hinges on therapeutic-grade positioning durability and spa channel consolidation momentum. Watch for mineral authentication chemist talent scarcity as an inflection signal for laboratory acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Implementation | Establishes batch-level mineral traceability demanded by ISO 16128-conscious Australian buyers. |
| Direct-to-Consumer Subscription Launch | Captures repeat purchase economics from Melbourne millennials through automated replenishment services. |
| Men's Grooming SKU Expansion | Addresses white-space demand for beard masks and mineral cleansers with minimal dedicated competition. |
| Queensland Spa Network Partnership | Reduces channel concentration risk beyond Sydney-Melbourne corridors through Gold Coast resort integration. |
| TGA Therapeutic-Grade Certification | Enables premium pricing power through compliance positioning in regulated pharmacy channels. |
Research Methodology
A standing panel of spa operations directors, cosmetic formulation chemists, TGA regulatory consultants, and Dead Sea basin export managers provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from Australian customs import records, TGA cosmetic notification databases, ISO certification registries, and wellness industry trade publications. Bottom-up demand modeling from spa center procurement patterns and top-down market sizing from channel revenue estimates were triangulated for consistency.
Outputs were validated against external benchmarks including Dead Sea mineral export volumes from Jordan and Israel, Australian biosecurity clearance data for cosmetic raw materials, and subscription commerce metrics from digital-native beauty brands. The analytical framework segmented demand across product format, application type, end-user archetype, and distribution channel throughout the forecast period. CAGRs were derived from trend extrapolation of spa protocol adoption rates and authenticated sourcing premium sustainability. Industry-specific inputs encompassed TGA regulatory pathway timelines and mineral authentication technology diffusion curves.
Decision-makers should treat outputs as directional under assumptions of stable Dead Sea basin export access and continued TGA cosmetic notification streamlining; material deviation in geopolitical conditions or regulatory enforcement intensity would warrant model refresh. Specific risk factors include ACCC therapeutic claim enforcement actions and state-level biosecurity protocol fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
UV Nail Gel Polish Market