
 Industrial Metal Strips Market | 2026-2036
Industrial Metal Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Metal Strips Market Insights
ISO 9001 and IATF 16949 certification is redrawing supplier eligibility for automotive and aerospace strip programs, forcing secondary mills to upgrade quality systems or exit tier-one supply chains. ArcelorMittal leverages its integrated European flat-rolled network to sustain premium automotive strip positions across multiple continents. Nucor Corporation anchors North American supply through electric-arc-furnace-based sheet and strip capacity with lower carbon intensity than integrated blast-furnace rivals. JFE Steel Corporation differentiates through advanced high-strength steel strip grades for Japanese OEM lightweighting programs.
Industrial metal strips are flat-rolled metal products typically under 600 mm in width and manufactured to precise thickness tolerances, serving as feedstock for stamping, forming, and joining operations across engineered goods production. Stainless steel strip dominates corrosion-critical applications in chemical processing and medical equipment, while aluminum strip captures the fastest growth trajectory as automakers substitute steel in closure panels and battery enclosures. The thickness dimension stratifies margin pools, with ultra-thin gauge strip commanding premium pricing for electronics flex circuits and precision shims, whereas heavy gauge serves structural construction with thinner margins and higher volume throughput.
REACH and RoHS frameworks in Europe restrict hazardous substance content in metal strip coatings and surface treatments, redirecting formulation investments toward compliant passivation and lubricant systems. China's GB standards and MEE enforcement tighten emissions thresholds for cold-rolling and annealing operations, raising capital requirements for strip producers in Shandong and Hebei provinces. In the United States, EPA air quality rules and OSHA workplace exposure limits shape permissible process chemistries and equipment configurations. Stakeholders must monitor evolving carbon border mechanisms and alloy scrap traceability mandates that will determine sourcing flexibility and landed cost competitiveness in cross-border strip trade.
Market Dynamics
Automotive lightweighting mandates and embodied carbon accounting are forcing a fundamental reconfiguration of metal strip sourcing, with OEMs now disqualifying suppliers unable to certify cradle-to-gate emissions and IATF 16949 quality systems simultaneously.
Growth Catalysts
- EU Green Deal carbon border adjustments:European automakers are accelerating procurement of low-carbon aluminum strip from electric-arc-furnace producers to avoid CBAM penalties on imported flat-rolled metal.
- Battery enclosure manufacturing:EV platform architectures in Germany and Japan are consuming high-strength aluminum strip grades for thermal management and crash-structure integration.
- India's western industrial corridor:Electrical infrastructure buildout and appliance manufacturing clusters in Gujarat and Maharashtra are scaling stainless-steel strip consumption for transformer cores and consumer durables.
Market Restraints
- Scrap aluminum price volatility:Secondary smelters face margin compression when London Metal Exchange aluminum spikes disrupt input cost models for strip rolling operations.
- Hebei province supply concentration:China's cold-rolling capacity clusters in pollution-controlled zones where MEE enforcement triggers unplanned production halts during air quality emergencies.
- Ultra-thin gauge technical limits:Sub-0.1 mm stainless strip for flex circuits requires specialized Sendzimir mills that fewer than twelve producers worldwide can operate profitably.
Strategic Opportunities
- India BIS certification gaps:Domestic appliance and electrical equipment manufacturers are importing premium-grade strip because local mills lack BIS-approved testing infrastructure for precision thickness tolerances.
- US Inflation Reduction Act clean manufacturing credits:Domestic aluminum strip producers with verified low-carbon production pathways qualify for tax incentives that improve landed cost competitiveness against Chinese imports.
- Digital twin process control:Convergence of inline thickness gauging with machine learning optimization is enabling real-time strip quality adjustment that reduces annealing cycle waste.
Industry Challenges
- IATF 16949 certification timelines:Secondary mills in Shandong province require eighteen to twenty-four months to implement automotive-quality management systems, blocking entry into tier-one supply chains.
- Legacy ERP integration friction:Strip processors running decades-old production planning software struggle to interface with customer EDI systems demanding real-time coil traceability data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Metal Strips Market |
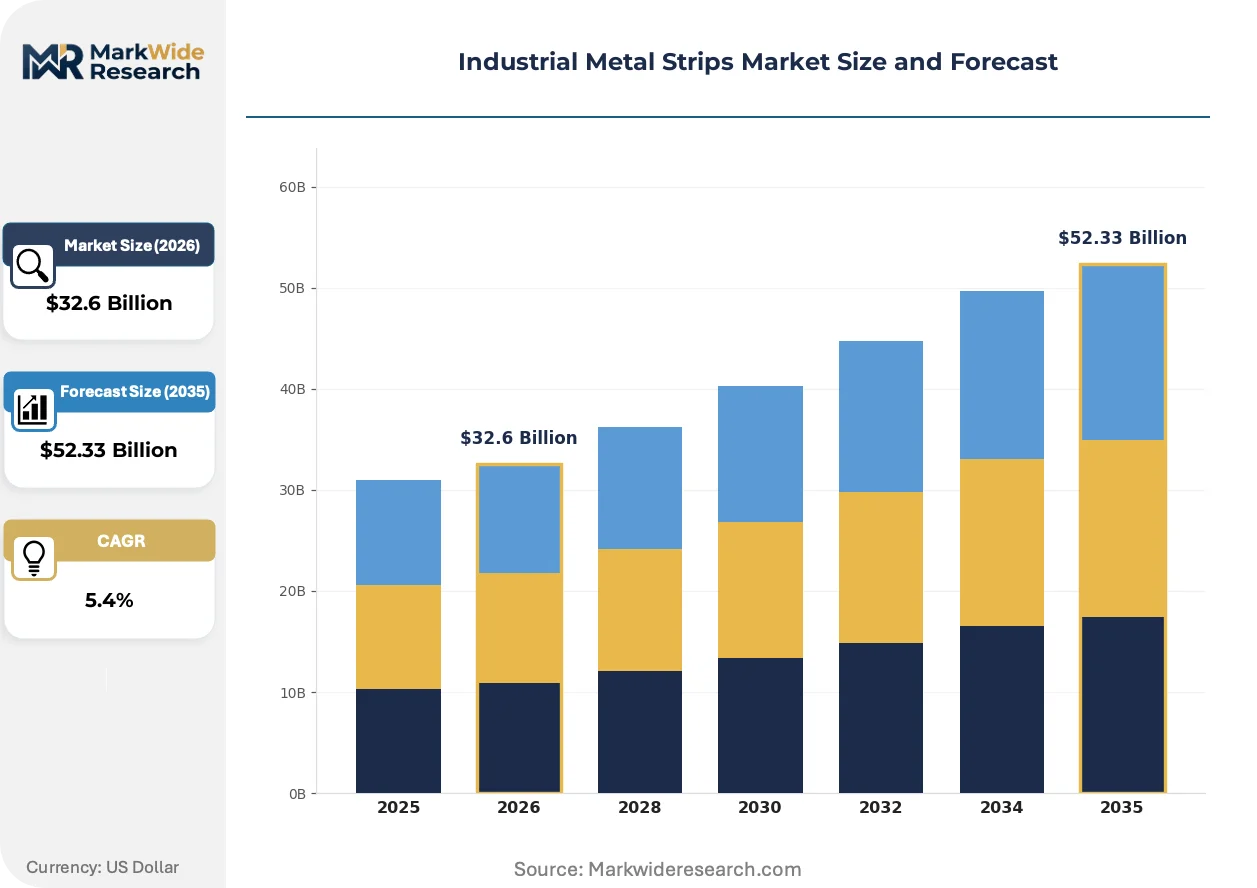
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $52.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Aluminum, Copper, Brass End Use Industry: Aerospace, Automotive Components, Electrical, Construction Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin Manufacturing Process: Stamping, Rolling, Laser Cutting, Shearing |
| Companies Covered | BlueScope Steel Limited, Nippon Steel & Sumitomo Metal Corporation, JFE Steel Corporation, ArcelorMittal, POSCO, Tata Steel, ThyssenKrupp, Nucor Corporation, China Baowu Steel Group Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Metal Strips Market Trends and Innovations
Process metallurgy and surface engineering are converging to produce strip grades with previously incompatible property combinations, while digitalization of quality documentation is compressing supplier qualification cycles from years to months.
Advanced high-strength steel strip with 980 MPa tensile strength is bifurcating the automotive body-in-white market, with Japanese OEMs adopting it for A-pillar reinforcement at volumes that outpace aluminum substitution in structural applications. German tier-one stampers are qualifying these grades for hot-formed components that reduce part count and assembly labor. The technology is bifurcating procurement strategies between legacy mild-steel programs and next-generation crash-performance architectures.
REACH Annex XVII restrictions on hexavalent chromium passivation are redirecting European strip processors toward trivalent chrome and silane-based surface treatments that satisfy corrosion requirements without hazardous substance liability. ECHA substance evaluation deadlines are accelerating reformulation investments ahead of sunset date enforcement. Surface treatment houses in the Netherlands and Italy are scaling compliant lines to maintain aerospace and medical equipment supply eligibility.
Automotive OEMs are consolidating coil suppliers to reduce inbound logistics complexity and improve lot traceability, with single-source agreements replacing fragmented multi-mill procurement for critical closure-panel grades. Tier-one stampers in Germany are accepting volume commitments in exchange for dedicated furnace capacity and priority scheduling during supply tightness. This concentration is most visible in battery enclosure programs where cell manufacturers demand identical metallurgical properties across multi-year production runs.
Industrial Metal Strips Market Segmentation
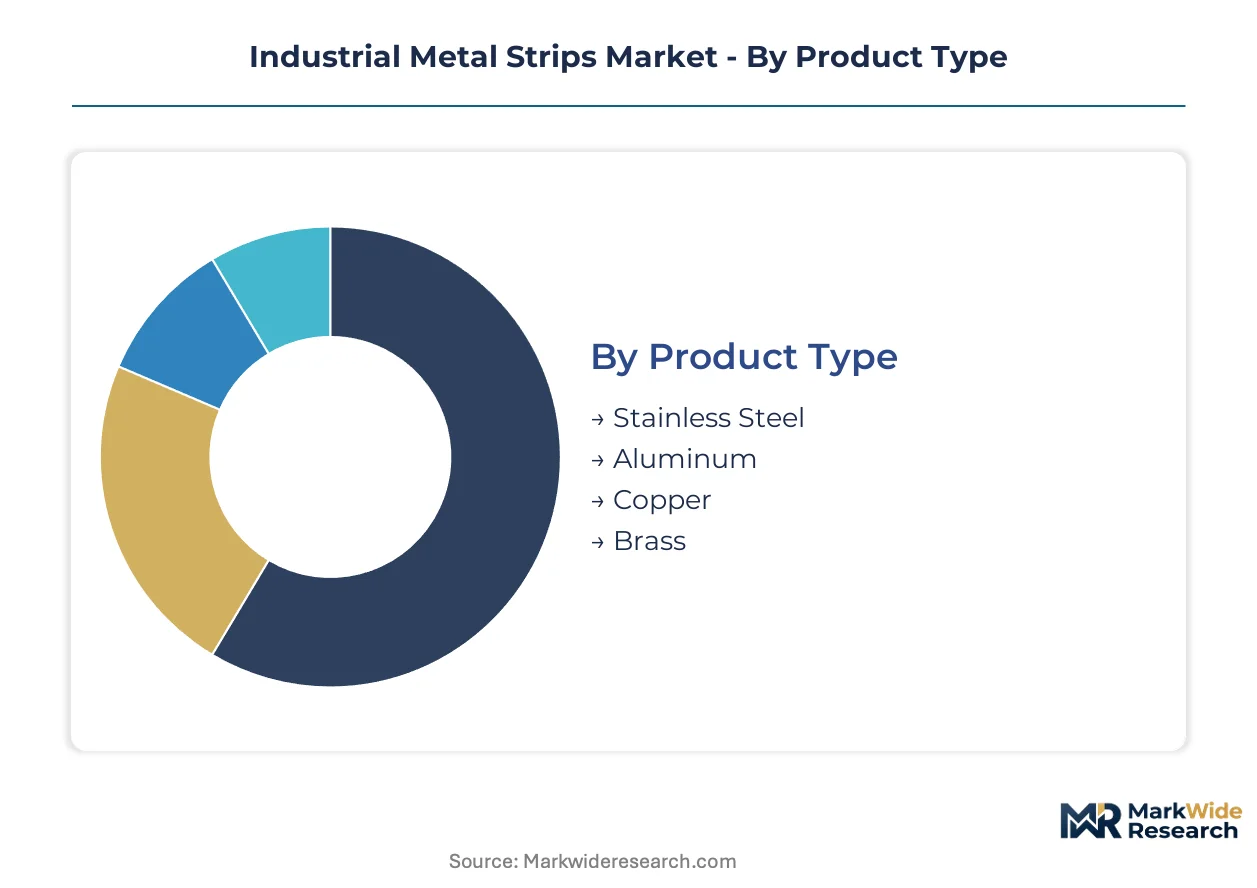
Metal strip procurement strategies diverge sharply across material grades, end-use specifications, and gauge tolerances. Each segmentation axis carries distinct margin profiles, certification requirements, and geographic sourcing patterns that reshape supplier selection criteria.
Product Type:
Domestic consumption patterns vary by alloy family, with aluminum strip increasingly produced near automotive assembly plants while stainless steel flows through established import corridors.
- Stainless Steel:Austenitic and ferritic grades dominate corrosion-critical applications in chemical processing equipment and medical instruments. German automotive suppliers specify precision-annealed 300-series strip for exhaust system flex connectors, with IATF 16949 certification mandatory for tier-one qualification.
- Aluminum:Heat-treatable 6xxx and 5xxx series strips serve EV battery enclosures and closure panels where weight reduction targets exceed 30% versus steel equivalents. Japanese OEMs in Toyota City and Nagoya industrial zones source directly from domestic rolling mills with verified low-carbon production pathways.
- Copper:Oxygen-free high-conductivity grades feed transformer winding and semiconductor leadframe applications in India's Gujarat electrical manufacturing cluster.
- Brass:Cartridge brass and free-machining grades supply plumbing fittings and decorative hardware producers across Italy's Lombardy metalworking district.
Stainless steel commands the established base. The steepest expansion runs through aluminum.
End Use Industry:
Application-specific metallurgical requirements stratify supplier tiers, with aerospace and automotive programs demanding traceable heat treatment records that construction-grade shipments rarely require.
- Aerospace:Titanium-stabilized stainless and precipitation-hardened aluminum strips must meet AMS specifications with full mill test report documentation. French tier-one suppliers near Toulouse maintain dedicated furnace capacity for aerospace-qualified coils.
- Automotive Components:Advanced high-strength steel strip with 980 MPa tensile strength enables A-pillar reinforcement designs that reduce part count. German stampers in Baden-Württemberg qualify these grades for hot-formed structural members.
- Electrical:Grain-oriented silicon steel strip for transformer cores requires precise magnetic domain control, with India's Maharashtra state emerging as a consumption hub for power infrastructure buildout.
- Construction:Structural aluminum and stainless strips for façade cladding and roofing systems prioritize yield strength consistency over surface finish refinement.
Automotive applications absorb the highest premium-grade volumes. Electrical infrastructure is climbing the fastest.
Thickness:
Gauge selection directly determines equipment requirements and feasible producer geography, as ultra-thin capabilities concentrate among specialized Sendzimir mill operators.
- Thin Gauge:Sub-1.0 mm aluminum and steel strips serve appliance panels and automotive interior trim, with thickness tolerances of ±0.02 mm achievable on modern tandem cold mills.
- Medium Gauge:1.0-3.0 mm range dominates structural automotive stampings and electrical enclosure manufacturing, balancing formability with crash-performance requirements.
- Heavy Gauge:Above 3.0 mm strips supply construction framing and heavy equipment components, with lower per-kilogram margins offset by volume throughput on less specialized rolling lines.
- Ultra-Thin:Sub-0.1 mm stainless strip for flex circuits and precision shims demands specialized 20-roll Sendzimir mills that fewer than twelve producers worldwide operate profitably. Japanese and German specialists control this segment.
Medium gauge holds the volume center. Ultra-thin commands the steepest premium escalation.
Manufacturing Process:
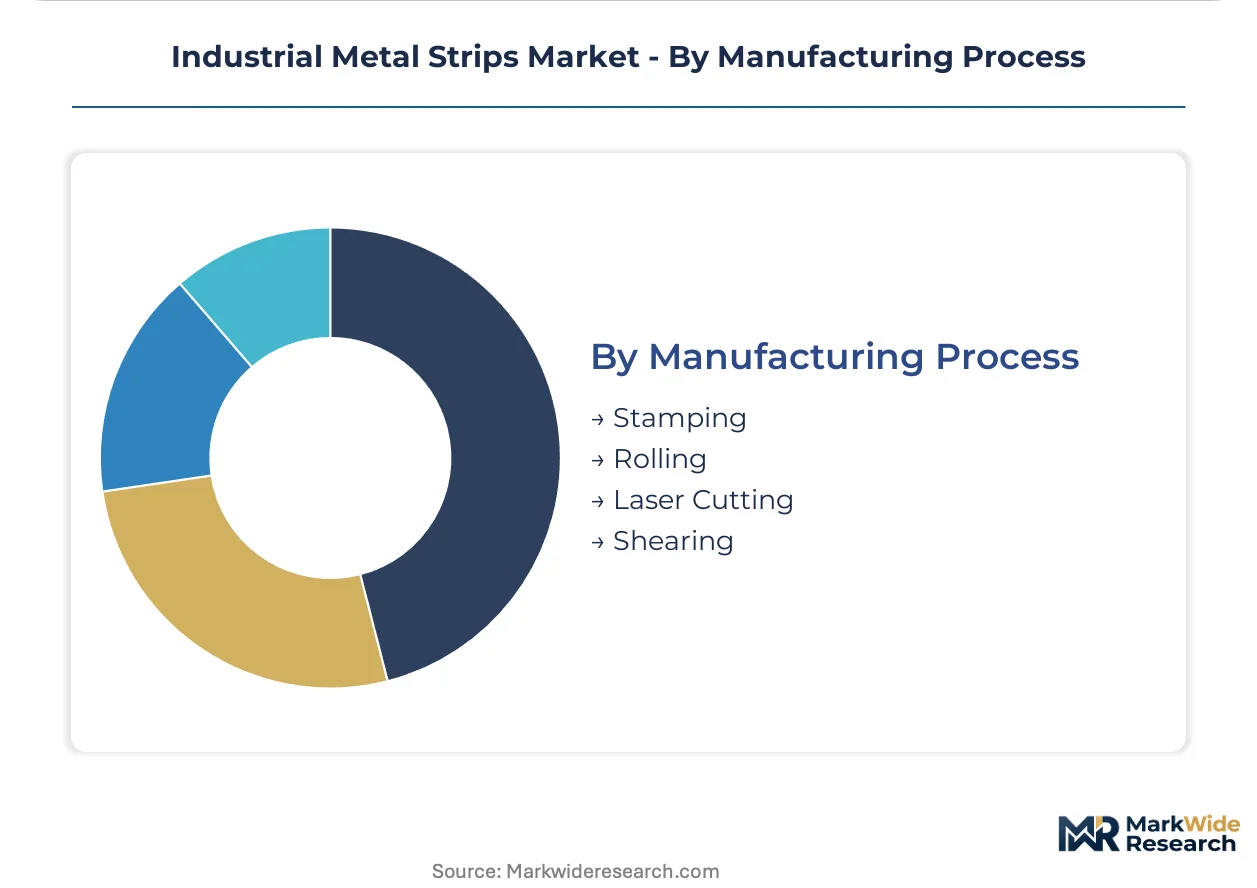
Process selection reflects part complexity and volume economics, with high-speed stamping dominating automotive programs while laser cutting serves prototype and short-run fabrication.
- Stamping:Progressive die systems process coiled strip into complex automotive brackets and electrical connectors at rates exceeding 600 parts per minute. Tool steel quality and die maintenance protocols determine output consistency.
- Rolling:Cold reduction and temper rolling establish final gauge and mechanical properties, with inline thickness gauging enabling real-time process adjustment that reduces annealing cycle waste.
- Laser Cutting:Fiber laser systems cut nested profiles from strip blanks without hard tooling investment, serving prototype development and architectural metalwork with lot sizes below 500 units.
- Shearing:Straight-line and rotary shearing operations convert master coils to specified widths for downstream stamping and forming operations, with edge quality critical for automated feeding systems.
Rolling underpins all downstream processing. Laser cutting is expanding most quickly into prototype-to-production workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive lightweighting programs and electrical infrastructure buildouts are concentrating procurement decisions among tier-one stampers and OEMs in Germany, Japan, China, India, and the United States. Each geography presents distinct certification requirements and supply chain configurations that reshape supplier eligibility.
Germany
Baden-Württemberg automotive stampers qualify advanced high-strength steel strip grades for hot-formed A-pillar components that reduce part count. EU Green Deal carbon border adjustments pressure procurement teams to source low-carbon aluminum strip from electric-arc-furnace producers. Stuttgart-area tier-one suppliers maintain dedicated furnace capacity for premium automotive programs with IATF 16949 certification mandates.
China
Shandong and Hebei province cold-rolling clusters face unplanned production halts when MEE enforcement triggers air quality emergency protocols. Dual carbon goals tighten embodied carbon accounting for flat-rolled metal inputs serving domestic EV battery enclosure manufacturers. Yangtze River Delta automakers in Shanghai and Jiangsu province accelerate substitution of steel with aluminum strip in closure panels.
Japan
Toyota City and Nagoya industrial zone OEMs source heat-treatable 6xxx and 5xxx series aluminum strip directly from domestic mills with verified low-carbon production pathways. METI efficiency standards drive precision thickness requirements for flex circuit and semiconductor leadframe applications. JIS-certified Sendzimir mill operators in the Chubu region control sub-0.1 mm ultra-thin stainless strip production.
India
Maharashtra and Gujarat electrical infrastructure buildouts scale grain-oriented silicon steel strip consumption for transformer core manufacturing. BIS certification gaps force domestic appliance manufacturers to import premium-grade strip because local mills lack approved testing infrastructure for precision tolerances. Mumbai-Pune industrial corridor stampers qualify medium-gauge aluminum strip for consumer durable enclosures.
United States
EPA air quality rules and OSHA workplace exposure limits shape permissible process chemistries for cold-rolling operations serving automotive and aerospace programs. Inflation Reduction Act clean manufacturing credits improve landed cost competitiveness for domestic aluminum strip producers with verified low-carbon pathways. Southeast automotive assembly plants near Georgia and South Carolina cluster procurement of medium-gauge steel strip for structural stampings.
Industrial Metal Strips Market Competitive Landscape
Player mix skews toward integrated steelmakers with captive flat-rolled networks and specialized cold-rolling specialists with Sendzimir mill capabilities. Consolidation around automotive-certified capacity has eliminated secondary mills unable to achieve IATF 16949 quality systems. Two strategic archetypes dominate: blast-furnace-based integrated producers with premium automotive positions and electric-arc-furnace operators with lower carbon intensity. Competitive moves center on M&A to secure coil coating assets and strategic partnerships for battery enclosure grade development.
Among Asia-Pacific integrated producers, Nippon Steel & Sumitomo Metal Corporation, JFE Steel Corporation, and POSCO occupy positions defined by proximity to Japanese and South Korean OEM lightweighting programs. ArcelorMittal anchors European supply through its integrated flat-rolled network spanning multiple continents. Nucor Corporation exemplifies the electric-arc-furnace archetype with North American sheet and strip capacity. China Baowu Steel Group Corporation Limited represents scale-driven production serving domestic demand and export markets.
| Leading Market Players |
|---|
| BlueScope Steel Limited |
| Nippon Steel & Sumitomo Metal Corporation |
| JFE Steel Corporation |
| ArcelorMittal |
| POSCO |
| Tata Steel |
| ThyssenKrupp |
| Nucor Corporation |
| China Baowu Steel Group Corporation Limited |
| Others |
Pricing and Supply Chain Analysis
IATF 16949 certification gates entry into automotive strip supply chains while simultaneously enabling price premiums of fifteen to twenty percent over uncertified secondary mill output. This dual function concentrates procurement power among qualified producers in Germany, Japan, and the United States, who leverage audit-compliant quality systems to defend margin structures against low-cost import competition.
Pricing Analysis
Long-term offtake contracts with London Metal Exchange indexation dominate aluminum strip procurement, shielding rolling mills from scrap price volatility while passing alloy cost fluctuations to automotive buyers. Price differentiation rests on certification tier and gauge precision, with ultra-thin Sendzimir mill output commanding substantial premiums over commodity cold-rolled coil. Cost compression in standard-grade stainless strip is intensifying because Chinese overcapacity in Hebei province floods export markets. Tier-one automotive stampers exhibit lowest price sensitivity, prioritizing lot traceability and dedicated furnace capacity over unit cost minimization.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Indian electrical manufacturers sourcing grain-oriented silicon steel from Japanese and South Korean mills. Supply concentrates in China, Japan, and Germany, with cold-rolling capacity clustering near automotive assembly plants in Toyota City, Stuttgart, and Shanghai. Raw material flows draw from bauxite refineries in Australia, nickel laterite operations in Indonesia, and ferrochrome smelters in South Africa. Single-source vulnerability pervades ultra-thin gauge stainless supply, where fewer than twelve Sendzimir operators worldwide serve flex circuit and semiconductor leadframe demand. Distribution runs through mill-direct arrangements for high-volume automotive programs, with regional service centers handling fragmented construction and appliance orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial metal strip demand sits in early-cycle expansion, with EV battery enclosure manufacturing and electrical infrastructure buildout in India accelerating penetration beyond traditional automotive stamping applications.
For Market Incumbents: Secure dedicated furnace capacity commitments from German and Japanese OEMs through multi-year volume agreements that block competitor access during supply tightness. Deepen backward integration into scrap sorting and alloy blending operations to insulate margin structures from London Metal Exchange volatility. The priority lever rests on IATF 16949 certification maintenance, as secondary mills in Shandong province threaten tier-two supply positions with accelerating quality system investments. For New Entrants and Emerging Players: Differentiate on low-carbon production pathways verified through electric-arc-furnace operations that qualify for EU Green Deal procurement preferences and US Inflation Reduction Act clean manufacturing credits. Target India's western industrial corridor, where BIS certification gaps force domestic appliance manufacturers to import premium-grade strip. The most penetrable segment lies in medium-gauge aluminum for electrical enclosures, where local mills lack precision tolerance capability. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated steelmakers divesting non-core cold-rolling assets to focus on green steel transition investments. Long-term viability favors electric-arc-furnace strip producers with verified Scope 1-2 emissions data and established automotive qualification. The signal to watch is carbon border adjustment mechanism enforcement timing, which will abruptly reprice import competitiveness for Chinese and Indian mill output.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Processing | Captive alloy feedstock insulates rolling margins from London Metal Exchange volatility spikes. |
| IATF 16949 Certification Investment | Automotive OEMs disqualify uncertified suppliers from battery enclosure and closure panel programs. |
| Low-Carbon Production Pathway Verification | Electric-arc-furnace operators qualify for EU Green Deal procurement and US IRA tax credits. |
| Sendzimir Mill Capacity Addition | Ultra-thin gauge capability serves flex circuit and semiconductor leadframe demand with limited competition. |
| India BIS Testing Infrastructure Buildout | Approved precision tolerance capability addresses import substitution opportunity in electrical and appliance segments. |
Research Methodology
The analysis maps cold-rolling, annealing, and surface treatment sub-sectors, each validated through procurement directors at tier-one automotive stampers, quality managers at electrical equipment manufacturers, and metallurgical engineers at specialty strip producers. Primary interviews with rolling mill operations heads, distribution channel partners, and regulatory compliance officers combined with secondary validation from customs trade data, SEC filings of listed steelmakers, and national standards body certification registries. Bottom-up coil shipment data triangulated against top-down end-use consumption estimates across automotive, electrical, and construction applications.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled material grade, gauge tolerance, end-use industry, and geographic production cluster dimensions. CAGRs derived from shipment volume trajectories, capacity utilization trends, and substitution elasticity between steel and aluminum grades. Forecast inputs incorporated electric vehicle platform rollout schedules, power infrastructure investment pipelines, and evolving carbon border mechanism implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained automotive lightweighting commitment, stable scrap alloy pricing, and incremental regulatory enforcement would require recalibration. Forecasts reflect assumptions regarding certification adoption rates, furnace capacity expansion timing, and trade flow responses to carbon accounting requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Tin Market
Metals
Osmium Market
Metals
Europe Aluminium Wire Rod Market
Metals
Aluminum Smelting Market
Metals
Seamless Stainless Steel Products Market
Metals
Shipbuilding Steel Plate Market
Metals
Carbotanium Market
Metals
Aluminium Powder Market
Metals
Global Aluminium Wire Rod Market
Metals
Rolled Steel Motor Market
Metals
India Special Steel Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Aluminum Hot Rolling Mill Market
Metals
316 Stainless Steel Container Market
Metals
Finished Steel Products Market
Metals
GCC Aluminium Cans Market