
 Europe Phytosterols Market | 2026-2036
Europe Phytosterols Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Phytosterols Market Foresight
EU Nutrition and Health Claims Regulation is decoupling market access from basic ingredient supply. BASF SE leverages its Ludwigshafen manufacturing complex to sustain integrated production of sterol esters for food fortification. Cargill, Incorporated anchors its European phytosterol position through Rotterdam distribution infrastructure and oilseed processing scale.
Phytosterols comprise plant-derived steroid alcohols—primarily beta-sitosterol, campesterol, and stigmasterol—typically extracted from vegetable oils and tall oil pitch through crystallization or molecular distillation at purity thresholds exceeding 95%. These compounds block intestinal cholesterol absorption, serving as functional ingredients in cardiovascular health products. Esterified phytosterols dominate volume flows due to superior fat solubility in margarine and spread applications, while free phytosterols capture premium positioning in dietary supplement capsules where bioavailability claims differentiate finished goods. Functional food applications command the deepest margin pools as branded cholesterol-lowering products command shelf-space premiums across German and French retail.
EFSA scientific opinions govern permitted health claims for phytosterol content, while ECHA REACH compliance dictates purity and contaminant thresholds for imported raw materials. The EU Green Deal is tightening sustainability traceability requirements for vegetable oil-derived inputs. Stakeholders must monitor evolving EFSA claim substantiation protocols and upstream oilseed supply certification standards to secure long-term formulation approvals.
Market Dynamics
EU Nutrition and Health Claims Regulation is decoupling market access from basic ingredient supply. EFSA scientific opinions now govern permitted cardiovascular health claims, forcing reformulators to substantiate bioavailability data before securing shelf placement in German and French retail channels.
Growth Catalysts
- EFSA Claim Substantiation:Approved Article 14 health claims for LDL cholesterol reduction are accelerating phytosterol incorporation into fortified dairy and spreads. Food manufacturers leverage these endorsements to justify premium positioning.
- Cardiovascular Disease Burden:Elevated cholesterol prevalence across aging populations in Germany and France is pulling functional food demand. Clinical validation of phytosterol efficacy reinforces physician recommendations.
- Tall Oil Pitch Recovery:Pulp and paper industry byproduct streams in Nordic countries are expanding sterol feedstock availability. Crystallization yields from this source reduce dependency on vegetable oil price cycles.
Market Restraints
- Soybean Oil Price Volatility:Phytosterol extraction costs track agricultural commodity swings, compressing margin predictability for esterified product lines dependent on soy-derived feedstocks.
- Supply Concentration Risk:Sterol ester production clusters around Ludwigshafen and Rotterdam infrastructure, creating single-point vulnerability for European formulation supply.
- Bioavailability Ceiling:Free phytosterol absorption rates plateau at fractional percentages, limiting efficacy claims against prescription statin alternatives in medical nutrition contexts.
Strategic Opportunities
- Poland Processed Food Corridor:Underpenetrated private-label spread manufacturers present white-space entry for sterol ester suppliers seeking volume expansion beyond German market saturation.
- EU Green Deal Traceability:Sustainability certification requirements for vegetable oil inputs are favoring suppliers with integrated upstream auditing. Early compliance secures preferential procurement status.
- Pharmaceutical-Grade Purity:99%+ sterol specifications for clinical nutrition applications command price multiples over food-grade material. Crystallization technology advances are opening this segment.
Industry Challenges
- REACH Registration Timelines:ECHA compliance documentation for novel sterol derivatives extends 18-24 months, delaying product launches and freezing formulation pipelines.
- Analytical Methodology Standardization:Inconsistent GC-FID protocols across national reference laboratories create batch rejection risks at border inspections, particularly for campesterol/stigmasterol ratio specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Phytosterols Market |
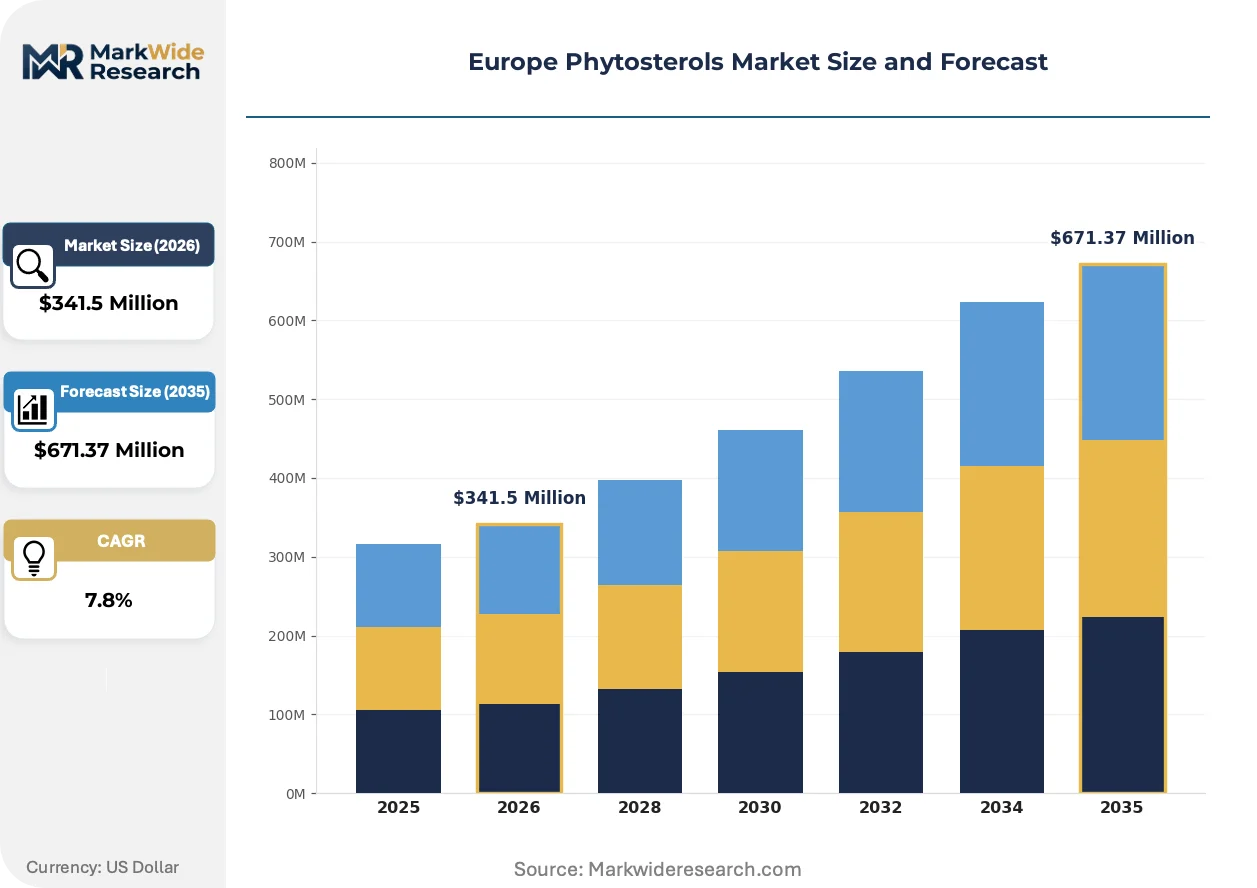
| Market Size in 2026 | $341.5 Million |
| Market Size in 2035 | $671.37 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Free Phytosterols, Esterified Phytosterols, Phytostanols, Beta-Sitosterol, Campesterol, Stigmasterol Application: Functional Food, Dietary Supplements, Pharmaceuticals, Personal Care, Animal Feed, Beverages End User: Food & Beverage Manufacturers, Nutraceutical Companies, Pharmaceutical Firms, Cosmetic Producers, Animal Nutrition Providers Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores, Contract Manufacturing |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill, Incorporated, Gustav Parmentier GmbH, Raisio Plc, Arboris, LLC, Pharmachem Laboratories, Inc., Bunge Limited, DuPont, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Phytosterols Market Shifts & Advancements
Processing technology advances and regulatory claim evolution are restructuring competitive advantage in phytosterol value chains. Manufacturers are repositioning around bioavailability differentiation and sustainability verification rather than commodity volume.
Supercritical CO2 extraction is modularizing sterol recovery from deodorizer distillates. Mid-scale toll processors in the Netherlands are adopting this equipment to bypass centralized refinery dependency. Modular plant footprints enable proximity sourcing from regional oilseed crushing, compressing logistics exposure and supporting EU Green Deal traceability mandates.
EFSA is tightening substantiation requirements for cholesterol-lowering claims through updated scientific opinion protocols. Food manufacturers must now demonstrate minimum 1.5g daily phytosterol intake efficacy in target populations. German spread producers are responding by reformulating toward higher ester concentrations and dual-claim packaging combining plant sterols with omega-3.
Retail pharmacy channels are displacing conventional grocery as the primary vector for premium phytosterol supplements. French consumers increasingly validate cardiovascular health purchases through pharmacist consultation, unbundling supplement distribution from mass-market shelf placement. This shift concentrates demand among formulary-approved SKUs with documented EFSA compliance.
Europe Phytosterols Market Segmentation
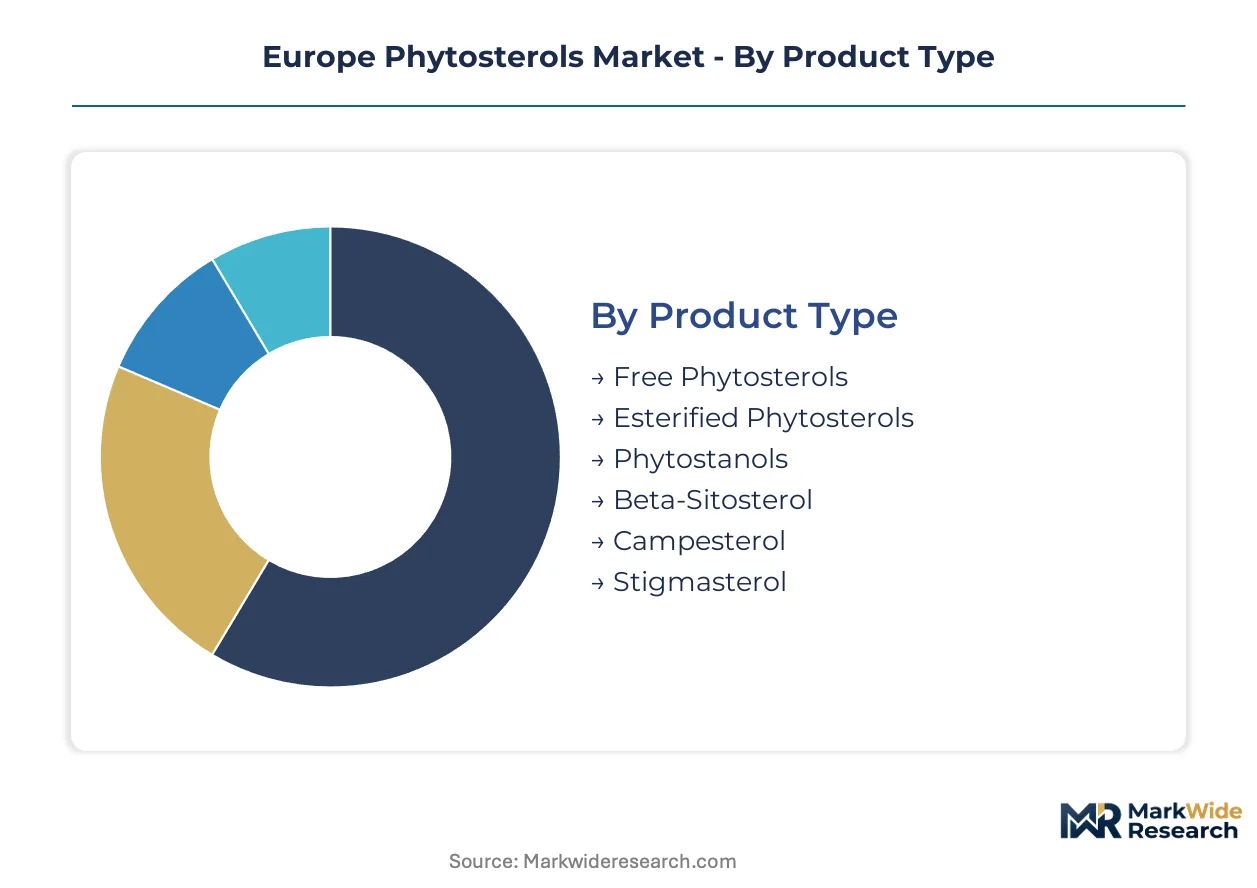
Phytosterol segmentation in Europe reflects divergent regulatory pathways across product forms and end-use applications. EFSA claim substantiation requirements and ECHA REACH compliance create tiered certification burdens that reshape supplier economics and customer procurement priorities.
Product Type:
EFSA Article 14 health claims apply differentially across sterol forms, with esterified variants requiring additional stability documentation for shelf-life validation.
- Free Phytosterols:Unesterified beta-sitosterol, campesterol, and stigmasterol maintain crystalline structure at ambient temperatures. Pharmaceutical firms in Germany specify 95%+ purity for clinical nutrition capsules where bioavailability claims require batch-specific dissolution data.
- Esterified Phytosterols:Fatty acid esters deliver superior lipid solubility for margarine and spread matrices. French functional food manufacturers concentrate procurement here, leveraging EFSA-approved LDL cholesterol reduction claims for premium positioning in retail dairy.
- Phytostanols:Saturated sterol variants resist oxidation during thermal processing. Bakery applications in the Netherlands favor this stability profile for fortified bread formulations.
- Beta-Sitosterol:Dominant sterol species from vegetable oil distillates. Dietary supplement producers specify this isolate for prostate health positioning.
- Campesterol:Brassica-derived variant with distinct analytical signatures. Tall oil pitch extraction in Nordic pulp mills yields concentrated streams for industrial-scale esterification.
- Stigmasterol:Soybean oil co-extract with sterol precursor applications. Pharmaceutical synthesis demand in Switzerland drives small-volume, high-purity contracts.
Leading the category by volume: Esterified Phytosterols. Expanding most quickly: Free Phytosterols in pharmaceutical-grade specifications.
Application:
Margin structures diverge sharply across application tiers, with functional food commanding shelf-space premiums and pharmaceuticals extracting purity-based multiples.
- Functional Food:Cholesterol-lowering spreads and fortified dairy in Germany and France absorb the majority of esterified sterol supply. EFSA claim substantiation enables price positioning at 2-3x commodity margarine levels.
- Dietary Supplements:Capsule and tablet formats concentrate in French pharmacy channels. Pharmacist consultation requirements favor documented EFSA compliance over mass-market distribution.
- Pharmaceuticals:Clinical nutrition and medical food specifications demand 99%+ purity with full contaminant profiling. Swiss and German contract manufacturers dominate this segment.
- Personal Care:Topical anti-inflammatory claims drive cosmetic incorporation. Italian and French formulators specify sterol emulsifiers for premium skincare lines.
- Animal Feed:Poultry and swine nutrition applications seek cost-reduced sterol fractions. Polish and Romanian compound feed producers represent emerging demand pockets.
- Beverages:Functional juice and plant milk fortification remains technically constrained by solubility limits. Dutch beverage innovators pilot microencapsulation for sterol dispersion stability.
Highest margin capture: Pharmaceuticals. Steepest volume expansion: Functional Food.
End User:
Procurement sophistication varies by buyer technical capability, with pharmaceutical and nutraceutical firms imposing stringent supplier audit protocols.
- Food & Beverage Manufacturers:German and French spread producers dominate volume offtake. These buyers integrate sterol esters into cholesterol-lowering product lines with dual-claim omega-3 formulations.
- Nutraceutical Companies:French pharmacy-channel specialists specify EFSA-compliant documentation for retail pharmacist validation. Capsule and soft-gel formats predominate.
- Pharmaceutical Firms:Clinical nutrition divisions in Switzerland and Germany source pharmaceutical-grade sterols for medical food applications. Full REACH registration and ICH Q3D elemental impurity compliance are mandatory.
- Cosmetic Producers:Italian skincare formulators leverage sterol emolliency for premium positioning. Sustainability certification requirements are tightening under EU Green Deal traceability mandates.
- Animal Nutrition Providers:Compound feed manufacturers in Poland and Spain seek cost-optimized sterol fractions for layer hen and broiler diets. Feed-grade specifications permit broader purity tolerances.
Most demanding procurement standards: Pharmaceutical Firms. Fastest-growing buyer segment: Nutraceutical Companies.
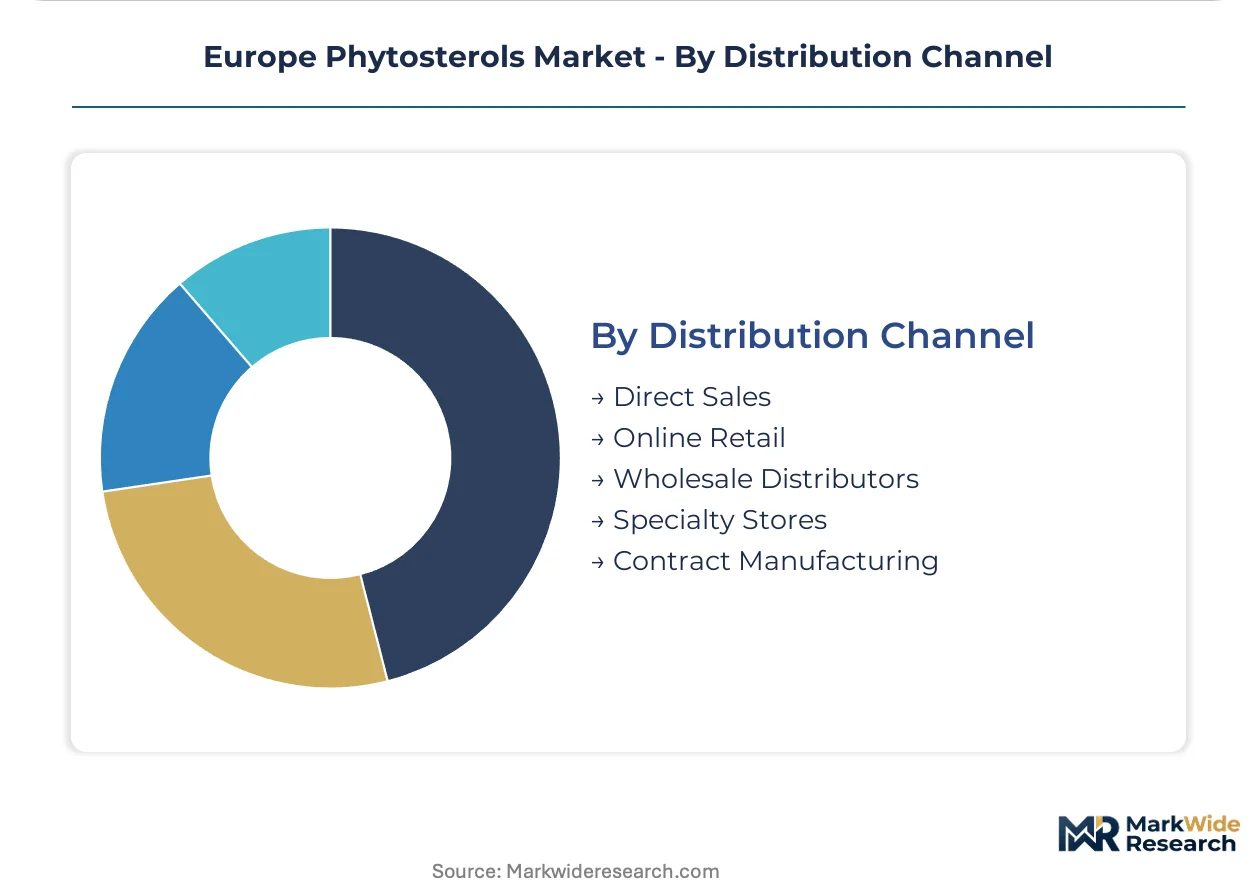
Distribution Channel:
Channel selection tracks order scale and technical service requirements, with direct sales capturing formulation-intensive accounts.
- Direct Sales:BASF SE and Cargill, Incorporated serve major food manufacturers through technical sales teams based in Ludwigshafen and Rotterdam. These relationships include application development support for sterol ester integration.
- Online Retail:Dietary supplement brands in France and Germany bypass wholesale layers for direct-to-consumer fulfillment. Pharmacy-affiliated platforms command premium positioning.
- Wholesale Distributors:Rotterdam-based ingredient traders aggregate sterol supplies for mid-scale food processors across Benelux and Northern France. Inventory pooling reduces working capital requirements for buyers.
- Specialty Stores:Health food retailers in German urban centers stock premium phytosterol supplements with organic and non-GMO certifications. These outlets validate products through independent lab testing.
- Contract Manufacturing:Toll processors in the Netherlands offer supercritical CO2 extraction services for regional oilseed crushers. Modular plant footprints support EU Green Deal traceability requirements.
Dominant channel by value: Direct Sales. Gaining share fastest: Contract Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's port-centric free trade zone concentrates phytosterol import flows and toll processing capacity, anchoring European distribution logistics. German chemical manufacturing clusters leverage this infrastructure for sterol ester production. French retail pharmacy networks pull finished goods through distinct regulatory channels.
Germany
Functional food manufacturers in North Rhine-Westphalia drive esterified phytosterol demand for cholesterol-lowering spreads. EFSA Article 14 health claim compliance shapes product development timelines. Ludwigshafen's integrated chemical complex sustains captive sterol ester production for food fortification applications.
Netherlands
Rotterdam-based ingredient traders aggregate vegetable oil distillates from global sources for regional toll processing. EU Green Deal traceability mandates accelerate sustainability certification adoption. Modular supercritical CO2 extraction facilities in the port zone enable proximity sourcing from Benelux oilseed crushing.
France
Pharmacy-channel supplement distribution concentrates demand among EFSA-compliant formulations. ANSM oversight of health claim substantiation reinforces pharmacist consultation requirements. Paris-region nutraceutical firms specialize in capsule formats with documented bioavailability data.
Switzerland
Swissmedic-regulated clinical nutrition manufacturers source pharmaceutical-grade sterols for medical food applications. Basel-area pharmaceutical contract manufacturers impose 99%+ purity specifications with full ICH Q3D elemental impurity profiling. Zürich-based synthesis specialists convert stigmasterol into sterol precursors for active pharmaceutical ingredients.
Poland
Private-label spread manufacturers in the Mazovia region present volume expansion opportunities beyond saturated Western markets. Cost-optimized compound feed producers in Lower Silesia seek sterol fractions for poultry nutrition applications. Warsaw-based food processors pilot fortified dairy formulations for regional retail chains.
Europe Phytosterols Market Competitive Landscape
German producers anchor the integrated manufacturing tier; Netherlands-based specialists hold distribution and toll processing positions. The vendor structure concentrates around chemical conglomerates with vegetable oil processing scale and mid-scale extraction technology providers. Three archetypes dominate: integrated petrochemical players with captive feedstock access, agribusiness traders with oilseed crushing infrastructure, and modular toll processors with supercritical extraction capability. Capacity expansion and sustainability certification acquisition represent the dominant competitive vectors.
Within the integrated chemical tier, BASF SE exemplifies Ludwigshafen-based manufacturing scale. Among agribusiness traders, Cargill, Incorporated occupies the Rotterdam distribution anchor position. Gustav Parmentier GmbH represents the specialized toll processing archetype with regional oilseed proximity. These three entities collectively illustrate the geographic and structural segmentation governing European phytosterol supply.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Gustav Parmentier GmbH |
| Raisio Plc |
| Arboris, LLC |
| Pharmachem Laboratories, Inc. |
| Bunge Limited |
| DuPont |
| Others |
Supply & Pricing Matrix
Vegetable oil deodorizer distillate costs cascade through three pricing tiers for phytosterol buyers, with soy-derived feedstock volatility compressing margins at the commodity ester level while pharmaceutical-grade crystalline sterols capture purity premiums in Swiss and German clinical nutrition procurement.
Pricing Analysis
Lead-time contracting distinguishes pricing tiers across European phytosterol procurement, with 12-month offtake agreements commanding 8-15% discounts against spot purchases for standard-grade sterol esters. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA certification status, REACH registration completeness, and volume scale. Pricing pressure stems from soybean oil commodity cycles eroding spread-manufacturer margins in Germany. Compound feed producers in Poland exhibit highest price sensitivity; pharmaceutical contract manufacturers in Basel show least.
Supply Chain Analysis
Specialized chemical process operators in Ludwigshafen and Rotterdam face tightening technical workforce availability as supercritical CO2 extraction expertise concentrates among Dutch toll processors. Supply clusters in Germany, the Netherlands, and Switzerland anchor European sterol ester production. Raw material flows draw from vegetable oil distillates, tall oil pitch from Nordic pulp mills, and brassica oilseeds from regional crushing. Single-source vulnerability concentrates around Rotterdam port infrastructure for import distillation. Distribution runs through direct technical sales for major food manufacturers, wholesale distributors for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing legacy crystallization methods, rewarding early equipment adopters with EU Green Deal traceability compliance and regional sourcing flexibility.
For Market Incumbents: Lock in feedstock security through backward integration into oilseed crushing or long-term distillate supply agreements with major refiners. BASF SE and Cargill must defend against modular toll processors by embedding application development teams with German spread manufacturers, converting technical service relationships into exclusive formulation partnerships.
For New Entrants and Emerging Players: Enter via Poland's private-label spread corridor, where EFSA claim awareness lags Western markets and price-sensitive buyers seek cost-optimized sterol ester alternatives. Target compound feed applications in Romania and Spain for volume base, then migrate toward pharmaceutical-grade specifications through crystallization technology licensing from Dutch equipment specialists.
For Investors and Strategic Acquirers: EFSA scientific opinion updates tightening claim substantiation requirements is the leading indicator that pharmaceutical-grade purity capabilities will command acquisition premiums. Five-to-ten year viability favors toll processors with supercritical extraction assets and integrated sustainability auditing. Monitor REACH registration timelines for novel sterol derivatives as the signal for formulation pipeline congestion.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Modular plant footprints enable EU Green Deal traceability compliance for regional oilseed sourcing. |
| EFSA Article 14 Claim Portfolio Expansion | Dual-claim formulations combining sterols with omega-3 justify premium positioning in French retail. |
| Pharmaceutical-Grade Purity Certification | 99%+ sterol specifications with ICH Q3D compliance unlock Swiss clinical nutrition contracts. |
| Poland Distribution Infrastructure | Proximity to underpenetrated private-label spread manufacturers captures volume beyond German saturation. |
| Tall Oil Pitch Feedstock Integration | Nordic pulp mill partnerships reduce vegetable oil price cycle exposure for esterified product lines. |
Research Methodology
EFSA scientific opinion databases, REACH registration filings, and EU customs trade statistics formed the secondary backbone for this study. Primary fieldwork incorporated structured interviews with food fortification R&D directors, Rotterdam-based ingredient procurement managers, Swiss clinical nutrition contract manufacturers, and Dutch supercritical extraction equipment specialists. Bottom-up volume modeling from application-level consumption data triangulated against top-down value estimates derived from trade flow analysis.
Historical trendline analysis established baseline growth patterns across functional food, dietary supplement, and pharmaceutical application segments. The projection framework modeled sterol form splits, purity grade tiers, and end-use industry demand clusters across the analysis window. CAGR derivation incorporated EFSA claim approval timelines, oilseed supply elasticity, and regulatory compliance cost trajectories specific to European phytosterol value chains.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA opinion reversals or vegetable oil supply disruptions. Model outputs reflect documented assumptions regarding claim substantiation protocols and upstream certification adoption rates. Material deviation in EFSA scientific opinion direction or REACH enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Potato Fiber Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Mirepoix Market
Ingredients
Passion Fruit Powder Market
Ingredients
Peanut Ingredients Market
Ingredients
Cooking Oils and Fats Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Africa Food Ingredients Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Citrus Fiber Market
Ingredients
Cocoa Market
Ingredients
Bay Leaf Oil Market
Ingredients
Europe Amino Acid Market
Ingredients
Arrowroot Starch Market
Ingredients
Pumpkin Seed Protein Market