
 Chocolate Based Spreads Market | 2026-2036
Chocolate Based Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Based Spreads Market Analysis
ISO 22000 certification for food safety management systems is reorganizing competitive access in chocolate based spreads, raising barriers for unqualified suppliers. Ferrero International SpA leverages its vertically integrated hazelnut supply chain to sustain premium positioning. The Hershey Company anchors North American distribution through controlled retail partnerships. Mondelēz International competes on manufacturing scale across multiple continental markets.
Chocolate based spreads are emulsified fat-sugar suspensions typically containing 25-35% vegetable oil and 7-13% cocoa solids, produced through conching and tempering processes to achieve stable viscosity and shelf life. The products serve as ready-to-eat toppings and industrial baking ingredients. Creamy formulations dominate volume sales while dark chocolate variants command higher per-unit margins due to elevated cocoa content positioning. Glass jar packaging retains premium channel preference though plastic containers are capturing food service and wholesale segments through lower breakage rates and logistics efficiency.
EFSA governs additive authorizations and cocoa butter equivalency standards while REACH regulates chemical inputs in processing equipment and packaging materials. FDA oversight applies to imports entering United States distribution channels. These frameworks shape formulation flexibility, label claim permissibility, and cross-border market access. Stakeholders must monitor evolving cocoa sustainability disclosure requirements and alternative fat labeling rules that will determine which product architectures retain commercial viability.
Market Dynamics
The EU's F-Gas Regulation is forcing refrigeration-dependent manufacturers to reformulate emulsion stability parameters while hazelnut supply concentration in Turkey reshapes input cost predictability across European production networks.
Growth Catalysts
- Artisanal Bakery Expansion:Germany's private-label retail programs are expanding shelf space allocations for premium spreads, creating pull-through demand for higher-margin formulations in adjacent EU markets.
- REACH Chemical Standards:ECHA's evolving packaging material classifications are accelerating migration-safe barrier film adoption, opening specification windows for compliant suppliers.
- Clean-Label Cocoa Processing:Mechanical conching refinements are displacing chemical lecithin dependence in viscosity control, satisfying retailer procurement criteria for reduced additive portfolios.
Market Restraints
- Hazelnut Supply Concentration:Turkish growers control roughly 70% of global output, exposing processors to climate-driven crop volatility and currency fluctuation pass-through.
- Vegetable Oil Input Costs:Palm and sunflower oil price swings directly compress formulation margins, with limited substitution flexibility due to crystallization behavior requirements.
- ISO 22000 Certification Barriers:The food safety management standard excludes smaller regional producers from retail distribution contracts, consolidating shelf access among qualified multinationals.
Strategic Opportunities
- Dark Chocolate Positioning:Elevated cocoa content variants command premium pricing bandwidth, with German and French consumers demonstrating willingness-to-pay for bitterness-calibrated formulations.
- Food Service Plastic Migration:Breakage-resistant containers are capturing institutional bakery and hotel channel volumes, displacing glass jar dominance in B2B procurement specifications.
- Sustainability Disclosure Mandates:Evolving EU cocoa traceability requirements favor early adopters with integrated farm-to-jar tracking infrastructure.
Industry Challenges
- Tempering Technician Scarcity:Precision viscosity control requires specialized operators, with vocational pipeline gaps constraining production line expansion timelines.
- Legacy Equipment Retrofit Costs:F-Gas-compliant refrigeration and conching system upgrades demand capital deployment that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Based Spreads Market |
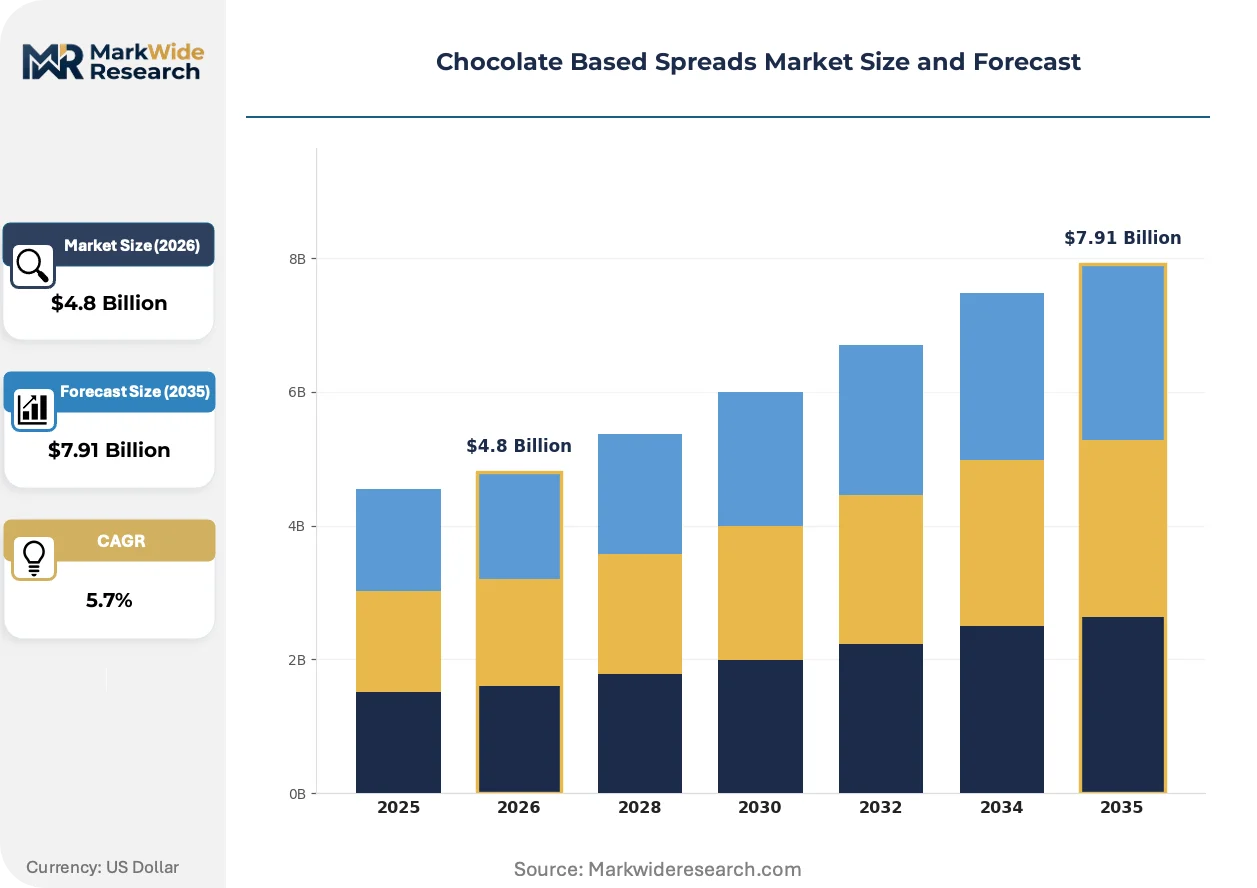
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy, Crunchy, Dark Chocolate, Milk Chocolate End User: Retail Consumers, Food Service, Bakeries, Confectioneries Packaging Type: Glass Jars, Plastic Containers, Pouches, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Ferrero International SpA, The Hershey Company, Nestlé S.A., Mondelēz International, Inc., Mars, Incorporated, Unilever, Premier Foods plc, The Kraft Heinz Company, Barry Callebaut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Based Spreads Market Emerging Trajectories
Formulation science and regulatory compliance are converging to redefine product architecture, with viscosity control technologies and packaging material specifications undergoing simultaneous transformation.
High-pressure processing equipment is miniaturizing for mid-scale confectionery lines, enabling pasteurization-level shelf life extension without thermal degradation of volatile aromatic compounds. Regional German producers are piloting these systems to support clean-label positioning. The technology is miniaturizing capital barriers that previously reserved extended stability to industrial-scale manufacturers.
REACH Annex XVII restrictions on phthalate plasticizers in food-contact materials are compelling polypropylene jar reformulation and accelerated silicone sealant qualification timelines. German packaging converters face the steepest compliance curves given their concentration in private-label supply chains. Bakery ingredient distributors are responding with dual-sourcing mandates to ensure continuity.
Direct-to-food-service procurement is consolidating purchase authority among national bakery chains, compressing traditional wholesaler intermediation. Industrial ingredient buyers now specify viscosity ranges and cocoa solid percentages in annual tenders rather than accepting manufacturer-standard grades. This pattern is most pronounced in France's frozen viennoiserie sector, where procurement teams centralize spread specifications across franchise networks.
Chocolate Based Spreads Market Segmentation
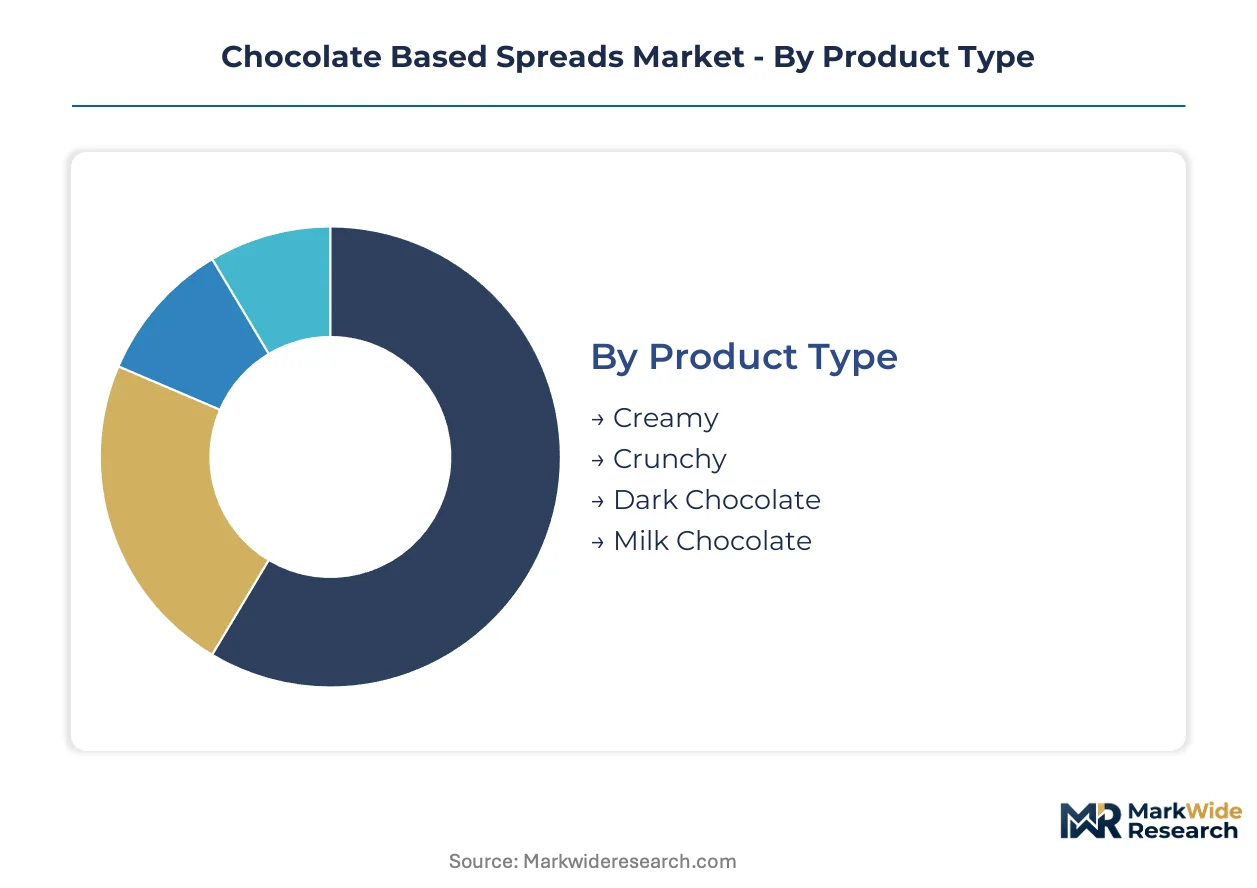
Chocolate based spreads stratify across formulation, channel, and packaging architectures that determine margin capture and shelf positioning. Distinct viscosity specifications and regulatory compliance requirements separate premium formulations from commodity-grade alternatives.
Product Type:
Highest per-unit margins concentrate in cocoa-forward variants where ingredient cost premiums translate directly to pricing bandwidth.
- Creamy:Emulsified fat-sugar suspensions with 25-35% vegetable oil content achieve stable viscosity through conching processes. German retail chains allocate expanded shelf space to creamy SKUs in private-label programs, driven by breakfast topping demand and industrial baking ingredient procurement.
- Dark Chocolate:Elevated cocoa solids content (typically 13%+) commands premium positioning through bitterness-calibrated formulations. French and German consumers demonstrate sustained willingness-to-pay for reduced-sugar, high-cocoa variants in specialty retail channels.
- Crunchy:Textured formulations incorporating hazelnut fragments target sensory differentiation in premium tiers.
- Milk Chocolate:Lower cocoa content variants dominate volume sales through family-oriented positioning and broader price accessibility.
The dominant share belongs to Creamy formulations, while Dark Chocolate is closing the gap fastest.
End User:
Procurement authority is shifting toward institutional buyers who specify viscosity ranges and cocoa percentages in annual tenders.
- Bakeries:Industrial ingredient buyers in Germany's artisanal bakery chains centralize spread specifications across franchise networks, requiring precise emulsion stability for frozen viennoiserie applications. EFSA additive authorizations constrain formulation flexibility for cross-border supply.
- Food Service:Hotel and institutional channels prioritize breakage-resistant packaging and bulk viscosity consistency. Procurement teams specify cocoa solid percentages rather than accepting manufacturer-standard grades.
- Retail Consumers:Household purchase decisions respond to clean-label positioning and sustainability disclosure mandates.
- Confectioneries:Industrial processors utilize spreads as enrobing and filling ingredients with stringent tempering requirements.
Bakeries command the largest volume absorption, with Food Service expanding most quickly through procurement centralization.
Packaging Type:
REACH Annex XVII compliance costs are restructuring competitive access across material categories.
- Glass Jars:Premium channel preference persists in retail environments where breakage risk is controlled. German packaging converters face accelerated silicone sealant qualification timelines under evolving ECHA classifications.
- Plastic Containers:Polypropylene jar reformulation is displacing glass dominance in B2B procurement. Lower breakage rates and logistics efficiency capture food service and wholesale segment volumes.
- Pouches:Flexible formats target single-serve and travel-oriented consumption occasions.
- Sachets:Portion-controlled packaging serves hotel breakfast and airline catering channels.
Glass Jars retain premium positioning, though Plastic Containers are gaining share fastest through food service migration.
Distribution Channel:
Direct-to-food-service procurement is compressing traditional wholesaler intermediation.
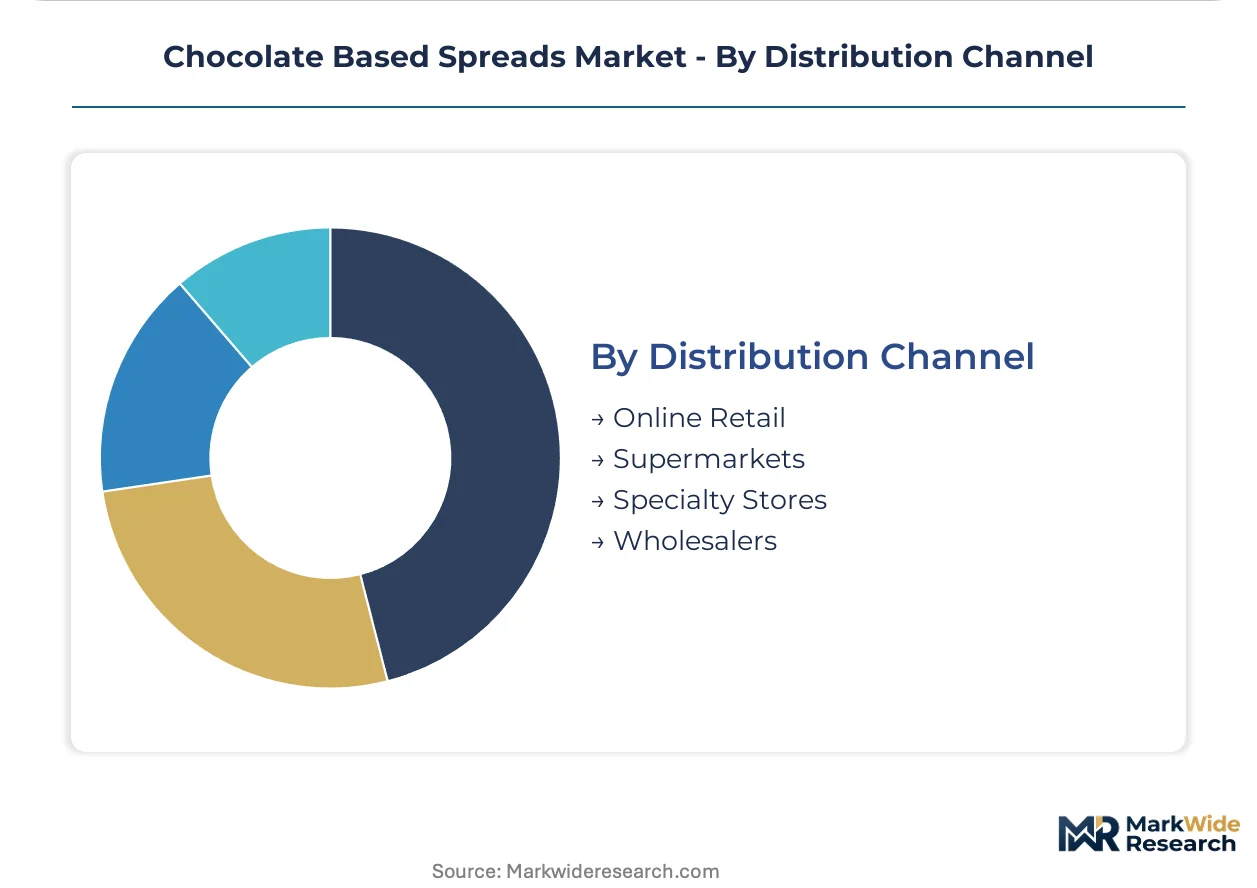
- Supermarkets:Controlled retail partnerships anchor volume distribution, with ISO 22000 certification requirements excluding unqualified suppliers from shelf access.
- Online Retail:Digital channels enable premium variant discovery and subscription-based replenishment models.
- Specialty Stores:Curated assortments emphasize dark chocolate positioning and artisanal provenance claims.
- Wholesalers:Traditional intermediation faces margin compression as national bakery chains consolidate purchase authority.
Supermarkets maintain the deepest penetration, while Online Retail is climbing the fastest through premium SKU expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisanal bakery chains and private-label retail programs concentrate procurement authority in Germany, while regulatory compliance requirements reshape competitive access across multiple jurisdictions.
Germany
Artisanal bakery chains and private-label retail programs drive premium spread demand through expanded shelf space allocations. EFSA additive authorizations constrain formulation flexibility for cross-border supply. The Cologne-Düsseldorf corridor hosts concentrated private-label manufacturing infrastructure serving EU distribution networks.
France
Frozen viennoiserie procurement teams centralize spread specifications across franchise networks, demanding precise emulsion stability. REACH Annex XVII restrictions on phthalate plasticizers compel packaging material reformulation. The Paris basin concentrates industrial bakery ingredient distribution with stringent viscosity requirements.
United States
Controlled retail partnerships anchor volume distribution through ISO 22000 certification requirements that exclude unqualified suppliers. FDA oversight applies to imports entering distribution channels. The Chicago metropolitan area hosts major confectionery processing infrastructure with tempering specialization.
Turkey
Hazelnut growers control roughly seventy percent of global output, exposing processors to climate-driven crop volatility. The country's national agricultural regulator monitors export quality standards for nut-based ingredients. The Black Sea region concentrates hazelnut cultivation with direct supply relationships to European processors.
Switzerland
Clean-label cocoa processing investments displace chemical lecithin dependence in viscosity control. Swissmedic maintains food-contact material safety standards for premium chocolate products. The Lake Geneva region hosts specialized conching equipment manufacturing serving mid-scale confectionery lines.
Chocolate Based Spreads Market Vendor Landscape
Player mix skews toward vertically integrated multinationals with captive ingredient supply and manufacturing scale advantages. The competitive structure consolidates around three tiers: premium-positioned specialists with controlled raw material access, mass-market manufacturers competing on distribution breadth, and private-label suppliers serving retailer-owned brands. Dominant competitive moves include backward integration into hazelnut sourcing and capacity expansion in F-Gas-compliant processing facilities.
Within the premium-positioned tier, Ferrero International SpA exemplifies vertical control through its hazelnut supply chain architecture. The Hershey Company occupies a position representing North American distribution consolidation through controlled retail partnerships. Mondelēz International sits within the scale-driven multinational archetype competing across multiple continental manufacturing footprints.
| Leading Market Players |
|---|
| Ferrero International SpA |
| The Hershey Company |
| Nestlé S.A. |
| Mondelēz International, Inc. |
| Mars, Incorporated |
| Unilever |
| Premier Foods plc |
| The Kraft Heinz Company |
| Barry Callebaut |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Turkish hazelnut processing facilities shapes both raw material availability floors and contract pricing structures across European chocolate spread manufacturing networks. Mondelēz International and Ferrero International SpA leverage captive roasting capacity to buffer against spot market volatility, while mid-scale processors absorb margin compression through formula adjustments.
Pricing Analysis
Cost-plus contracts with vegetable oil indexation dominate procurement between German private-label manufacturers and Turkish hazelnut suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified multinationals from regional processors and commodity importers. Pricing pressure stems from palm oil price volatility and REACH compliance costs in packaging materials. Food service buyers exhibit highest price sensitivity due to annual tender specifications, while specialty retail channels absorb premiums for dark chocolate variants.
Supply Chain Analysis
Black Sea transit corridors underpin hazelnut delivery reliability to European conching facilities, with Istanbul port congestion periodically disrupting just-in-time schedules. Turkish growers, Italian processors, and German packagers anchor the upstream-to-downstream flow. Raw material dependencies center on hazelnut paste, cocoa butter equivalents, and sunflower lecithin. Single-source vulnerability concentrates in Turkish hazelnut supply, where climate-driven crop failures cascade through formulation costs. Distribution runs through controlled retail partnerships and direct-to-bakery procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against plant-based and nut-butter alternatives that capture clean-label positioning. Incumbents must navigate reformulation threats while preserving emulsion stability credentials.
For Market Incumbents: Fortify hazelnut supply security through backward integration into Turkish cultivation networks or long-term offtake agreements with Black Sea cooperatives. Accelerate F-Gas-compliant equipment retrofit timelines before regulatory deadlines consolidate shelf access among qualified multinationals. ISO 22000 certification investment remains essential for retail contract retention.
For New Entrants and Emerging Players: ISO 22000 fast-track programs through accredited German certification bodies unlock private-label supply opportunities with Cologne-Düsseldorf corridor manufacturers. Food service plastic packaging specifications present the most penetrable white space, with breakage-resistant polypropylene containers displacing glass jar dominance in hotel and institutional channels. Target direct procurement relationships with frozen viennoiserie chains seeking viscosity-calibrated formulations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among private-label suppliers with multi-year retailer contracts and captive hazelnut processing infrastructure. Long-term viability favors processors with integrated farm-to-jar traceability systems compliant with evolving EU cocoa sustainability mandates. Watch for inflection signals in dark chocolate variant adoption rates across German and French specialty retail channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hazelnut Sourcing | Captive supply from Turkish Black Sea region insulates against climate-driven crop volatility. |
| F-Gas-Compliant Equipment Upgrade | Refrigeration system retrofit preserves retail distribution access under EU regulatory deadlines. |
| Clean-Label Conching Refinement | Mechanical viscosity control displaces chemical lecithin to satisfy retailer procurement criteria. |
| Food Service Packaging Migration | Breakage-resistant polypropylene containers capture institutional bakery and hotel channel volumes. |
| Farm-to-Jar Traceability Infrastructure | Integrated tracking systems align with EU cocoa sustainability disclosure mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with German bakery procurement directors, Turkish hazelnut cooperative managers, Italian conching equipment specialists, and French frozen viennoiserie franchise operators. Secondary validation drew from EFSA additive authorization databases, REACH Annex XVII regulatory filings, EU customs trade statistics for cocoa and hazelnut imports, and Nielsen retail audit data for spread category performance. Bottom-up volume modeling triangulated against top-down value estimates derived from manufacturer capacity disclosures.
The projection horizon spans the full analysis window with annual interval granularity. Segmentation dimensions include formulation type, end-use application, packaging material, and distribution channel, with additional modeling for regulatory compliance tier. CAGRs were computed from year-over-year growth trajectories adjusted for input cost inflation and capacity expansion timelines. Forecast inputs incorporated hazelnut harvest yield variability, vegetable oil price index movements, and F-Gas Regulation implementation schedules.
Decision-makers should treat outputs as directional under stable Turkish hazelnut supply and unchanged REACH packaging classifications; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU cocoa traceability mandates and alternative fat labeling rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Rice Noodles Market
Packaged Foods
North America Chewing Gum Market