
 Food Grade Activated Carbon Market | 2026-2036
Food Grade Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Activated Carbon Market Foresight
Capital-intensity divergence between steam-activation and chemical-activation asset bases is bifurcating competitive economics in food-grade activated carbon. Kuraray Co., Ltd. leverages its integrated precursor supply chain to sustain cost advantages in coconut-shell granular production. Cabot Corporation anchors North American distribution density through its Calgon Carbon subsidiary, while Jacobi Carbons Group specializes in pharmaceutical-grade extruded formats that command premium positioning.
Food grade activated carbon comprises thermally or chemically activated carbonaceous material with controlled pore distribution, typically exhibiting iodine numbers exceeding 800 mg/g and meeting food-contact compliance standards for adsorption of pigments, off-flavors, and process contaminants. Powdered variants dominate sugar refining and edible oil purification due to rapid kinetics and low capital deployment, while pelletized formats capture expanding share in continuous beverage filtration systems where pressure-drop management determines operational economics. Granular coconut-shell grades retain margin concentration in high-purity pharmaceutical and cosmetic applications where residual ash tolerance tightens.
FDA food-contact substance notifications and EFSA food additive evaluations shape product registration pathways and reformulation requirements for suppliers targeting regulated jurisdictions. BIS certification requirements in India and China's GB standards for food-processing materials add compliance layers that favor producers with multi-jurisdictional testing infrastructure. Stakeholders must track evolving EU Green Deal constraints on activation-energy sourcing and precursor traceability, as these will increasingly determine supply-qualification thresholds for multinational food and beverage procurement teams.
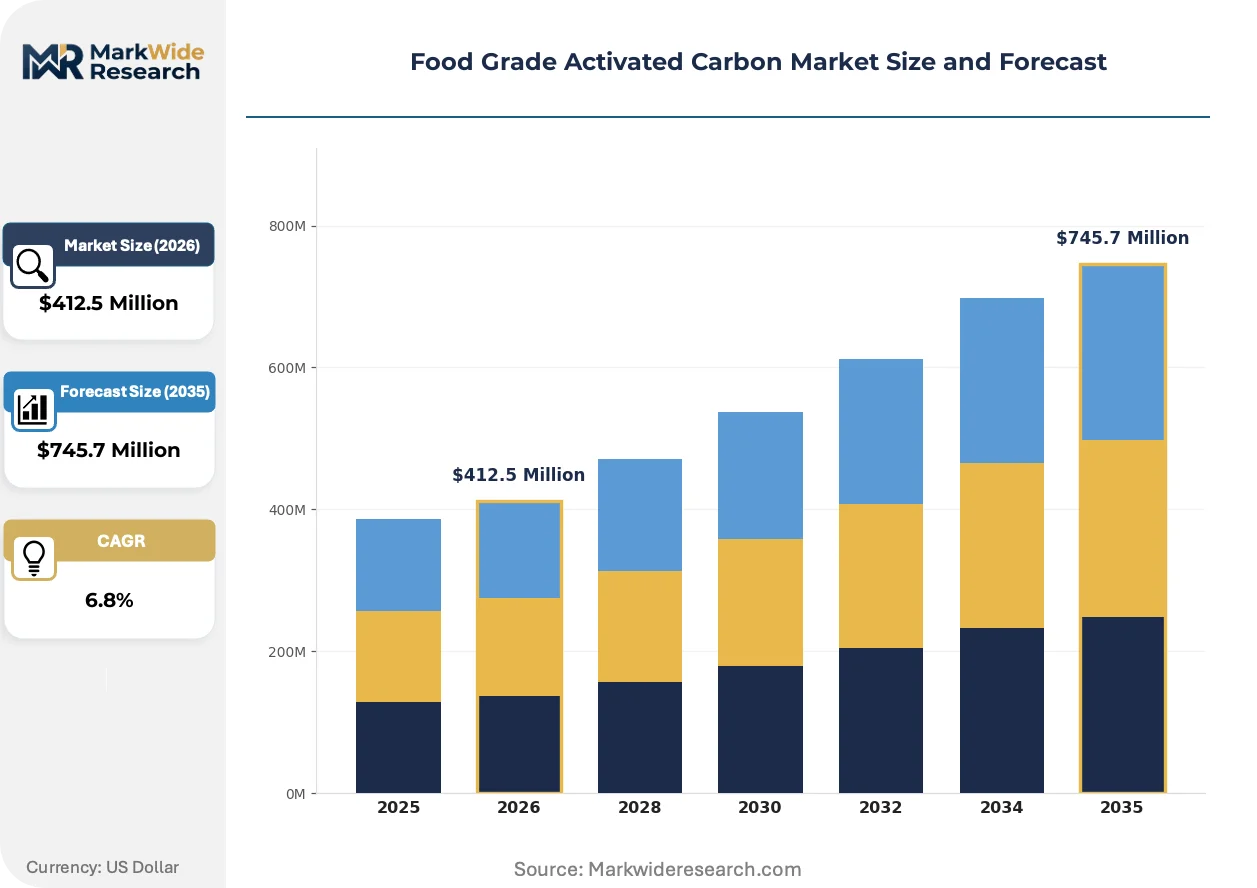
Market Dynamics
Steam-activation and chemical-activation asset bases diverge in capital intensity, bifurcating competitive economics as energy costs reshape plant location decisions and precursor sourcing strategies.
Growth Catalysts
- FDA Food-Contact Substance Notifications:Tightening purity mandates for decolorization and contaminant removal in beverage manufacturing accelerate qualification demand for compliant carbon grades.
- Coconut-Shell Granular Production:Integrated precursor supply chains in Southeast Asia sustain cost advantages for high-iodine-number grades serving pharmaceutical and cosmetic applications.
- German Production Clusters:Specialized manufacturing concentrations around Donau Carbon GmbH and CarboTech AC GmbH anchor premium supply capacity for European food and beverage procurement.
Market Restraints
- Coconut Shell Price Volatility:Precursor availability fluctuates with agricultural harvest cycles and competing demand from metallurgical coke production.
- Activation Energy Sourcing:EU Green Deal constraints on fossil-fuel-derived process heat threaten cost structures for European steam-activation facilities.
- Powdered Format Limitations:Rapid kinetics advantages in batch processing face pressure from continuous system automation favoring pelletized formats.
Strategic Opportunities
- India BIS Certification Pathways:Multi-jurisdictional testing infrastructure investments unlock qualified supplier status for domestic food-processing material standards.
- Continuous Beverage Filtration:Pressure-drop management requirements in automated bottling lines expand addressable market for extruded pellet formats.
- China GB Standards Alignment:Food-processing material compliance layers favor producers with established analytical capabilities for GB testing protocols.
Industry Challenges
- Multi-Jurisdictional Testing Infrastructure:EFSA food additive evaluations, FDA notifications, and national certification requirements demand dedicated regulatory affairs capacity.
- Legacy Batch Processing Integration:Powdered carbon users in sugar refining and edible oil purification face capital barriers migrating to continuous system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Activated Carbon Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powdered, Pelletized, Extruded Application: Beverage Purification, Sugar Refining, Food Additive Removal, Edible Oil Purification, Flavor Enhancement End User: Food Processing Plants, Beverage Manufacturers, Pharmaceutical Companies, Cosmetic Producers Packaging Type: Bag, Drum, Bulk Container, Cartridge |
| Companies Covered | Kuraray Co., Ltd., Cabot Corporation, Calgon Carbon Corporation, Haycarb PLC, Donau Carbon GmbH, Jacobi Carbons Group, Osaka Gas Chemicals Co., Ltd., Kureha Corporation, CarboTech AC GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Activated Carbon Market Shifts & Advancements
Activation technology evolution and regulatory compliance architectures are compressing supplier margins while opening premium positioning for traceable, low-ash production methods.
Microwave-assisted regeneration technology is fragmenting traditional thermal reactivation economics. Beverage bottlers in Germany and Switzerland adopt on-site carbon recovery systems to reduce virgin material consumption. This distributed reactivation model is fragmenting centralized supply relationships and compressing spot-market volumes for standard granular grades.
EFSA food additive evaluations now mandate expanded contaminant testing for polycyclic aromatic hydrocarbons and heavy metals. European suppliers face reformulation requirements to meet tightened purity thresholds for food-contact applications. Coconut-shell producers with integrated analytical laboratories capture premium positioning against coal-based competitors lacking equivalent traceability documentation.
Certification-driven preference shifts now dominate multinational procurement decisions. Food and beverage manufacturers in the United States prioritize suppliers with simultaneous FDA food-contact substance notifications and third-party kosher/halal certifications. This multi-credential requirement filters the qualified supplier base and extends sales cycle duration for new market entrants lacking established regulatory dossiers.
Food Grade Activated Carbon Market Segmentation
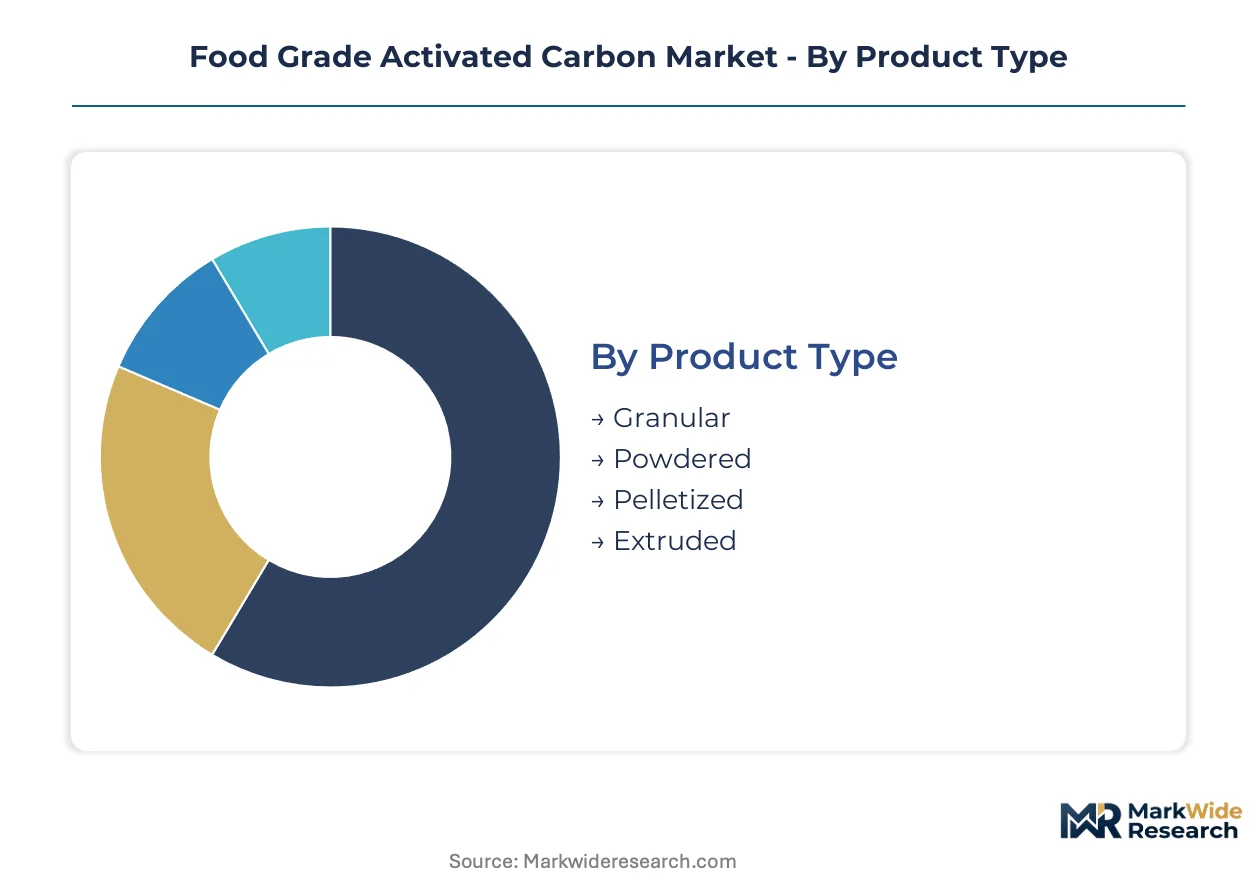
Product format selection in food-grade activated carbon directly determines capital deployment patterns and regeneration economics across processing facilities. Procurement teams segment supplier qualification by pore distribution specifications, activation method traceability, and compliance documentation depth rather than commodity pricing alone.
Product Type:
Powdered formats dominate domestic sugar refining and edible oil operations where batch processing prevails, while pelletized and extruded grades concentrate in export-oriented beverage filtration infrastructure serving multinational bottlers.
- Granular:Coconut-shell-derived granular carbon exhibits iodine numbers exceeding 900 mg/g with tight ash tolerance, commanding premium positioning in German pharmaceutical and cosmetic applications where EFSA purity thresholds are most stringent.
- Powdered:Rapid adsorption kinetics suit batch decolorization in sugar refineries and edible oil plants; deployment favors facilities with legacy infrastructure unable to justify continuous system migration capital.
- Pelletized:Uniform particle sizing enables pressure-drop optimization in automated beverage bottling lines.
- Extruded:High mechanical strength supports repeated thermal regeneration cycles in centralized carbon recovery services.
Powdered carbon commands the established base in batch processing industries. The steepest expansion runs through pelletized formats as continuous beverage filtration displaces legacy architectures.
Application:
Cost tier stratification separates commodity decolorization from premium contaminant removal, with beverage applications absorbing higher unit economics for certification documentation and pharmaceutical-grade traceability.
- Beverage Purification:Decolorization and off-flavor removal in bottled water, wine, and juice processing; FDA food-contact substance notifications and kosher/halal certifications filter qualified supplier pools and extend procurement cycles.
- Sugar Refining:Molasses pigment adsorption and ash reduction in cane and beet sugar production; powdered carbon dominates due to rapid kinetics and minimal capital barrier for seasonal campaign operations.
- Food Additive Removal:Process contaminant scrubbing in intermediate food ingredient manufacturing.
- Edible Oil Purification:Bleaching earth complementation for carotenoid and chlorophyll removal in palm, soybean, and sunflower oil refining.
- Flavor Enhancement:Selective adsorption of bitter compounds and off-notes in fermentation-derived ingredients.
Sugar refining absorbs the highest volume base. The steepest expansion trajectory is gaining share fastest in beverage purification as clean-label positioning intensifies contaminant scrutiny.
End User:
Customer type determines contract structure, with pharmaceutical and cosmetic producers demanding dedicated batch traceability while food processors prioritize spot-market flexibility for seasonal campaigns.
- Food Processing Plants:Seasonal campaign economics in sugar and oil refining favor flexible procurement with spot-market powdered carbon sourcing.
- Beverage Manufacturers:Continuous filtration operations in automated bottling lines drive pelletized format qualification and long-term supply agreements with regeneration service integration.
- Pharmaceutical Companies:German and Swiss facilities impose the tightest residual ash and heavy metal specifications, capturing margin concentration for coconut-shell granular suppliers with integrated analytical laboratories.
- Cosmetic Producers:Low-ash granular grades for color cosmetic and oral care applications where EFSA cosmetic ingredient evaluations overlap with food-contact compliance requirements.
Food processing plants anchor volume concentration. The steepest expansion is climbing the fastest among beverage manufacturers as on-site regeneration systems fragment traditional supply relationships.
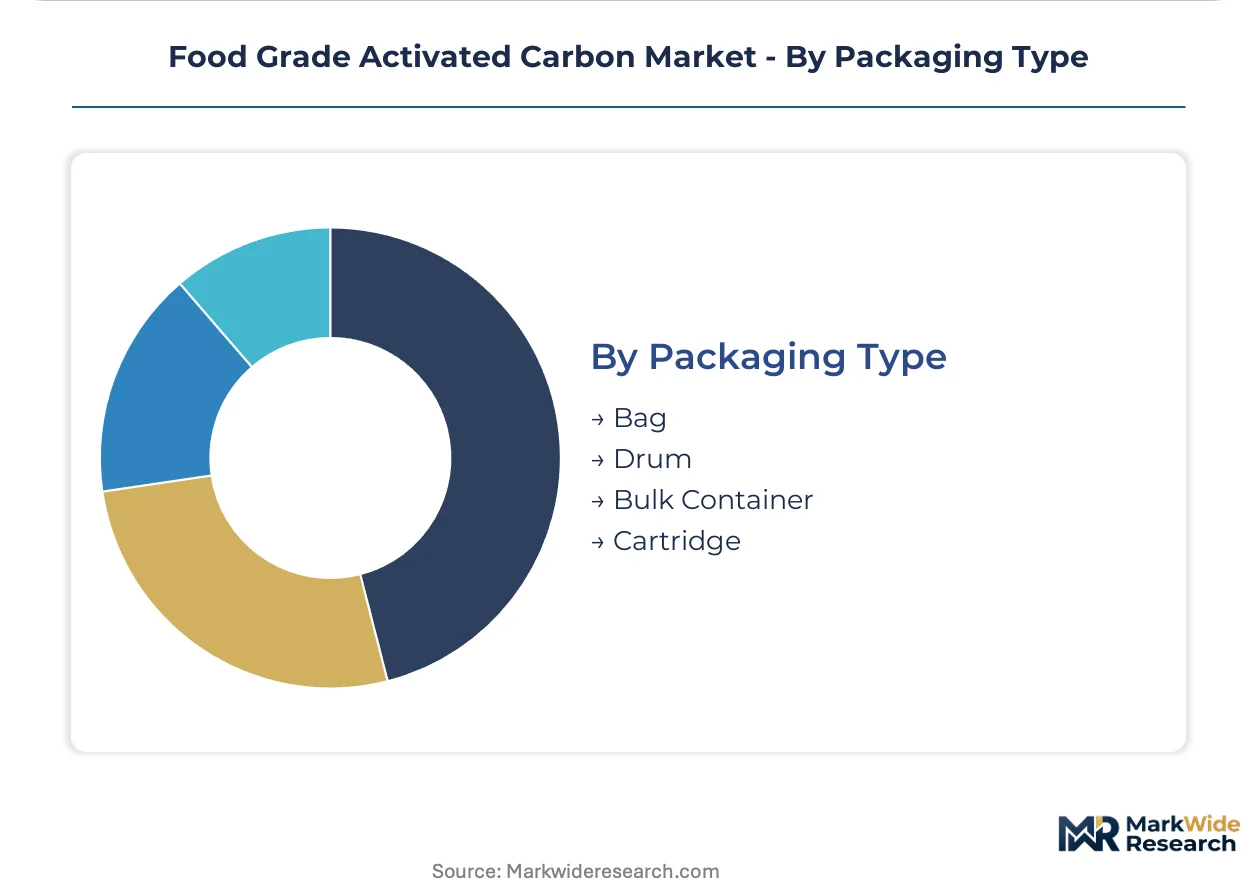
Packaging Type:
Volume scale and handling automation requirements separate bulk container deployments in large refineries from cartridge formats in pilot-scale pharmaceutical operations.
- Bag:Standard 25 kg multi-wall paper bags for powdered carbon in batch processing facilities with manual handling infrastructure.
- Drum:Steel and fiber drums for granular and pelletized grades requiring moisture protection during extended storage.
- Bulk Container:Flexible intermediate bulk containers and pneumatic discharge systems for high-volume sugar refineries and oil processing plants with automated material handling.
- Cartridge:Pre-packed filter elements for beverage bottling line integration and pharmaceutical pilot-scale operations where changeover speed determines operational economics.
Bulk containers dominate volume throughput in large-scale refining. The steepest expansion is gaining share fastest in cartridge formats as point-of-use filtration modularizes system design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland absorb steep premiums for EFSA-certified low-ash grades, while Indian sugar refiners and Chinese edible oil processors prioritize spot-market powdered carbon sourced through trading houses.
Germany
Pharmaceutical and cosmetic manufacturers in Baden-Württemberg and North Rhine-Westphalia drive qualification-intensive procurement for coconut-shell granular grades. EU Green Deal activation-energy constraints are forcing steam-activation facilities toward renewable process heat investments. The specialized production cluster around Donau Carbon GmbH and CarboTech AC GmbH in the Ruhr region anchors premium supply capacity for European beverage bottlers.
United States
Continuous beverage filtration automation in California and Texas bottling corridors expands pelletized carbon demand. FDA food-contact substance notifications filter qualified supplier pools, extending procurement cycles for multinational food manufacturers. Chicago and Atlanta distribution hubs concentrate Calgon Carbon subsidiary logistics serving North American sugar refineries and edible oil processors.
China
Edible oil purification plants in Shandong and Guangdong provinces absorb high-volume powdered carbon for bleaching earth complementation. GB standards for food-processing materials add compliance layers favoring domestic producers with established analytical capabilities. Yangtze River Delta chemical activation facilities face margin pressure from coconut shell precursor import dependence.
India
Seasonal sugar campaign economics in Maharashtra and Uttar Pradesh favor flexible spot-market powdered carbon procurement. BIS certification requirements for food-contact materials unlock qualified supplier status for producers with multi-jurisdictional testing infrastructure. Gujarat edible oil refineries concentrate demand for rapid-kinetics decolorization grades during peak processing windows.
Japan
Pharmaceutical-grade traceability requirements in Osaka and Tokyo metropolitan areas sustain premium positioning for high-iodine-number granular suppliers. METI energy-efficiency guidelines shape activation facility investment decisions toward lower-carbon process heat. Kansai region carbon regeneration service providers are fragmenting traditional virgin material supply relationships through on-site recovery system deployment.
Food Grade Activated Carbon Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated precursor operators sustaining margin advantages against distributed reactivation service entrants. The vendor base compresses around three strategic tiers: multinational chemical conglomerates with carbon divisions, specialized activated carbon pure-plays, and regional trading houses with blending capabilities. Dominant competitive moves include backward integration into coconut-shell precursor supply chains and geographic expansion through distribution partnerships in emerging certification-heavy jurisdictions.
Among Japanese chemical conglomerates with carbon operations, Kuraray Co., Ltd. and Osaka Gas Chemicals Co., Ltd. occupy positions exemplifying integrated production archetypes. German specialists Donau Carbon GmbH and CarboTech AC GmbH anchor the premium-tier European supply cluster. Cabot Corporation through its Calgon Carbon subsidiary represents the North American distribution-density model, while Jacobi Carbons Group sits within the pharmaceutical-grade specialization vector.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| Cabot Corporation |
| Calgon Carbon Corporation |
| Haycarb PLC |
| Donau Carbon GmbH |
| Jacobi Carbons Group |
| Osaka Gas Chemicals Co., Ltd. |
| Kureha Corporation |
| CarboTech AC GmbH |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day virgin carbon lead times in European pharmaceutical procurement compress pricing power toward integrated coconut-shell producers with captive precursor supply, while beverage bottlers in Germany and Switzerland absorb premiums for EFSA-certified low-ash grades that spot-market trading houses cannot replicate.
Pricing Analysis
Regeneration service contracts and carbon recovery subscriptions now drive lifetime value beyond virgin material transactions. Three-tier pricing structure across pharmaceutical-grade, food-contact-certified, and industrial-standard levels segments buyer pools, with FDA food-contact substance notifications and kosher/halal certifications commanding 15-25% premia over uncertified equivalents. Cost compression in standard powdered grades intensifies as microwave-assisted on-site regeneration displaces virgin replenishment cycles. Sugar refiners in India and edible oil processors in China exhibit highest price sensitivity due to seasonal campaign economics and spot-market procurement flexibility.
Supply Chain Analysis
Strategic stockpiling of coconut-shell precursor dominates Southeast Asian integrated producers, while European steam-activation facilities maintain lean just-in-time inventories vulnerable to energy price spikes. Manufacturing concentration in Indonesia, Philippines, and Sri Lanka feeds global granular supply, with German specialized clusters and North American distribution hubs completing downstream fulfillment. Raw material dependencies center on coconut-shell charcoal, phosphoric acid for chemical activation, and metallurgical-grade steam coal for process heat. Single-source vulnerability in Southeast Asian precursor harvests threatens supply continuity during El Niño drought cycles. Distribution runs through regional carbon regeneration service networks and direct mill-to-plant bulk contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food grade activated carbon faces substitution pressure from membrane filtration and advanced oxidation processes in beverage pretreatment stages, forcing incumbents to defend regeneration service relationships and certification moats.
For Market Incumbents: Fortify backward integration into coconut-shell precursor supply chains in Indonesia and the Philippines to neutralize harvest volatility exposure. Deepen EFSA and FDA regulatory dossiers ahead of tightened polycyclic aromatic hydrocarbon testing mandates. Lock in long-term regeneration service contracts with German and Swiss pharmaceutical manufacturers to create switching costs against membrane substitution. For New Entrants and Emerging Players: Differentiate on rapid BIS certification completion for Indian sugar refinery supply, where incumbent documentation gaps create qualification delays. Target cartridge-format pelletized carbon for automated Chinese beverage bottling lines, where continuous filtration automation outpaces legacy powdered carbon infrastructure. Pursue joint testing protocols with Gujarat edible oil refineries to establish rapid-kinetics credibility during peak processing windows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical-activation facilities facing EU Green Deal renewable energy retrofit requirements. Five-to-ten-year viability favors integrated precursor operators with analytical laboratory assets over pure-play reactivation service entrants. Acquisition targets should display simultaneous FDA notification completion and third-party kosher/halal certification. The signal to watch is EFSA contaminant threshold tightening, which accelerates supplier consolidation toward traceable low-ash producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive coconut-shell sourcing in Indonesia neutralizes harvest price volatility and secures margin concentration. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA, EFSA, and BIS dossier completion filters qualified supplier pools and extends procurement cycles. |
| On-Site Regeneration Service Deployment | Microwave-assisted carbon recovery in German beverage plants fragments traditional virgin supply relationships. |
| Continuous Filtration Format Expansion | Pelletized and extruded grades capture automated bottling line share from legacy powdered batch systems. |
| Analytical Laboratory Integration | In-house PAH and heavy metal testing accelerates EFSA compliance and commands pharmaceutical-grade premia. |
Research Methodology
A spread of perspectives from carbon plant operations managers, beverage procurement directors, pharmaceutical regulatory affairs leads, and edible oil refinery technical directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings of listed carbon producers, EFSA food additive evaluation registers, and BIS certification databases. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers across the projection horizon.
Segmentation dimensions modeled include product format (powdered, granular, pelletized, extruded), activation method (steam versus chemical), application tier (beverage purification, sugar refining, edible oil processing, pharmaceutical), and end-user procurement structure (spot-market versus long-term contract). CAGRs were derived from volume-demand elasticity analysis and price trajectory assumptions across the modeling period. Forecast inputs incorporated EU Green Deal energy transition timelines, FDA food-contact notification approval velocities, and coconut-shell harvest cycle patterns.
Material uncertainties — regulatory threshold revisions, El Niño-driven precursor shortages, and membrane filtration substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification-driven procurement inertia and regeneration service adoption curves. Revision becomes warranted when membrane filtration cost-performance crosses beverage pretreatment economic thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Europe and MEA Food Phosphate Market