
 India Starch and Starch Derivative Market | 2026-2036
India Starch and Starch Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
India Starch and Starch Derivative Market Foresight
Premium-grade modified starch specifications are reorganizing competitive dynamics in India's starch landscape. Sukhjit Starch & Chemicals Ltd leverages its Punjab-based corn processing infrastructure to dominate North Indian supply chains. Tirupati Starch & Chemicals Ltd anchors southern markets through specialized tapioca-derived offerings for textile sizing applications. Ingredion Incorporated competes via technology leadership in enzymatic modification processes tailored to Indian climatic conditions.
Starch and starch derivatives comprise carbohydrate polymers extracted from agricultural feedstocks through wet milling, enzymatic conversion, or chemical modification to achieve specific viscosity, gelatinization temperature, and retrogradation resistance profiles. These functional properties serve as binding, thickening, and film-forming agents across food manufacturing, pharmaceutical tableting, paper surface sizing, and textile warp sizing operations. Modified starch commands the deepest margin pools due to customization premiums for pharmaceutical and convenience food applications, while native starch remains volume-dominant in paper and corrugated board manufacturing where cost minimization governs procurement. Starch derivatives represent the fastest-expanding category as FSSAI-mandated clean-label requirements drive replacement of synthetic hydrocolloids in processed foods.
FSSAI purity standards, BIS ISI certification requirements, and CDSCO pharmaceutical excipient guidelines collectively determine market access thresholds and product differentiation possibilities for domestic manufacturers. The PLI scheme for food processing machinery indirectly accelerates capacity modernization among derivative producers seeking export qualification. Stakeholders must monitor evolving BIS specifications for resistant starch content and glycemic index labeling claims that will reshape R&D allocation across the value chain.
Market Dynamics
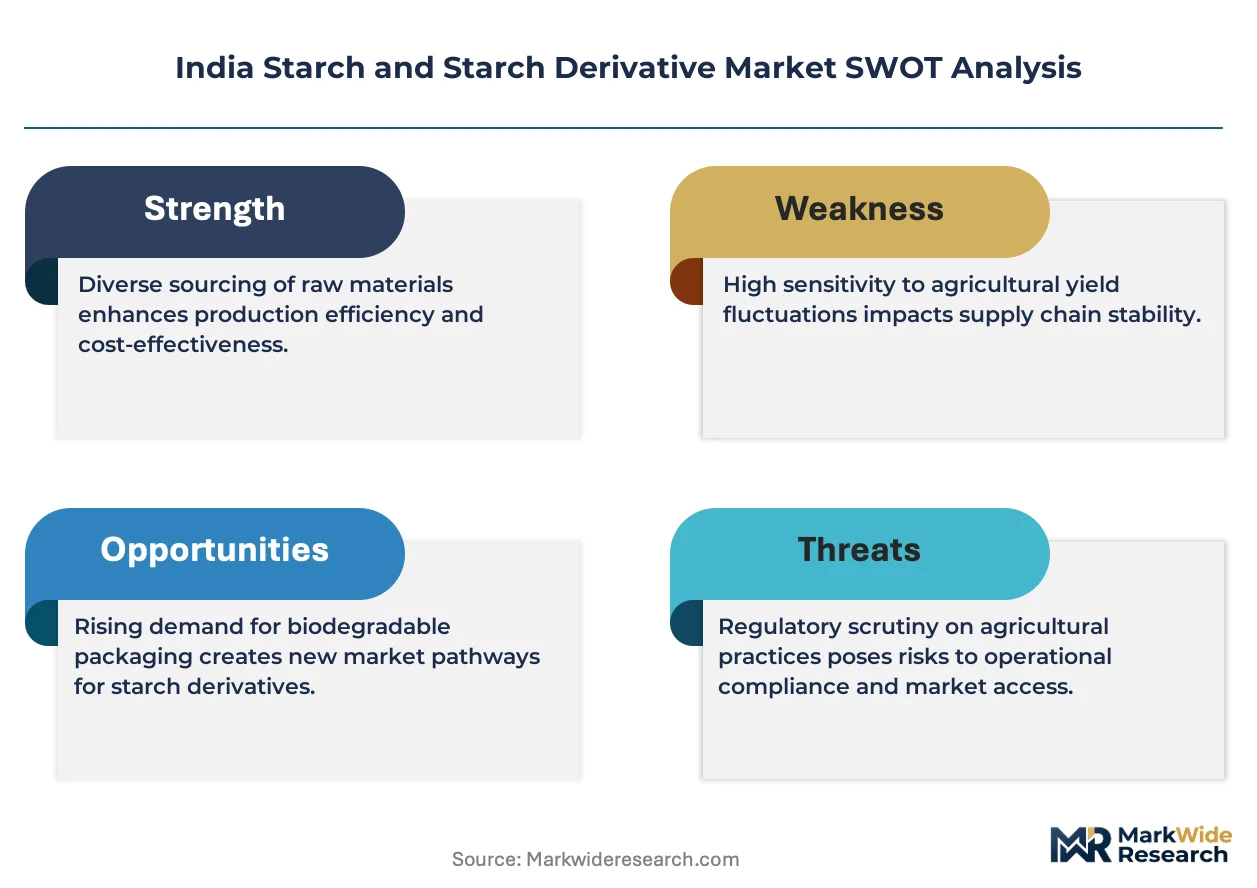
FSSAI clean-label mandates and BIS purity specifications are compressing margins for commodity-grade producers while rewarding enzymatic modification capabilities. Corn and tapioca processing clusters in Maharashtra, Gujarat, and Tamil Nadu concentrate feedstock access, creating geographic asymmetries in derivative supply.
Growth Catalysts
- PLI Scheme for Food Processing:Machinery modernization incentives accelerate derivative capacity upgrades among domestic manufacturers seeking export qualification under FSSAI-BIS alignment.
- Pharmaceutical Excipient Demand:CDSCO guidelines for tablet binding and controlled-release formulations pull pharmaceutical-grade modified starch into chronic disease medication production.
- Convenience Food Manufacturing:Western and southern India food processors expand modified starch procurement for ready-to-eat and frozen product lines requiring freeze-thaw stability.
Market Restraints
- Corn Feedstock Volatility:Monsoon-dependent corn harvests in Punjab and Haryana create input cost instability for North Indian wet milling operations.
- Technical Substitution Ceiling:Native starch cannot achieve the viscosity stability and retrogradation resistance required for pharmaceutical tableting, locking commodity producers out of premium segments.
- BIS Certification Friction:Resistant starch content testing protocols and glycemic index labeling claims extend product approval timelines for reformulated offerings.
Strategic Opportunities
- Northeast India Penetration:Underdeveloped tapioca processing infrastructure in Assam and Meghalaya offers first-mover positioning for integrated cultivation-to-derivative operations.
- Resistant Starch R&D:BIS specifications for dietary fiber claims create white space for enzymatically modified starches targeting functional food and nutraceutical applications.
- Textile Sizing Convergence:Tirupati Starch's tapioca-derived formulations demonstrate pathway for southern processors to capture synthetic polymer displacement in Tamil Nadu weaving clusters.
Industry Challenges
- Enzymatic Modification Talent Gap:Shortage of process engineers skilled in alpha-amylase and glucoamylase conversion optimization limits capacity expansion for pharmaceutical-grade output.
- Legacy Equipment Integration:Batch reactor systems in older Gujarat and Maharashtra facilities require capital-intensive retrofitting to achieve CDSCO excipient contamination standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Starch and Starch Derivative Market |
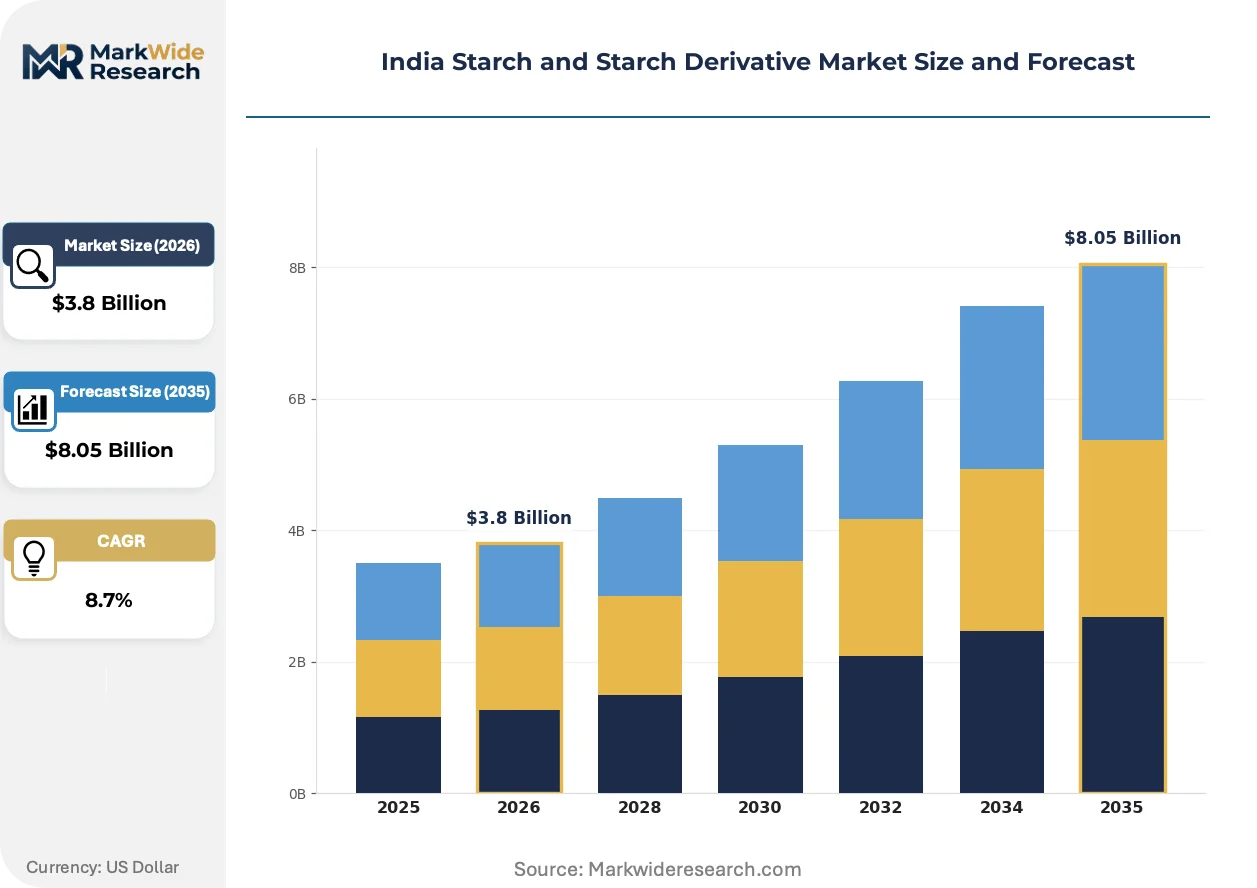
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Liquid Starch, Starch Derivatives End Use Industry: Food & Beverage, Pharmaceuticals, Paper, Textiles Form: Powder, Granule, Gel, Liquid Application: Thickening Agent, Stabilizer, Filler, Coating Agent |
| Companies Covered | Gulshan Polyols Ltd, Sukhjit Starch & Chemicals Ltd, Archer Daniels Midland Company, SBH Foods Pvt. Ltd., RDAI International Private Limited, Ingredion Incorporated, Tirupati Starch & Chemicals Ltd, Emarc India, Cargill Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Starch and Starch Derivative Market Shifts & Advancements
Enzymatic modification technologies and clean-label formulation requirements are restructuring competitive advantage around R&D depth rather than feedstock scale alone. Processors with in-house biotechnology capabilities capture widening margin premiums.
Dual enzymatic hydrolysis combining alpha-amylase and transglucosidase treatments is displacing single-enzyme processes for resistant starch production. Pharmaceutical formulators in Hyderabad and Bangalore adopt these modified starches for controlled-release tablet matrices. The technology is displacing chemically cross-linked starches in premium excipient applications where CDSCO purity thresholds apply.
FSSAI's 2023 clean-label guidelines for processed foods mandate disclosure of synthetic hydrocolloids, accelerating native and modified starch substitution in convenience food formulations. Food manufacturers in Maharashtra and Gujarat reformulate sauces, dressings, and frozen products to meet disclosure requirements. Bakery and dairy segments show fastest compliance response, with western India processors leading formulation shifts.
Direct procurement contracts between starch derivative producers and Maharashtra food processing clusters are compressing traditional trader-mediated distribution. Large convenience food manufacturers negotiate volume commitments with Sukhjit Starch and Tirupati Starch for modified starch supply security. This channel consolidation is most visible in Mumbai-Pune and Ahmedabad-Vadodara industrial corridors where buyer concentration enables specification customization.
India Starch and Starch Derivative Market Segmentation
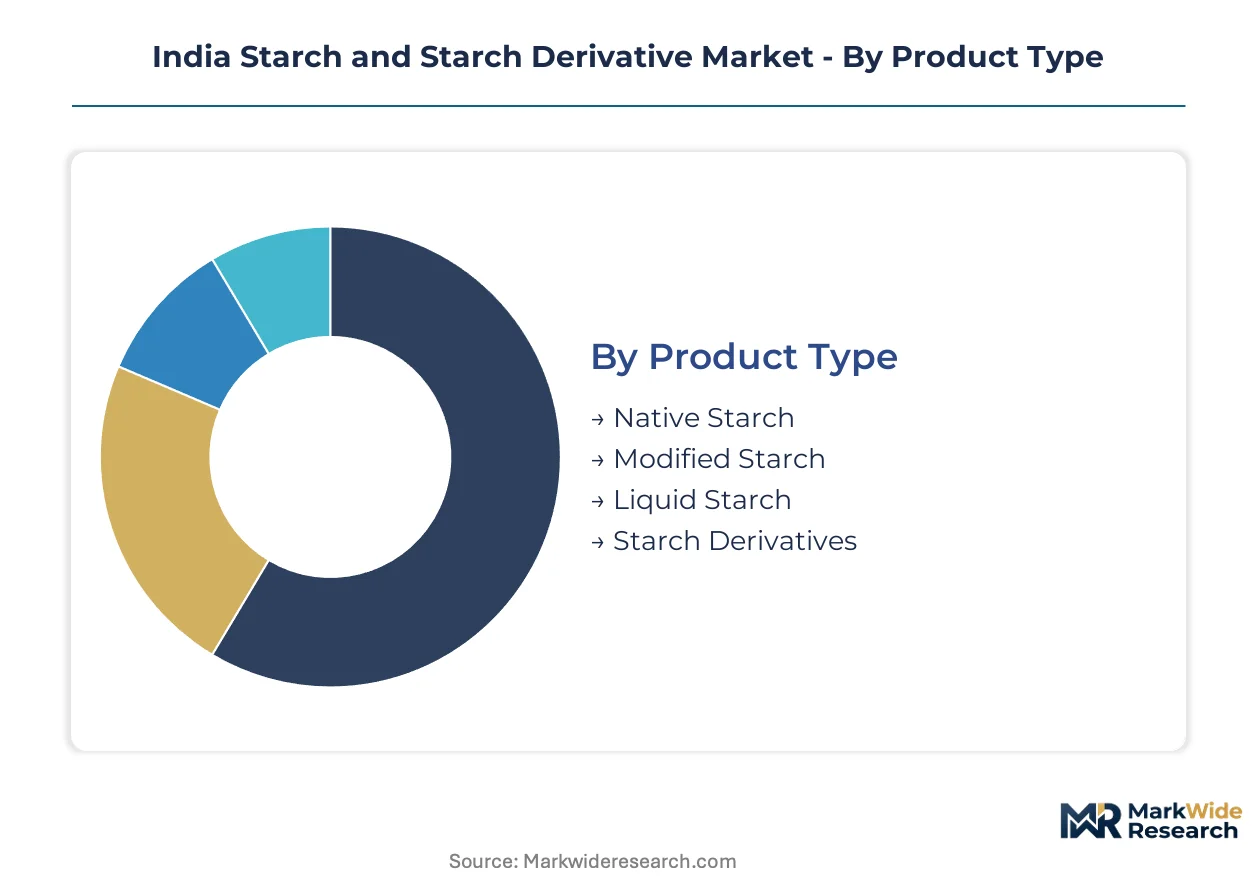
Segmentation in India's starch market reveals how margin pools concentrate around modification depth and regulatory compliance. Product type and end-use industry splits expose where enzymatic capabilities and BIS certification requirements create defensible competitive positions.
Product Type:
Margin pools concentrate deepest in segments requiring enzymatic modification capabilities and pharmaceutical-grade purity certification.
- Modified Starch:Chemically or enzymatically altered to achieve specific viscosity, gelatinization temperature, and retrogradation resistance profiles. Maharashtra and Gujarat food processors procure modified starches for freeze-thaw stable convenience foods under FSSAI clean-label mandates. Pharmaceutical tableting applications in Hyderabad and Bangalore pull premium-grade material meeting CDSCO excipient guidelines.
- Starch Derivatives:Hydrolyzed or converted products including maltodextrins, cyclodextrins, and glucose syrups produced through acid or enzymatic treatment. Southern India textile clusters in Tamil Nadu drive demand for low-viscosity derivatives in warp sizing applications. FSSAI-mandated clean-label requirements accelerate substitution of synthetic hydrocolloids in processed foods.
- Native Starch:Unmodified carbohydrate polymers extracted through wet milling of corn or tapioca feedstocks, serving cost-sensitive paper and corrugated board manufacturing.
- Liquid Starch:Pre-gelatinized aqueous suspensions used in continuous-process industrial applications requiring ready-to-use viscosity without heat activation.
Modified Starch holds installed capacity. Starch Derivatives is rotating up the share rankings.
End Use Industry:
Application concentration patterns follow India's geographic industrial clustering and regulatory enforcement intensity.
- Food & Beverage:Largest volume sink across all product types, spanning bakery, dairy, sauces, and convenience food manufacturing. Western India processors in Mumbai-Pune and Ahmedabad-Vadodara corridors lead procurement of modified starches for clean-label reformulation compliance.
- Pharmaceuticals:Highest margin segment driven by CDSCO tablet binding and controlled-release formulation requirements. Hyderabad and Bangalore formulators specify enzymatically modified starches for chronic disease medication matrices.
- Paper:Volume-dominant native starch consumption for surface sizing and corrugated board adhesive applications where cost minimization governs procurement.
- Textiles:Specialized tapioca-derived derivatives for warp sizing in Tamil Nadu weaving clusters, displacing synthetic polymer alternatives.
Food & Beverage anchors volume throughput. Pharmaceuticals is climbing the fastest on value contribution.
Form:
Physical state selection correlates with manufacturing process integration and supply chain handling economics.
- Powder:Dominant dry form for food manufacturing and pharmaceutical tableting, offering extended shelf stability and precise dosing control.
- Liquid:Pre-hydrated suspensions eliminating gelatinization energy requirements in continuous-process paper and textile applications.
- Granule:Intermediate moisture content format for controlled-release pharmaceutical formulations and specialized food texturization.
- Gel:Fully gelatinized systems for instant food applications and cosmetic formulations requiring immediate viscosity development.
Powder maintains production scale leadership. Liquid is gaining share fastest through process integration benefits.
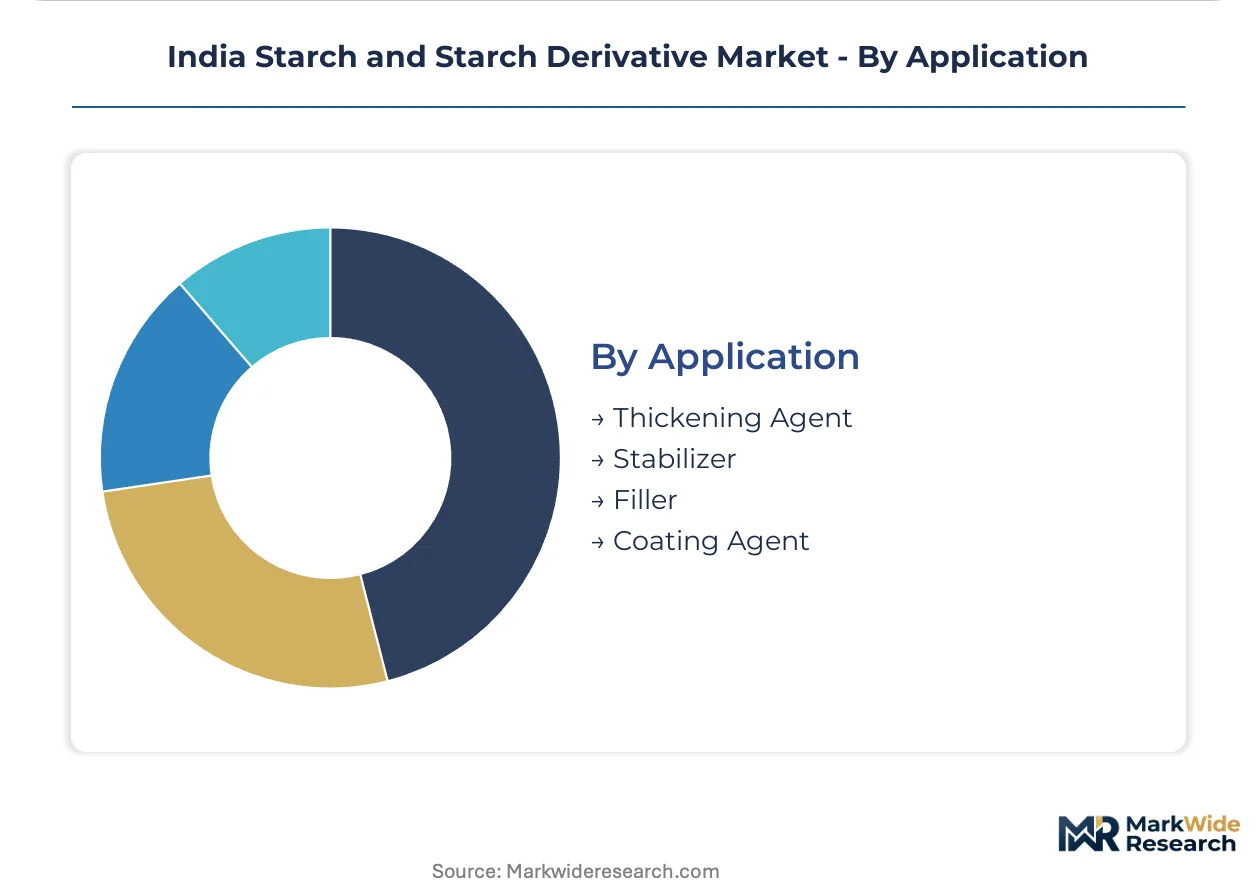
Application:
Functional role segmentation maps directly to end-use value capture and technical specification intensity.
- Thickening Agent:Primary function in sauces, soups, and dairy products where viscosity development without syneresis determines performance. FSSAI clean-label disclosure mandates accelerate starch substitution for synthetic hydrocolloids in western India food processing.
- Stabilizer:Freeze-thaw stability and emulsion preservation in frozen foods and dressings, requiring modified starch with specific amylopectin branching patterns.
- Filler:Volume and binding function in pharmaceutical tableting and low-moisture food systems where inert carrier properties are essential.
- Coating Agent:Film-forming applications for controlled-release drug delivery and paper surface sizing, demanding precise gelatinization temperature control.
Thickening Agent commands installed formulation share. Stabilizer is rotating up the share rankings on convenience food expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's starch derivative trade balance tilts toward import dependence for pharmaceutical-grade enzymatically modified starches while surplus native starch flows to Bangladesh and Southeast Asian paper mills. Western and southern states anchor production capacity. BIS certification requirements create regional specialization patterns.
Maharashtra
Mumbai-Pune food processors drive modified starch consumption for clean-label convenience foods under FSSAI disclosure mandates. The state's PLI scheme for food processing machinery accelerates wet milling modernization in Nashik and Aurangabad industrial zones. Corn processing clusters around Sangli and Kolhapur supply feedstock for western India's derivative output.
Gujarat
Ahmedabad-Vadodara corridor concentrates India's deepest modified starch manufacturing base serving pharmaceutical and food export markets. CDSCO excipient guidelines pull Gujarat producers toward enzymatic modification capabilities for Hyderabad and Bangalore formulators. Legacy batch reactor facilities in older Anand and Bharuch plants face capital-intensive retrofitting pressures.
Tamil Nadu
Tiruppur and Coimbatore textile clusters displace synthetic polymer warp sizing with tapioca-derived starch derivatives. Tapioca cultivation in Salem and Erode districts anchors southern India's cassava processing infrastructure. Tirupati Starch exemplifies regional specialization in textile-grade low-viscosity formulations.
Punjab
Sukhjit Starch leverages Amritsar and Ludhiana corn processing infrastructure to dominate North Indian supply chains. Monsoon-dependent harvests in Haryana border districts create input cost volatility for wet milling operations. The state's procurement networks face margin compression from BIS purity specifications tightening on commodity-grade output.
Telangana
Hyderabad pharmaceutical formulators specify enzymatically modified starches for controlled-release tablet matrices serving chronic disease medication production. Genome Valley biotech corridor attracts CDSCO-compliant excipient suppliers seeking proximity to formulation R&D. The state's diagnostic and API manufacturing density drives premium-grade derivative demand.
India Starch and Starch Derivative Market Competitive Landscape
Listed leaders compete with private specialists across enzymatic modification capabilities and BIS certification depth. The vendor base stratifies into three tiers: multinational technology licensors, integrated domestic processors with captive feedstock, and regional commodity mills. Two strategic archetypes dominate—Punjab-based corn processors and Tamil Nadu-centered tapioca specialists. Capacity expansion and backward integration into cultivation define current competitive moves.
Among integrated domestic processors, Sukhjit Starch & Chemicals Ltd and Tirupati Starch & Chemicals Ltd exemplify the feedstock-anchored archetype, while Ingredion Incorporated represents multinational technology leadership in enzymatic modification processes. These three occupy positions spanning North Indian corn-based supply chains, southern tapioca-derived textile applications, and pharmaceutical-grade excipient technology transfer respectively.
| Leading Market Players |
|---|
| Gulshan Polyols Ltd |
| Sukhjit Starch & Chemicals Ltd |
| Archer Daniels Midland Company |
| SBH Foods Pvt. Ltd. |
| RDAI International Private Limited |
| Ingredion Incorporated |
| Tirupati Starch & Chemicals Ltd |
| Emarc India |
| Cargill Inc. |
| Others |
Supply & Pricing Matrix
FSSAI clean-label certification gates both supply qualification and price differentiation simultaneously, compressing commodity-grade margins while rewarding enzymatic modification capabilities with premium positioning. BIS purity specifications and CDSCO excipient guidelines create tiered access that separates pharmaceutical-grade producers from native starch mills.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in India's starch market. Pharmaceutical formulators in Hyderabad and Bangalore pay certification premiums for CDSCO-compliant excipients, while paper mills drive cost compression in native starch procurement. Price differentiation rests on enzymatic modification depth and BIS certification tier. Margins are tightening in commodity grades due to monsoon-driven corn feedstock volatility.
Supply Chain Analysis
Monsoon-dependent harvests in Punjab and Haryana create chokepoint risk for North Indian wet milling operations. Feedstock sourcing concentrates in Maharashtra, Gujarat, and Tamil Nadu where corn and tapioca processing clusters anchor derivative output. Raw material dependencies include corn grits, cassava roots, and alpha-amylase enzymes. Single-source vulnerability runs through Punjab's rain-fed cultivation belt. Distribution runs through direct procurement contracts with Mumbai-Pune and Ahmedabad-Vadodara food processors, compressing traditional trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's starch market sits in cyclical recovery as PLI scheme incentives for food processing machinery drive capital expenditure normalization after monsoon-induced feedstock disruptions.
For Market Incumbents: Shield margin pools by deepening enzymatic modification capabilities for pharmaceutical-grade output and securing backward integration into tapioca cultivation in Tamil Nadu. Invest in CDSCO excipient certification to lock out commodity competitors from Hyderabad and Bangalore formulator relationships. Prioritize retrofitting legacy Gujarat batch reactors to meet contamination standards. For New Entrants and Emerging Players: Lead with resistant starch R&D targeting BIS dietary fiber claims in functional foods, exploiting white space left by incumbent focus on pharmaceutical excipients. Penetrate Assam and Meghalaya's underdeveloped tapioca processing infrastructure through integrated cultivation-to-derivative operations. Position via direct supply contracts with Northeast India food processors seeking clean-label ingredient security. For Investors and Strategic Acquirers: FSSAI's evolving glycemic index labeling requirements reshape the acquisition landscape toward enzymatic biotechnology capabilities. Over a multi-year horizon, integrated processors with captive feedstock and in-house modification technology offer superior viability versus standalone mills. Target mid-cap specialists with BIS certification depth and established pharmaceutical customer relationships. Watch for BIS resistant starch content protocol finalization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | Captures pharmaceutical-grade margin premiums under CDSCO excipient guidelines. |
| Backward Integration into Tapioca Cultivation | Secures feedstock supply for Tamil Nadu textile sizing derivative production. |
| BIS Certification Investment | Enables clean-label positioning for Maharashtra and Gujarat food processors. |
| Resistant Starch R&D Program | Positions for FSSAI dietary fiber claim requirements in functional foods. |
| Direct Procurement Contracting | Bypasses trader networks to capture specification customization value. |
Research Methodology
Desk research of BIS certification databases, FSSAI regulatory filings, and CDSCO excipient guidelines preceded structured interviews with starch plant managers, food processor procurement leads, pharmaceutical formulator R&D directors, and textile sizing technical officers. Primary fieldwork combined with secondary validation from customs trade records, SEC filings of listed processors, and industry association capacity surveys. Bottom-up installation assessments and top-down demand modeling were triangulated.
Variance decomposition across product type, end-use industry, modification technology tier, and regional production hub informed the analytical framework. CAGRs were derived from segmented growth rate aggregation. Modeled inputs included PLI scheme machinery investment flows, monsoon-derived corn yield volatility assumptions, and pharmaceutical formulation shift timelines toward enzymatic excipients.
Forecasts assume regulatory continuity in FSSAI clean-label mandates and BIS purity specifications; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as CDSCO excipient guideline enforcement intensity and PLI scheme extension decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Notoginseng Root Extract Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
North America Malt Ingredients Market
Ingredients
Egg Yolk Powder Market
Ingredients
Meat Extract Market
Ingredients
Pulses Ingredients Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Industrial Starch Market
Ingredients
Eucalyptus Oil Market
Ingredients
Fiber Rich Flours Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Fermented Ingredients Market
Ingredients
Edible Animal Fat Market
Ingredients
Organic Pastry Flour Market