
 Fruit Concentrate Market | 2026-2036
Fruit Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Concentrate Market Analysis
Buyer concentration among multinational beverage bottlers is realigning procurement leverage across the fruit concentrate supply base. Dohler GmbH leverages its integrated flavor and ingredient platform to secure long-term contracts with consolidated bottling groups. Kerry Group plc anchors its position through deep beverage application expertise and regional technical service networks. AGRANA Beteiligungs-AG competes on cost-efficient Central European fruit sourcing and backward integration into orchard operations.
Fruit concentrate denotes a reduced-water extract obtained through evaporation, filtration, or freezing processes, typically achieving soluble solids content of 65–72 degrees Brix for standardized industrial use. Manufacturers employ vacuum evaporation at sub-boiling temperatures to preserve volatile aromatic compounds and color stability in the final concentrate. Citrus and berry categories dominate volume throughput due to established procurement infrastructure and year-round blending flexibility for beverage formulators. Liquid concentrate maintains share leadership in direct-to-processor channels, while spray-dried formats gain traction in confectionery and dairy powder applications where storage efficiency and transport economics matter.
EU regulators enforce maximum residue limits through EFSA scientific opinions and REACH compliance for processing aids, while FDA standards govern import tolerances and GRAS determinations for US-bound concentrate shipments. BIS certification requirements in India and evolving FSSAI labeling norms for reconstituted products reshape market access conditions across major demand centers. Stakeholders must monitor divergence between regional contaminant thresholds and emerging digital traceability mandates to preempt supply disqualification risks.
Market Dynamics
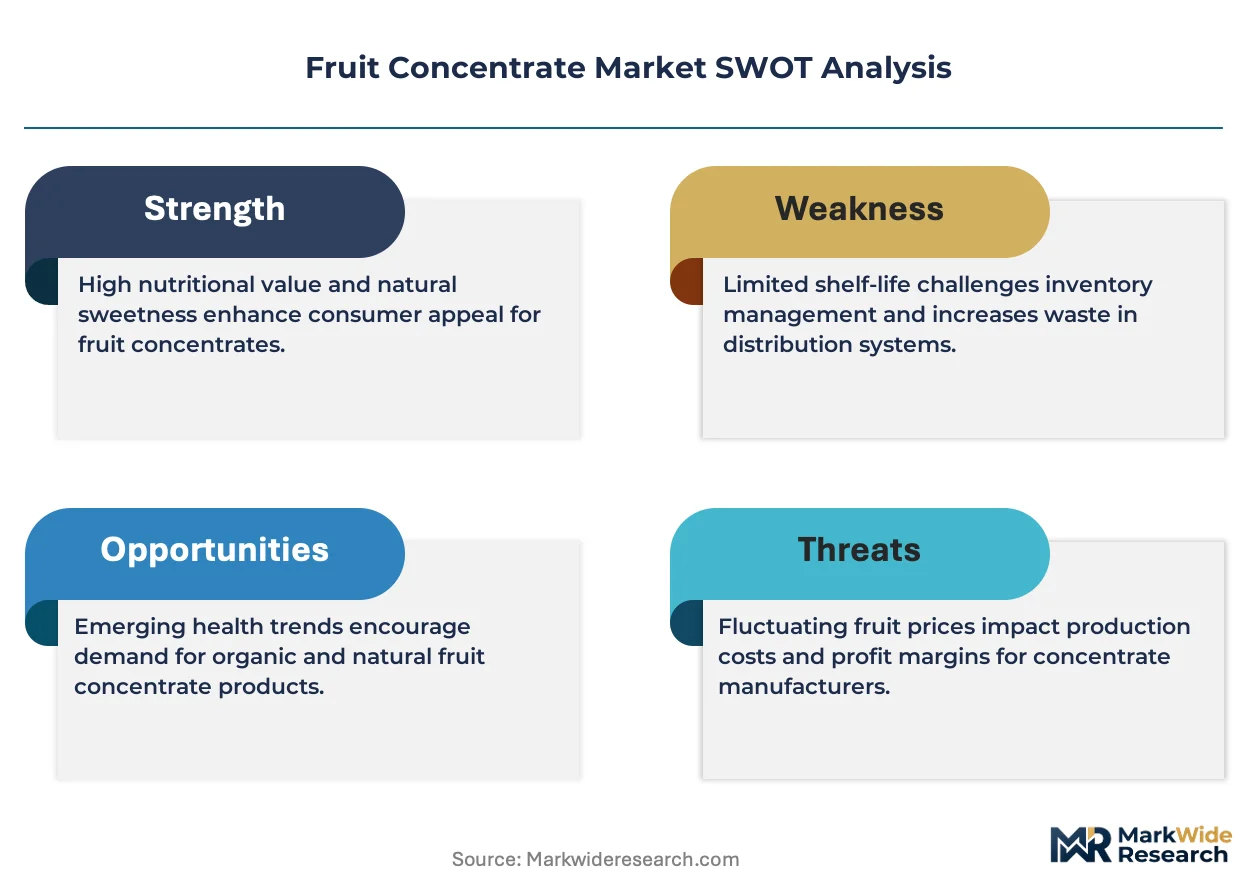
Clean-label procurement mandates from multinational beverage bottlers are compressing supplier margins while forcing rapid traceability system upgrades across European and North American processing networks.
Growth Catalysts
- EU Farm to Fork Strategy:Tightened residue limits and digital traceability mandates are accelerating consolidation among compliant processors. German ingredient hubs capture expanded sourcing volumes as bottlers seek pre-qualified supply chains.
- Reformulated soft drink portfolios:Major beverage groups are replacing synthetic flavor systems with natural concentrates. Berry and citrus concentrates gain formulation share in reduced-sugar product lines.
- Vacuum evaporation at sub-boiling temperatures:This processing technology preserves volatile aromatic compounds. Premium juice brands specify this method for color-stable concentrate procurement.
Market Restraints
- Input cost volatility in orchard operations:Climate stress on Mediterranean citrus groves and Polish apple regions creates raw material price instability. Backward integration into captive orchards requires multi-year capital commitments.
- Supply concentration in Central European processing:AGRANA and Dohler anchor regional capacity. Bottlers face limited alternative sourcing for EU-origin concentrate meeting Farm to Fork specifications.
- Technical limitation in spray-dried formats:Heat-sensitive berry compounds degrade during atomization. Confectionery applications requiring authentic fruit notes remain dependent on liquid concentrate supply.
Strategic Opportunities
- Underpenetrated dairy powder applications:Spray-dried citrus and tropical concentrates offer flavor stability in extended-shelf-life yogurt powders. European dairy processors are testing reformulated fruit-inclusions for export markets.
- FSSAI labeling evolution in India:New reconstituted product disclosure norms create first-mover advantage for traceable concentrate supply. Kerry Group technical service networks position for specification-setting roles.
- Technology convergence of blockchain traceability and IoT sensors:Real-time orchard-to-processor monitoring satisfies EU digital product passport requirements. Early adopters secure long-term bottler contracts with audit-ready documentation.
Industry Challenges
- Specialized technician scarcity in aroma recovery systems:Vacuum evaporation operation requires precise temperature-pressure calibration. Process engineering talent concentrates at established German and Austrian processing centers.
- Capex intensity for REACH-compliant solvent recovery:Processing aid containment systems demand seven-figure equipment investments. Mid-scale processors delay upgrades, risking supply disqualification from consolidated bottler panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Concentrate Market |
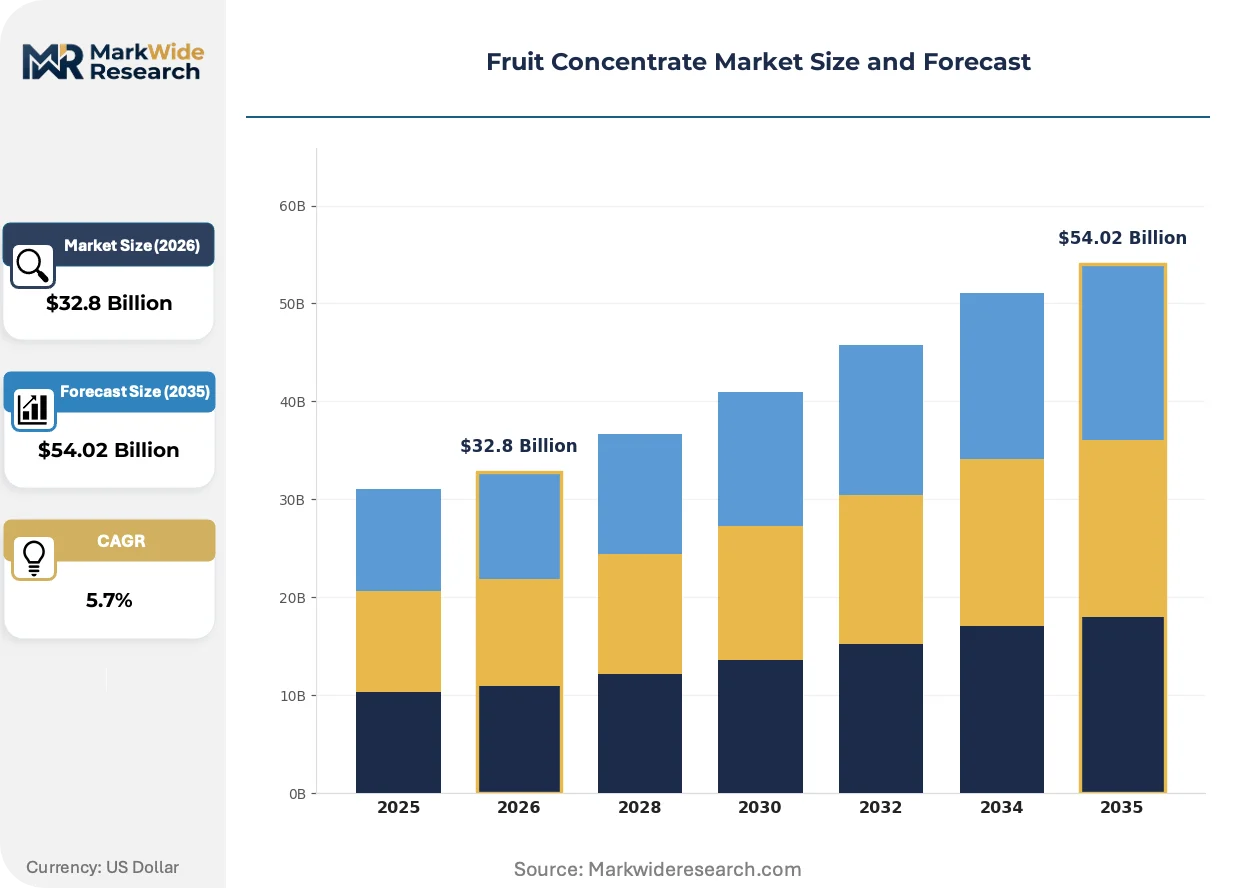
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
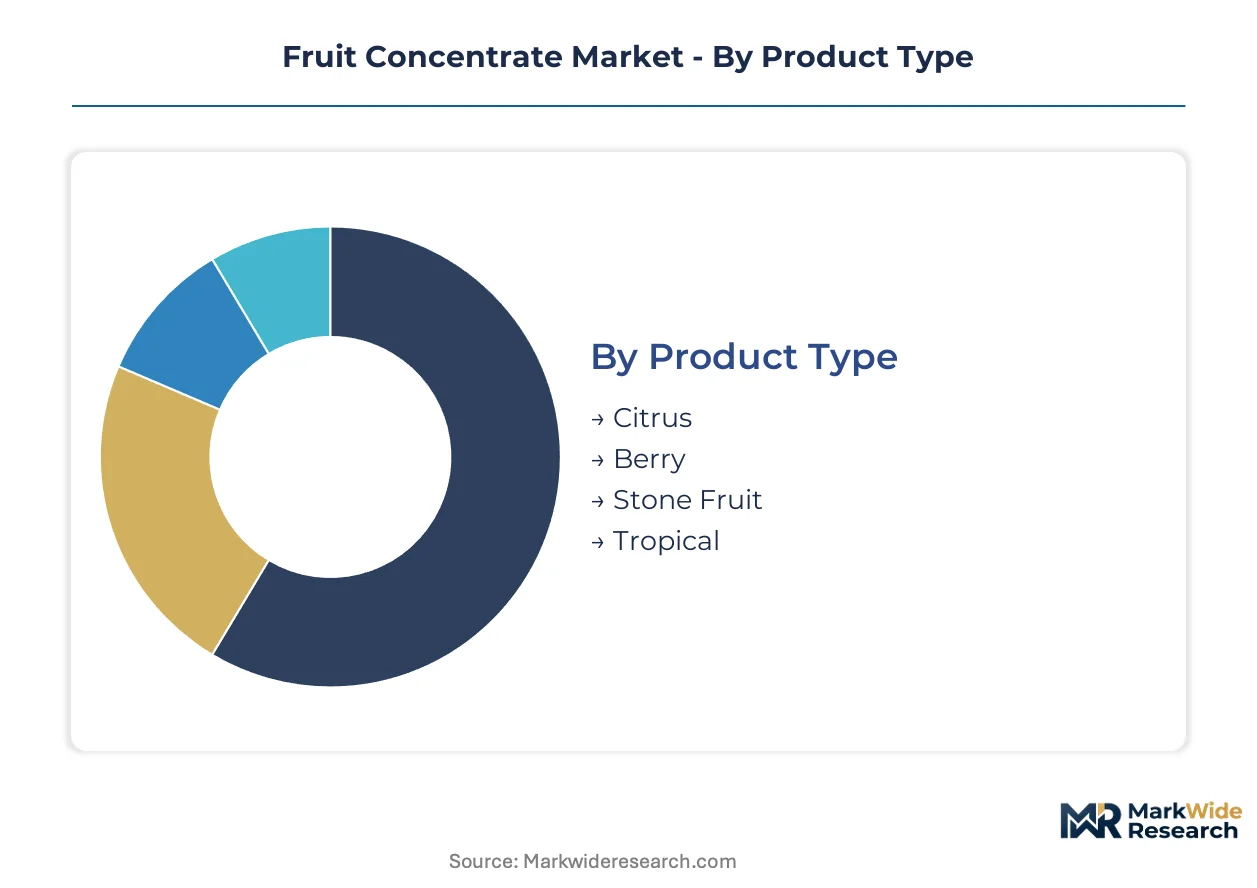
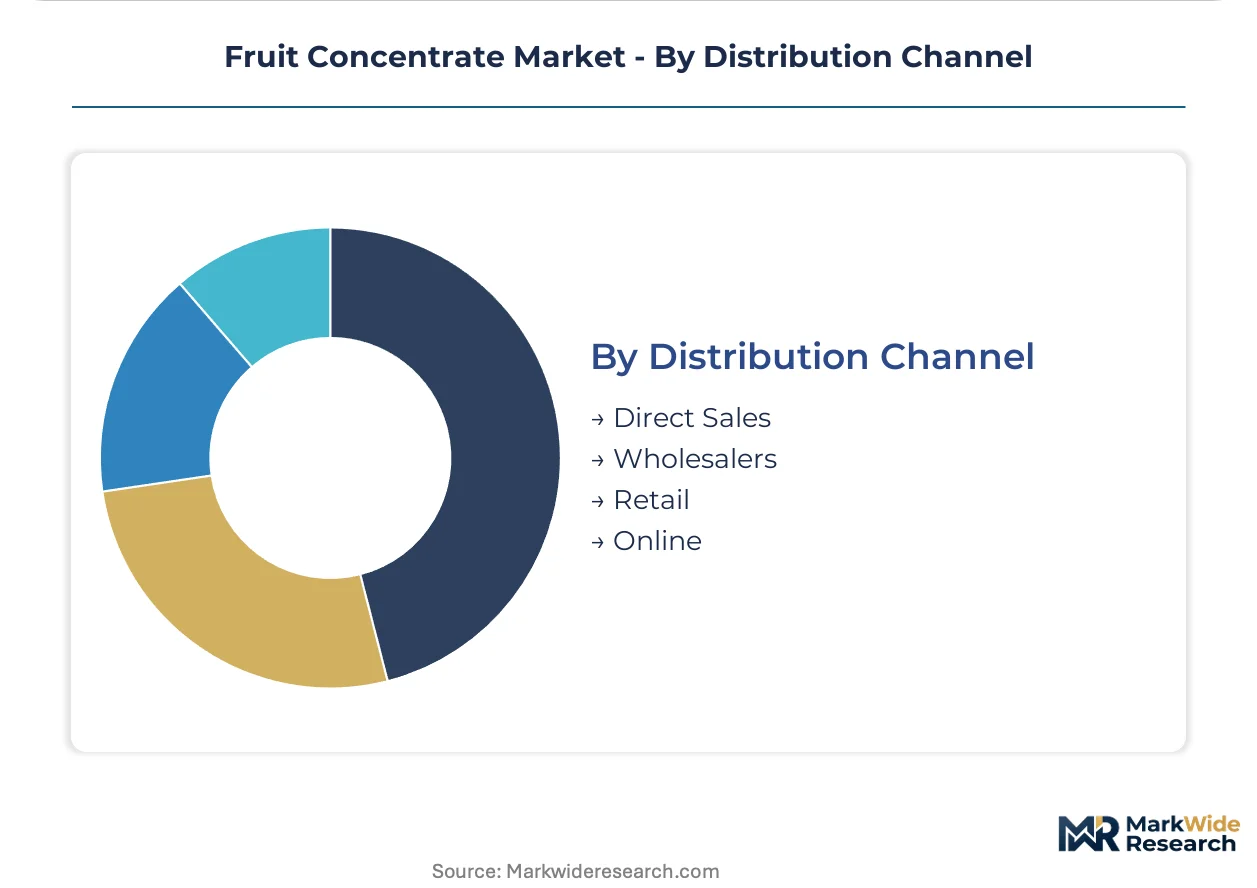
| Segmentation | Product Type: Citrus, Berry, Stone Fruit, Tropical Application: Beverages, Bakery, Confectionery, Dairy Form: Liquid, Powder, Frozen, Spray-Dried Distribution Channel: Direct Sales, Wholesalers, Retail, Online |
| Companies Covered | Dohler GmbH, Kerry Group plc, Archer Daniels Midland Company, AGRANA Beteiligungs-AG, SunOpta Inc., Ingredion Incorporated, Lemon Concentrate S.L., Kerr Concentrates Inc., Royal Cosun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Concentrate Market Emerging Trajectories
Processing technology and procurement specifications are converging to reward suppliers with integrated flavor platforms and verified clean-label credentials across beverage and adjacent food categories.
Membrane filtration combined with vacuum evaporation is consolidating market share among premium concentrate producers. Beverage formulators in Germany and the Netherlands specify this technology for low-heat berry processing. The method is consolidating supplier tiers by disqualifying processors lacking capital for dual-system installation.
REACH compliance for processing aids and EFSA scientific opinions on maximum residue limits are tightening contaminant thresholds. Concentrate imports into the EU face enhanced documentation requirements at Rotterdam and Hamburg entry points. Citrus processors in Spain and Italy are accelerating solvent substitution programs to maintain GRAS-equivalent status for US-bound shipments.
Beverage bottlers are compressing supplier panels and extending contract durations to secure traceable concentrate supply. Direct procurement relationships with orchard-integrated processors are replacing spot-market purchasing in Germany. This concentration is most visible among Central European bottling groups reformulating portfolios for clean-label positioning.
Fruit Concentrate Market Segmentation
Procurement specifications for fruit concentrate diverge sharply across end-use applications, with beverage formulators demanding color-stable aromatic profiles while dairy and confectionery buyers prioritize storage economics and handling convenience. These functional requirements reshape supplier positioning across every category.
Product Type:
Standardization dominates citrus and berry procurement through established Brix specifications, while stone fruit and tropical categories retain customization flexibility for niche formulation work.
- Citrus:Orange and lemon concentrates achieve 65–72 degrees Brix through vacuum evaporation, preserving volatile terpene compounds for color-stable juice reconstitution. German bottlers anchor procurement volumes for reformulated reduced-sugar portfolios, though Mediterranean climate stress on Spanish and Italian groves creates raw material price instability.
- Berry:Strawberry and raspberry concentrates require low-temperature processing to protect anthocyanin colorants. Demand concentrates in premium juice brands and clean-label soft drink lines across the Netherlands and Scandinavia, where EFSA residue limits drive preference for orchard-integrated supply chains.
- Stone Fruit:Peach and apricot concentrates serve flavor-forward beverage applications with distinct aromatic profiles.
- Tropical:Pineapple and mango concentrates support exotic flavor positioning in limited-edition product launches.
Leading the category by volume: Citrus. Expanding most quickly: Berry.
Application:
Volume scale separates beverage procurement from adjacent categories, while margin structure inverts toward dairy and confectionery for spray-dried formats.
- Beverages:Juice reconstitution and soft drink formulation consume the majority of liquid concentrate throughput. Multinational bottlers in Germany compress supplier panels to secure traceable supply meeting EU Farm to Fork specifications.
- Bakery:Fruit fillings and glazes demand consistent viscosity and water activity control for shelf-stable applications.
- Confectionery:Heat-sensitive berry compounds limit spray-dried adoption, keeping liquid concentrate dependency high for authentic fruit notes.
- Dairy:Yogurt and ice cream inclusions represent underpenetrated territory for spray-dried citrus and tropical concentrates in extended-shelf-life powder applications.
Dominating procurement scale: Beverages. Gaining share fastest: Dairy.
Form:
Transport economics and storage infrastructure determine format selection, with liquid retaining direct-processor channel leadership while powder formats unlock new application adjacencies.
- Liquid:Bulk tanker delivery to beverage processing facilities minimizes handling costs for high-volume citrus and berry procurement. Vacuum-evaporated concentrates at 65–72 Brix require refrigerated storage and rapid turnover.
- Powder:Agglomerated formats reduce moisture content below 5% for confectionery and dairy powder applications where warehouse efficiency matters.
- Frozen:Single-strength purees preserve fresh-fruit aromatics for premium positioning in artisanal bakery and specialty beverage channels.
- Spray-Dried:Atomization technology faces technical limitations with heat-labile berry compounds, constraining penetration in authentic-flavor confectionery segments.
Commanding volume leadership: Liquid. Climbing the fastest: Spray-Dried.
Distribution Channel:
Relationship intensity varies from embedded technical service in direct sales to transactional efficiency in digital procurement.
- Direct Sales:Long-term contracts with orchard-integrated processors replace spot-market purchasing among Central European bottling groups. Technical service networks from ingredient platforms support formulation development and regulatory documentation.
- Wholesalers:Regional distributors aggregate smaller-volume demand from independent bakery and confectionery manufacturers.
- Retail:Packaged concentrates for foodservice and small-scale industrial buyers move through specialty ingredient distributors.
- Online:Digital platforms gain traction for standardized specifications and rapid sample procurement in product development phases.
Anchoring procurement value: Direct Sales. Expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers in Germany anchor procurement volumes for Central European concentrate supply, while reformulated soft drink portfolios in the Netherlands and Scandinavia drive specification upgrades across orchard-integrated processing networks.
Germany
Ingredient processors in Hamburg and Frankfurt anchor distribution networks for reformulated juice portfolios. EFSA residue limits and REACH compliance for processing aids tighten procurement specifications. Bavarian orchard operations supply backward-integrated concentrate to bottling groups seeking Farm to Fork traceability credentials.
United States
Multinational beverage manufacturers in California and Florida expand clean-label concentrate procurement for reduced-sugar product lines. FDA import tolerances and GRAS determinations govern concentrate shipments from Mediterranean suppliers. Pacific Northwest berry processors invest in vacuum evaporation capacity for premium juice brands.
India
Dairy powder manufacturers in Maharashtra and Gujarat test spray-dried citrus concentrates for extended-shelf-life yogurt applications. FSSAI labeling norms for reconstituted products reshape import documentation requirements. Karnataka-based processors position for technical service roles as disclosure standards evolve.
Spain
Mediterranean citrus groves in Valencia and Murcia face climate stress affecting raw material price stability. EFSA scientific opinions on maximum residue limits accelerate solvent substitution programs. Andalusian processors upgrade containment systems to maintain US-bound shipment eligibility under FDA standards.
Netherlands
Premium juice brands in Rotterdam and Amsterdam specify low-temperature berry processing for anthocyanin colorant preservation. EU digital product passport requirements drive blockchain traceability adoption. Dutch bottlers compress supplier panels to secure long-term contracts with compliant Central European processors.
Fruit Concentrate Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue spray-dried format expansion and dairy powder adjacencies. Market structure reflects moderate consolidation among orchard-integrated processors and ingredient platforms with technical service networks. Three archetypes dominate: flavor-integrated ingredient platforms, backward-integrated orchard operators, and application-focused technical service providers. Competitive moves center on supplier panel compression by multinational bottlers and capital deployment toward REACH-compliant solvent recovery systems.
Within the flavor-integrated tier, Dohler GmbH and Kerry Group plc represent archetypes combining concentrate supply with formulation development capabilities. AGRANA Beteiligungs-AG anchors the backward-integrated orchard operator position through Central European fruit sourcing control. These three entities occupy positions shaped by procurement leverage realignment among consolidated bottling groups seeking traceable supply chains.
| Leading Market Players |
|---|
| Dohler GmbH |
| Kerry Group plc |
| Archer Daniels Midland Company |
| AGRANA Beteiligungs-AG |
| SunOpta Inc. |
| Ingredion Incorporated |
| Lemon Concentrate S.L. |
| Kerr Concentrates Inc. |
| Royal Cosun |
| Others |
Supply Flow & Price Mechanics
Mediterranean citrus futures and Polish apple spot indices cascade through Central European processing networks, compressing margins at contract-renewal junctures while orchard-integrated suppliers capture premium-tier pricing power through Farm to Fork traceability credentials.
Pricing Analysis
Volume leadership in liquid citrus concentrates runs on thin margins driven by spot-market raw material exposure, while spray-dried berry and tropical formats command premium-mid-economy pricing differentiation based on heat-stability certification and extended shelf-life performance. Price differentiation hinges on REACH-compliant solvent recovery investment and backward integration into captive orchards. Cost compression in standard-tier liquid supply is intensifying because multinational bottlers compress supplier panels and extend contract durations. Independent confectionery manufacturers show highest price sensitivity due to limited volume scale, whereas premium juice brands demonstrate lowest sensitivity when specifying vacuum-evaporated, color-stable concentrates.
Supply Chain Analysis
EFSA scientific opinions and REACH compliance certifications gate market access for processors serving EU-bound concentrate demand, with Spanish and Italian citrus operations, Polish and German apple processors, and Dutch berry specialists forming the geographic core. Raw material supply draws from Mediterranean citrus groves, Central European orchard belts, and Nordic berry cultivation zones. Single-source vulnerability concentrates in vacuum evaporation equipment and aroma recovery system technicians anchored at German and Austrian processing centers. Distribution runs through direct tanker delivery to beverage bottlers, with digital platforms gaining share in sample procurement and development-phase purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fruit Concentrate Market operates as a cost-of-compliance arena where EU Farm to Fork Strategy mandates erect capital barriers that orchard-integrated processors exploit to widen competitive moats against undercapitalized mid-scale competitors.
For Market Incumbents:Anchoring procurement leverage requires accelerated solvent substitution programs and blockchain-traceability system deployment to preempt disqualification from consolidated bottler panels. Dohler GmbH and Kerry Group plc demonstrate how technical service networks defend position against emerging spray-dried specialists. Backward integration into additional orchard capacity in Bavaria and Poland secures raw material cost control.
For New Entrants and Emerging Players:Launch via digital procurement platforms targeting independent bakery and confectionery manufacturers underserved by direct-sales infrastructure. Spray-dried citrus concentrates for extended-shelf-life dairy powder applications in India represent the most penetrable white-space segment. Technical service partnerships with Maharashtra-based yogurt processors offer viable go-to-market positioning before FSSAI labeling norms fully crystallize.
For Investors and Strategic Acquirers:The window for entry favors orchard-integrated processors with existing REACH compliance and vacuum evaporation capacity across the five-to-ten year horizon. Acquisition targets should display captive fruit supply, digital traceability infrastructure, and established bottler contract relationships. Solvent substitution program completion status serves as the critical inflection signal for supply-disqualification risk assessment.
| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Backward Integration | Captive Polish and Bavarian fruit supply secures raw material cost stability against climate volatility. |
| Vacuum Evaporation Capacity Expansion | Low-temperature processing preserves anthocyanin compounds for premium Netherlands juice brands. |
| Blockchain Traceability Deployment | Real-time orchard-to-processor monitoring satisfies EU digital product passport requirements for Rotterdam entry. |
| Spray-Dried Format Development | Atomized citrus concentrates unlock extended-shelf-life yogurt powder applications in Maharashtra dairy plants. |
| Solvent Substitution Program | REACH-compliant processing aid containment maintains GRAS-equivalent status for US-bound Spanish shipments. |
Methodological Framework
Independent corroboration across beverage formulation executives, procurement directors at multinational bottling groups, orchard operations managers, regulatory affairs specialists, and ingredient platform technical service teams underwrites the qualitative findings. Secondary validation draws from EFSA scientific opinions, REACH compliance filings, FSSAI labeling directives, FDA import tolerance determinations, and customs trade data for concentrate shipments through Rotterdam and Hamburg. Bottom-up volume modeling triangulates against top-down value estimates derived from procurement contract structures.
Comparable-period anchoring to historical Farm to Fork implementation phases and prior EU residue limit tightening cycles established the forecast window baseline. The analytical framework models volume and value across product type, application, form, and distribution channel dimensions, with regional regulatory cluster and orchard-integration status as industry-specific overlays. CAGRs derive from segment-level demand elasticity calibrated to bottler procurement panel compression trends and spray-dried technology penetration curves in dairy powder adjacencies.
Climate stress on Mediterranean groves, divergence between EFSA and FDA contaminant thresholds, and FSSAI disclosure norm evolution are the dominant revision risks. A model refresh is warranted upon material change in EU digital product passport implementation timelines or solvent substitution compliance deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Commercial Flour Market
Ingredients
Diastatic Malt Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Pomace Olive Oil Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Food Colors Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Modified Flour Market
Ingredients
Olive Leaf Extract Market
Ingredients
Rendered Products Market