
 Global Inactive Dried Yeast Market | 2026-2036
Global Inactive Dried Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inactive Dried Yeast Market Outlook
Pet nutrition is pivoting toward inactive dried yeast as a sustainable protein alternative to fishmeal and soy concentrates. Lallemand Inc. leverages its strain development capabilities to supply pet food manufacturers with species-specific yeast derivatives. Lesaffre Group anchors European supply through its fermentation facilities in France and Belgium. Angel Yeast Co., Ltd. dominates Asian production scale with integrated yeast extraction operations.
Inactive dried yeast consists of Saccharomyces cerevisiae cells rendered non-viable through thermal or pasteurization treatment, typically retaining 40-50% crude protein and B-vitamin complexes for nutritional applications. The ingredient functions primarily as a flavor enhancer, palatability agent, and nutrient dense additive across food and feed systems. Nutritional yeast occupies the premium tier within the type segmentation, commanding margin pools from clean-label and vegan positioning in dietary supplements and health stores. Brewer's yeast segments compete on volume through animal feed applications, where bulk bag packaging and commodity pricing predominate. Bakery products sustain steady offtake through instant yeast formats optimized for industrial dough conditioning.
EFSA feed additive evaluations and FAMI-QS certification frameworks govern European market access for yeast-derived ingredients, while FDA GRAS determinations and AAFCO ingredient definitions shape United States commercialization pathways. USDA organic standards and EU organic regulations create dual compliance burdens for suppliers targeting premium positioning in health stores and specialty food manufacturers. Stakeholders must monitor evolving protein labeling claims and fermentation carbon accounting methodologies as procurement criteria tighten across end-user categories.
Market Dynamics
Precision fermentation capacity concentration in Germany and France is compressing supply chains, forcing buyers to secure long-term offtake agreements or risk allocation shortfalls as pet food protein substitution accelerates.
Growth Catalysts
- EFSA feed additive authorizations:Harmonized safety assessments under EU Regulation 1831/2003 streamline cross-border ingredient approvals, reducing time-to-market for yeast-derived protein additives.
- Pet food protein diversification:Manufacturers facing fishmeal volatility and soy sustainability scrutiny are expanding inactive dried yeast procurement for palatability and amino acid balance.
- Fermentation cluster density:Concentrated production in Belgium's Flemish biotech corridor enables feedstock sharing and shared utilities, lowering marginal production costs.
Market Restraints
- Molasses price volatility:Cane sugar crop fluctuations in Brazil and India directly impact yeast fermentation feedstock costs, compressing processor margins.
- Single-source supply risk:Strain IP concentration among three dominant developers creates vulnerability if propagation failures or contamination events disrupt master cell bank access.
- AAFCO definition lag:United States ingredient nomenclature updates trail EU regulatory clarity, delaying product positioning in premium pet nutrition segments.
Strategic Opportunities
- India aquafeed penetration:Shrimp and carp farming expansion in Andhra Pradesh and Gujarat creates unserved demand for protein-rich yeast additives as fishmeal prices rise.
- EU Green Deal carbon accounting:Fermentation-derived proteins with verified low-carbon intensity qualify for procurement preferences under corporate sustainability reporting mandates.
- Direct-to-manufacturer platforms:Digital ingredient marketplaces bypass traditional distributor markups, enabling smaller pet food brands to access bulk yeast pricing tiers.
Industry Challenges
- FAMI-QS certification timelines:Feed safety management system audits require 12-18 month implementation cycles, delaying new supplier qualification for urgent procurement needs.
- Downstream formulation integration:Pet food extrusion parameters require recalibration when substituting yeast proteins for conventional binders, demanding technical service investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inactive Dried Yeast Market |
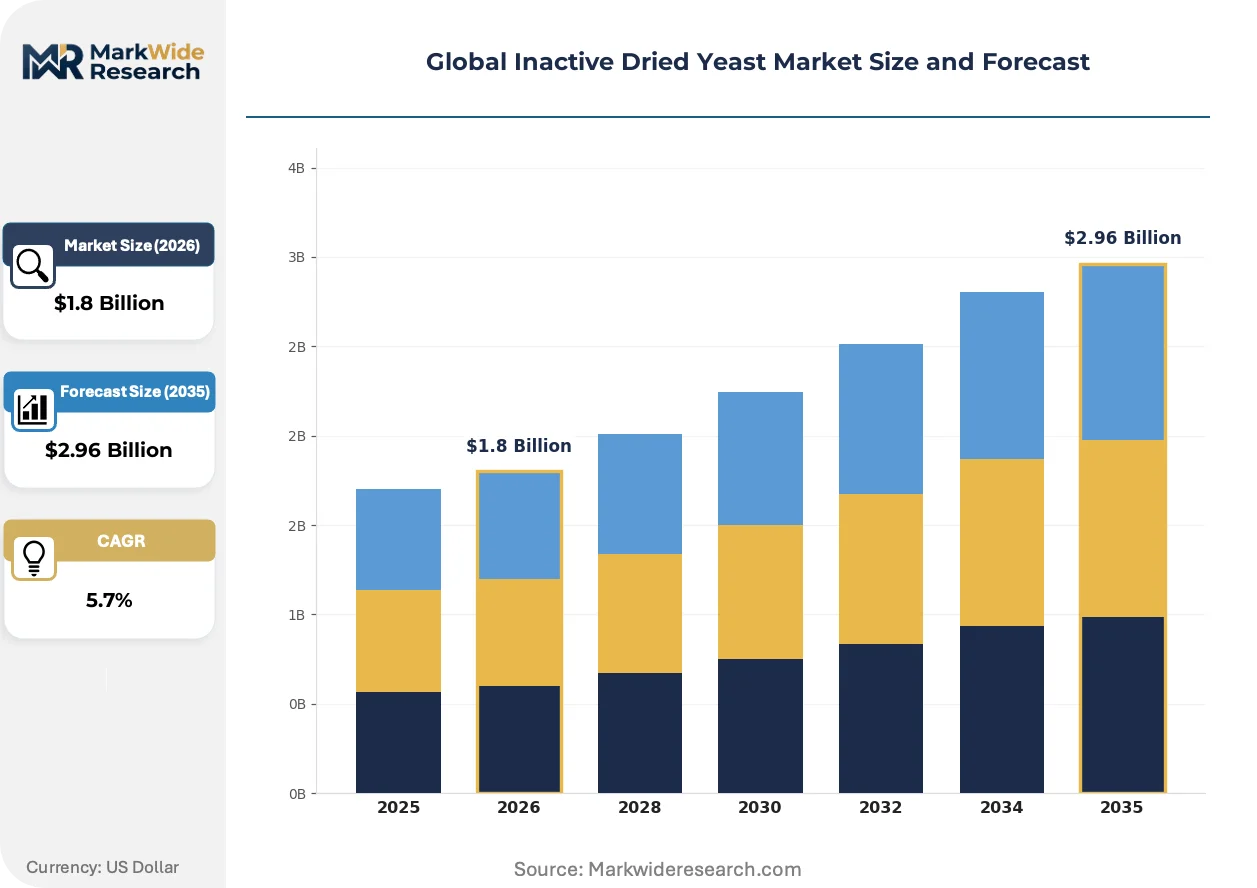
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Baker's Yeast, Nutritional Yeast, Brewer's Yeast, Instant Yeast Application: Bakery Products, Dietary Supplements, Animal Feed, Food Flavoring End User: Food Manufacturers, Bakeries, Health Stores, Restaurants Packaging Type: Bulk Bags, Sachets, Tins, Jars |
| Companies Covered | Angel Yeast Co., Ltd., Lallemand Inc., Lesaffre Group, Associated British Foods PLC, Leiber GmbH, Alltech, AB Mauri, Kerry Group PLC, Ohly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inactive Dried Yeast Market Strategic Shifts
Continuous fermentation monitoring systems and automated cell viability assessment are compressing batch-to-batch variation, enabling specification-grade supply for pharmaceutical and premium nutrition applications.
Electrochemical real-time biomass sensors are electrifying process control in large-scale fermentation facilities. Angel Yeast and Lesaffre have deployed dissolved oxygen and capacitance probes across Chinese and Belgian plants, cutting off-spec batches by half. This precision is enabling just-in-time delivery contracts that were previously impossible with thermal kill-step variability.
REACH biocidal product regulations are reclassifying certain yeast cell wall derivatives, forcing manufacturers to submit full substance dossiers or reformulate. The compliance burden falls heaviest on smaller toll processors without regulatory affairs capacity. German and Dutch ingredient suppliers are consolidating formulation services to spread dossier costs across client portfolios.
Ingredient procurement through sustainability-linked contracts is displacing spot-market purchasing in Nordic and Benelux pet food manufacturing. Buyers now specify carbon intensity thresholds and third-party animal welfare certifications alongside protein content. This behavioral shift is most visible in Denmark, where three major brands have eliminated open-market yeast purchasing entirely.
Global Inactive Dried Yeast Market Segmentation
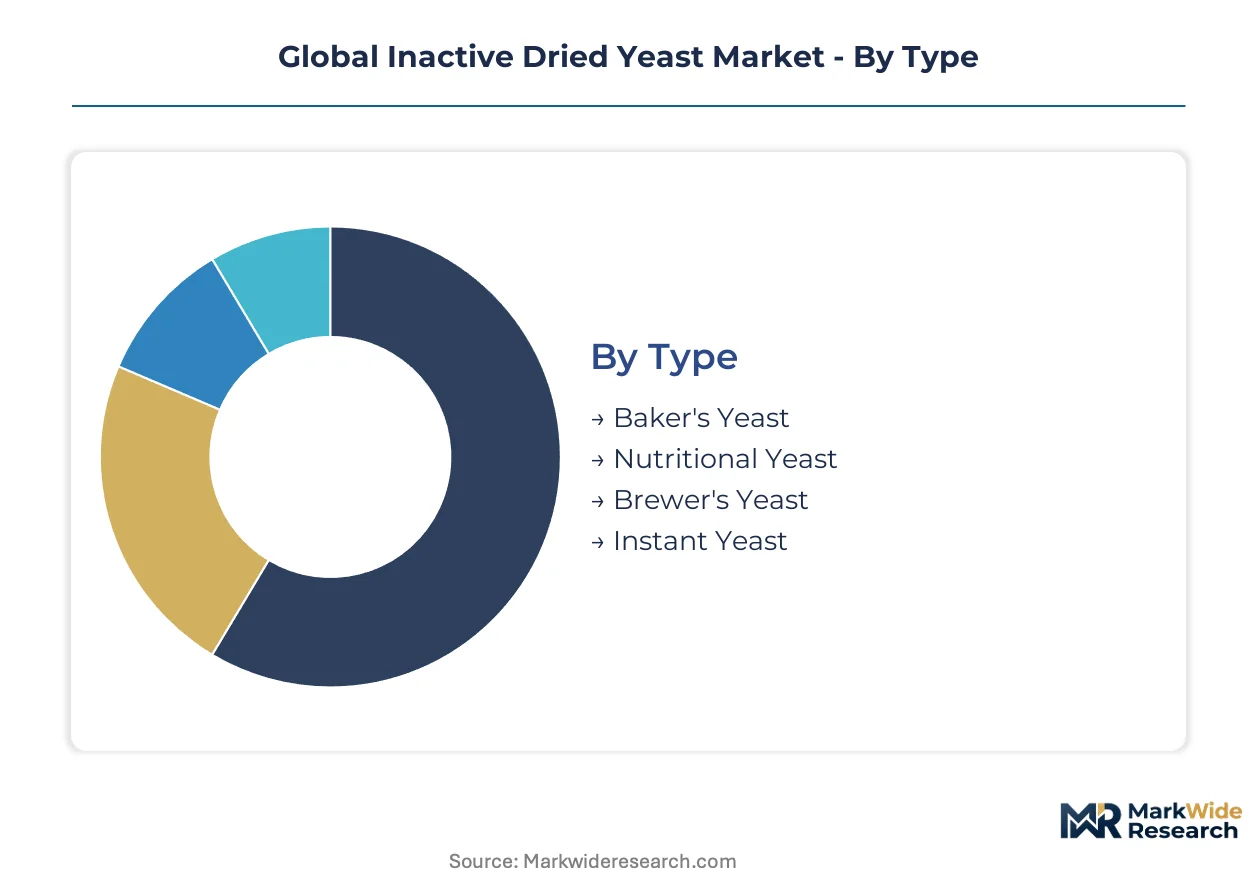
Inactive dried yeast markets fragment across fermentation technology tiers and downstream formulation requirements. Capital deployment intensity varies sharply between commodity-scale animal feed operations and pharmaceutical-grade nutritional yeast facilities.
Type:
Fermentation infrastructure requirements dictate capital intensity across type segments, with strain development and thermal processing capabilities separating premium from commodity positioning.
- Nutritional Yeast:Saccharomyces cerevisiae cultivated on enriched molasses or sugar beet substrates, then drum-dried to preserve B-vitamin profiles and beta-glucan content. Demand concentrates in German and Danish health stores where clean-label vegan positioning commands procurement premiums under EU organic regulations.
- Brewer's Yeast:Spent biomass recovered from beer fermentation, debittered through alkali washing and dried for protein concentrate applications. Animal feed manufacturers in Belgium and the Netherlands absorb volume through FAMI-QS certified supply chains as fishmeal substitution accelerates.
- Baker's Yeast:Live active cultures killed through controlled thermal treatment for dough conditioning applications.
- Instant Yeast:Agglomerated particles with enhanced rehydration kinetics for industrial bakery throughput.
Most installed capacity flows through Brewer's Yeast. Expansion is steepest in Nutritional Yeast.
Application:
Formulation complexity and regulatory burden stratify applications, with pharmaceutical-adjacent supplements requiring GMP compliance that feed-grade operations bypass.
- Animal Feed:Protein fortification and palatability enhancement in pet food extrusion and aquafeed pelletizing, with EFSA feed additive authorizations under EU Regulation 1831/2003 governing market access. German precision fermentation clusters supply strain-optimized derivatives to Mars and Nestlé Purina formulation centers.
- Dietary Supplements:Tablet and capsule formulations leveraging beta-1,3/1,6-glucan immunomodulatory claims, with US FDA GRAS determinations and USDA organic certification creating dual compliance pathways for premium positioning.
- Bakery Products:Dough conditioning and flavor modulation through inactivated cell wall constituents.
- Food Flavoring:Umami enhancement and savory note contribution in processed food systems.
Volume concentration sits with Animal Feed. Value capture is climbing fastest in Dietary Supplements.
End User:
Procurement scale and technical service requirements separate end user categories, with multinational food manufacturers demanding integrated supply security that fragmented bakeries cannot match.
- Food Manufacturers:Industrial-scale procurement through long-term offtake agreements, with sustainability-linked contracts specifying carbon intensity thresholds and third-party animal welfare certifications displacing spot-market purchasing in Nordic markets.
- Health Stores:Small-lot sourcing of organic-certified and non-GMO verified SKUs, with direct-to-manufacturer digital platforms enabling access to bulk pricing tiers previously reserved for multinational accounts.
- Bakeries:Instant yeast formats optimized for consistent fermentation performance across variable dough conditions.
- Restaurants:Limited penetration through specialty nutritional yeast as vegan cheese substitute.
Supply contracts concentrate with Food Manufacturers. Digital procurement adoption is advancing most quickly among Health Stores.
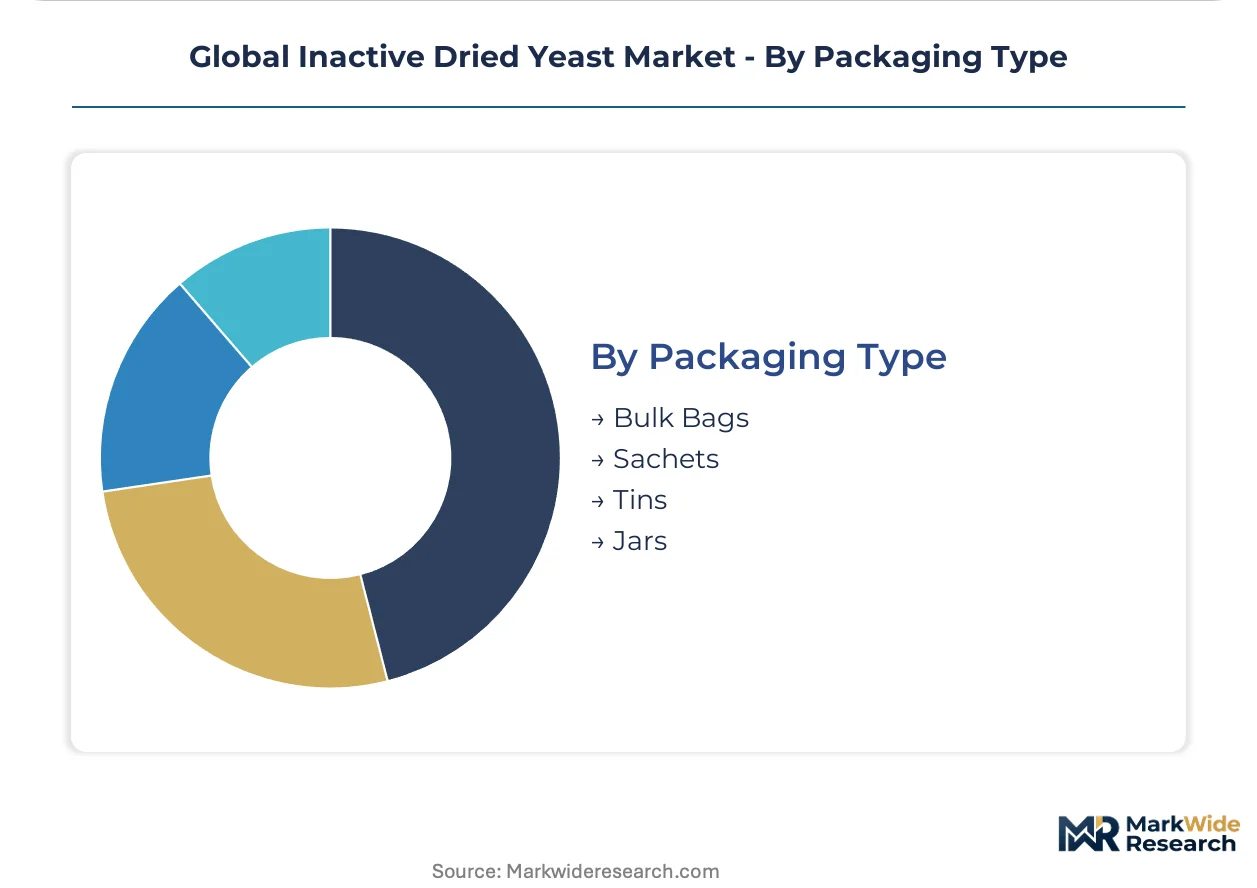
Packaging Type:
Handling infrastructure and shelf-life requirements shape packaging investment, with aseptic filling lines for retail formats demanding capital multiples above bulk bagging operations.
- Bulk Bags:One-tonne flexible intermediate bulk containers with moisture-barrier liners for animal feed compounders and industrial bakeries, with just-in-time delivery contracts enabled by electrochemical biomass sensors that compress batch-to-batch variation.
- Sachets:Nitrogen-flushed laminated film for oxygen-sensitive nutritional yeast, with portion-controlled formats penetrating health store and direct-to-consumer channels in Germany and France.
- Tins:Metal canisters with resealable lids for pantry-stable home baking segments.
- Jars:Clear PET or glass containers for retail visibility in specialty food positioning.
Throughput dominance belongs to Bulk Bags. Premium positioning is expanding most rapidly through Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting inactive dried yeast fermentation capacity toward jurisdictions with streamlined feed additive approval pathways and concentrated biotech infrastructure. Manufacturers are relocating master cell bank operations and thermal processing facilities to exploit gaps between EFSA harmonization timelines and national enforcement capacity.
Germany
Precision fermentation clusters in the Rhineland and Bavaria anchor European supply security for pet food protein fortification. EFSA feed additive authorizations under EU Regulation 1831/2003 enable cross-border ingredient movement with reduced re-approval burdens. The Flemish biotech corridor extension into North Rhine-Westphalia creates shared utilities and feedstock pooling that compress marginal production costs for yeast derivatives.
China
Integrated yeast extraction operations in Hubei and Guangxi provinces dominate Asian production scale for both nutritional and feed-grade segments. SAMR feed additive registration requirements and GB standards for fermented products create compliance pathways distinct from Western regulatory frameworks. Angel Yeast's captive molasses sourcing networks in Yunnan and Guangdong insulate batch consistency against Brazilian cane sugar price volatility.
United States
AAFCO ingredient definition lag delays premium pet nutrition positioning relative to EU clarity, though FDA GRAS determinations sustain dietary supplement channel access. Midwest corn belt proximity supplies dextrose feedstock for fermentation facilities in Wisconsin and Illinois. The Pacific Northwest hosts emerging precision fermentation ventures targeting carbon-accounting preferences under state-level climate disclosure mandates.
Belgium
FAMI-QS certification density in the Flemish Region creates qualification bottlenecks for new suppliers while securing incumbent supply relationships with Mars and Nestlé Purina formulation centers. REACH biocidal product reclassifications of yeast cell wall derivatives force dossier submission costs onto toll processors. The Port of Antwerp molasses terminal anchors feedstock logistics for Lesaffre Group fermentation operations.
India
Shrimp aquafeed expansion in Andhra Pradesh and Gujarat generates unserved demand for protein-rich yeast additives as fishmeal prices rise and soy sustainability scrutiny intensifies. FSSAI feed ingredient notifications and BIS quality standards create dual compliance layers for imported versus domestically produced yeast. Gujarat's Special Economic Zone fermentation parks offer tax holidays that attract toll processing joint ventures with European strain developers.
Global Inactive Dried Yeast Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated strain IP concentration among three dominant developers creating tiered supply security. The vendor base organizes around fermentation technology ownership, thermal processing capability, and regulatory affairs capacity rather than pure scale. Three archetypes prevail: integrated strain-to-powder operators, toll processors serving private-label brands, and specialty extractors targeting pharmaceutical-adjacent beta-glucan applications. Capacity expansion and strategic partnerships dominate competitive moves as buyers secure long-term offtake agreements.
Among integrated fermentation operators, Angel Yeast Co., Ltd. and Lesaffre Group exemplify the strain-to-powder archetype with captive production networks, while Lallemand Inc. occupies a position within the specialty derivatives tier. These three anchors collectively concentrate master cell bank access and thermal kill-step expertise that smaller toll processors cannot replicate. Contract manufacturers without regulatory affairs capacity face consolidation pressure as REACH dossier costs and FAMI-QS audit timelines escalate.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| Lallemand Inc. |
| Lesaffre Group |
| Associated British Foods PLC |
| Leiber GmbH |
| Alltech |
| AB Mauri |
| Kerry Group PLC |
| Ohly |
| Others |
Value Chain & Pricing Dynamics
Fermentation technologist concentration in Belgium's Flemish biotech corridor and Germany's Rhineland widens pricing-tier spreads between FAMI-QS certified premium supply and commodity-grade toll processing. Labor-cost differentials between these precision fermentation clusters and lower-cost Indian toll operations compress margins on standardized brewer's yeast while sustaining premiums on strain-optimized nutritional yeast derivatives.
Pricing Analysis
Distributor markups of 15-25% on nutritional yeast sachets for health store channels separate premium positioning from direct-to-manufacturer bulk bag pricing for pet food compounders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with USDA organic and EU organic tiers commanding procurement premiums. Cost compression in commodity brewer's yeast is intensifying because Brazilian molasses price volatility feeds directly into fermentation feedstock costs. Pet food manufacturers exhibit highest price sensitivity due to fishmeal substitution economics, while pharmaceutical-adjacent beta-glucan extractors show lowest sensitivity given immunomodulatory claim premiums.
Supply Chain Analysis
India's phased manufacturing program and domestic content preferences for aquafeed ingredients are reshaping sourcing patterns for European strain developers seeking toll processing joint ventures. Supply concentration centers on China, Belgium, and Germany, with Angel Yeast's integrated Hubei operations, Lesaffre's Antwerp fermentation complex, and German precision fermentation clusters anchoring global capacity. Raw material dependencies hinge on Brazilian cane molasses, Chinese sugar beet substrates, and Midwest US dextrose from corn belt processing. Single-source vulnerability concentrates in master cell bank access controlled by three dominant strain developers. Distribution runs through FAMI-QS certified feed compounders in Benelux and long-term offtake agreements with Mars and Nestlé Purina formulation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Inactive Dried Yeast Market functions as a stable compounder anchored by irreversible pet food protein diversification away from fishmeal and soy concentrates. Substitution demand from aquafeed expansion and clean-label vegan positioning in dietary supplements sustains volume growth with limited cyclicality.
For Market Incumbents: Lock in strain IP advantages through exclusive master cell bank licensing to Indian toll processors, insulating against domestic-content mandates while capturing aquafeed growth. Prioritize FAMI-QS certification investment for Belgian and German facilities to defend against REACH biocidal reclassification costs that burden smaller competitors without regulatory affairs capacity. Capacity addition in Gujarat Special Economic Zone fermentation parks secures tax-advantaged supply for Asian aquafeed demand. For New Entrants and Emerging Players: Digital ingredient marketplaces offer the most penetrable channel for bypassing traditional distributor markups and accessing bulk pricing tiers previously reserved for multinational pet food accounts. White-space targets include direct-to-manufacturer platforms for Nordic sustainability-linked contract procurement and carbon-accounting verified supply for EU Green Deal compliance. Go-to-market positioning should emphasize verified low-carbon intensity fermentation with third-party animal welfare certifications. For Investors and Strategic Acquirers: Pet food manufacturers with captive formulation centers are the most active acquirer in this space, seeking backward integration into strain-optimized yeast derivatives for protein fortification. Long-term viability frames around 5-10 year protein substitution trajectories in pet nutrition and aquafeed. Acquisition target archetype: toll processors with FAMI-QS certification and regulatory affairs capacity stranded by REACH dossier cost escalation. Signal to watch: molasses price volatility spikes triggering consolidation among margin-compressed commodity processors.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Secures molasses feedstock through Brazilian cane sugar processor partnerships, insulating Angel Yeast against crop volatility. |
| Backward Integration | Captive Yunnan and Guangdong molasses sourcing networks compress input cost variation for Chinese fermentation scale. |
| Joint Venture | Gujarat Special Economic Zone toll processing partnerships enable European strain developers to satisfy Indian domestic-content preferences. |
| Capacity Expansion | German precision fermentation cluster additions supply Mars and Nestlé Purina formulation centers with strain-optimized derivatives. |
| Green Certification Program | EU organic and carbon-accounting verification qualifies supply for Nordic sustainability-linked procurement mandates. |
Study Parameters
Direct dialogue with fermentation facility managers, pet food formulation scientists, FAMI-QS certification auditors, and EFSA regulatory affairs specialists grounded qualitative insights in operational reality. Secondary validation drew from EFSA feed additive authorization databases, EU Regulation 1831/2003 implementation records, SAMR feed additive registrations, customs trade data on molasses and yeast derivatives, and SEC filings from publicly traded ingredient suppliers. Bottom-up capacity modeling across Chinese, Belgian, and German fermentation facilities triangulated against top-down pet food protein substitution demand estimates.
Segment-level value and volume trajectories across the analysis window reflect disaggregated modeling by type, application, end user, and packaging format. The analytical framework incorporated fermentation technology tier, thermal processing capability, and regulatory compliance burden as cross-cutting segmentation dimensions. CAGRs derived from installed capacity expansion timelines, offtake agreement visibility, and substitution elasticity parameters for fishmeal and soy concentrate displacement. Industry-specific forecast inputs included molasses price volatility indices and EFSA authorization pipeline velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Brazilian cane sugar crop failures, REACH biocidal reclassification scope expansion, and AAFCO ingredient definition updates trailing EU regulatory clarity. Forecasts reflect documented assumptions on protein substitution rates and fermentation yield improvements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Germany Gelatin Market
Ingredients
Compressed Yeast Market
Ingredients
Europe Fats and Oil Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
North America Cocoa Products Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Wheat Gluten Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Arachidonic Acid Market
Ingredients
Citrus Fiber Market
Ingredients
Textured Soy Protein Market
Ingredients
Ingredients Market