
 Soy Protein Hydrolysate Market | 2026-2036
Soy Protein Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Protein Hydrolysate Market Analytics
A shift from single-source soy procurement to multi-origin sourcing is restructuring supply security across the soy protein hydrolysate value chain. Cargill leverages its crushing network across North and South America to secure non-GMO bean streams. Archer Daniels Midland anchors its position through wet-milling infrastructure that converts flakes directly into enzymatically hydrolyzed isolates. Kerry Group competes on flavor-masked hydrolysate systems tailored for ready-to-drink protein beverages.
Soy protein hydrolysate consists of enzymatically or acid-cleaved soy proteins yielding peptides typically below 10 kDa molecular weight, designed for rapid gastrointestinal absorption and reduced allergenicity compared to intact soy proteins. Hydrolysates dominate high-performance nutrition formulations where solubility and digestibility rates exceed standard concentrate benchmarks. Food and Beverages applications lead volume consumption, while Nutritional Supplements command premium pricing due to clinical positioning around post-workout recovery. Feed applications sustain baseline demand as aquaculture operators substitute fishmeal with hydrolyzed soy peptides in salmon and shrimp diets.
FDA GRAS notifications and EFSA novel food assessments shape product entry pathways for hydrolysate ingredients in the United States and European Union. China's SAMR enforces GB standards for plant protein labeling that restrict hydrolysate concentration claims in infant formula segments. Feed-grade hydrolysate producers must track FAMI-QS certification requirements for EU market access. Stakeholders should monitor enzyme supplier consolidation and regional crushing capacity expansion as determinants of hydrolysate cost curves and margin sustainability.
Market Dynamics
Enzymatic hydrolysis technology is concentrating production capability among processors with captive protease supply chains, locking in margin advantages for integrated operators while fragmenting the merchant hydrolysate tier.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for hydrolyzed plant proteins accelerate European market entry for food-grade formulations targeting clinical nutrition segments.
- Aquaculture Feed Substitution:Salmon and shrimp producers in Norway and Chile replace fishmeal with hydrolyzed soy peptides to meet marine ingredient reduction mandates.
- Sports Nutrition Absorption Science:Post-workout recovery formulations leverage sub-10 kDa peptide fractions for rapid amino acid kinetics, pulling hydrolysate demand from intact protein concentrates.
Market Restraints
- Non-GMO Soybean Premium Volatility:Identity-preserved bean streams command 15-25% price premiums over conventional, compressing hydrolysate margins for organic-positioned brands.
- Brazilian Crushing Concentration:Three processors control 60% of South American soy protein isolate feedstock, creating supply vulnerability for hydrolysate operators without origination contracts.
- Bitter Peptide Technical Ceiling:Enzymatic cleavage of hydrophobic amino acid sequences generates off-flavors that mask poorly in neutral-pH beverage systems.
Strategic Opportunities
- India Functional Foods White Space:FSSAI's 2023 protein fortification guidelines for school meals and mid-day programs create institutional procurement channels for hydrolysate-enhanced products.
- Cell Culture Media Convergence:Precision fermentation and cultivated meat processes require defined peptide nitrogen sources, opening pharmaceutical-grade hydrolysate applications.
- Direct-to-Consumer Subscription Channels:Ready-to-mix protein brands bypass traditional distribution markups through recurring shipment models, capturing full value chain margin.
Industry Challenges
- FAMI-QS Certification Timelines:Feed-grade hydrolysate producers face 12-18 month audit cycles for EU market access, delaying revenue recognition for new manufacturing assets.
- Protease Supplier Consolidation:Three enzyme houses control 80% of food-grade protease supply, creating input scarcity during Q4 crush season peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Protein Hydrolysate Market |
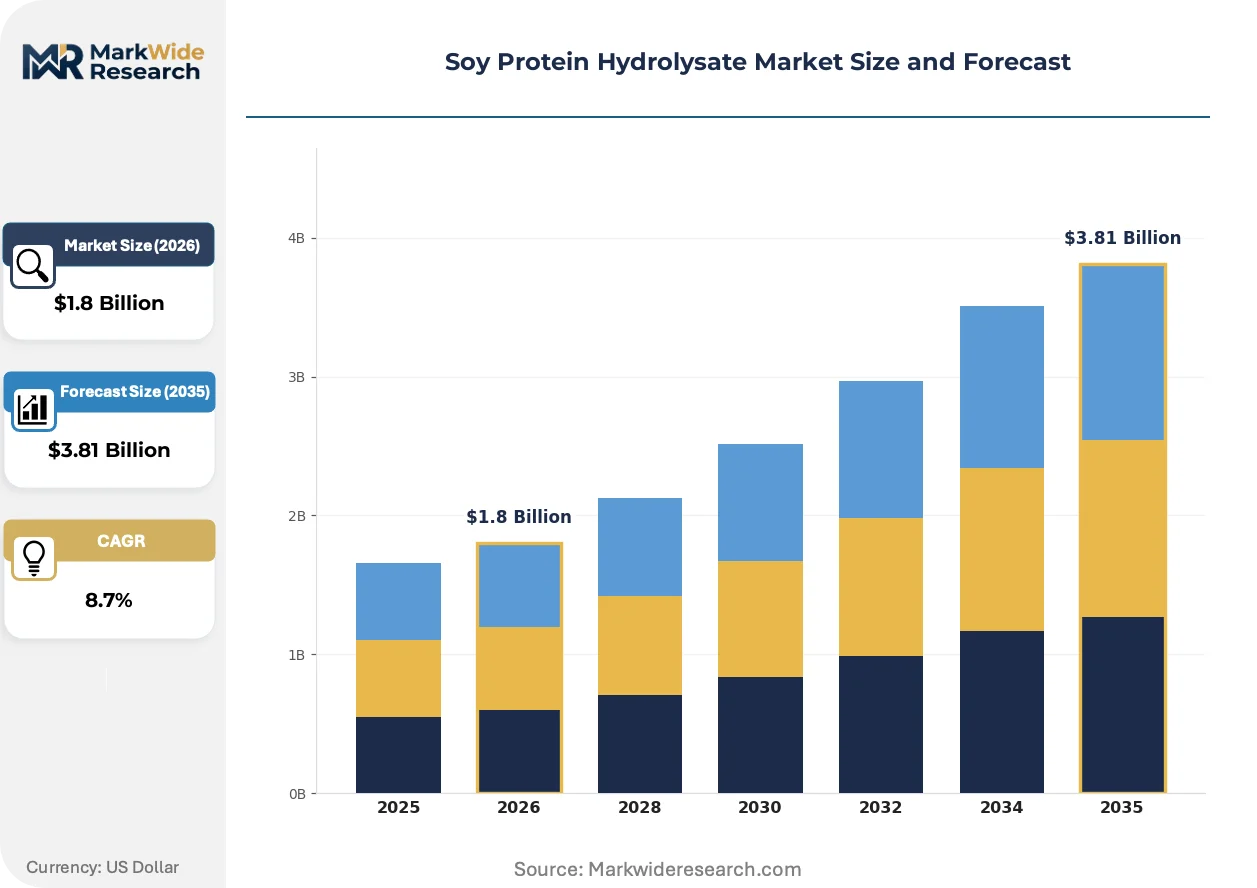
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured Protein, Hydrolysates Application: Food & Beverages, Nutritional Supplements, Feed, Cosmetics End User: Food Manufacturers, Dietary Supplement Companies, Personal Care Brands, Animal Feed Producers Distribution Channel: Direct Sales, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | DuPont, Archer Daniels Midland, ADM, CHS Inc., Wilmar International Limited, Cargill, Sojaprotein, Bunge, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Protein Hydrolysate Market Evolving Landscape
Membrane filtration and precision enzyme engineering are compressing cost curves while regulatory frameworks for novel protein claims tighten formulation transparency requirements.
Alkaline protease-enzyme blends paired with ceramic membrane separation are overtaking traditional acid-precipitation methods for producing low-molecular-weight peptide fractions. Sports nutrition manufacturers in Germany and the United States adopt these systems at pilot scale, cutting process water consumption by 40% while enabling precise molecular weight cutoff control for targeted absorption claims.
China's SAMR enforcement of GB 28050-2021 nutrition labeling standards restricts hydrolysate concentration claims in infant formula segments, forcing reformulation toward whole-protein equivalence statements. Domestic brands are responding by pivoting hydrolysate volumes toward adult medical nutrition and geriatric care products where peptide-specific claims remain permissible under GB 29922.
Buyers in the nutritional supplements channel increasingly demand batch-level peptide profiling data and third-party digestibility certification, displacing traditional protein content certificates as the primary procurement filter. This specification escalation concentrates purchasing power among hydrolysate suppliers with in-house analytical capabilities, most visible in contract manufacturing relationships between U.S. sports nutrition brands and their ingredient vendors.
Soy Protein Hydrolysate Market Segmentation
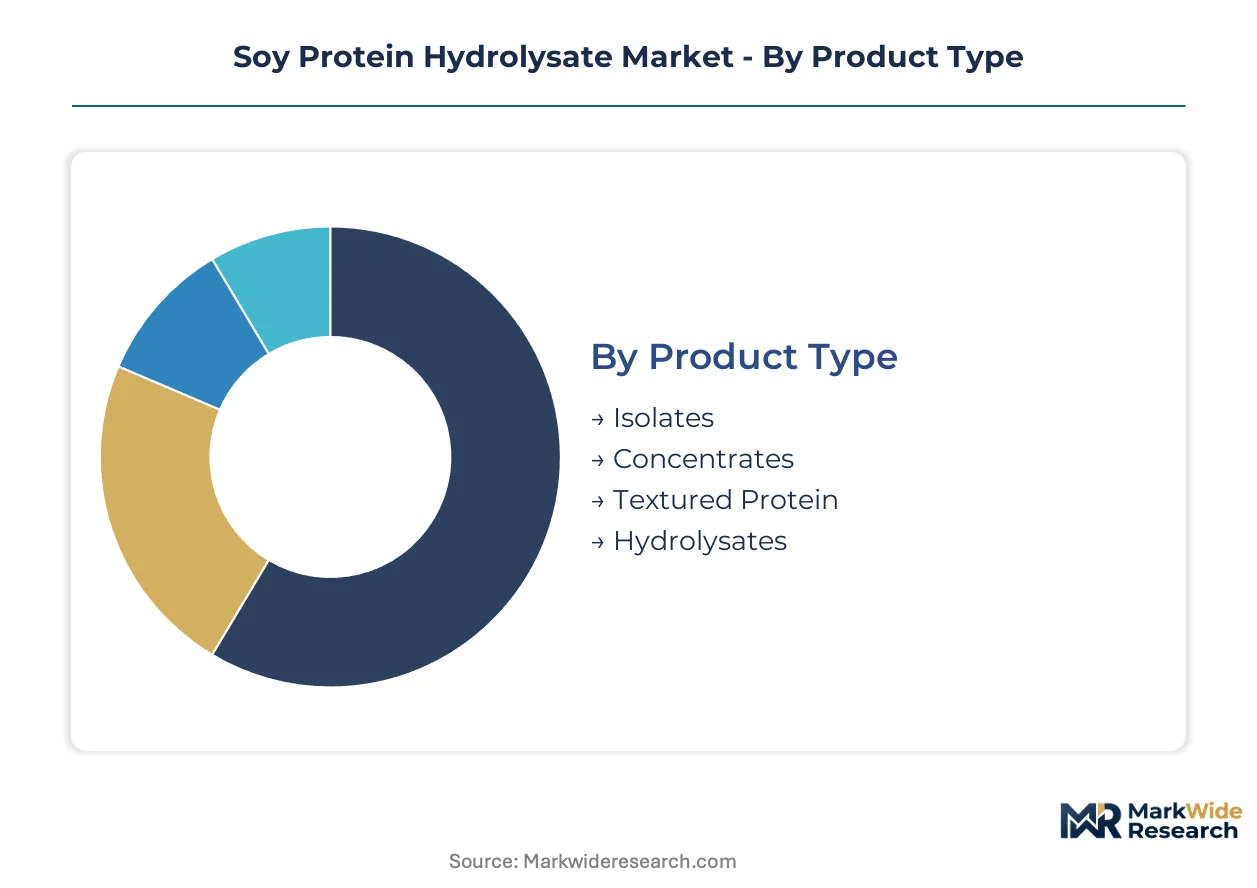
Soy protein hydrolysate buyers segment sharply by technical specification tolerance, with feed operators prioritizing bulk peptide nitrogen while clinical nutrition brands demand sub-10 kDa fraction verification. These divergent requirement sets fragment supplier capabilities and pricing architectures across the value chain.
Product Type:
Cost tier separates commodity processors from premium-positioned ingredient houses.
- Isolates:Protein content exceeds 90% with minimal carbohydrate carryover, commanding premium positioning in infant formula and medical nutrition applications where nitrogen purity standards are non-negotiable. German clinical nutrition brands specify isolate-based hydrolysates for enteral feeding products, absorbing 20-30% price premiums over concentrate alternatives.
- Concentrates:Protein content ranges 70-85%, retaining soluble carbohydrate fractions that enhance palatability in sports nutrition applications. Chinese functional food manufacturers source concentrate-derived hydrolysates for adult protein fortification, prioritizing cost efficiency over molecular weight precision.
- Textured Protein:Extruded and structured formats for meat analog applications requiring chew resistance and water-binding capacity.
- Hydrolysates:Enzymatically cleaved peptide fractions below 10 kDa molecular weight, designed for rapid absorption claims in performance nutrition.
Hydrolysates lead volumes today; isolates are gaining share fastest.
Application:
Margin structure varies dramatically by regulatory burden and certification depth.
- Food & Beverages:Bakery, beverage, and dairy alternative applications leverage hydrolysates for emulsification stability and solubility across pH ranges. Chinese beverage brands integrate hydrolysates into plant-based milk alternatives, navigating SAMR's GB 28050-2021 labeling restrictions on peptide-specific claims.
- Nutritional Supplements:Post-workout recovery and clinical nutrition segments demand batch-level peptide profiling and third-party digestibility certification. U.S. sports nutrition brands specify sub-10 kDa fractions for rapid amino acid kinetics, displacing intact protein concentrates in premium formulations.
- Feed:Aquaculture and livestock applications substitute hydrolyzed soy peptides for fishmeal, with Norwegian salmon producers driving marine ingredient reduction mandates.
- Cosmetics:Hair and skin conditioning applications utilize low-molecular-weight peptides for film-forming and moisture-retention properties.
Feed applications anchor volume baselines; nutritional supplements deliver steepest margin expansion.
End User:
Procurement sophistication separates institutional buyers from emerging channel entrants.
- Food Manufacturers:Large-scale bakery, beverage, and meat alternative producers negotiate long-term supply agreements with volume-tier pricing and dedicated production line allocation.
- Dietary Supplement Companies:Contract manufacturers and branded finished goods houses demand peptide molecular weight distribution data and allergen threshold documentation. U.S. and German brands increasingly require in-house analytical capabilities from hydrolysate suppliers as a procurement filter.
- Personal Care Brands:Cosmetic formulators prioritize peptide stability and color consistency in rinse-off and leave-on applications.
- Animal Feed Producers:Aquaculture operators in Norway and Chile specify hydrolysate inclusion rates for salmon and shrimp diets, tracking FAMI-QS certification requirements for EU market access.
Food manufacturers dominate procurement volumes; dietary supplement companies are expanding specification intensity fastest.
Distribution Channel:
Customer acquisition cost and technical service depth determine channel viability.
- Direct Sales:Technical ingredient houses deploy field application scientists to co-develop hydrolysate formulations with major food and supplement manufacturers. Cargill and ADM leverage direct relationships for captive supply agreements with multi-year volume commitments.
- Online Retail:Direct-to-consumer protein brands bypass traditional distribution markups through subscription models, capturing full value chain margin. Ready-to-mix hydrolysate products ship direct from contract manufacturers to U.S. and European consumers.
- Supermarkets:Mass-market retail placement for finished protein beverages and fortified foods with hydrolysate positioning.
- Specialty Stores:Sports nutrition and natural products retailers curate premium hydrolysate brands with third-party certification badges.
Direct sales commands B2B volume; online retail is climbing the fastest as subscription models scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clinical nutrition clusters anchor hydrolysate demand through enteral feeding product lines and medical peptide formulations. Regulatory frameworks in multiple jurisdictions reshape ingredient approval pathways and label claim permissibility.
Germany
Enteral nutrition manufacturers in North Rhine-Westphalia drive pharmaceutical-grade hydrolysate procurement for hospital feeding systems. EFSA novel food assessments govern peptide-specific positioning in adult medical foods. Cologne-based ingredient houses coordinate with Bavarian dairy alternatives producers on enzymatic hydrolysate integration.
China
SAMR enforcement of GB 28050-2021 redirects hydrolysate volumes from infant formula toward adult medical nutrition and geriatric care applications. School meal protein fortification programs under FSSAI guidelines create institutional procurement channels. Yangtze River Delta beverage manufacturers pivot hydrolysate claims toward whole-protein equivalence statements.
United States
FDA GRAS notifications structure entry pathways for food-grade hydrolysate ingredients targeting sports nutrition and clinical segments. Post-workout recovery brands specify sub-10 kDa peptide fractions for rapid amino acid kinetics. California contract manufacturers demand batch-level peptide profiling from ingredient vendors.
Norway
Salmon aquaculture operators substitute hydrolyzed soy peptides for fishmeal to comply with marine ingredient reduction mandates. FAMI-QS certification requirements govern EU market access for feed-grade hydrolysate producers. Bergen-area feed compounders specify inclusion rates for hydrolysate-enhanced salmon diets.
India
FSSAI's 2023 protein fortification guidelines for school meals and mid-day programs open institutional channels for hydrolysate-enhanced products. Domestic functional food manufacturers source concentrate-derived hydrolysates for adult protein fortification. Maharashtra-based ingredient distributors coordinate with Gujarat processing facilities on cost-efficient hydrolysate supply.
Soy Protein Hydrolysate Market Competitive Landscape
Global majors compete with regional champions across enzymatic processing capability and origination contract security. The vendor base stratifies into integrated crushers with captive protease supply, flavor-system specialists, and merchant hydrolysate processors. Three archetypes dominate: North American agricultural conglomerates with crushing networks, European ingredient houses with clinical nutrition positioning, and Asian plantation-integrated processors. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Within the integrated agricultural tier, Cargill and Archer Daniels Midland occupy positions defined by wet-milling infrastructure and multi-continent bean origination. Kerry Group exemplifies the flavor-masked hydrolysate system specialist archetype, competing on beverage application co-development. Among Asian plantation-integrated players, Wilmar International Limited anchors the cost-efficient feed-grade supply position through Southeast Asian crushing assets.
| Leading Market Players |
|---|
| DuPont |
| Archer Daniels Midland |
| ADM |
| CHS Inc. |
| Wilmar International Limited |
| Cargill |
| Sojaprotein |
| Bunge |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Batch-level peptide profiling requirements from U.S. sports nutrition brands are forcing hydrolysate suppliers to invest in in-house analytical capabilities, compressing margins for merchant processors while concentrating pricing power among integrated operators with captive testing infrastructure.
Pricing Analysis
Input-cost pass-through from identity-preserved non-GMO soybean premiums runs through food-grade hydrolysate tiers, with organic-positioned brands absorbing 15-25% uplifts over conventional feedstocks. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates clinical nutrition suppliers from commodity aquaculture feed compounders. Pricing pressure stems from Brazilian crushing concentration, where three processors control 60% of South American isolate feedstock. Feed-grade buyers in Norway and Chile exhibit highest price sensitivity due to marine ingredient reduction mandates, while German enteral nutrition brands show lowest sensitivity given nitrogen purity non-negotiability.
Supply Chain Analysis
Workforce availability constraints in Iowa and Illinois wet-milling corridors, combined with skilled enzymologist shortages in Bavaria and North Rhine-Westphalia, are tightening production capacity for high-specification hydrolysate fractions. Supply concentrates in the United States, Germany, and China, with Yangtze River Delta beverage manufacturers and Cologne-based ingredient houses anchoring regional demand clusters. Raw material dependencies span identity-preserved soybeans, food-grade protease enzymes, and ceramic membrane filtration systems. Single-source vulnerability permeates the protease tier, where three enzyme houses control 80% of food-grade supply. Distribution runs through direct technical sales for B2B ingredient volumes and subscription channels for direct-to-consumer protein brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's SAMR-restricted infant formula segment and India's FSSAI-fortified school meal programs creates cost-adjacent demand migration for hydrolysate volumes seeking permissible peptide-specific claim environments.
For Market Incumbents: Deploy captive protease supply chains to lock in margin advantages against merchant hydrolysate processors facing Q4 enzyme scarcity. Secure origination contracts with Brazilian crushers before capacity allocation tightens. Invest in ceramic membrane filtration infrastructure to cut process water consumption and meet German beverage manufacturer sustainability specifications. For New Entrants and Emerging Players: Capture India's functional foods white space under FSSAI's 2023 protein fortification guidelines for school meals and mid-day programs. Target Maharashtra-based ingredient distributors coordinating with Gujarat processing facilities for cost-efficient supply aggregation. Pursue direct-to-consumer subscription channels for ready-to-mix protein brands bypassing traditional distribution markups. For Investors and Strategic Acquirers: Asymmetric upside sits with flavor-system specialists capable of masking bitter peptide off-flavors in neutral-pH beverage applications. Long-term viability centers on suppliers with clinical nutrition positioning and pharmaceutical-grade certification depth. Watch enzyme supplier consolidation velocity as inflection indicator for input cost trajectory and margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protease Supply | Captive enzyme production insulates margins from Q4 scarcity peaks at three dominant supplier houses. |
| Ceramic Membrane Filtration Scale-Up | German and U.S. sports nutrition manufacturers adopt pilot systems cutting process water consumption by 40%. |
| FAMI-QS Certification Investment | Twelve-to-eighteen-month audit cycles for EU market access delay revenue recognition for new feed-grade assets. |
| Direct-to-Consumer Channel Launch | Subscription models capture full value chain margin bypassing traditional retail distribution markups. |
| Clinical Nutrition Partnership | Cologne-based ingredient houses coordinate with Bavarian dairy alternatives producers on enzymatic integration. |
Research Methodology
Direct dialogue with hydrolysate procurement managers at sports nutrition brands, enzymology directors at processing facilities, regulatory affairs leads navigating FDA GRAS and EFSA novel food pathways, and aquaculture feed compounders in Norway and Chile grounded qualitative findings. Secondary validation drew from FDA GRAS notification databases, EFSA novel food assessment registers, SAMR GB standard enforcement bulletins, FAMI-QS certification records, and customs trade data for soy protein isolate flows. Bottom-up volume builds across application segments triangulated against top-down market sizing from crushing capacity and peptide fraction yield assumptions.
Bottom-up modeling aggregated hydrolysate consumption by product grade, application end-use, and geographic regulatory cluster across the analysis window. Segmentation dimensions spanned isolate-concentrate-hydrolysate product tiers, food-beverage-supplement-feed application splits, and country-specific certification requirements. CAGRs derived from enzyme technology diffusion curves, aquaculture feed substitution rates, and clinical nutrition formulation shifts. Industry-specific inputs included protease supplier concentration indices and Brazilian crushing capacity utilization rates.
Underlying measurement precision varies by segment; pharmaceutical-grade hydrolysate volumes carry tighter precision than feed-grade commodity tiers due to concentrated buyer visibility. Forecasts reflect assumptions around regulatory pathway timelines, enzyme technology adoption curves, and aquaculture marine ingredient reduction mandate compliance. Material deviation in SAMR enforcement intensity, Brazilian crushing consolidation, or protease supplier merger activity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
USA Yeast Extracts Market
Ingredients
Global Gelatin Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Revivable Yeast Market
Ingredients
Cheese Cultures Market
Ingredients
Vegetable Concentrates Market
Ingredients
Stabilized Starch Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Egg Free Premix Market
Ingredients
South America Vegetable Oil Market
Ingredients
Microencapsulated Oil Market
Ingredients
Clean Label Flour Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Fig Ingredient Market