
 Industrial and Bar-B-Que Charcoal Market | 2026-2036
Industrial and Bar-B-Que Charcoal Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial and Bar-B-Que Charcoal Market Outlook
Asset-light leasing models for carbonization kilns are rewriting capital barriers for new entrants in the charcoal supply chain. Kingsford Products Company leverages its captive hardwood supply networks across the eastern United States to sustain consistent briquette output. Royal Oak Enterprises anchors its position through deep channel control in mass retail and club store distribution. Gryfskand sp. Z.o.o competes by specializing in premium European hardwood grades for industrial metallurgy applications.
Industrial and Bar-B-Que Charcoal comprises carbonized biomass typically produced through pyrolysis at temperatures between 400°C and 700°C in oxygen-limited environments, yielding a porous carbon matrix with fixed carbon content exceeding 75% by weight. Its primary commercial purpose spans high-heat metallurgical processes, water filtration media, and controlled-combustion cooking applications where consistent burn profiles matter. Briquettes dominate volume throughput in North American retail channels due to standardized density and predictable ignition behavior, while natural lump commands premium positioning among restaurant buyers seeking rapid heat-up and minimal ash residue. The instant light segment carries elevated margin pools through proprietary accelerant formulations, though regulatory scrutiny on chemical additives is intensifying.
The EPA enforces particulate matter thresholds for domestic charcoal manufacturing facilities under Clean Air Act provisions, pushing producers toward enclosed retort systems. The EU Deforestation Regulation mandates geolocation traceability for all charcoal sold into European Union member states, reshaping sourcing documentation requirements for exporters in Indonesia and Brazil. FDA food-contact assessments govern charcoal marketed for direct cooking applications in the United States, creating compliance bifurcation between industrial and consumer grades. Stakeholders must monitor how carbon border adjustment mechanisms and emerging biochar certification standards redefine competitive access across key demand corridors.
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing wholesale restructuring of charcoal import documentation, with European port authorities now rejecting shipments lacking geolocation-verified supply chain records from origin forests.
Growth Catalysts
- Churrascaria expansion:Restaurant chains across Southeast Asia are scaling wood-fired menu formats, driving bulk procurement contracts for natural lump grades with minimal ash residue specifications.
- EU Deforestation Regulation:The EUDR is accelerating supplier consolidation as only large-scale exporters can afford satellite-based geolocation tracking systems for forest-origin documentation.
- Pyrolysis retort modernization:Enclosed carbonization systems are capturing methane byproducts for energy recovery, improving unit economics for facilities upgrading from traditional kiln methods.
Market Restraints
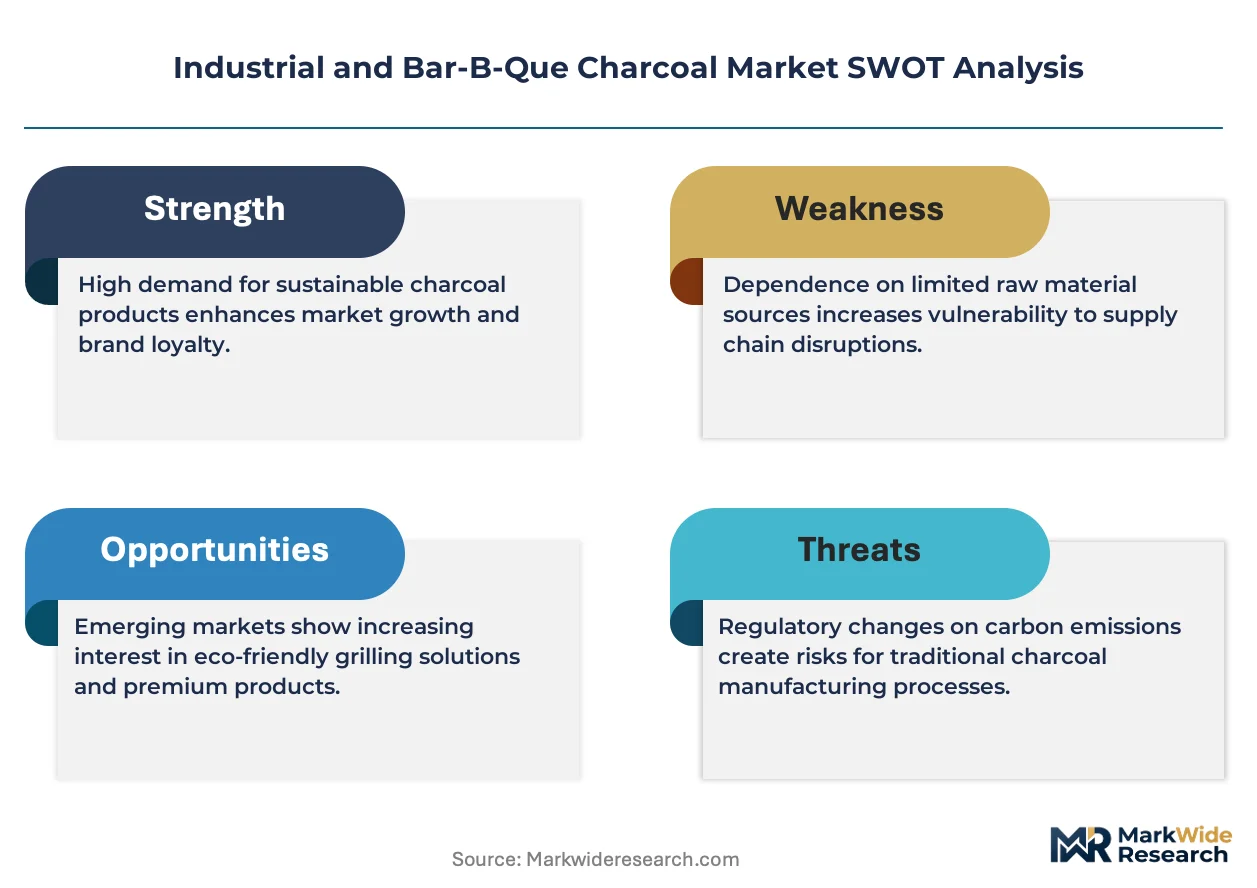
- Hardwood feedstock volatility:Sawmill residue and forestry thinning supplies fluctuate with construction cycles and pest outbreaks, compressing margins for briquette producers without captive timber access.
- Brazilian production concentration:Domestic churrascaria culture and industrial metallurgy demand absorb most South American hardwood carbonization capacity, limiting export availability during peak seasons.
- Accelerant chemical scrutiny:FDA food-contact assessments and state-level air quality boards are restricting proprietary instant-light formulations, constraining margin pools in the premium convenience segment.
Strategic Opportunities
- Biochar certification pathways:Emerging carbon sequestration credit frameworks for pyrogenic carbon are creating dual-revenue models for producers able to document permanence and measurement protocols.
- Asset-light kiln leasing:Retort system lessors are lowering capital barriers for new entrants in Indonesia and Vietnam, enabling rapid capacity scaling without balance-sheet-heavy infrastructure commitments.
- Industrial metallurgy specialization:Premium European hardwood grades for silicon and ferroalloy production command price premiums over cooking applications, rewarding producers with metallurgical-grade quality control systems.
Industry Challenges
- Cross-border documentation latency:EUDR geolocation traceability requirements are extending customs clearance times at Rotterdam and Hamburg, forcing inventory buffer increases and working capital strain.
- Pyrolysis technician scarcity:Skilled operators capable of managing oxygen-limited retort environments at 400°C to 700°C are concentrated in legacy producing regions, limiting new facility commissioning speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial and Bar-B-Que Charcoal Market |
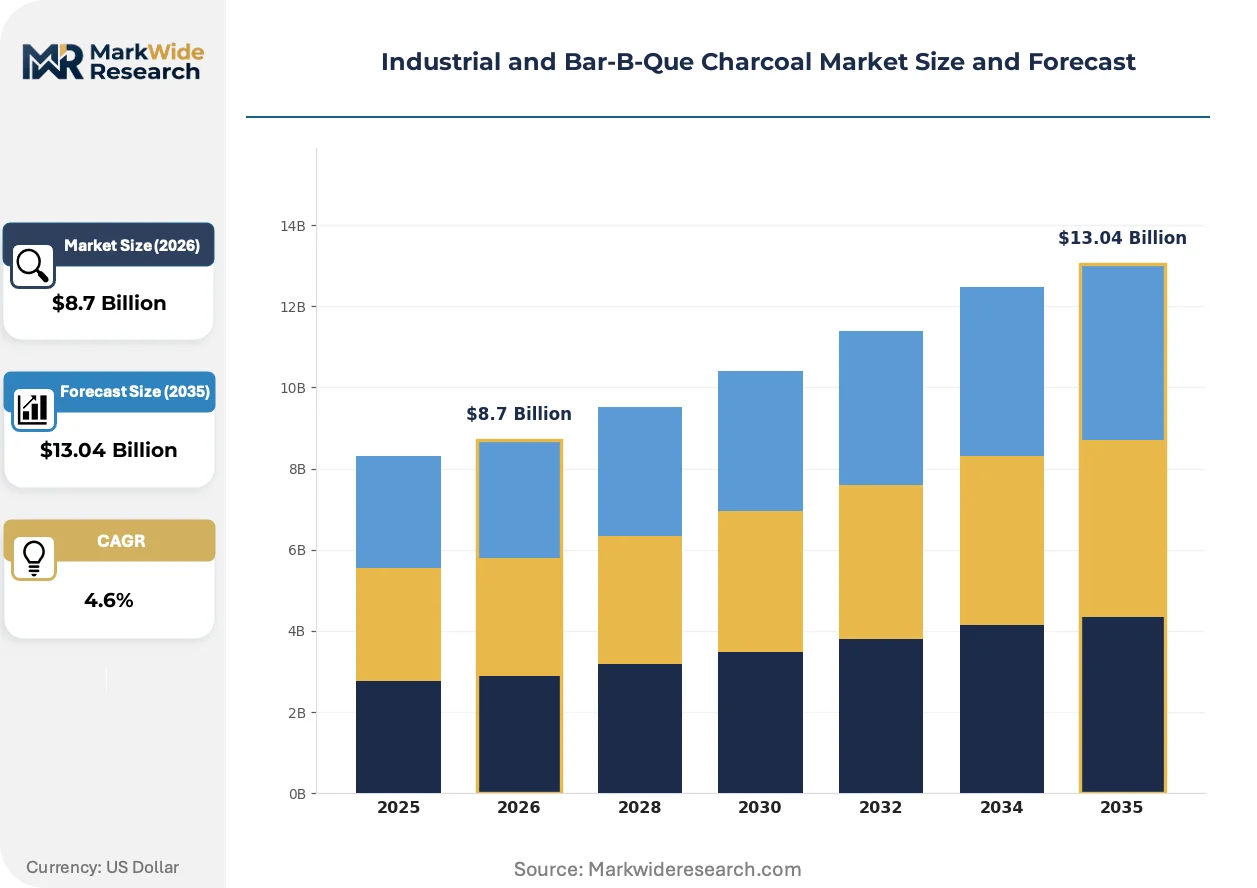
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binchotan, Natural Lump, Briquettes, Instant Light End User: Restaurants, Food Trucks, Catering Services, Home Users Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Supermarkets Material: Hardwood, Coconut Shell, Charcoal Dust, Others |
| Companies Covered | Kingsford Products Company, Royal Oak Enterprises, Duraflame Inc., Gryfskand sp. Z.o.o, MAUROBERA SA, PT Dharma Hutani Makmur, The Saint Louis Charcoal Company, Timber Charcoal Co., Parker Charcoal Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial and Bar-B-Que Charcoal Market Strategic Shifts
Carbonization technology and supply chain verification systems are compressing traditional competitive advantages rooted in feedstock proximity, while regulatory compliance infrastructure itself becomes a differentiating capability.
Continuous-feed pyrolysis retorts with real-time temperature monitoring and automated oxygen control are rendering obsolete batch-operated traditional kilns that depend on manual vent management and produce inconsistent fixed carbon yields. Industrial metallurgy buyers in Germany and Japan are specifying continuous-system output for silicon carbide and ferrochrome applications where carbon reactivity must stay within narrow bands. The technology shift is concentrating supply relationships around producers with capital reserves for retort installation.
EU Deforestation Regulation geolocation traceability requirements are mandating satellite-verified polygon mapping of every forest parcel entering European supply chains, with non-compliant shipments facing port detention and destruction. Indonesian and Brazilian exporters are absorbing third-party audit costs and blockchain documentation platform subscriptions to maintain market access. The compliance burden is filtering out informal sector suppliers lacking land-title documentation or cooperative aggregation structures.
Restaurant procurement teams are consolidating supplier relationships around integrated distributors offering combined charcoal, wood chip, and firestarter assortments with consolidated logistics and invoice streams. Southeast Asian churrascaria chains are dropping fragmented spot-market purchasing in favor of annual volume contracts with penalty clauses for specification deviation. The purchasing model compression is disintermediating traditional commodity brokers and rewarding distributors with cold-chain adjacent infrastructure and quality testing laboratories.
Industrial and Bar-B-Que Charcoal Market Segmentation
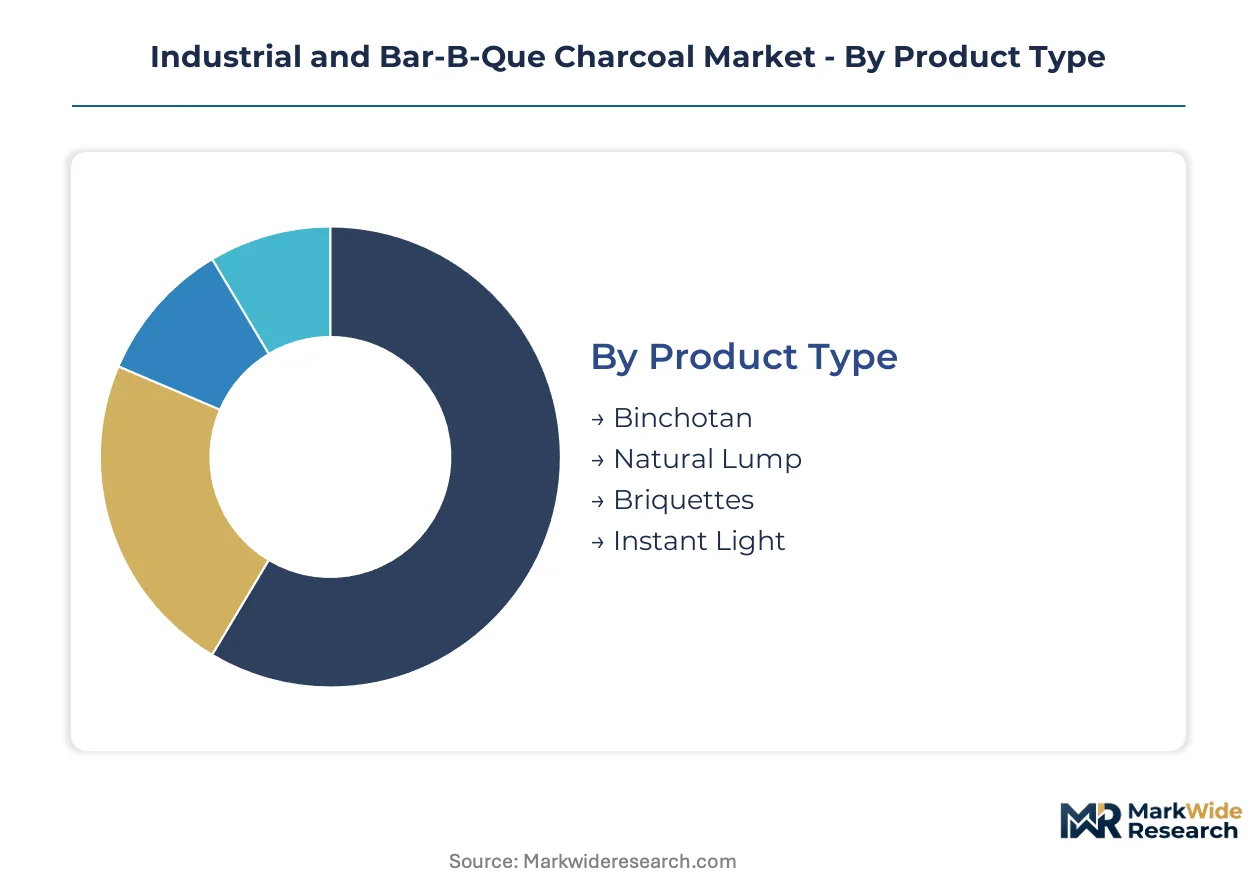
Segmentation in charcoal markets separates commodity-grade volume from premium positioning. Product formulation, end-use thermal requirements, and certification complexity create divergent margin pools across categories.
Product Type:
Charcoal products span artisanal carbonization methods to engineered consistency, with burn profile predictability determining price tier placement.
- Briquettes:Compressed charcoal dust bound with starch or mineral fillers achieves uniform density and controlled burn rates. North American retail channels favor standardized briquette formats for backyard grilling consistency, though EPA Clean Air Act enforcement on particulate emissions is elevating retort-system capital requirements for domestic producers.
- Natural Lump:Irregular carbonized hardwood chunks retain native wood porosity and deliver rapid heat-up with minimal ash residue. Southeast Asian churrascaria chains specify natural lump for wood-fired menu execution, driving bulk procurement contracts with geolocation documentation to satisfy EU Deforestation Regulation port requirements.
- Binchotan:Traditional Japanese white charcoal fired at extreme temperatures yields metallic hardness and infrared radiant heat properties prized for yakitori applications.
- Instant Light:Briquettes impregnated with petroleum-based accelerants enable single-match ignition, though FDA food-contact assessments and state air quality restrictions are constraining chemical additive formulations.
Established volume favors Briquettes; emerging adoption favors Natural Lump.
End User:
Customer thermal requirements range from precise temperature control in professional kitchens to occasional recreational use, with specification stringency scaling accordingly.
- Restaurants:Full-service establishments with dedicated grill stations require consistent heat output and low-ash specifications for continuous service periods. Brazilian churrascaria operators in São Paulo and expanding Southeast Asian chains negotiate annual volume contracts with penalty clauses for specification deviation, consolidating supplier relationships around integrated distributors.
- Catering Services:Mobile and event-based food operations prioritize rapid ignition and portable fuel formats for off-site execution without fixed infrastructure.
- Food Trucks:Space-constrained mobile kitchens favor compact storage and quick heat recovery between service rushes.
- Home Users:Seasonal recreational grilling drives retail channel concentration, with North American consumers predominantly selecting briquette formats for predictable backyard performance.
Procurement consolidation favors Restaurants; seasonal volatility concentrates in Home Users.
Distribution Channel:
Channel selection reflects order scale, specification testing capacity, and documentation burden tolerance across customer tiers.
- Wholesale Distributors:Integrated supply operations offering combined charcoal, wood chip, and firestarter assortments with consolidated logistics are displacing fragmented spot-market purchasing. Southeast Asian restaurant chains favor annual contracts with distributors maintaining cold-chain adjacent infrastructure and quality testing laboratories.
- Retail Stores:Mass merchandisers and hardware chains stock standardized briquette formats for seasonal home grilling demand, with club store formats commanding volume discounts.
- Supermarkets:Grocery channel placement targets impulse purchases and convenience-oriented consumers seeking single-use package sizes.
- Online Platforms:Direct-to-consumer shipment of charcoal faces freight cost disadvantages against bulk wholesale, though specialty binchotan and premium lump grades find niche subscription markets.
Relationship consolidation favors Wholesale Distributors; margin pressure concentrates in Online Platforms.
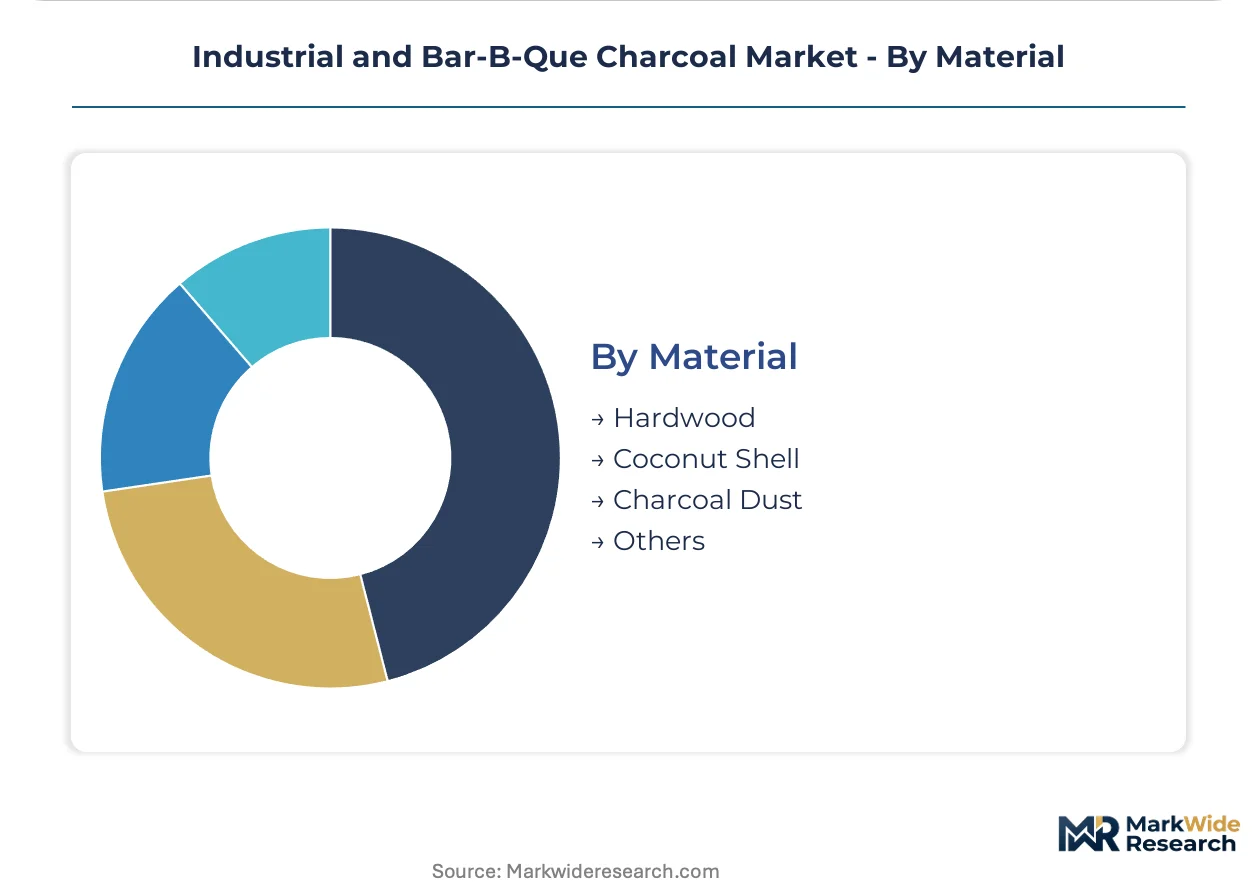
Material:
Feedstock origin determines carbon reactivity, ash chemistry, and regulatory traceability burden across end-use applications.
- Hardwood:Dense timber species including oak, hickory, and quebracho deliver high fixed carbon content and prolonged burn duration. Brazilian domestic production consumes most South American hardwood carbonization capacity for churrascaria culture and industrial metallurgy, limiting export availability during peak seasons.
- Coconut Shell:Agricultural residue from tropical processing operations yields high-surface-area carbon prized for water filtration media and metallurgical applications requiring specific reactivity profiles.
- Charcoal Dust:Sawmill residue and carbonization byproducts serve as briquette feedstock, with supply fluctuating according to construction cycles and pest outbreaks affecting forestry thinning operations.
- Others:Bamboo carbonization and agricultural waste pyrolysis supply regional niche markets with distinct ash chemistry and burn characteristics.
Industrial absorption favors Hardwood; sustainability positioning favors Coconut Shell.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Deforestation Regulation traceability mandates are restructuring import documentation requirements for charcoal entering European ports. Kingsford Products Company leverages captive hardwood supply networks across the eastern United States. Southeast Asian restaurant chains are consolidating procurement around integrated distributors with cold-chain adjacent infrastructure.
United States
Restaurant chains in Texas and the Southeast are expanding wood-fired menu formats, driving bulk procurement contracts for natural lump grades. EPA Clean Air Act enforcement pushes domestic producers toward enclosed retort systems with higher capital requirements. Kingsford Products Company anchors production capacity through captive hardwood networks across Kentucky and Tennessee.
Brazil
Churrascaria culture in São Paulo and industrial metallurgy demand absorb most South American hardwood carbonization capacity. ANVISA governs food-contact assessments for charcoal marketed to restaurant operators. Domestic producers in Minas Gerais and Rio Grande do Sul face limited export availability during peak seasonal demand periods.
Germany
Industrial metallurgy buyers in the Ruhr region specify continuous-feed pyrolysis output for silicon carbide applications requiring narrow carbon reactivity bands. EUDR geolocation traceability requirements extend customs clearance times at Hamburg and Rotterdam ports. Producers in North Rhine-Westphalia concentrate supply relationships around facilities with retort installation capital reserves.
Indonesia
Coconut shell carbonization for water filtration media and metallurgical applications scales capacity through asset-light kiln leasing models. EUDR compliance forces exporters to absorb third-party audit costs and blockchain documentation platform subscriptions. Facilities in Sumatra and Kalimantan filter out informal sector suppliers lacking land-title documentation.
Japan
Binchotan producers in Wakayama Prefecture command premium positioning for yakitori applications requiring infrared radiant heat properties. METI standards govern pyrolysis temperature specifications for traditional white charcoal firing methods. The Kansai region maintains specialized carbonization knowledge concentrated among legacy family-operated kilns.
Industrial and Bar-B-Que Charcoal Market Competitive Environment
On the supply side, the industry is consolidating around producers with capital reserves for continuous-feed retort installation and EUDR-compliant documentation infrastructure. The vendor base separates into three strategic archetypes: captive timber owners with backward-integrated carbonization, specialist distributors with quality testing laboratories, and asset-light kiln lessors enabling rapid capacity scaling. Dominant competitive moves include M&A to secure hardwood feedstock access and strategic partnerships with satellite-based geolocation verification providers.
Among North American producers, Kingsford Products Company and Royal Oak Enterprises exemplify the captive-supply archetype through control of hardwood sourcing networks. Gryfskand sp. Z.o.o occupies a position representing European metallurgical-grade specialization. These three anchors illustrate how feedstock proximity, channel control, and certification infrastructure define competitive positioning across distinct regional demand corridors.
| Leading Market Players |
|---|
| Kingsford Products Company |
| Royal Oak Enterprises |
| Duraflame Inc. |
| Gryfskand sp. Z.o.o |
| MAUROBERA SA |
| PT Dharma Hutani Makmur |
| The Saint Louis Charcoal Company |
| Timber Charcoal Co. |
| Parker Charcoal Company |
| Others |
Value Chain & Pricing Dynamics
Brazilian hardwood carbonization capacity absorbs most South American feedstock for domestic churrascaria and industrial metallurgy, concentrating margin capture among distributors with EUDR-compliant documentation infrastructure and cold-chain adjacent quality testing laboratories.
Pricing Analysis
Certification level creates the primary spread between metallurgical-grade European hardwood and commodity cooking grades, with EUDR geolocation traceability and biochar carbon sequestration documentation commanding premium positioning. Three-tier pricing structure separates premium continuous-feed retort output from standard batch-kiln grades and economy briquette formats. Cost compression in the instant-light segment intensifies because FDA food-contact assessments and state air quality restrictions constrain chemical accelerant formulations. Home users in North American retail channels exhibit highest price sensitivity, while German silicon carbide producers accept elevated rates for narrow-band carbon reactivity specifications.
Supply Chain Analysis
Extended payment terms from wholesale distributors to Indonesian kiln operators now stretch ninety to one hundred twenty days, reflecting working capital strain from EUDR documentation latency at European ports. Raw material flows draw from Brazilian quebracho forests, Indonesian coconut shell processing residues, and eastern United States hardwood thinning operations. Single-source vulnerability concentrates in pyrolysis technician scarcity, with skilled retort operators concentrated in legacy producing regions. Distribution runs through integrated distributors offering combined charcoal, wood chip, and firestarter assortments with consolidated logistics and annual volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Restaurant procurement consolidation around integrated distributors with quality testing infrastructure represents a platform-economics inflection, as EUDR traceability requirements and blockchain documentation platforms create interoperability barriers for fragmented spot-market suppliers.
For Market Incumbents:Pre-empt kiln leasing competitors by acquiring captive hardwood networks in Kentucky and Tennessee, securing feedstock proximity that asset-light entrants cannot replicate. Invest in continuous-feed retort installation to meet German metallurgy specifications and displace batch-kiln rivals. Channel control through club store distribution defends against private-label encroachment in North American retail.
For New Entrants and Emerging Players:Pursue biochar certification pathways in Indonesia and Vietnam, where carbon sequestration credit frameworks create dual-revenue models without retort capital requirements. Asset-light kiln leasing from third-party lessors enables rapid capacity scaling in Sumatra and Kalimantan. Target Southeast Asian churrascaria chains with geolocation-verified natural lump grades and annual contract structures.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with PE-backed distributors lacking EUDR-compliant documentation infrastructure, creating consolidation targets for buyers with satellite-based geolocation verification capabilities. Long-term viability hinges on regulatory compliance architecture rather than feedstock proximity alone. Watch for carbon border adjustment mechanism implementation as inflection indicator for premium-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Feed Retort Installation | Meets German silicon carbide specifications and concentrates supply relationships around capital-reserved producers. |
| EUDR Geolocation Traceability Investment | Enables European port access and filters out informal sector competitors lacking land-title documentation. |
| Asset-Light Kiln Leasing Expansion | Lowers capital barriers for Indonesian and Vietnamese entrants without balance-sheet-heavy infrastructure. |
| Biochar Certification Program | Creates dual-revenue streams through carbon sequestration credits for pyrogenic carbon documentation. |
| Integrated Distributor Partnership | Consolidates Southeast Asian restaurant procurement around cold-chain adjacent quality testing laboratories. |
Study Parameters
Operator-level perspectives from pyrolysis technicians, wholesale distributor procurement leads, churrascaria chain supply managers, and metallurgical buyer quality engineers anchored the qualitative base. Primary fieldwork combined with customs trade records, EPA Clean Air Act enforcement disclosures, EUDR implementation guidance documents, and SEC filings from captive timber owners. Bottom-up capacity assessments across Brazilian, Indonesian, and United States production facilities triangulated against top-down demand estimates from restaurant expansion pipelines and industrial metallurgy consumption patterns.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product formulation, end-use thermal requirements, feedstock origin, and certification complexity. CAGRs derived from trend extrapolation of churrascaria chain expansion rates, retort modernization capital deployment cycles, and EUDR compliance cost absorption trajectories. Forecast inputs incorporated hardwood feedstock volatility from construction cycle correlation and pyrolysis technician scarcity constraints on new facility commissioning speeds.
Sensitivities concentrate around EUDR documentation latency extensions, Brazilian export availability during peak domestic demand seasons, and accelerant chemical restriction tightening. Forecasts reflect stated assumptions regarding regulatory implementation timelines and technology adoption curves. Macroeconomic construction cycle downturn, unilateral regulatory delay, or breakthrough continuous-pyrolysis automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Distillers Corn Oil Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Asparagus Extract Market
Ingredients
China Cane Sugar Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Citrus Pectin Market
Ingredients
Bean Ingredients Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Boysenberry Extract Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Virginiamycin Market
Ingredients
Hen Egg White Protein Market
Ingredients
Pulses Ingredients Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Sunflower Lecithin Market