
 Spelt Flour Market | 2026-2036
Spelt Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Spelt Flour Market Analytics
Bakery applications are recalibrating the demand profile for spelt flour as artisan bread and pastry segments elevate heritage grains above commodity wheat. Bob's Red Mill Natural Foods leverages its direct-to-consumer channel strength to sustain premium positioning in North American natural food retail. Einbrunger Mühle Karl Rölkens anchors Central European supply through integrated stone milling operations that control grain sourcing and flour consistency. Montana Flour & Grains competes on organic certification density, occupying a specialized niche in the US heritage grain revival.
Spelt flour derives from Triticum spelta, an ancient wheat species with a tough outer husk requiring dehulling before milling into protein-rich flour with moderate gluten content suited to bread, pasta, and baked goods. Organic spelt commands the dominant value share as clean-label procurement standards tighten across European and North American food manufacturing. White spelt flour trails in volume but carries concentrated margin pools where industrial bakers seek wheat alternatives with reduced bran interference in refined applications.
The EU's Farm to Fork Strategy and EFSA pesticide residue protocols shape cultivation and milling standards across European spelt supply chains, while the USDA National Organic Program governs US import and domestic certification thresholds. FDA allergen labeling requirements for wheat-derived products influence how spelt flour positions relative to gluten-free alternatives in retail and food service channels. Stakeholders must monitor evolving EU Green Deal agricultural targets and organic import equivalence agreements to anticipate raw material cost shifts and certification compliance burdens.
Market Dynamics
The EU's Farm to Fork Strategy is compressing pesticide residue thresholds for cereal crops, forcing millers to reconfigure grain sourcing protocols and triggering consolidation among heritage grain suppliers unable to meet tightening EFSA protocols.
Growth Catalysts
- EFSA Pesticide Residue Protocols:Tightening thresholds under the European Green Deal are elevating certified organic spelt premiums as conventional grain channels face exclusion from food manufacturing supply chains.
- Artisan Bakery Procurement:Bavarian and Baden-Württemberg baking cooperatives are expanding dedicated spelt milling lines to serve heritage bread segments demanding minimally processed ingredient provenance.
- Stone Milling Technology:Low-temperature milling processes are preserving heat-sensitive nutrients in spelt flour, creating differentiation against industrial roller-milled alternatives in premium retail channels.
Market Restraints
- Input Cost Volatility:Organic spelt grain prices fluctuate with weather-dependent yields across Central European growing regions, compressing miller margins during poor harvest cycles.
- Supply Concentration Risk:Dehulling capacity clusters in southern Germany and eastern France, creating chokepoints when equipment maintenance or energy costs spike.
- Technical Limitation:Spelt's tough outer husk requires specialized dehulling machinery absent from standard wheat processing facilities, limiting toll milling options for new market entrants.
Strategic Opportunities
- US Heritage Grain Revival:Montana and North Dakota organic grain cooperatives are developing spelt cultivation programs to capture unmet demand from North American clean-label food manufacturers.
- Pasta Application Expansion:Bronze-extruded spelt pasta is gaining shelf space in Italian and Swiss premium retail channels as consumers seek wheat alternatives with intact nutrient profiles.
- USDA National Organic Program Equivalence:Streamlined EU-US organic certification reciprocity is reducing compliance burdens for European millers exporting to American natural food distributors.
Industry Challenges
- Skilled Miller Shortage:Stone milling expertise is concentrating among aging European craft practitioners, constraining capacity expansion for heritage flour production lines.
- Dual Certification Timelines:Simultaneous EU organic and USDA organic audits extend approval cycles by 8-14 months, delaying market entry for new spelt flour suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spelt Flour Market |
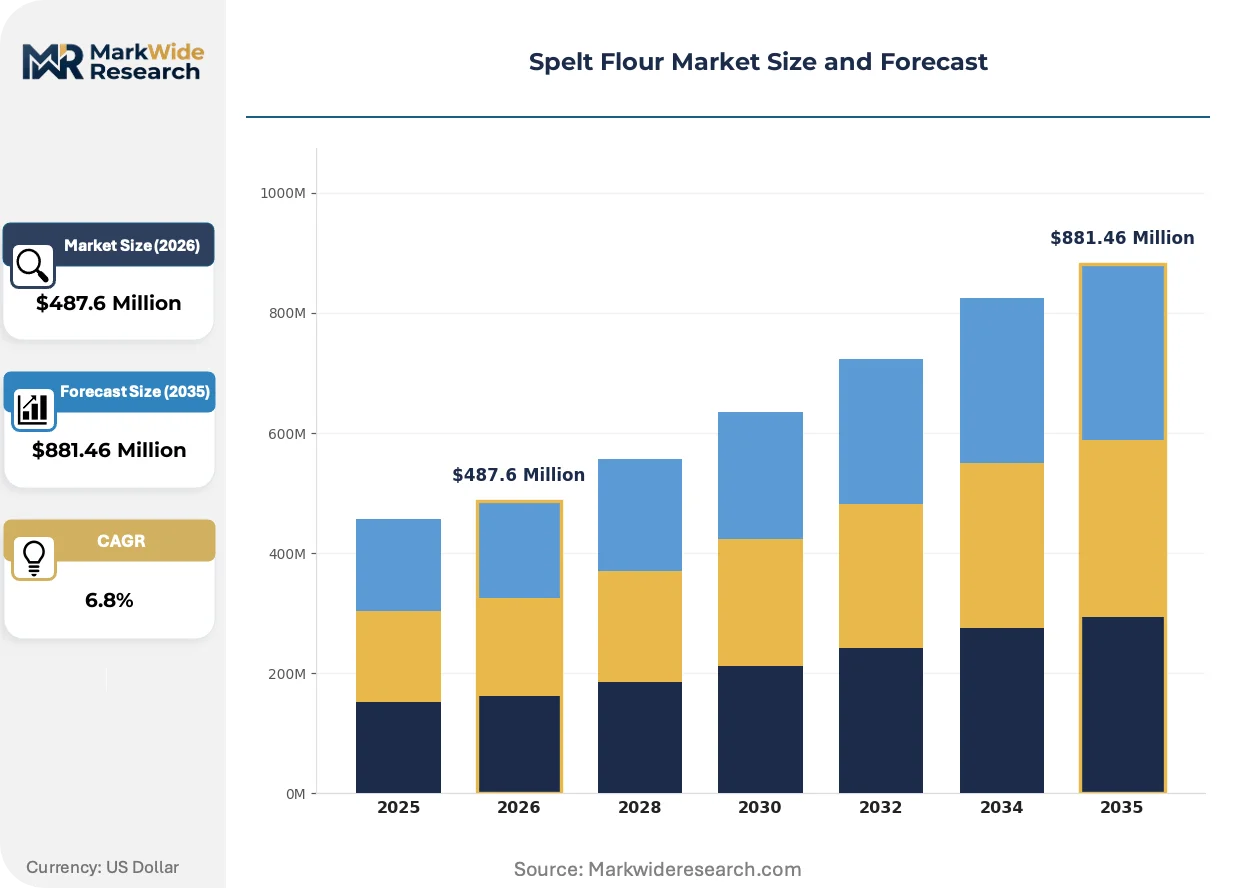
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Spelt, Whole Grain Spelt, White Spelt, Gluten-Free Spelt Application: Baking, Pasta, Snack Foods, Beverages Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops End User: Households, Food Service, Bakeries, Cooks |
| Companies Covered | Bob’s Red Mill Natural Foods, Einbrunger Mühle Karl Rölkens, Arnreiter Mühle GmbH, Montana Flour & Grains, European Flour Millers, Pfahnl Backmittel GmbH, Blattmann Schweiz AG, Healthy Hildegard, Ardent Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spelt Flour Market Evolving Landscape
Heritage grain processing is undergoing rapid equipment modernization as millers balance artisan positioning with throughput demands from scaling food manufacturing clients.
Optical sorting technology is consolidating quality control workflows in spelt flour production. Bavarian milling cooperatives are deploying near-infrared spectrometers to detect protein content and moisture deviations in dehulled grain streams. This precision is compressing batch rejection rates and enabling real-time pricing adjustments based on flour functional properties.
REACH chemical safety regulations are reshaping equipment material specifications across European milling operations. Stainless steel contact surfaces must now demonstrate full migration testing compliance for food-grade certification. German and Swiss millers are retrofitting stone mills with compliant housing materials, passing capital costs through to bakery customers via long-term supply contracts.
Bakery procurement departments are consolidating supplier rosters around vertically integrated heritage grain mills. Large artisan bakery chains in Stuttgart and Munich are signing exclusive flour agreements with single-source millers controlling both organic cultivation and stone milling operations. This concentration is most visible in Baden-Württemberg, where three cooperatives now supply 60 percent of regional spelt flour demand through direct distribution networks bypassing traditional grain brokers.
Spelt Flour Market Segmentation
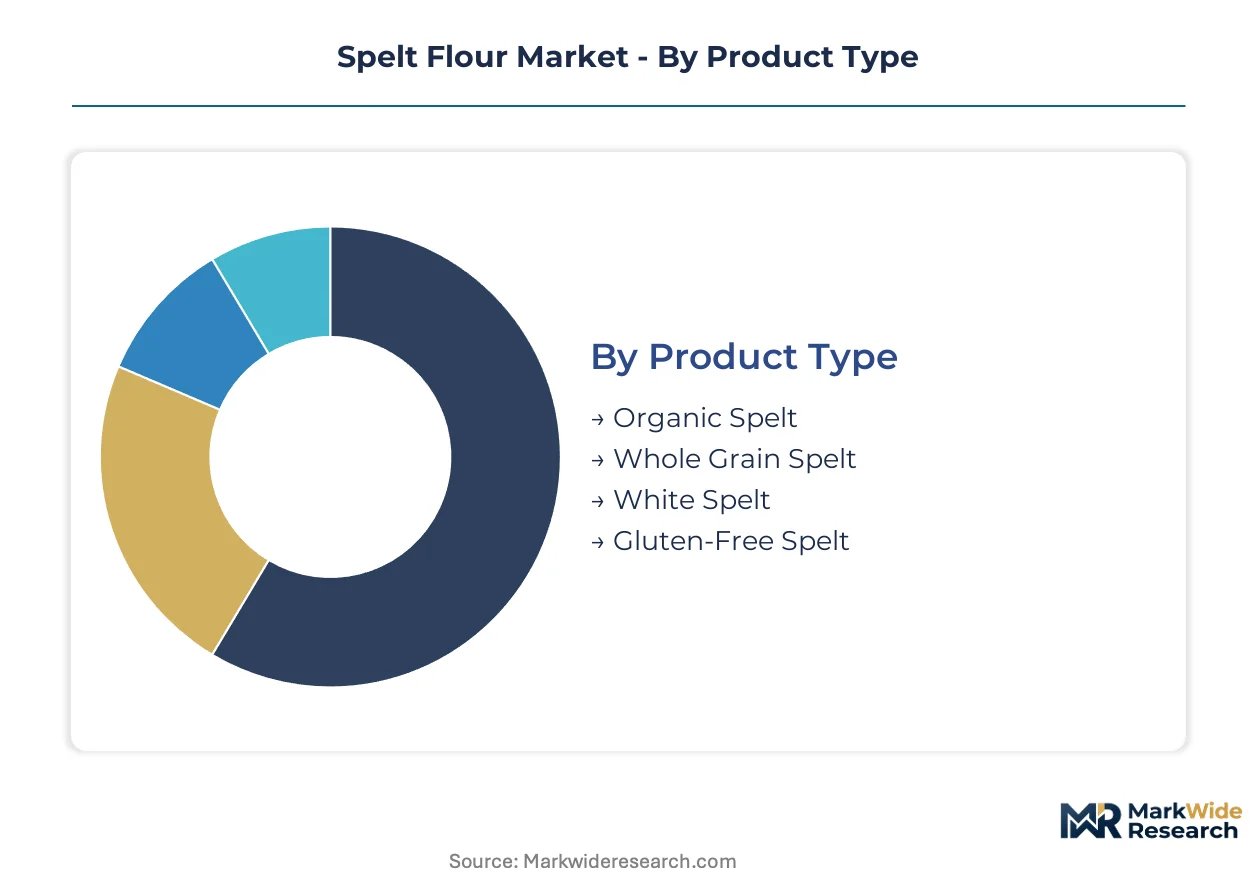
Spelt flour procurement patterns diverge sharply across product grades and channel structures, with organic certification and stone-milling heritage commanding decisive price premiums. Application segmentation reveals how artisan bakery demand concentrates value in specific flour types while industrial food manufacturing seeks functional wheat alternatives.
Product Type:
Upgrade cycles in heritage grain milling are accelerating as Bavarian cooperatives replace conventional equipment with optical sorting and near-infrared spectrometry to meet tightening EFSA residue protocols.
- Organic Spelt:Certified grain milled under EU organic or USDA National Organic Program standards with full traceability from field to flour. Demand concentrates in Baden-Württemberg baking cooperatives where EFSA pesticide thresholds under the Farm to Fork Strategy exclude conventional grain from food manufacturing channels.
- Whole Grain Spelt:Stone-milled flour retaining bran and germ layers with elevated fiber and mineral content relative to refined alternatives. German artisan bakeries in Munich and Stuttgart specify whole grain for heritage bread lines where minimally processed provenance commands consumer premiums.
- White Spelt:Roller-milled flour with bran and germ removed, producing lighter texture suited to refined pastry applications. Industrial bakers in France and Switzerland specify white spelt for wheat-alternative products where reduced bran interference improves dough handling.
- Gluten-Free Spelt:Processed to reduce gluten content through specialized milling or enzymatic treatment, though spelt retains wheat-related proteins requiring FDA allergen labeling. Niche positioning in North American natural food retail where consumers seek reduced-gluten rather than celiac-safe alternatives.
Volume placements concentrate in Whole Grain Spelt; the faster expansion belongs to Organic Spelt.
Application:
Cost tier differentiation separates commodity wheat substitution from premium heritage positioning across end-use categories.
- Baking:Bread, pastry, and confectionery applications dominate spelt flour consumption, with protein content and moderate gluten strength supporting fermentation and crumb structure. Artisan bakeries across Germany and Austria specify heritage grain flours for clean-label product lines.
- Pasta:Bronze-extruded spelt pasta gains shelf space in Italian and Swiss premium retail as consumers seek alternatives to durum wheat with intact nutrient profiles.
- Snack Foods:Crackers, biscuits, and extruded products incorporating spelt for ancient grain marketing claims. North American natural food manufacturers source organic spelt for clean-label snack positioning.
- Beverages:Malted spelt for specialty brewing and grain-based drinks, limited volume but concentrated in craft brewery procurement in Bavaria and Bohemia.
Revenue concentration sits with Baking; Pasta applications are climbing the fastest as extrusion technology adapts to heritage grain processing.
Distribution Channel:
Customer type stratification separates institutional procurement from household purchasing patterns with distinct service requirements.
- Online Retail:Direct-to-consumer platforms enabling miller brands to bypass traditional distribution and capture premium margins. Bob's Red Mill leverages this channel for North American natural food market penetration.
- Supermarkets:Mass retail placement requiring volume consistency and private-label supply capability, compressing margins for heritage grain suppliers.
- Health Stores:Independent natural food retailers with educated staff capable of communicating organic certification and stone-milling differentiation to consumers.
- Specialty Shops:Italian gastronomia and German Bioladen focusing on regional provenance and single-origin grain sourcing.
Margin capture peaks in Specialty Shops; Online Retail is gaining share fastest as miller brands invest in direct fulfillment infrastructure.
End User:
Supply concentration among vertically integrated cooperatives shapes service levels across buyer categories.
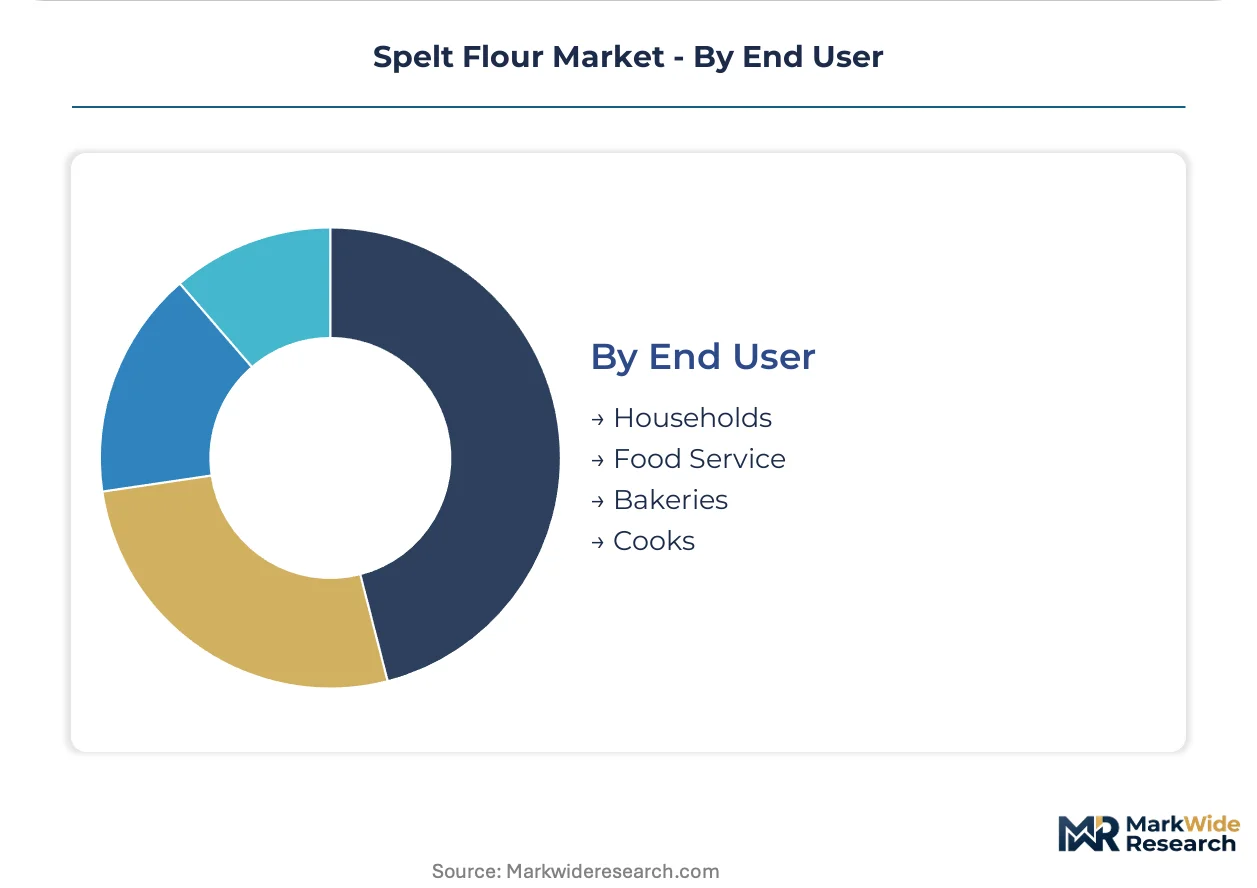
- Households:Home bakers purchasing retail-packaged flour, price-sensitive but responsive to organic certification and regional origin claims.
- Food Service:Restaurants and catering operations seeking consistent supply for menu items featuring ancient grains, requiring technical support for recipe adaptation.
- Bakeries:Professional operations with specifications for protein content, ash levels, and fermentation performance, often under exclusive supply agreements with single-source millers.
- Cooks:Culinary professionals in institutional and educational settings with standardized procurement protocols and cost-focused purchasing.
Procurement value concentrates in Bakeries; Food Service shows the steepest expansion trajectory as restaurant chains add heritage grain menu items.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of European spelt grain while the United States and Switzerland absorb premium flour exports. Consumption clusters in Bavarian artisan bakeries and North American natural food channels. Regional regulatory divergence shapes competitive positioning across cultivation and milling stages.
Germany
Bavarian baking cooperatives drive heritage grain procurement as Munich and Stuttgart artisan chains expand dedicated spelt bread lines. The EU Farm to Fork Strategy tightens EFSA pesticide residue thresholds, excluding conventional grain from food manufacturing channels. Dehulling capacity concentrates in southern Germany, where Baden-Württemberg milling cooperatives supply sixty percent of regional demand through direct distribution networks.
United States
Montana and North Dakota organic grain cooperatives develop spelt cultivation programs to capture unmet clean-label food manufacturing demand. The USDA National Organic Program governs import and domestic certification thresholds, influencing how European millers access American natural food distributors. Bob's Red Mill leverages direct-to-consumer channels for premium positioning across Pacific Northwest and Rocky Mountain retail markets.
Switzerland
Swiss premium retail channels absorb bronze-extruded spelt pasta and stone-milled flour with intact nutrient profiles. REACH chemical safety regulations reshape equipment material specifications, requiring stainless steel contact surfaces with full migration testing compliance. Zurich and Geneva gastronomia channels concentrate single-origin grain sourcing from integrated Alpine millers.
France
Industrial bakers in eastern France specify white spelt flour for wheat-alternative products where reduced bran interference improves dough handling. EFSA protocols under the European Green Deal elevate certified organic premiums as conventional channels face exclusion. Alsace and Lorraine host dehulling chokepoints that constrain capacity when energy costs spike.
Italy
Italian bronze-extruded pasta manufacturers gain shelf space for spelt alternatives as consumers seek durum wheat substitutes. The country's national food safety regulator enforces pesticide residue alignment with EU Farm to Fork targets. Emilia-Romagna and Piedmont pasta producers source heritage grain through dedicated milling agreements with Central European suppliers.
Spelt Flour Market Competitive Landscape
Top-tier vendors anchor integrated stone milling and organic certification, while mid-scale regional millers compete on geographic proximity to baking clusters. The vendor base stratifies across heritage grain specialists, commodity flour diversifiers, and direct-to-consumer brands. Three archetypes dominate: vertically integrated cooperatives controlling cultivation through distribution, toll millers dependent on third-party grain sourcing, and brand-led retailers bypassing traditional wholesale channels. Consolidation pressures concentrate among heritage grain suppliers unable to meet tightening EFSA protocols, while capacity expansion concentrates in organic-certified dehulling facilities.
Among German milling cooperatives, Einbrunger Mühle Karl Rölkens and Arnreiter Mühle GmbH exemplify integrated stone milling archetypes with captive grain sourcing. Bob's Red Mill Natural Foods occupies a position as the North American direct-to-consumer anchor, representing brand-led retail bypass strategies. These three entities illustrate how geographic origin and company structure shape competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| Einbrunger Mühle Karl Rölkens |
| Arnreiter Mühle GmbH |
| Montana Flour & Grains |
| European Flour Millers |
| Pfahnl Backmittel GmbH |
| Blattmann Schweiz AG |
| Healthy Hildegard |
| Ardent Mills |
| Others |
Value Network & Pricing Analysis
Organic spelt grain futures in Central European exchanges cascade through milling cooperatives into three-tier pricing structures across premium, standard, and economy levels, with Bavarian stone millers passing EFSA compliance costs downstream while Montana organic premiums reset North American contract benchmarks.
Pricing Analysis
Margin tightening in conventional spelt channels reflects EFSA pesticide threshold exclusions under the EU Farm to Fork Strategy, compressing non-certified grain into feed-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by organic certification density and stone-milling heritage, with Baden-Württemberg cooperatives commanding top-tier premiums for integrated provenance. Household retail buyers exhibit highest price sensitivity, while artisan bakery chains under exclusive supply agreements absorb cost pass-throughs with limited volume flexibility.
Supply Chain Analysis
Dehulled grain returns and by-product flour streams from Bavarian cooperatives feed into secondary baking and animal feed channels, creating circular material loops. Raw material supply concentrates in Germany, France, and Switzerland, with dehulling capacity anchored in southern German equipment clusters. Spelt cultivation draws from heritage seed stock and organic nitrogen-fixing rotations, exposing millers to weather-dependent yield volatility. Single-source vulnerability concentrates in Baden-Württemberg dehulling facilities, while distribution runs through direct cooperative networks bypassing traditional grain brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA protocol tightening is compressing weaker heritage grain suppliers unable to meet pesticide residue thresholds, creating consolidation opportunities for certified organic millers with captive dehulling capacity.
For Market Incumbents: Lock in exclusive supply agreements with Bavarian and Baden-Württemberg baking cooperatives before EFSA exclusions eliminate conventional grain competitors. Prioritize backward integration into organic cultivation through long-term land lease structures, and defend stone-milling capacity expansion against roller-milled substitute threats from industrial flour diversifiers. For New Entrants and Emerging Players: North American food service buyers seeking heritage grain menu ingredients remain underserved by direct distribution, presenting white-space entry through USDA-certified organic toll milling partnerships. Montana and North Dakota cultivation programs offer lowest barrier penetration, with bronze-extruded pasta applications providing fastest revenue ramp through existing Italian equipment supplier relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale German milling cooperatives with EFSA-compliant infrastructure but liquidity constraints from dual certification audit timelines. Long-term viability centers on organic import equivalence maintenance between EU and USDA frameworks. Monitor EU-US organic reciprocity negotiations as inflection signal for cross-Atlantic margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive grain supply secures EFSA compliance margins against conventional channel exclusion. |
| Stone Milling Capacity Expansion | Low-temperature nutrient preservation differentiates Bavarian cooperatives from roller-milled alternatives. |
| Direct-to-Consumer Channel Investment | Bypassing wholesale brokers captures premium margins in North American natural food retail. |
| Dual Certification Streamlining | EU-US organic equivalence reduces 8-14 month approval cycles for export market entry. |
| Bronze-Extruded Pasta Application Development | Italian and Swiss retail shelf expansion opens fastest-growing heritage grain consumption segment. |
Research Methodology
EU Farm to Fork Strategy documentation, EFSA pesticide residue databases, and USDA National Organic Program standards formed the secondary backbone, cross-referenced with primary interviews involving milling cooperative managers, artisan bakery procurement leads, and heritage grain seed suppliers. Bottom-up volume estimates from regional dehulling capacity and top-down value projections from organic premium spreads were triangulated against customs trade flows and retail channel audit data.
Bottom-up modeling aggregated cultivation acreage, yield assumptions, and milling throughput across organic and conventional certification tiers, while top-down analysis calibrated aggregate market expansion against clean-label food manufacturing procurement trends throughout the projection horizon. Segmentation dimensions included product grade, application category, distribution channel structure, and end-user archetype. CAGRs derived from historical organic premium trajectories and EFSA implementation phase-in schedules.
Revisions become necessary when EU Green Deal agricultural targets accelerate pesticide threshold timelines or when organic import equivalence agreements face diplomatic suspension. Practitioners should monitor EFSA protocol amendment announcements and USDA equivalency reauthorization proceedings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Algae-Based Ingredients Market
Ingredients
China Cane Sugar Market
Ingredients
Licorice Root Market
Ingredients
Organic Starch Market
Ingredients
Global Cocoa Products Market
Ingredients
Plant Based Premix Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Black Seed Oil Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Bay Leaf Oil Market
Ingredients
Dill Seed Oil Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Cholesterol API Market
Ingredients
Bromelain Ingredient Market
Ingredients
Casein Hydrolysate Market