
 China Citric Acid Market | 2026-2036
China Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
China Citric Acid Market Intelligence
China's dual carbon goals are recalibrating fermentation plant operations across the citric acid value chain. COFCO Biochemical leverages its integrated corn-processing infrastructure to sustain cost advantages in bulk citric acid output. Shandong Ensign Industry anchors regional supply through concentrated manufacturing bases in Shandong Province. RZBC Group differentiates via specialized anhydrous citric acid grades for pharmaceutical contract manufacturing.
Citric acid is a tricarboxylic acid produced primarily through submerged fermentation of Aspergillus niger on carbohydrate substrates, typically yielding purity levels above 99.5% for food-grade material. Its primary commercial purpose centers on pH regulation, chelation, and preservative functions across food systems, pharmaceutical formulations, and industrial cleaning applications. Anhydrous citric acid commands premium positioning in pharmaceutical applications where moisture sensitivity determines formulation stability. Crystal citric acid dominates food and beverage procurement volumes due to handling convenience and dissolution control. Sodium citrate is gaining share in personal care and cleaning agent segments as formulators seek milder alkalinity buffers.
SAMR enforces food additive purity standards under GB 1886.235, while MEE implements wastewater discharge limits that elevate compliance costs for fermentation facilities. NMPA pharmaceutical-grade certification requirements create entry barriers for unqualified producers serving drug manufacturers. Stakeholders must monitor how China's evolving carbon intensity benchmarks reshape provincial production licensing and energy sourcing decisions for fermentation assets.
Market Dynamics
China's dual carbon goals are compressing fermentation plant margins while concentrating operational licenses in provinces with superior renewable energy infrastructure. This structural pressure is reshaping where citric acid capacity can economically operate.
Growth Catalysts
- Natural Preservative Demand:Food and beverage manufacturers are expanding citric acid procurement to replace synthetic preservatives in clean-label formulations.
- GB 1886.235 Enforcement:SAMR's food additive purity standards are consolidating qualified supplier pools, advantaging compliant domestic producers.
- Shandong Cluster Effects:Concentrated manufacturing bases in Shandong Province generate logistics efficiencies and shared wastewater treatment infrastructure.
Market Restraints
- Corn Price Volatility:Fermentation feedstock costs fluctuate with agricultural commodity cycles, compressing bulk citric acid margins unpredictably.
- Shandong Supply Concentration:Over 70 percent of national capacity resides in one province, creating geographic risk exposure to regional energy restrictions.
- MEE Wastewater Limits:Tightening discharge standards elevate compliance capital requirements for fermentation facilities without scale advantages.
Strategic Opportunities
- Pharmaceutical-Grade Anhydrous:NMPA certification requirements create specialized supply gaps that qualified producers can capture at premium pricing.
- Sodium Citrate Personal Care:Formulators in cleaning and cosmetic segments are adopting milder alkalinity buffers for sensitive-skin applications.
- Carbon-Intensive Licensing:Provincial production permits increasingly favor facilities with captive renewable energy or carbon capture integration.
Industry Challenges
- Fermentation Process Expertise:Aspergillus niger strain optimization and contamination control require specialized bioprocess engineers in short supply domestically.
- Multi-Site Certification Timelines:NMPA pharmaceutical-grade approvals demand 18-24 month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Citric Acid Market |
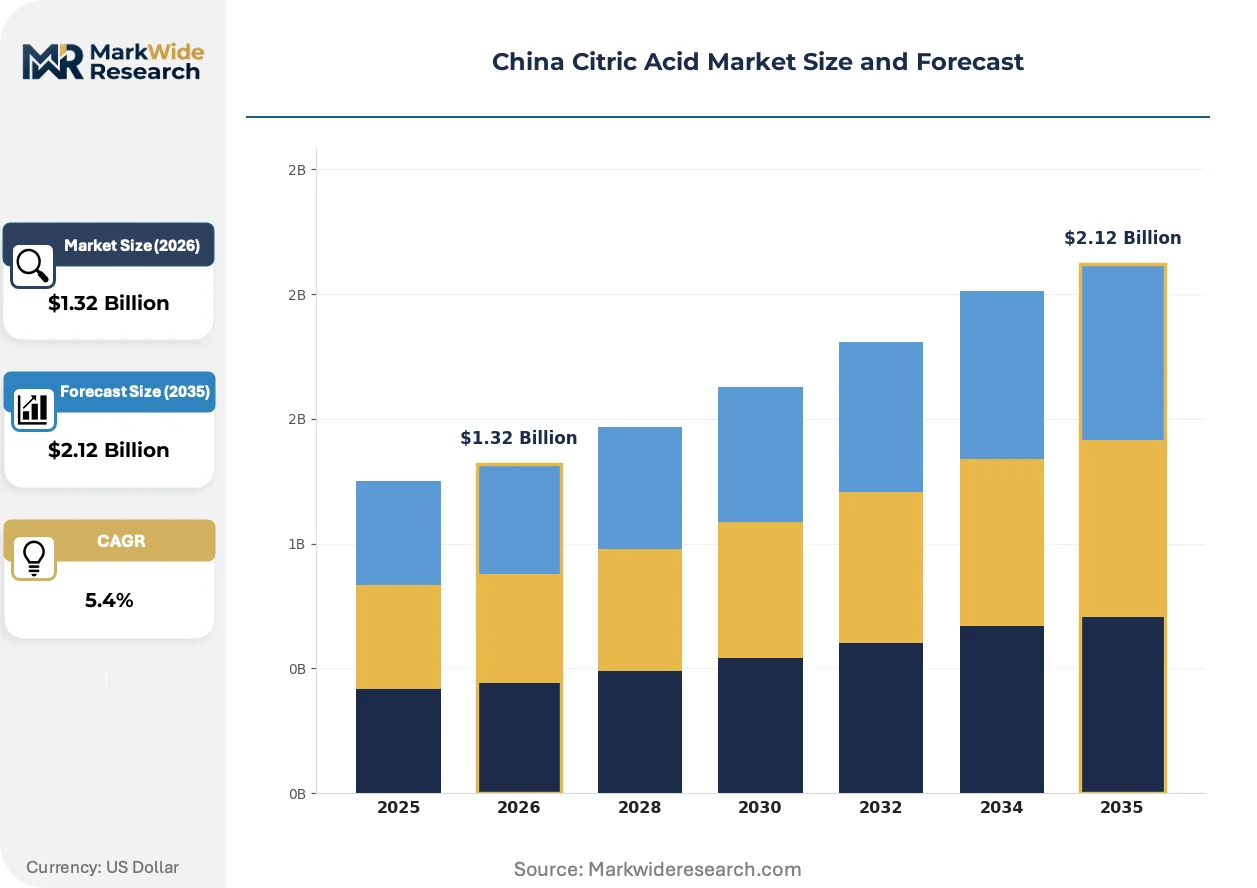
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Crystal, Anhydrous, Sodium Citrate Application: Food & Beverages, Pharmaceuticals, Personal Care, Cleaning Agents End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Household Products Packaging Type: Bulk Bags, Drums, pails, Bottles |
| Companies Covered | COFCO Biochemical, Foodchem International, Anhui BBCA Biochemical Co., Shandong Ensign Industry, Fondland Chemicals, RZBC Group, Huangshi Xinghua Biochemicals, Polifar Group, Weifang Ensign Industry Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Citric Acid Market Strategic Shifts & Innovations
Continuous fermentation systems and carbon-intensity tracking are displacing batch processes across Shandong manufacturing bases. These operational shifts are tightening quality variance while elevating energy compliance visibility.
Membrane filtration technology is electrifying downstream purification economics in citric acid recovery. Pharmaceutical contract manufacturers are adopting ceramic membrane systems to achieve 99.9 percent purity with reduced solvent consumption. This electrifying advance is compressing capital payback periods for anhydrous grade production lines.
MEE's evolving carbon intensity benchmarks are recalibrating provincial production licensing priorities. Fermentation facilities must now document Scope 2 emissions reductions to maintain operating permits. Shandong-based producers are responding by sourcing captive solar generation or purchasing green power purchase agreements.
Direct procurement relationships between food manufacturers and fermentation plants are displacing layered distributor networks. Large beverage conglomerates are negotiating volume commitments with Shandong Ensign and COFCO Biochemical for five-year supply security. This concentration is most visible in packaged juice and carbonated soft drink segments where formulation consistency demands batch-to-batch stability.
China Citric Acid Market Segmentation
Citric acid procurement patterns diverge sharply across purity grades, end-use specifications, and handling requirements. Buyers in Shandong Province and downstream sectors prioritize different performance attributes, creating distinct commercial segments with specialized supply relationships.
Product Type:
Formulation chemistry and moisture sensitivity separate buyers into four distinct procurement tiers with divergent price elasticities.
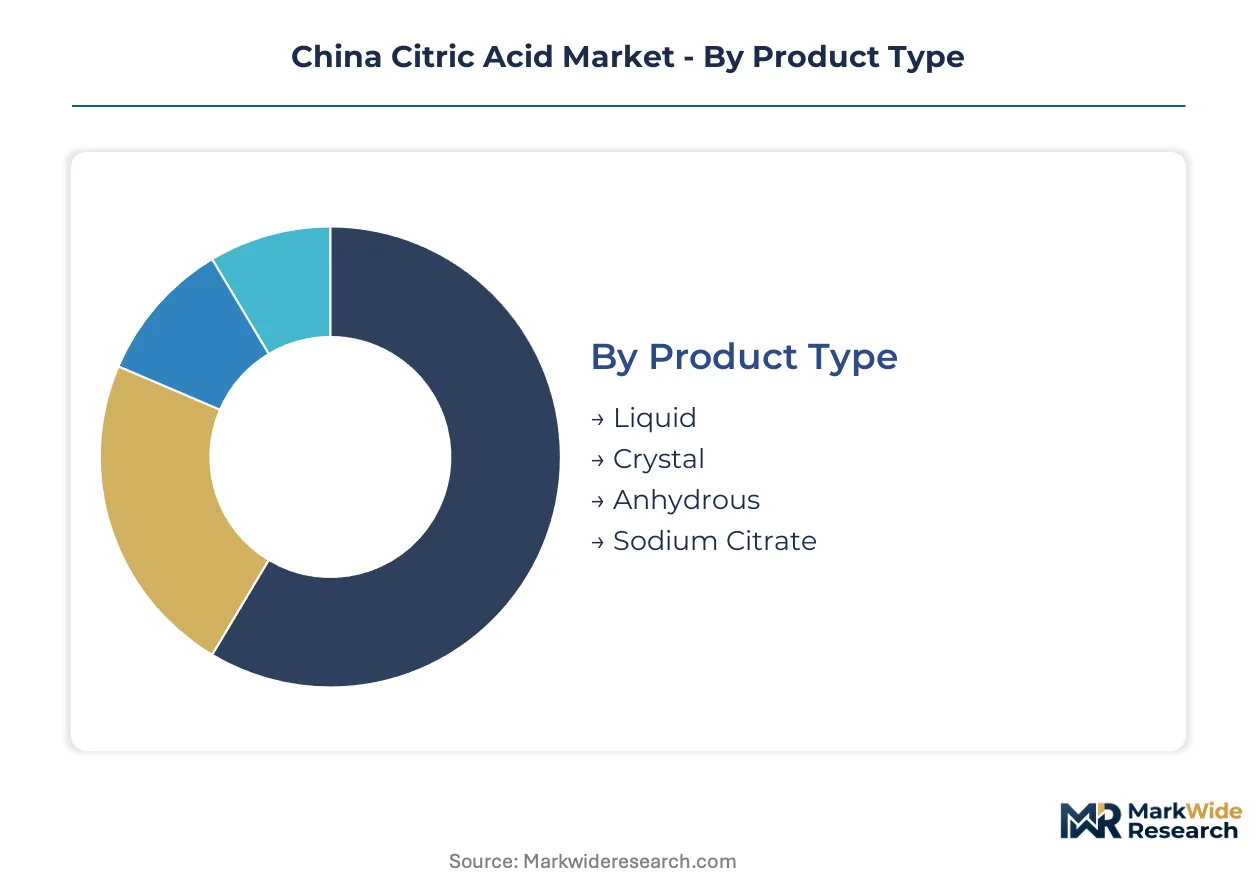
- Crystal:Monohydrate citric acid with controlled particle size distribution dominates food and beverage manufacturing for its handling stability and predictable dissolution kinetics. Juice processors and carbonated soft drink bottlers in Shandong Province specify crystal grades for batch-to-batch consistency in pH adjustment protocols.
- Anhydrous:Free-flowing powder with moisture content below 0.5% commands premium positioning in pharmaceutical formulations where hydroscopic instability degrades active ingredient shelf life. NMPA-certified producers capture this specialized demand through dedicated production lines with ceramic membrane purification.
- Liquid:Aqueous solutions at 50-60% concentration serve industrial cleaning compound manufacturers seeking direct pumpable feedstock without dissolution steps.
- Sodium Citrate:Trisodium salt functions as mild alkalinity buffer in personal care formulations for sensitive-skin applications.
Volume sits with Crystal; growth tilts toward Anhydrous.
Application:
Regulatory certification requirements and formulation complexity create four demand pools with distinct supplier qualification barriers.
- Food & Beverages:pH regulation and preservative functions in clean-label formulations drive procurement from SAMR-compliant facilities. Beverage conglomerates negotiate direct five-year supply commitments with Shandong-based fermentation plants.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications demand NMPA-validated purity above 99.9% with documented batch traceability.
- Personal Care:Chelating and pH buffering in cosmetic formulations favors sodium citrate grades for reduced irritation potential.
- Cleaning Agents:Industrial and household detergent manufacturers specify liquid citric acid for scale removal and biodegradable chelation.
Procurement concentrates in Food & Beverages; Pharmaceuticals expands most quickly.
End User:
Scale economies and technical service requirements fragment the buyer landscape into four categories with divergent contracting patterns.
- Food Manufacturers:Large-scale beverage and packaged food producers leverage volume commitments for price stability and dedicated production slots.
- Pharmaceutical Firms:Drug manufacturers require 18-24 month NMPA validation cycles that lock in supplier relationships and create switching costs.
- Cosmetic Companies:Mid-tier formulators prioritize sodium citrate availability and technical documentation for regulatory submission support.
- Household Products:Cleaning brand owners source liquid grades through distributors with just-in-time logistics capabilities.
Contracting runs thickest with Food Manufacturers; validation complexity peaks with Pharmaceutical Firms.
Packaging Type:
Handling infrastructure and consumption velocity determine container specifications across the value chain.
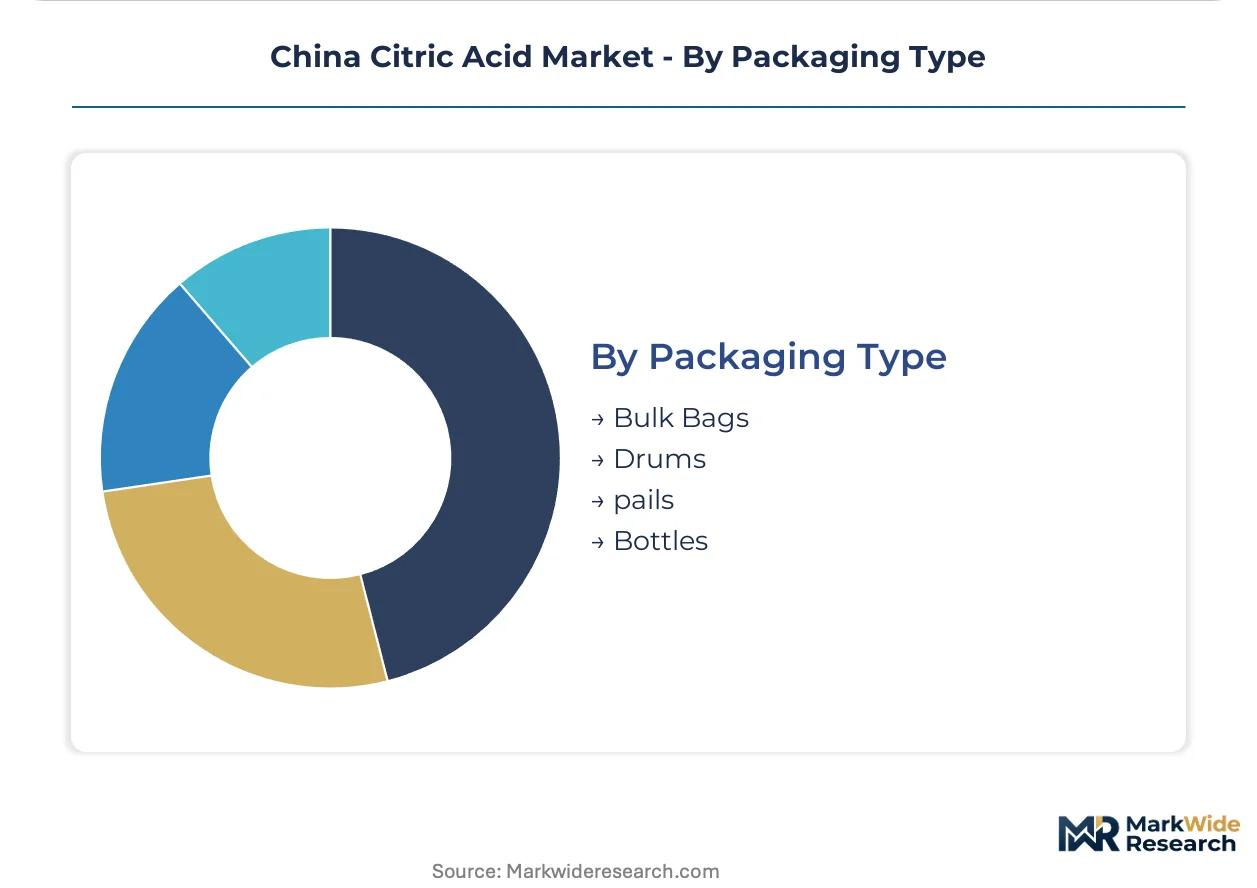
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume food and beverage plants with pneumatic conveying systems.
- Drums:200-liter steel or plastic drums bridge mid-scale pharmaceutical and cosmetic manufacturing with forklift-accessible warehousing.
- Pails:20-25 liter containers target specialty chemical distributors serving fragmented personal care compounders.
- Bottles:Retail and laboratory-scale packaging for analytical reagent and small-batch pharmaceutical applications.
Shipment weight concentrates in Bulk Bags; flexibility demands cluster around Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors China's citric acid production geography, hosting over 70 percent of national fermentation capacity within its industrial corridor. The province's corn belt proximity and shared wastewater infrastructure sustain cost advantages for bulk manufacturers. Provincial energy restrictions and MEE discharge limits are now recalibrating where new capacity can locate.
Shandong Province
Beverage bottlers and juice processors in Jinan and Qingdao drive crystal-grade procurement volumes for pH regulation protocols. SAMR's GB 1886.235 enforcement consolidates qualified supplier pools around fermentation plants with documented purity compliance. Weifang and Laiwu host concentrated manufacturing bases where producers share centralized effluent treatment facilities.
Jiangsu Province
Pharmaceutical contract manufacturers in Suzhou and Nanjing generate specialized demand for anhydrous grades with NMPA batch traceability. The province's stricter MEE carbon intensity benchmarks favor facilities with captive solar generation or verified green power purchase agreements. Taizhou's chemical industrial park attracts producers seeking proximity to drug formulation clusters.
Guangdong Province
Personal care formulators in Guangzhou and Shenzhen source sodium citrate grades for sensitive-skin cosmetic applications. Provincial dual carbon implementation timelines accelerate faster than northern provinces, pressuring fermentation assets to document Scope 2 reductions. The Pearl River Delta's logistics infrastructure supports just-in-time delivery to mid-tier cosmetic compounders.
Hebei Province
Cleaning agent manufacturers in Shijiazhuang and Baoding specify liquid citric acid for industrial scale removal formulations. The province's agricultural corn supply chains feed fermentation feedstock requirements for regional bulk producers. Tangshan industrial zones accommodate mid-scale facilities serving northern China's household detergent brands.
China Citric Acid Market Key Industry Players
The competitive structure tilts toward integrated agribusiness conglomerates with captive corn-processing infrastructure. Three distinct archetypes populate the supplier base: state-linked food processors with upstream grain control, specialized chemical manufacturers with pharmaceutical-grade certification, and regional fermentation specialists serving commodity bulk markets. Capacity expansion and NMPA validation investments constitute the dominant competitive moves as producers defend position against tightening environmental compliance costs.
Among Shandong-based integrated producers, COFCO Biochemical and Shandong Ensign Industry exemplify the agribusiness archetype with corn-to-citric acid value chain control. RZBC Group occupies a position within the specialized tier, differentiated by anhydrous grade capabilities for pharmaceutical contract manufacturing. These three anchors illustrate how certification depth and feedstock integration separate competitive tiers in a market reshaped by carbon intensity licensing.
| Leading Market Players |
|---|
| COFCO Biochemical |
| Foodchem International |
| Anhui BBCA Biochemical Co. |
| Shandong Ensign Industry |
| Fondland Chemicals |
| RZBC Group |
| Huangshi Xinghua Biochemicals |
| Polifar Group |
| Weifang Ensign Industry Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Clean-label procurement mandates from beverage conglomerates are forcing fermentation plants to absorb certification and carbon-compliance costs without full pass-through, compressing margins across Shandong's bulk manufacturing tier while amplifying price premiums for NMPA-validated pharmaceutical grades.
Pricing Analysis
Pharmaceutical-grade purity thresholds anchor value-based pricing at the top tier, with NMPA-certified anhydrous citric acid commanding substantial premiums over food-grade crystal material. Three-tier pricing structure across pharmaceutical, food-grade, and industrial liquid grades reflects certification depth and batch documentation burden. Cost compression in bulk crystal supply is intensifying because corn feedstock volatility and MEE wastewater compliance investments stack fixed cost layers onto commodity output. Beverage manufacturers exhibit highest price sensitivity due to formulation volume scale, while drug formulators accept premium positioning for validated excipient security.
Supply Chain Analysis
Bioprocess engineer scarcity in Weifang and Laiwu industrial corridors constrains fermentation plant expansion velocity, tethering capacity growth to specialized talent migration patterns. Manufacturing concentrates in Shandong Province, with secondary nodes in Jiangsu and Hebei. Corn supply chains from North China Plain agricultural belts, ceramic membrane purification systems, and NMPA validation documentation constitute critical input dependencies. Single-province concentration creates geographic risk exposure to Shandong's energy restriction protocols. Distribution runs through direct procurement relationships between fermentation plants and large food manufacturers, displacing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive corn-processing infrastructure and NMPA certification depth separate competitive tiers, with upstream grain control and downstream pharmaceutical validation emerging as the decisive levers for margin defense.
For Market Incumbents: Anticipate tightening MEE carbon intensity benchmarks by securing captive renewable energy supply or verified green power purchase agreements before provincial licensing gates harden. Deepen backward integration into corn wet-milling operations to buffer feedstock cost volatility that synthetic preservative substitution demand is amplifying. Defend pharmaceutical-grade positioning through dedicated ceramic membrane production lines with documented batch traceability. For New Entrants and Emerging Players: Capture sodium citrate supply gaps in Guangdong personal care manufacturing where mild alkalinity buffer demand outpaces qualified domestic capacity. Target Jiangsu pharmaceutical contract manufacturing clusters with anhydrous grade capabilities supported by accelerated NMPA validation timelines. Lead with technical documentation and regulatory submission support services rather than price competition. For Investors and Strategic Acquirers: The window for entry favors state-linked agribusiness conglomerates with existing grain infrastructure and capital reserves for multi-year certification investments. Long-term viability rests on carbon-compliant production licensing and pharmaceutical-grade validation depth rather than commodity scale alone. Watch Shandong provincial energy restriction enforcement severity as the inflection signal for capacity relocation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet-Milling | Captive feedstock supply buffers COFCO Biochemical and Shandong Ensign against agricultural commodity cycle volatility. |
| NMPA Pharmaceutical-Grade Certification | RZBC Group's validation investment creates 18-24 month switching costs that lock in drug manufacturer relationships. |
| Captive Renewable Energy Sourcing | Shandong-based producers with solar generation or green PPAs secure operating permits under tightening MEE carbon benchmarks. |
| Ceramic Membrane Purification Deployment | Electrified downstream recovery achieves 99.9% purity with reduced solvent consumption for anhydrous grade lines. |
| Direct Procurement Relationship Concentration | Beverage conglomerates negotiate five-year volume commitments that displace layered distributor networks in packaged juice segments. |
Research Approach
Independent corroboration across fermentation plant managers, pharmaceutical procurement leads, beverage industry formulation directors, and SAMR regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from customs trade data, SEC 10-K filings of listed agribusiness conglomerates, MEE discharge standard documentation, and NMPA pharmaceutical-grade certification records. Bottom-up capacity modeling triangulates against top-down demand aggregation across food, pharmaceutical, and industrial end-use segments.
Comparable historical periods anchored the projection framework, with CAGR derivation reflecting segmented growth differentials across purity grades and end-use applications. The analytical framework models crystal, anhydrous, liquid, and sodium citrate product tiers against food and beverage, pharmaceutical, personal care, and cleaning agent demand pools. Corn price volatility assumptions and provincial carbon intensity licensing trajectories constitute key forecast inputs alongside fermentation yield improvement curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Shandong energy restriction enforcement, NMPA validation timeline shifts, and corn belt climate variability. Assumptions reflect documented regulatory trajectories and disclosed capacity expansion plans. A small set of triggers—MEE benchmark acceleration, pharmaceutical import substitution policy shifts, and fermentation strain breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Engine Oil Additive Market
Additives
United Kingdom Feed Additives Market
Additives
Feedstuff Additives Market
Additives
Dishwashing Additives Market
Additives
Hexyl Acetate Market
Additives
Extrusion Aids Market
Additives
Packaging Coating Additives Market
Additives
Inhibited Propylene Glycol Market
Additives
Global Ester Gum Market
Additives
Micronized Powder Market
Additives
Antiblock Agents Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Sodium Potassium Tartrate Market
Additives
Global Feed Acidifiers Market
Additives
Global UV Stabilizers Market