
 Isodecyl Citrate Market | 2026-2036
Isodecyl Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Isodecyl Citrate Market Foresight
European specialty ester producers is restructuring capacity allocation toward higher-purity cosmetic grades as brand owners tighten ingredient specifications. BASF SE leverages its integrated citric acid backbone to secure backward integration into ester feedstocks. Eastman Chemical Company anchors North American supply through its Kingsport manufacturing complex, while Croda International Plc differentiates via lipid-technology expertise in personal-care applications.
Isodecyl citrate functions as a citric acid ester produced through Fischer esterification of citric acid with isodecanol, yielding a colorless liquid with low volatility and excellent solubility in organic solvents; manufacturers deploy it primarily as a skin-conditioning agent, plasticizer, and solvent carrier across cosmetic and industrial formulations. Cosmetic-grade supply commands premium positioning due to ECOCERT and COSMOS certification requirements, whereas industrial-grade volumes compete on price in lubricant and coating applications. Pharmaceutical-grade development remains nascent, constrained by USP monograph gaps and validation costs that limit producer participation.
FDA cosmetic ingredient oversight, REACH substance registration thresholds, and EU Cosmetics Regulation Annex III restrictions collectively elevate compliance costs for non-certified producers while creating market-access barriers for uncertified imports. ECHA substance evaluation under REACH drives reformulation timelines, compressing procurement cycles for European cosmetics manufacturers. Stakeholders must monitor evolving PFAS-analog scrutiny that could extend to long-chain citrate esters and recalibrate supply agreements before regulatory reclassification disrupts qualifying raw-material status.
Market Dynamics
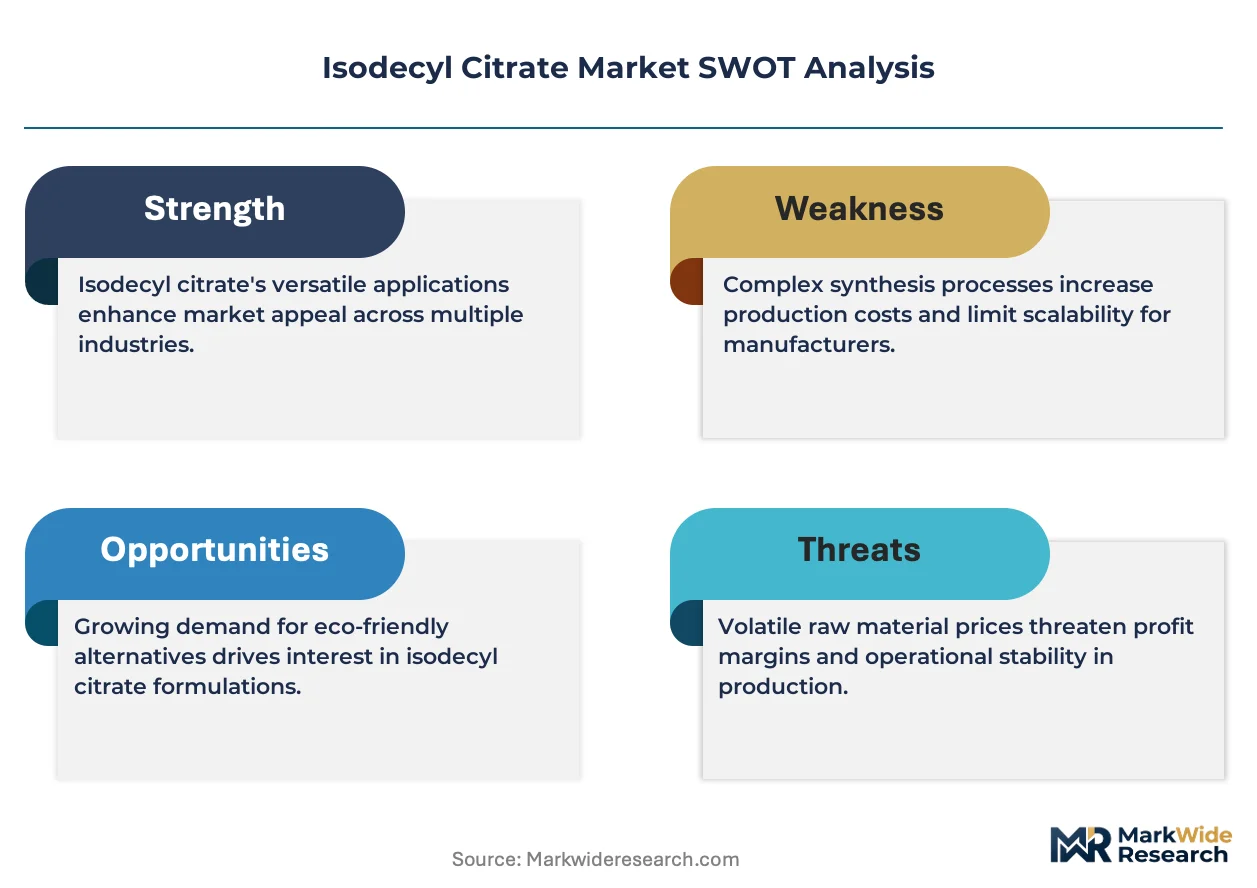
Phthalate displacement mandates are compressing formulation timelines across cosmetic and personal care supply chains, forcing compounders to validate citrate ester alternatives under accelerated certification protocols.
Growth Catalysts
- REACH Annex III restrictions:European cosmetics manufacturers face mandatory phthalate phase-outs, redirecting procurement toward ECOCERT-validated citrate esters for skin-conditioning applications.
- Isodecanol feedstock availability:Oxo-alcohol producers in Germany and the United States have stabilized supply chains, reducing raw material volatility for esterification operations.
- Clean beauty formulators:Indie cosmetic brands and contract manufacturers are specifying COSMOS-certified plasticizers, creating pull-through demand for cosmetic-grade supply.
Market Restraints
- Citric acid price volatility:Fermentation-based citric acid supply from Chinese producers fluctuates with corn feedstock costs and energy input spikes.
- Cosmetic-grade concentration:Certified production capacity clusters among three integrated specialty chemical producers, creating procurement bottlenecks during reformulation surges.
- USP monograph gaps:Absence of validated pharmaceutical-grade standards limits expansion into topical drug delivery applications.
Strategic Opportunities
- India personal care manufacturing:CDSCO cosmetic ingredient notifications are aligning with EU standards, opening formulation export channels for BIS-compliant citrate esters.
- Biodegradable lubricant formulations:Industrial fluid compounders are testing citrate esters as base oils for environmentally acceptable hydraulic fluids.
- EU Green Deal chemical sustainability targets:National implementation programs in France and Germany are subsidizing bio-based plasticizer transitions in coating applications.
Industry Challenges
- ECHA substance evaluation timelines:REACH compliance documentation for new citrate ester variants requires 18-24 month pre-registration periods, compressing product launch windows.
- Analytical method standardization:Cosmetic manufacturers lack harmonized test protocols for citrate ester purity verification, forcing redundant third-party validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isodecyl Citrate Market |
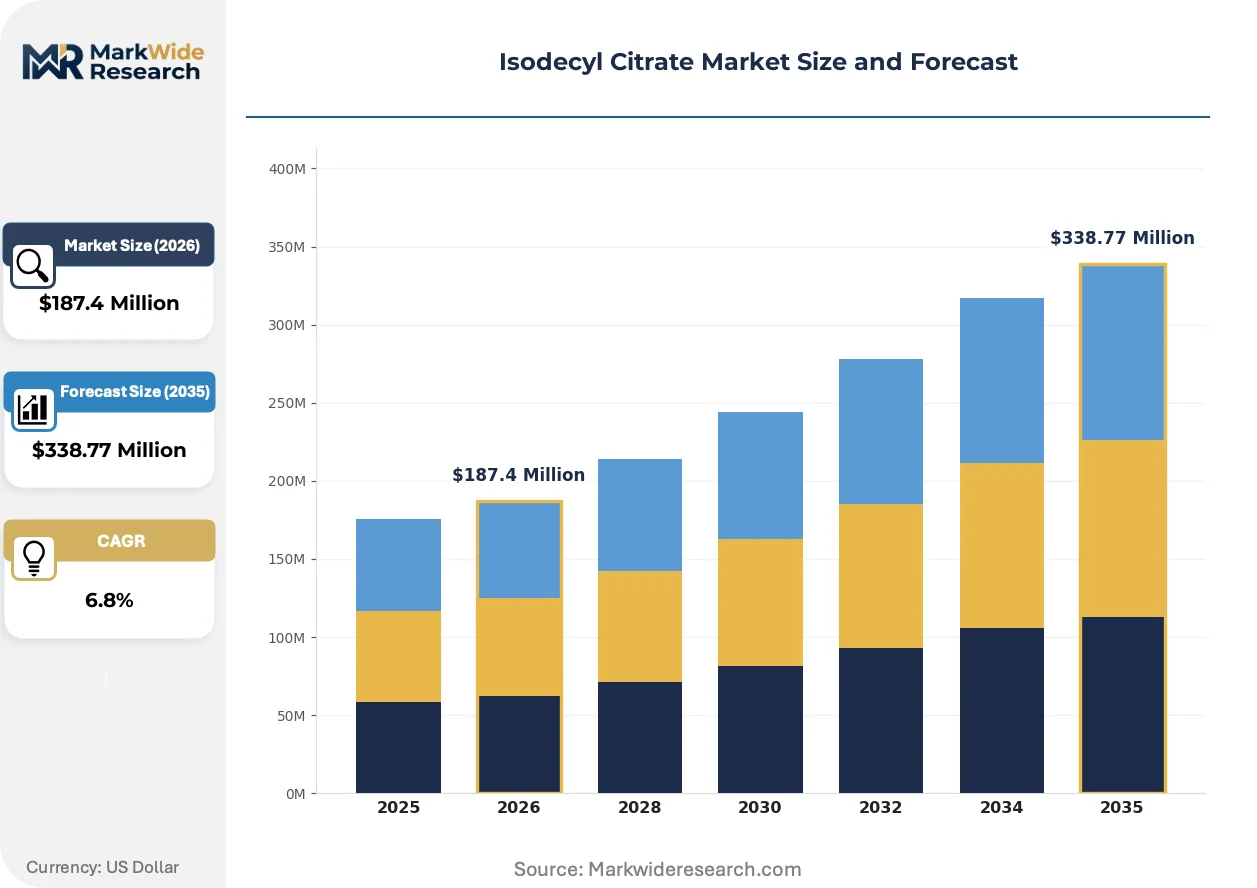
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Personal Care, Home Care, Food Preservation, Lubricants End User: Cosmetics Manufacturers, Food Processors, Chemical Producers, Pharmaceutical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | BASF SE, Eastman Chemical Company, Dow Chemical Company, Evonik Industries AG, Croda International Plc, Clariant AG, Lonza Group Ltd, Univar Inc., Vertellus Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isodecyl Citrate Market Shifts & Advancements
Process intensification and regulatory alignment are converging to reshape how citrate esters move from commodity chemical status toward specification-grade positioning in personal care supply chains.
Continuous flow esterification reactor technology is unifying batch-to-batch consistency for cosmetic-grade production. German and Swiss specialty chemical producers have retrofitted pilot-scale flow chemistry modules, cutting residence times from hours to minutes. This process architecture is compressing validation cycles for ECOCERT submissions and reducing thermal degradation byproducts that previously complicated purity certification.
EU Cosmetics Regulation microplastic restrictions are forcing reformulation of rinse-off products containing synthetic film-forming agents. ECHA guidance documents published under REACH substance evaluation protocols have designated specific citrate esters as acceptable alternatives for hair-conditioning applications. French and German formulators are fastest to adapt, with Italian contract manufacturers trailing by 12-18 months due to slower ANSM notification processing.
Specification-driven purchasing is consolidating buyer power among multinational cosmetic houses. Procurement teams at L'Oréal, Beiersdorf, and Unilever have implemented unified raw material qualification platforms that bypass traditional distributor relationships for direct producer contracting. This channel compression is most visible in Germany and the United States, where specialty ester producers have established dedicated technical service teams for account-specific formulation support.
Isodecyl Citrate Market Segmentation
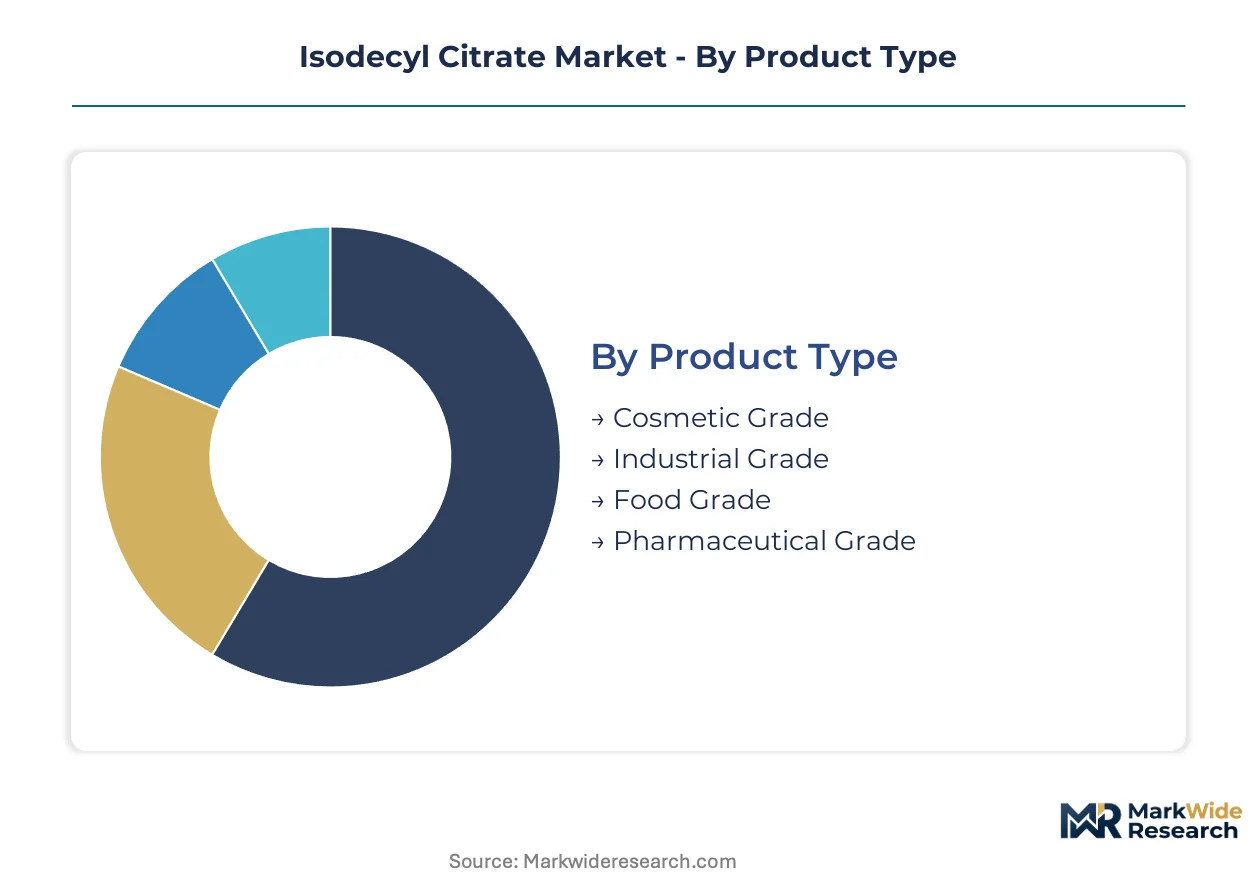
Isodecyl citrate procurement patterns diverge sharply between specification-critical cosmetic applications and price-sensitive industrial uses. Grade certification requirements and end-use regulatory exposure determine margin structures and supplier relationships across each segment cluster.
Product Type:
Integration depth varies from standalone cosmetic formulations requiring ECOCERT validation to embedded industrial systems where citrate esters function as additive components within larger chemical matrices.
- Cosmetic Grade:Purity thresholds demand sub-100ppm residual acid content and full COSMOS compliance for skin-conditioning claims. German and French formulators drive procurement concentration as REACH Annex III phthalate restrictions force rapid reformulation cycles.
- Industrial Grade:Technical specifications prioritize color stability and viscosity control over certification documentation. Lubricant compounders in the United States absorb volume through direct producer contracts, bypassing distributor markups.
- Food Grade:FSSAI and FDA indirect food contact approvals limit qualified supplier pools to fermentation-citric-acid integrated producers.
- Pharmaceutical Grade:USP monograph gaps constrain commercialization; topical drug delivery developers await validated analytical methods before specification adoption.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Cosmetic Grade.
Application:
Cost-tier stratification separates premium personal-care positioning from commodity lubricant and preservation uses where citrate esters compete on functional equivalence.
- Personal Care:Skin-conditioning formulations leverage isodecyl citrate as a phthalate replacement in emollient systems. Clean beauty brand specifications in Germany and the United States are compressing supplier qualification timelines.
- Lubricants:Biodegradable hydraulic fluid formulations test citrate ester base oils against synthetic polyol esters. EU Green Deal subsidies in France and Germany are accelerating field trials.
- Home Care:Rinse-off product reformulations respond to EU microplastic restrictions; citrate esters replace synthetic film-formers in hair-conditioning applications.
- Food Preservation:Indirect additive applications in packaging coatings require migration testing under FDA and EFSA frameworks.
Revenue concentration sits with Personal Care; Lubricants are climbing the fastest on sustainability-driven substitution.
End User:
Customer-type fragmentation creates divergent procurement behaviors between multinational cosmetic houses and fragmented chemical processors.
- Cosmetics Manufacturers:L'Oréal, Beiersdorf, and Unilever procurement teams have implemented unified qualification platforms that bypass traditional distribution. Direct producer contracting compresses channel margins.
- Chemical Producers:Industrial compounders prioritize feedstock security through multi-year supply agreements with integrated citric acid producers.
- Food Processors:Packaging material suppliers specify food-grade citrate esters for indirect contact applications under tightening migration limits.
- Pharmaceutical Companies:Topical formulation developers await USP monograph finalization before committing to validation batches.
Procurement scale concentrates among Cosmetics Manufacturers; Pharmaceutical Companies show the steepest expansion trajectory contingent on regulatory clarity.
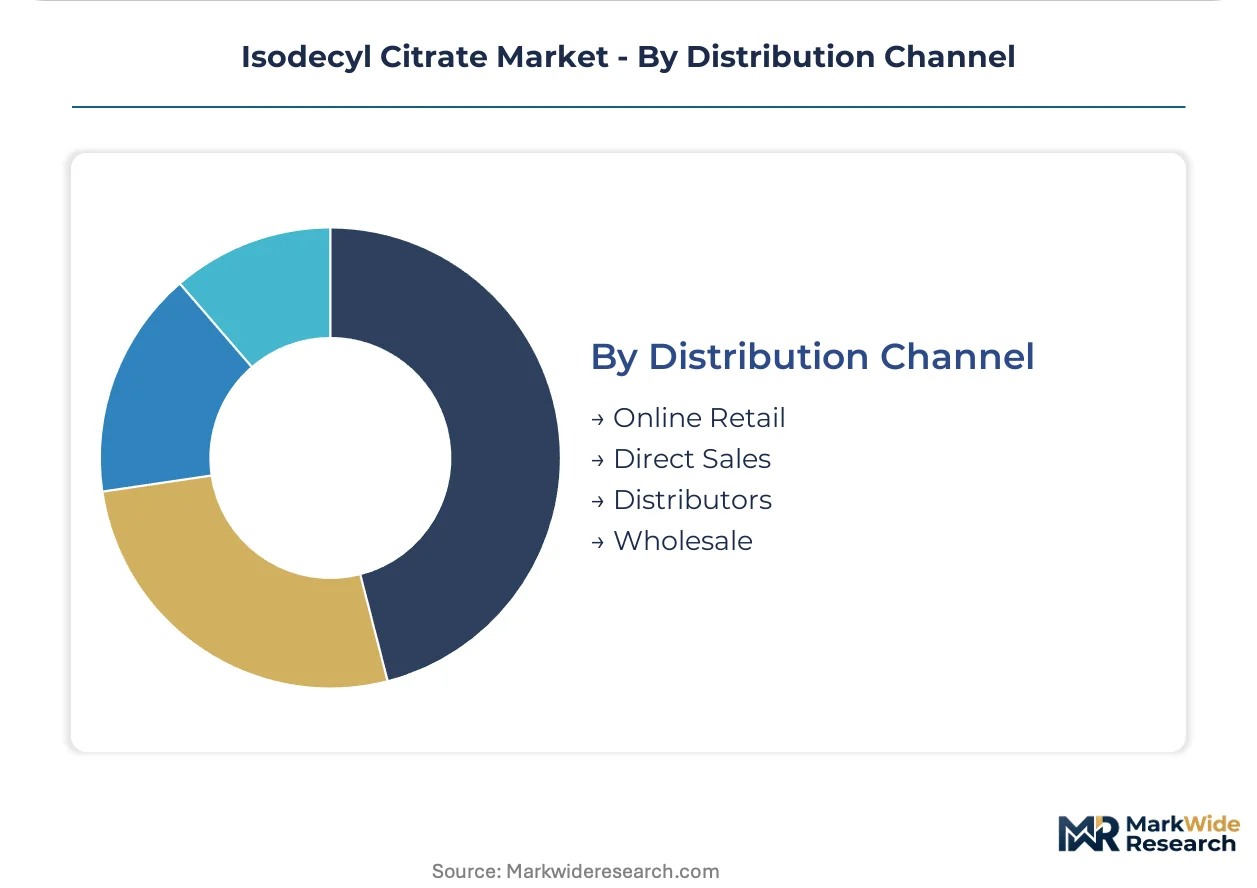
Distribution Channel:
Supply concentration patterns favor direct relationships for high-volume cosmetic and industrial accounts, with distributor networks serving fragmented regional processors.
- Direct Sales:Account-specific technical service teams at BASF SE, Eastman Chemical Company, and Croda International Plc support formulation development for multinational cosmetic houses.
- Distributors:Regional chemical distributors maintain inventory positions for mid-tier lubricant compounders and home care formulators lacking volume scale for direct contracts.
- Wholesale:Bulk industrial-grade volumes move through established chemical wholesale networks serving coating and adhesive manufacturers.
- Online Retail:Small-scale cosmetic formulators and indie brands source certified grades through specialized chemical marketplaces with documentation transparency.
Transaction value concentrates in Direct Sales; Online Retail is gaining share fastest among emerging clean beauty formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isodecanol feedstock availability clusters in Germany and the United States, with Chinese citric acid fermentation capacity anchoring Asia-Pacific supply chains. Procurement patterns concentrate where specialty ester infrastructure overlaps with REACH-compliant cosmetic formulation hubs.
Germany
Personal care formulators in Hamburg and Düsseldorf drive cosmetic-grade procurement as REACH Annex III phthalate restrictions compress reformulation timelines. ECHA substance evaluation protocols under REACH redirect supply agreements toward ECOCERT-validated producers. The Cologne-Leverkusen chemical corridor hosts backward-integrated citric acid-to-ester operations serving Beiersdorf and other multinational houses.
United States
Clean beauty brands and contract manufacturers in New Jersey and California specify COSMOS-certified plasticizers, creating pull-through demand for validated supply. FDA cosmetic ingredient oversight tightens documentation requirements for skin-conditioning claims. Eastman Chemical Company's Kingsport manufacturing complex anchors North American production capacity for downstream blending operations.
China
Fermentation-based citric acid producers in Shandong and Jiangsu provinces supply raw material for regional esterification operations, though price volatility tracks corn feedstock costs and energy input spikes. GB standards for cosmetic ingredients are converging with EU technical specifications. The Yangtze River Delta clusters personal care contract manufacturers testing citrate ester alternatives for export formulations.
France
L'Oréal procurement teams in Clichy implement unified raw material qualification platforms that bypass traditional distributor relationships. ANSM notification processing for cosmetic ingredients operates slower than German counterparts, creating 12-18 month adaptation lags. The Lyon-Grenoble chemical corridor hosts specialty ester producers retrofitting continuous flow reactor modules for ECOCERT validation.
India
CDSCO cosmetic ingredient notifications are aligning with EU standards, opening formulation export channels for BIS-compliant citrate esters. Maharashtra and Gujarat-based contract manufacturers absorb industrial-grade volumes for lubricant and coating applications. Mumbai-Pune chemical processors are qualifying cosmetic-grade supply for indie personal care brands targeting Middle East export markets.
Isodecyl Citrate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent certification niches and regional distribution partnerships. Supply concentrates among three integrated specialty chemical producers with captive citric acid feedstock, creating procurement bottlenecks during reformulation surges. Strategic archetypes include backward-integrated fermentation specialists, lipid-technology formulators, and regional distributors with inventory positions for mid-tier compounders. Dominant competitive moves center on direct technical service teams for multinational accounts and continuous flow reactor retrofits for batch consistency.
Within the integrated-producer tier, BASF SE and Eastman Chemical Company exemplify archetypes anchored to citric acid backbone control and regional manufacturing complexes respectively. Croda International Plc occupies a position representing lipid-technology expertise in personal-care applications. These three entities sit within the cosmetic-grade concentration that commands premium positioning against industrial-grade price competition.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Dow Chemical Company |
| Evonik Industries AG |
| Croda International Plc |
| Clariant AG |
| Lonza Group Ltd |
| Univar Inc. |
| Vertellus Holdings LLC |
| Others |
Supply & Pricing Matrix
Continuous flow esterification reactor retrofits in German and Swiss specialty chemical plants compress production costs while simultaneously tightening supply concentration among ECOCERT-validated producers. This process intensification technology reduces thermal degradation byproducts that previously complicated purity certification, creating cost advantages that only backward-integrated fermentation specialists can fully exploit.
Pricing Analysis
Technical service bundling separates cosmetic-grade quotations from stripped industrial-grade pricing, with formulation support and ECOCERT documentation included in premium tiers. Three-tier pricing structure across cosmetic, industrial, and food-grade levels tracks certification burden and purity thresholds, with cosmetic buyers showing lowest price sensitivity due to phthalate displacement urgency. Cost compression in industrial grades intensifies as lubricant compounders negotiate direct contracts bypassing distributor markups. Price differentiation hinges on COSMOS validation status and captive citric acid supply, with uncertified imports facing margin erosion from REACH compliance documentation requirements.
Supply Chain Analysis
Citric acid feedstock rests on fermentation operations in China, Germany, and the United States, with Shandong and Jiangsu province producers anchoring raw material volatility to corn input costs. Isodecanol oxo-alcohol supply draws from German and US petrochemical complexes, creating dual-dependency exposure for esterification operations. Single-source vulnerability concentrates in cosmetic-grade capacity clustered among three integrated producers with captive citric acid. Distribution runs through direct technical service teams for multinational cosmetic houses, with regional distributors serving mid-tier lubricant compounders lacking volume scale for producer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cosmetic-grade production capacity bottlenecks prop pricing power among ECOCERT-validated suppliers, constraining procurement options during REACH-driven reformulation surges.
For Market Incumbents: Deploy continuous flow reactor retrofits to compress batch validation cycles and defend ECOCERT positioning against emerging lipid-technology specialists. Expand captive citric acid capacity in the Cologne-Leverkusen corridor to secure feedstock advantage during Chinese fermentation price spikes. Reinforce direct technical service teams for L'Oréal and Beiersdorf accounts to lock out distributor intermediaries. For New Entrants and Emerging Players: Indie clean beauty brands in California and New Jersey represent the most penetrable buyer archetype, with COSMOS certification gaps creating procurement friction for established suppliers. Target BIS-compliant supply for Maharashtra-based contract manufacturers exporting to Middle East markets, where CDSCO-EU alignment opens formulation channels. Pursue online marketplace distribution with full documentation transparency to bypass incumbent technical service requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated specialty chemical houses seeking lipid-technology capabilities or regional manufacturing footprints. Long-term viability favors producers with backward-integrated fermentation assets and validated continuous flow production. Watch ECHA substance evaluation timelines for citrate ester variants as the inflection signal that compresses product launch windows and favors incumbent scale.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Retrofit | ECOCERT validation cycles compress from batch inconsistencies at German pilot-scale modules. |
| Backward Integration into Citric Acid | BASF SE's fermentation backbone secures feedstock advantage against Chinese price volatility. |
| COSMOS Certification Investment | Clean beauty brand specifications in California create pull-through demand for validated supply. |
| Direct Technical Service Teams | L'Oréal procurement platforms bypass distributors for account-specific formulation support. |
| Long-term Supply Agreements | Industrial compounders lock multi-year contracts with integrated producers for feedstock security. |
Research Methodology
Independent corroboration across plant managers at esterification facilities, procurement leads at downstream cosmetic OEMs, and distribution channel partners underwrites the qualitative findings. Technical R&D directors at specialty chemical producers provided primary input on continuous flow reactor validation protocols. Secondary validation drew from customs and trade data, Cefic specialty ester reports, and SEC 10-K filings from integrated chemical producers. Bottom-up volume modeling triangulated against top-down market sizing from fermentation capacity and oxo-alcohol supply estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers by grade tier, end-use industry, and regional production hub. CAGRs derive from segment-level growth rates applied to base-year estimates, with cross-checks against historical citric acid price elasticity and REACH reformulation timeline data. Forecast inputs incorporate CDSCO notification alignment progress in India and EU Green Deal subsidy implementation in France and Germany.
Revisions become necessary when ECHA substance evaluation timelines accelerate, USP monograph finalization unlocks pharmaceutical-grade adoption, or PFAS-analog scrutiny extends to long-chain citrate esters. Forecasts reflect documented assumptions on certification penetration rates and feedstock price normalization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Squalane Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Ethylene Bis Stearamide Market