
 Global UV Stabilizers Market | 2026-2036
Global UV Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV Stabilizers Market Foresight
The gap between specification-grade and commodity UV stabilizer supply is broadening as automotive and construction end-users impose tighter QUV-accelerated weathering protocols while bulk packaging buyers prioritize unit cost. BASF SE leverages its Ludwigshafen integrated base to sustain captive supply of hindered amine intermediates for European coating producers. SONGWON Industrial anchors its position through dedicated liquid HALS production lines serving Korean and Southeast Asian fiber manufacturers. Clariant AG differentiates via color-stabilizer bundled formulations that occupy premium slots in automotive exterior part specifications.
UV stabilizers are chemical additives, predominantly hindered amine light stabilizers and benzotriazole derivatives, that interrupt photo-oxidative degradation pathways in polymers by scavenging free radicals or absorbing ultraviolet radiation in the 290–400 nm range; manufacturers compound them at 0.1–3.0 weight percent loadings to extend service life of exposed plastics and coatings. Hindered amine light stabilizers command the largest volume share due to their regenerative stabilization mechanism and broad polymer compatibility, though triazine derivatives are gaining fastest in polycarbonate and PET applications where low-volatility requirements dominate. Masterbatch form factors capture disproportionate margin pools as compounders bundle stabilizers with pigments and processing aids to lock in multi-year supply contracts with polymer manufacturers.
REACH in Europe and EPA chemical evaluation frameworks in the United States are jointly restricting certain benzotriazole chemistries, forcing reformulation investments and opening market access for alternative quinoline and triazine platforms. China's GB standards and MIIT industry guidelines are tightening voluntary weathering specifications for building materials and automotive plastics, indirectly elevating stabilizer performance thresholds for domestic and export-qualified production. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate which additive chemistries will retain multi-region approval status and justify sustained R&D allocation.
Market Dynamics
The automotive and construction sectors are tightening QUV-accelerated weathering protocols, forcing a bifurcation between specification-grade and commodity UV stabilizer supply tiers as masterbatch producers invest in captive compounding capacity.
Growth Catalysts
- REACH benzotriazole restrictions:ECHA's phased limitations on legacy benzotriazole chemistries are redirecting European formulation investments toward triazine derivatives and novel quinoline platforms.
- China's Yangtze River Delta cluster:Integrated masterbatch producers in this polymer hub are building captive stabilizer compounding capacity to serve domestic packaging film and fiber export markets.
- Automotive exterior specifications:OEM weathering-resistance mandates are intensifying procurement of high-performance HALS combinations across polymer manufacturers.
Market Restraints
- Hindered amine intermediate concentration:Captive supply of key HALS building blocks concentrates in Ludwigshafen and Ulsan, creating single-source vulnerability for European and Korean coating producers.
- Polycarbonate volatility requirements:Low-volatility thresholds in optical-grade polycarbonate and PET applications restrict benzotriazole deployment despite mature cost structures.
- Regulatory divergence friction:Divergent approval timelines across EPA, REACH, and China's GB standards force redundant safety testing and fragment R&D allocation.
Strategic Opportunities
- India's building materials upgrade:BIS voluntary weathering specifications for construction plastics remain underpenetrated versus China's GB enforcement, opening formulation partnerships with domestic compounders.
- Color-stabilizer bundling:Pigment-masterbatch convergence creates premium slots for stabilizer suppliers who integrate weathering protection with color consistency in automotive exterior specifications.
- Japan's METI circularity guidelines:Recycled-content mandates for automotive plastics create demand for stabilizer systems compatible with post-consumer polymer streams.
Industry Challenges
- Formulation chemist scarcity:Expertise in quinoline and triazine stabilization mechanisms remains concentrated among legacy benzotriazole specialists, constraining reformulation velocity.
- Multi-jurisdiction certification timelines:Simultaneous EPA, ECHA, and NMPA notification requirements extend product launch cycles for novel stabilizer platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV Stabilizers Market |
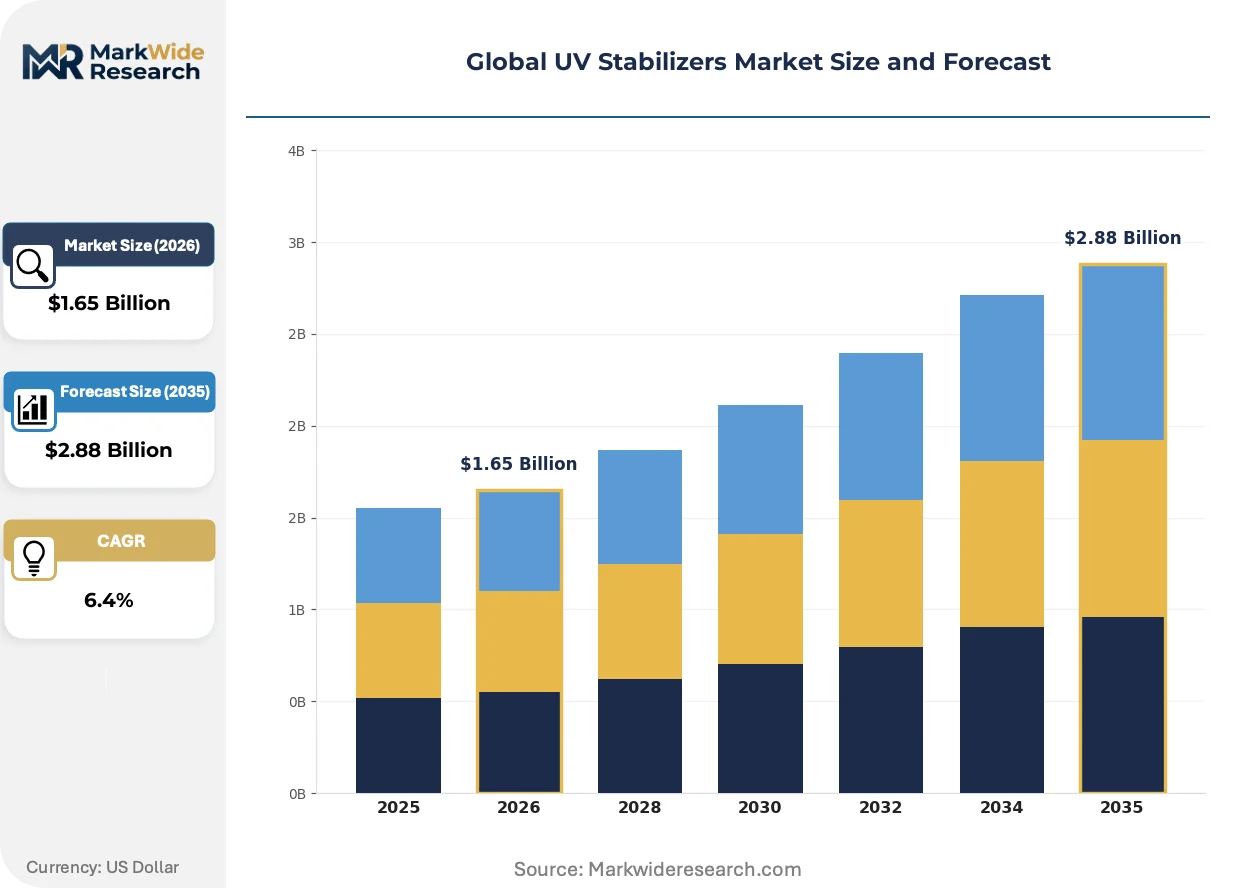
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hindered Amine Light Stabilizers, Benzotriazoles, Quinoline Derivatives, HALS Combination, Triazine Derivatives Application: Packaging Films, Coatings, Fibers, Adhesives, Automotive Exterior Parts End User Industry: Polymer Manufacturers, Coating Producers, Textile Manufacturers, Plastic Fabricators, Building Materials Suppliers Form: Powder, Liquid, Granules, Masterbatch, Emulsion |
| Companies Covered | BASF SE, Clariant AG, SONGWON Industrial Co., Ltd., ADEKA Corporation, Syensqo SA/NV, Rianlon Corporation, SABO S.p.A., Everlight Chemical Industrial Corporation, SI Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV Stabilizers Market Shifts & Advancements
Formulation automation and regulatory chemistry substitution are compressing development cycles while procurement consolidation among polymer manufacturers reshapes supplier relationships.
Reactive extrusion compounding is automating the integration of liquid HALS into high-shear polymer matrices with precision dosing previously requiring batch processing. Korean and Southeast Asian fiber manufacturers are adopting these systems at pilot scale. This automation is compressing minimum order quantities and enabling just-in-time stabilizer delivery against volatile polymer demand.
REACH's restriction roadmap for benzotriazole UV absorbers is forcing coating producers to validate triazine alternatives across accelerated weathering protocols. The industrial consequence is a two-year reformulation window before 2027 sunset dates. European automotive exterior coating specifications are responding with provisional approvals for quinoline-based systems pending full QUV data.
Automotive OEMs are consolidating approved supplier lists for exterior plastic components, compressing multi-year masterbatch contracts into single-source agreements with performance guarantees. Tier-1 polymer processors are absorbing formulation risk previously borne by compounders. This concentration is most visible in Germany's KBA-certified automotive supply chain, where three masterbatch producers now serve twelve OEM platforms.
Global UV Stabilizers Market Segmentation
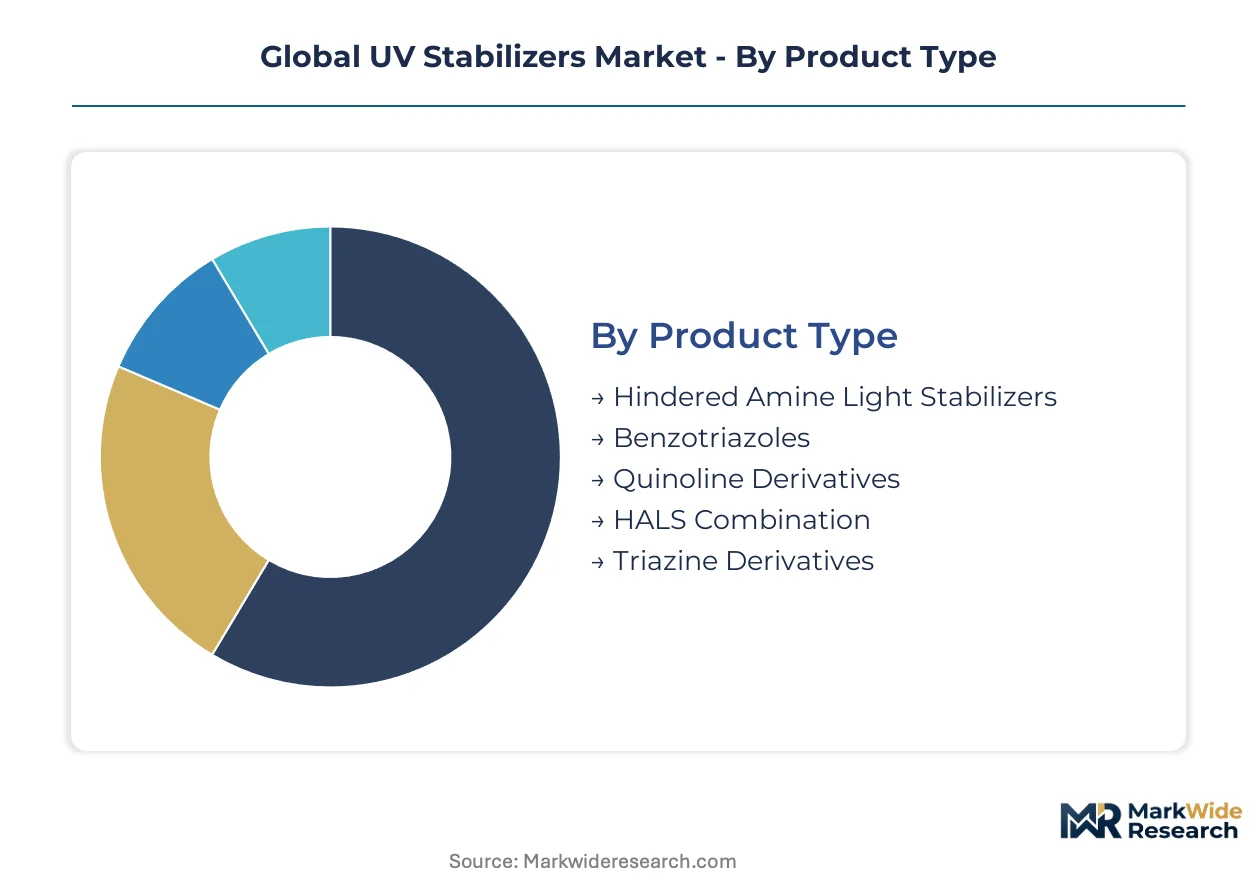
UV stabilizer procurement patterns diverge sharply across product chemistries and form factors, with capital requirements for reactive extrusion equipment and regulatory compliance driving supplier selection. Masterbatch bundling and captive compounding investments are reshaping margin capture across polymer value chains.
Product Type:
Capital intensity concentrates in multi-step synthesis routes for hindered amine intermediates and novel quinoline platforms, where integrated producers sustain cost advantages through backward control over nitroxyl radical precursors.
- Hindered Amine Light Stabilizers:Regenerative radical scavenging mechanisms enable extended service intervals in polyolefin applications. Polymer manufacturers across Germany's KBA-certified automotive supply chain specify HALS combinations for exterior trim components facing stringent QUV protocols.
- Benzotriazoles:Mature 2-hydroxyphenyl chemistries face phased REACH restrictions across European coating applications. Reformulation investments are redirecting toward triazine alternatives as ECHA sunset dates approach.
- Quinoline Derivatives:Novel platforms gaining provisional automotive approvals pending full weathering data.
- HALS Combination:Synergistic blends commanding premium slots in specification-grade masterbatches.
- Triazine Derivatives:Low-volatility absorption profiles suit polycarbonate and PET optical applications where benzotriazole outgassing is prohibited.
Hindered Amine Light Stabilizers absorb the bulk of installed capacity; Triazine Derivatives is expanding most quickly.
Application:
Customer procurement scale separates specification-driven automotive programs from volume-oriented packaging contracts, with tier-1 polymer processors absorbing formulation risk previously borne by compounders.
- Packaging Films:High-volume flexible packaging demands cost-optimized stabilizer loadings at 0.1–0.5 weight percent. China's Yangtze River Delta masterbatch producers are building captive compounding capacity to serve export-qualified film operations.
- Automotive Exterior Parts:OEM weathering mandates enforce multi-year performance guarantees on bumper fascias and mirror housings. German and Korean coating producers face tightened QUV-accelerated protocols requiring validated stabilizer systems.
- Coatings:Architectural and industrial formulations prioritize color stability alongside substrate protection.
- Fibers:Korean and Southeast Asian manufacturers pilot reactive extrusion for liquid HALS integration.
- Adhesives:Pressure-sensitive and structural applications require low-migration stabilizer grades.
Packaging Films commands the greatest volume throughput; Automotive Exterior Parts claims the steepest expansion trajectory.
End User Industry:
Formulation expertise scarcity constrains reformulation velocity for coating producers pivoting from legacy benzotriazole systems, while polymer manufacturers consolidate approved supplier lists.
- Polymer Manufacturers:Integrated compounders specify stabilizer masterbatches with bundled pigments and processing aids. Tier-1 processors in Germany now serve consolidated OEM platforms through single-source agreements.
- Coating Producers:European automotive exterior specialists face compressed two-year reformulation windows. ECHA restriction roadmaps are forcing validation of quinoline and triazine alternatives across accelerated weathering protocols.
- Textile Manufacturers:Fiber spinners in Korea adopt automated liquid HALS dosing systems.
- Plastic Fabricators:Injection molders and extruders prioritize just-in-time stabilizer delivery.
- Building Materials Suppliers:China's GB standards enforcement elevates weathering thresholds for construction plastics.
Polymer Manufacturers represent the dominant demand source; Coating Producers are gaining share fastest.
Form:
Margin capture concentrates in masterbatch and liquid delivery systems, where precision dosing automation enables differentiated service models against commodity powder supply.
- Masterbatch:Concentrated pellets bundle stabilizers with colorants and processing aids, locking multi-year supply contracts. Clariant AG and integrated Yangtze River Delta compounders occupy premium specification slots through bundled formulations.
- Liquid:Pumpable HALS systems enable continuous reactive extrusion compounding. Korean fiber manufacturers deploy precision dosing at pilot scale to compress minimum order quantities.
- Powder:Lowest-cost delivery for high-volume packaging film applications.
- Granules:Intermediate handling convenience for mid-scale compounders.
- Emulsion:Water-based dispersions for coating and adhesive formulations.
Masterbatch captures disproportionate margin pools; Liquid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta polymer cluster anchors procurement concentration for UV stabilizers, with integrated masterbatch producers building captive compounding capacity to serve export-qualified packaging film and fiber operations.
China
Packaging film manufacturers in the Yangtze River Delta are absorbing formulation risk through vertical integration into stabilizer compounding. MIIT industry guidelines tighten voluntary weathering specifications for automotive plastics. Shanghai and Jiangsu province house the dominant masterbatch production bases serving domestic and export fiber markets.
Germany
Automotive OEMs in the KBA-certified supply chain enforce multi-year performance guarantees on exterior plastic components. ECHA's REACH restrictions on legacy benzotriazole chemistries force coating producers toward triazine and quinoline alternatives. Ludwigshafen sustains captive supply of hindered amine intermediates for European coating producers.
United States
EPA chemical evaluation frameworks restrict certain benzotriazole chemistries, opening market access for alternative stabilizer platforms. Tier-1 polymer processors consolidate approved supplier lists for exterior automotive components. Michigan and Ohio automotive corridors drive specification-grade HALS procurement.
South Korea
Fiber manufacturers in the Busan-Ulsan industrial zone pilot reactive extrusion systems for liquid HALS integration. Domestic producers maintain dedicated production lines serving Southeast Asian export markets. Ulsan anchors regional supply of hindered amine building blocks.
India
BIS voluntary weathering specifications for construction plastics remain underpenetrated versus China's GB enforcement. Building materials suppliers in Maharashtra and Gujarat seek formulation partnerships with domestic compounders. Mumbai-Pune industrial corridor shows emerging procurement of specification-grade stabilizers.
Global UV Stabilizers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification-grade versus bulk packaging applications, with masterbatch bundling and captive compounding investments reshaping margin capture. The vendor base separates into three archetypes: integrated chemical majors with backward control over hindered amine intermediates, specialty additive houses focused on color-stabilizer bundled formulations, and regional compounders serving fiber and film export markets. Dominant competitive moves include reactive extrusion automation investments and multi-jurisdiction regulatory certification programs.
Among European integrated majors, BASF SE and Clariant AG exemplify divergent strategic positioning. BASF SE occupies the upstream chemical tier through captive supply of hindered amine intermediates. Clariant AG anchors the specialty formulation tier via bundled color-stabilizer systems. SONGWON Industrial represents the Asia-Pacific regional specialist archetype with dedicated liquid HALS production lines.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| SONGWON Industrial Co., Ltd. |
| ADEKA Corporation |
| Syensqo SA/NV |
| Rianlon Corporation |
| SABO S.p.A. |
| Everlight Chemical Industrial Corporation |
| SI Group, Inc. |
| Others |
Supply & Pricing Matrix
Reactive extrusion automation is compressing production economics while concentrating margin capture among integrated compounders with precision dosing capabilities. This manufacturing transition simultaneously elevates capital barriers for commodity powder suppliers and rewards liquid HALS producers with just-in-time service premiums.
Pricing Analysis
Performance-guarantee contracting anchors value-based pricing for specification-grade masterbatches serving automotive exterior programs. Price differentiation separates REACH-validated triazine systems from legacy benzotriazole formulations facing sunset restrictions. Cost compression in commodity powder grades intensifies as China's Yangtze River Delta captive compounders absorb downstream margin. Packaging film manufacturers exhibit highest price sensitivity; German OEM-certified suppliers demonstrate lowest elasticity due to single-source contract lock-in.
Supply Chain Analysis
Freight cost differentials favor regional liquid HALS production over intercontinental powder shipments to fiber and film compounders. Supply concentrates in Germany, South Korea, and China, with Ludwigshafen and Ulsan anchoring hindered amine intermediate output. Nitroxyl radical precursors and 2,2,6,6-tetramethylpiperidine derivatives constitute critical input dependencies. Single-source vulnerability in HALS building blocks creates structural risk for European coating producers. Distribution runs through masterbatch compounders bundling stabilizers with pigments and processing aids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UV stabilizers sector is executing a chemistry-transition phase as REACH-mandated benzotriazole substitution accelerates reformulation toward triazine and quinoline platforms. This technology displacement compresses the competitive window for legacy specialists while opening premium positioning for validated alternative suppliers.
For Market Incumbents: Extend backward integration into nitroxyl radical precursors to secure captive HALS intermediate supply against Ludwigshafen and Ulsan concentration risk. Deepen reactive extrusion automation investments to compress minimum order quantities and defend margin position against Yangtze River Delta captive compounders. Prioritize multi-jurisdiction regulatory certification across EPA, ECHA, and MIIT frameworks to sustain cross-border formulation approval.
For New Entrants and Emerging Players: Digital-channel routes through specialty chemical marketplaces enable direct procurement relationships with mid-scale polymer processors bypassing consolidated masterbatch tiers. Target India's underpenetrated building materials segment where BIS voluntary weathering specifications lag China's GB enforcement. Pursue formulation partnerships with Maharashtra and Gujarat construction plastics suppliers as the most penetrable entry vector.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty additive houses with bundled color-stabilizer capabilities and validated quinoline platforms. Long-term viability hinges on regulatory chemistry substitution completion and automotive OEM supplier list consolidation velocity. Monitor ECHA benzotriazole sunset implementation timelines as the primary inflection signal for alternative platform adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Extrusion Automation | Korean fiber manufacturers deploy precision liquid HALS dosing to compress order minimums. |
| Backward Integration into Intermediates | BASF SE's Ludwigshafen base sustains captive nitroxyl radical precursor supply. |
| Multi-Jurisdiction Regulatory Certification | Simultaneous EPA, ECHA, and MIIT approval extends product commercialization runway. |
| Color-Stabilizer Bundling | Clariant AG occupies premium automotive specification slots through integrated formulations. |
| Captive Compounding Capacity | Yangtze River Delta masterbatch producers absorb stabilizer margin through vertical integration. |
Research Methodology
Independent corroboration across primary interviews with polymer manufacturer procurement leads, coating producer R&D directors, and masterbatch compounder technical specialists underwrites the qualitative findings. Secondary validation draws from ECHA restriction roadmaps, MIIT industry guideline publications, and customs trade data for hindered amine and benzotriazole chemistries. Bottom-up volume modeling across product type, application, and form factor segments triangulates against top-down market sizing from integrated chemical major disclosures.
Comparable-period anchoring to historical automotive production cycles and packaging film export volumes establishes the forecast baseline across the projection horizon. Segmentation dimensions modeled include chemistry platform, polymer substrate compatibility, delivery form, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating OEM weathering specification tightening and REACH substitution timelines. Industry-specific inputs capture polycarbonate optical-grade volatility thresholds and fiber spinning line automation adoption curves.
The model holds under steady regulatory implementation schedules; deviation in ECHA sunset enforcement velocity or MIIT mandatory versus voluntary specification transitions would shift chemistry platform adoption trajectories. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Automotive Coolant Additives Market
Additives
Sodium Benzoate Market
Additives
Encapsulated Citric Acid Market
Additives
High Performing Matting Agents Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Polysorbate-80 Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Cetane Improver Additives Market
Additives
Asia Pacific Silage Additives Market
Additives
Europe Citric Acid Market
Additives
Americas Coating Additives Market
Additives
Sodium Potassium Tartrate Market
Additives
Low Melt Inclusions Market
Additives
Acrylamide Reducing Ingredients Market