
 Global Transfer Membrane Market | 2026-2036
Global Transfer Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transfer Membrane Market Foresight
Contract research organizations are unwinding purchasing patterns away from academic laboratories as the dominant buyer archetype in transfer membrane procurement. Thermo Fisher Scientific leverages its vertical integration across western blotting reagents and consumables to sustain pricing power in high-volume diagnostic segments. Bio-Rad Laboratories anchors its competitive position through specialized PVDF membrane formulations optimized for low-background protein detection workflows.
Transfer membranes are porous sheets manufactured from nitrocellulose, polyvinylidene difluoride, or nylon polymers with defined pore sizes typically ranging from 0.1 to 0.45 micrometers, engineered to immobilize biomolecules during electrophoretic transfer for subsequent immunodetection or nucleic acid hybridization. The PVDF membrane segment leads value contribution due to superior mechanical strength and chemical compatibility with stripping protocols, while the western blotting technology dimension dominates volume as the foundational protein analysis method in pharmaceutical testing and biomedical research applications.
The FDA regulates transfer membranes as components of in vitro diagnostic devices when bundled with clinical assay kits, while REACH and RoHS frameworks in Europe restrict hazardous substances in nitrocellulose manufacturing supply chains. ISO 13485 quality management standards shape supplier qualification criteria for diagnostic center procurement committees across multiple geographies. Stakeholders must monitor evolving EMA guidance on companion diagnostic validation requirements, as these protocols directly influence membrane performance specifications demanded by pharmaceutical testing laboratories.
Market Dynamics
Contract research organizations are displacing academic laboratories as the dominant procurement archetype, compressing order cycles and forcing membrane suppliers to reconfigure volume-discount structures around multi-site service contracts rather than institutional purchase orders.
Growth Catalysts
- Companion diagnostic expansion:EMA guidance on companion diagnostic validation protocols is elevating membrane performance specifications across pharmaceutical testing laboratories in Germany and France.
- PVDF mechanical superiority:Superior chemical compatibility with stripping protocols is accelerating replacement of nitrocellulose in high-throughput protein detection workflows.
- REACH compliance investments:EU Green Deal funding streams are underwriting solvent-recovery infrastructure upgrades at nitrocellulose production facilities in Belgium and the Netherlands.
Market Restraints
- Nitrocellulose feedstock volatility:Cotton linter supply concentration in South Asian agricultural markets exposes membrane manufacturers to raw material price swings.
- Specialized polymer production:PVDF resin synthesis requires capital-intensive fluoropolymer infrastructure controlled by a limited supplier base in China and Japan.
- Western blot protocol lock-in:Established SOP documentation at diagnostic centers creates switching costs that delay membrane format transitions.
Strategic Opportunities
- Single-use bioprocessing convergence:Tangential flow filtration membrane demand from mRNA vaccine manufacturing is creating cross-selling pathways for protein transfer membrane suppliers.
- India research infrastructure:CDSCO streamlined IVD registration pathways are attracting CRO facility investments in Hyderabad and Bengaluru clusters.
- Automated western blot platforms:Integration with walk-away protein analysis systems is opening specification partnerships with liquid-handling instrument manufacturers.
Industry Challenges
- ISO 13485 certification timelines:Diagnostic center procurement committees are extending supplier qualification periods to 18-24 months for membrane component vendors.
- Cross-functional technical sales:Membrane suppliers must field simultaneous expertise in polymer chemistry, electrophoretic transfer protocols, and immunoassay validation to secure CRO contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transfer Membrane Market |
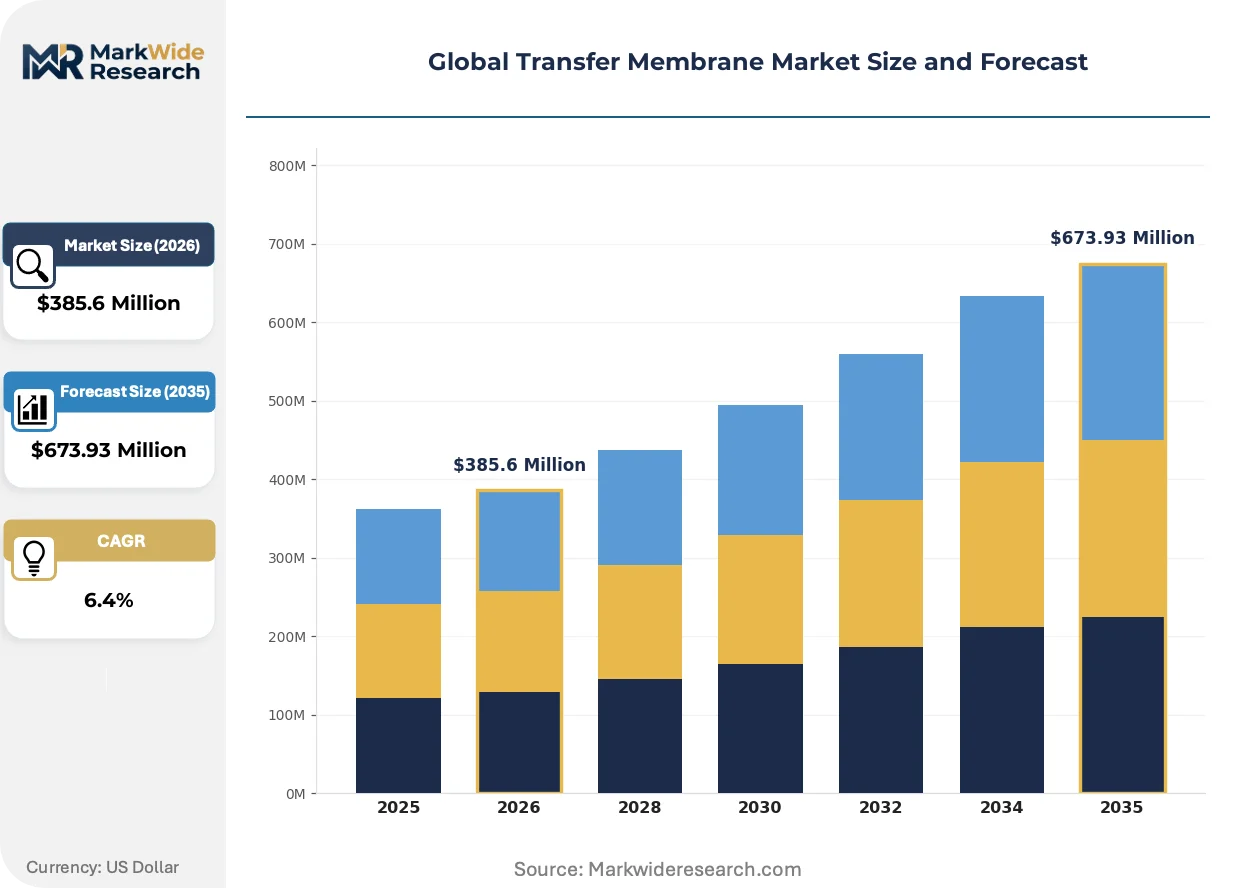
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrocellulose Membrane, PVDF Membrane, Nylon Membrane, Mixed Cellulose Ester Membrane Technology: Western Blotting, Protein Detection, DNA Transfer, RNA Analysis, Immunodetection Application: Biomedical Research, Academic Laboratories, Pharmaceutical Testing, Molecular Diagnostics, Food Safety End User: Biotechnology Firms, Diagnostic Centers, Research Institutions, Contract Research Organizations, Quality Control Units |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, GE Healthcare, Merck KGaA, PerkinElmer, Abcam PLC, Agilent Technologies, Macherey-Nagel, Azure Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transfer Membrane Market Shifts & Advancements
Membrane technology is fragmenting into application-optimized formulations while regulatory pressure and procurement rationalization compress supplier margins and consolidate buying power among large service organizations.
Pre-cast gel and membrane cassette systems are bifurcating the protein transfer workflow market into high-throughput diagnostic users and low-volume research laboratories. Large CROs and pharmaceutical QC departments are standardizing on integrated cassette formats to reduce technician variability and compress assay turnaround times. This format shift is compressing demand for standalone membrane sheets while expanding specification control by platform manufacturers over consumable sourcing decisions.
REACH authorization requirements for nitrocellulose manufacturing solvents are forcing European membrane producers to retrofit solvent-recovery systems or relocate finishing operations. ECHA enforcement timelines are tightening through 2027, with German and French production facilities facing the steepest compliance investments. Suppliers are responding by qualifying alternative polymer substrates and accelerating PVDF formulation development to reduce nitrocellulose dependency.
Consolidated procurement contracts are displacing institutional purchasing autonomy across multi-site CRO networks. Centralized sourcing departments in United States and German service organizations are unbundling membrane purchases from broader western blot reagent bundles to capture volume leverage. This concentration is most visible in Boston and San Diego biotech clusters, where three CROs now account for a disproportionate share of high-sensitivity PVDF membrane orders.
Global Transfer Membrane Market Segmentation
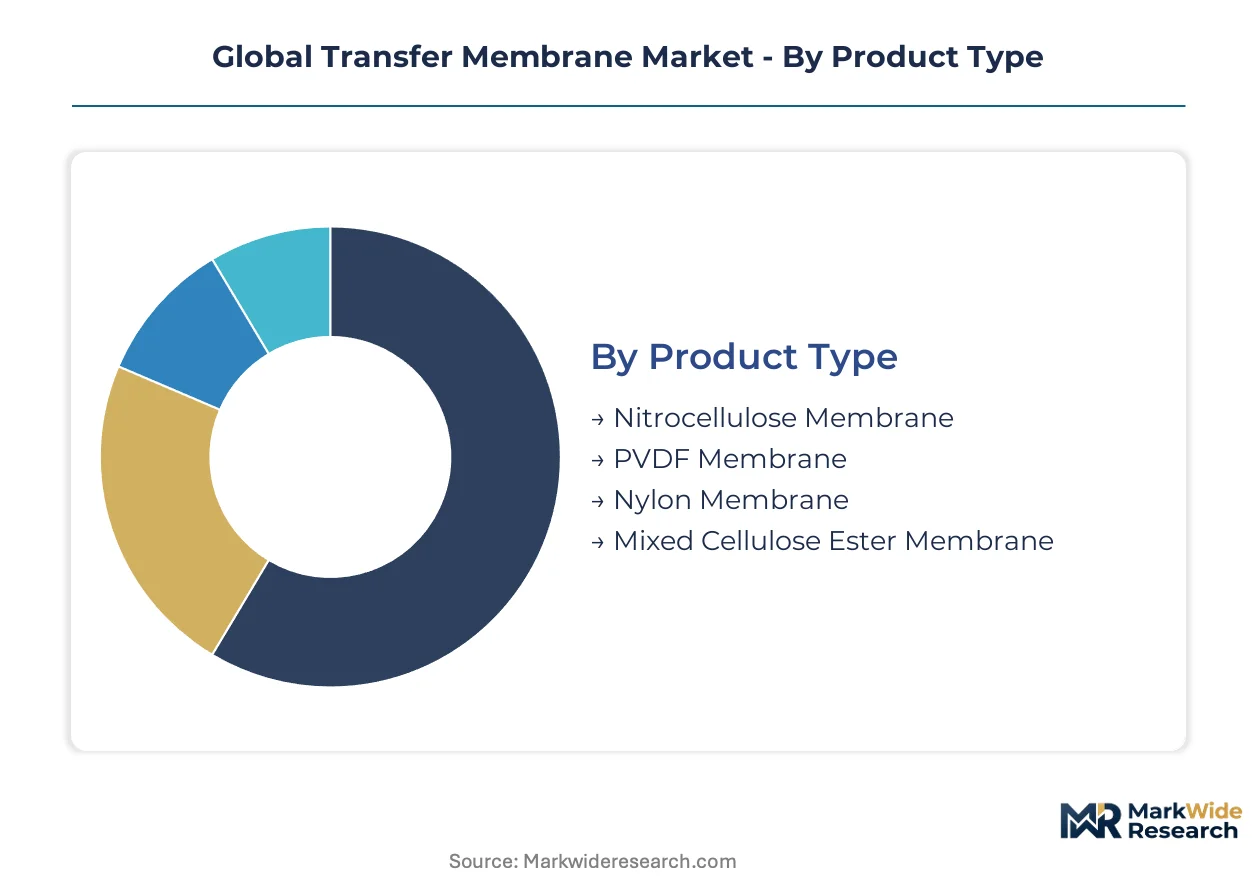
Transfer membrane procurement patterns diverge sharply across end-use contexts, with pharmaceutical testing laboratories demanding validated PVDF formulations while academic users prioritize cost-efficient nitrocellulose sheets. Segment boundaries are blurring as automated western blot platforms force standardization across customer types previously served by distinct product lines.
Product Type:
PVDF membrane production concentrates in fluoropolymer manufacturing clusters across Japan and China, while nitrocellulose finishing operations remain anchored in Belgian and Dutch solvent-recovery infrastructure.
- PVDF Membrane:Fluoropolymer sheets engineered for superior mechanical strength and chemical compatibility with stripping protocols. Pharmaceutical testing laboratories in Germany and the United States specify PVDF for high-sensitivity protein detection workflows requiring membrane reuse.
- Nitrocellulose Membrane:Cotton linter-derived porous substrates with established protein-binding affinity. REACH solvent authorization timelines are compressing European manufacturing capacity and accelerating sourcing shifts toward South Asian feedstock suppliers.
- Nylon Membrane:Polyamide substrates optimized for nucleic acid hybridization applications with enhanced durability.
- Mixed Cellulose Ester Membrane:Blended polymer formulations serving specialized environmental monitoring and air sampling protocols.
PVDF Membrane holds the largest share; momentum sits with Nitrocellulose Membrane as REACH compliance costs reshape European supply geography.
Technology:
Western blotting protocols dominate volume procurement through diagnostic center networks, while nucleic acid transfer methods concentrate in research institution purchasing.
- Western Blotting:Electrophoretic protein transfer to membrane substrates for subsequent antibody-based detection. Contract research organizations in Boston and San Diego biotech clusters are standardizing on pre-cast gel and membrane cassette systems to compress assay turnaround times.
- Protein Detection:Membrane-based immunoassay workflows for quantitative and qualitative protein analysis. Academic laboratories across India and China are expanding adoption as CDSCO and NMPA streamline diagnostic validation pathways.
- DNA Transfer:Southern blotting and related nucleic acid immobilization techniques for genomic analysis.
- RNA Analysis:Northern blotting protocols for transcript detection and expression profiling.
- Immunodetection:Antigen-antibody binding assays on membrane substrates for serological and clinical applications.
Western Blotting commands the greatest procurement volume; Protein Detection is climbing the fastest as companion diagnostic expansion elevates membrane performance specifications.
Application:
Pharmaceutical testing applications concentrate purchasing power through centralized CRO procurement committees, while biomedical research maintains fragmented institutional buying patterns.
- Pharmaceutical Testing:Quality control and validation workflows for biologic drug development and release. EMA companion diagnostic guidance is tightening membrane performance specifications across German and French testing facilities.
- Biomedical Research:Fundamental protein and nucleic acid analysis in university and institute settings. Research infrastructure investments in Hyderabad and Bengaluru are expanding membrane consumption in Indian metropolitan clusters.
- Academic Laboratories:Educational and exploratory research applications with price-sensitive procurement profiles.
- Molecular Diagnostics:Clinical assay development and point-of-care test validation on membrane substrates.
- Food Safety:Pathogen detection and allergen screening protocols for regulatory compliance testing.
Pharmaceutical Testing captures the highest value per unit; Biomedical Research is gaining share fastest as public research funding expands in Asia-Pacific markets.
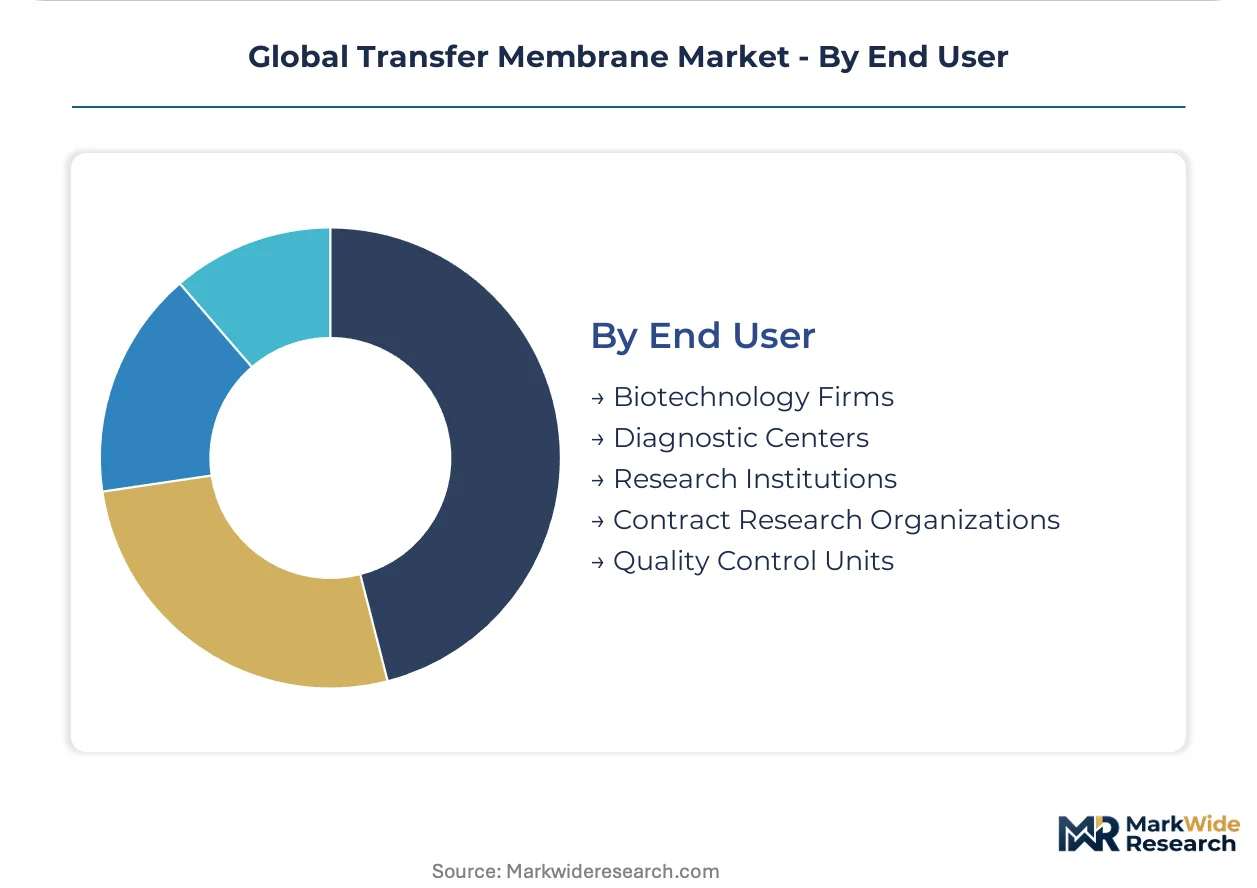
End User:
Contract research organizations are consolidating procurement autonomy across multi-site networks, displacing the fragmented purchasing patterns of research institutions.
- Contract Research Organizations:Multi-site service providers managing outsourced pharmaceutical development and testing. Three CROs in United States biotechnology corridors now account for disproportionate shares of high-sensitivity PVDF membrane orders.
- Diagnostic Centers:Clinical laboratories performing routine and specialized diagnostic testing. ISO 13485 certification requirements are extending supplier qualification periods to 18-24 months for membrane component vendors serving these facilities.
- Biotechnology Firms:Product development and process development groups in biologic drug companies.
- Research Institutions:Universities and government laboratories with decentralized purchasing authority.
- Quality Control Units:In-house testing departments within pharmaceutical and food manufacturing operations.
Contract Research Organizations hold the largest share; Diagnostic Centers show the steepest expansion trajectory as companion diagnostic validation protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's solvent-handling infrastructure underwrites European nitrocellulose membrane finishing capacity, while Shanghai Yangshan Port anchors fluoropolymer resin imports feeding Chinese PVDF production lines.
United States
Boston and San Diego biotech clusters concentrate contract research organization procurement of high-sensitivity PVDF membranes. FDA oversight of in vitro diagnostic device components shapes membrane performance specifications for pharmaceutical testing laboratories. Three CRO networks in these corridors now account for disproportionate shares of premium membrane orders.
Germany
Rhine-Ruhr industrial infrastructure supports specialized PVDF membrane formulation facilities serving pharmaceutical quality control workflows. EMA companion diagnostic guidance tightens validation protocols across German testing laboratories. REACH authorization timelines for nitrocellulose solvents are compressing manufacturing capacity in Belgian and Dutch border regions.
China
Yangtze River Delta fluoropolymer manufacturing clusters dominate PVDF resin synthesis for membrane substrates. NMPA streamlined diagnostic registration pathways accelerate membrane consumption in biologic drug development. Shanghai and Suzhou host the largest concentrations of western blot consumables production outside Japan.
India
Hyderabad and Bengaluru research infrastructure investments expand membrane procurement by contract research organizations. CDSCO streamlined IVD registration attracts CRO facility clustering in these metropolitan areas. Public research funding expansion drives biomedical research membrane consumption across Indian academic institutions.
Japan
Chubu region fluoropolymer production infrastructure supplies high-grade PVDF resins to membrane manufacturers. METI industrial policy supports advanced materials R&D for protein detection workflows. Osaka-based chemical conglomerates maintain captive supply relationships with diagnostic platform developers.
Global Transfer Membrane Market Competitive Landscape
Concentration sits with diversified life science conglomerates controlling integrated western blotting workflows. Thermo Fisher Scientific leverages backward integration across reagents and consumables to sustain pricing power in high-volume diagnostic segments. Specialized membrane formulators compete on application-specific performance optimization. Capacity expansion in Chinese fluoropolymer infrastructure and strategic partnerships with automated platform developers represent dominant competitive vectors.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify contrasting strategic positions. Thermo Fisher Scientific occupies a scale-driven archetype through upstream control over reagent and consumable portfolios. Bio-Rad Laboratories represents the specialized formulation archetype, anchoring competitive positioning through membrane substrates optimized for low-background protein detection. GE Healthcare and Merck KGaA sit within the European diversified chemicals tier, leveraging ISO 13485 certification infrastructure to serve diagnostic center procurement committees.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| GE Healthcare |
| Merck KGaA |
| PerkinElmer |
| Abcam PLC |
| Agilent Technologies |
| Macherey-Nagel |
| Azure Biosystems |
| Others |
Supply & Pricing Matrix
PVDF resin displacement of nitrocellulose feedstock simultaneously relocates production gravity toward Yangtze River Delta fluoropolymer clusters and compresses pricing power at European solvent-recovery facilities facing REACH compliance cost absorption.
Pricing Analysis
Three-tier pricing structure across premium PVDF formulations, standard nitrocellulose grades, and economy nylon substrates governs procurement negotiations. Price differentiation hinges on ISO 13485 certification tier and volume scale within multi-site CRO contracts. Cost compression in standard-grade nitrocellulose intensifies because REACH solvent authorization timelines extend supplier qualification periods. Academic laboratories exhibit highest price sensitivity, while pharmaceutical testing laboratories in Germany and the United States prioritize performance specifications over unit economics.
Supply Chain Analysis
China and Japan anchor fluoropolymer resin synthesis for PVDF membrane substrates, while Belgium and the Netherlands host nitrocellulose finishing operations tethered to Port of Rotterdam solvent-handling infrastructure. Raw material dependencies center on cotton linter supply from South Asian agricultural markets, fluoropolymer precursor chemicals, and specialized pore-forming agents. Single-source vulnerability concentrates in PVDF resin production controlled by limited Japanese and Chinese chemical conglomerates. Distribution runs through diagnostic platform manufacturers and direct procurement committees at consolidated CRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through CRO procurement consolidation, as three multi-site service organizations now capture disproportionate shares of high-sensitivity PVDF membrane orders in Boston and San Diego biotechnology corridors.
For Market Incumbents: Consolidate backward integration into fluoropolymer resin supply to defend margin position against Chinese capacity expansion. Secure ISO 13485 certification infrastructure early to compress supplier qualification timelines that diagnostic center procurement committees are extending to 18-24 months. Lock in multi-year offtake agreements with Yangtze River Delta resin producers before feedstock competition intensifies.
For New Entrants and Emerging Players: Differentiate on application-optimized membrane formulations for automated western blot platforms that large CROs are standardizing across multi-site networks. Target Indian CRO facility investments in Hyderabad and Bengaluru clusters where CDSCO streamlined IVD registration is attracting membrane consumption growth. Pursue specification partnerships with liquid-handling instrument manufacturers rather than competing for standalone membrane sheet volumes.
For Investors and Strategic Acquirers: The market sits at a procurement-rationalization phase that favors specialized membrane formulators with captive diagnostic platform relationships. Long-term viability over the next decade hinges on positioning upstream of cassette-integrated workflow standardization. Watch EMA companion diagnostic validation protocol proliferation as the inflection signal elevating membrane performance specifications across pharmaceutical testing laboratories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive PVDF supply secures margin protection against Japanese and Chinese producer pricing power. |
| ISO 13485 Certification Infrastructure Investment | Compressed supplier qualification timelines unlock diagnostic center procurement committee access. |
| Automated Platform Specification Partnership | Integration with walk-away protein analysis systems captures cassette-format workflow standardization. |
| REACH-Compliant Solvent Recovery Retrofit | European nitrocellulose finishing capacity preservation depends on ECHA authorization timeline compliance. |
| India CRO Facility Geographic Expansion | Hyderabad and Bengaluru clustering leverages CDSCO streamlined pathways for membrane consumption growth. |
Research Methodology
A spread of perspectives from diagnostic center procurement managers, CRO supply chain directors, membrane manufacturing plant engineers, and pharmaceutical quality control laboratory heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA companion diagnostic guidance documents, REACH authorization timelines published by ECHA, and trade flow data through Rotterdam and Shanghai Yangshan ports. Bottom-up membrane consumption estimates triangulated against top-down biomedical research funding allocations across the United States, Germany, and China.
Segmentation dimensions modeled span product type, transfer technology, end-use application, and end-user procurement archetype across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating EMA validation protocol evolution, REACH compliance cost pass-through assumptions, and CRO facility investment pipelines. Industry-specific forecast inputs included western blot protocol standardization rates and pre-cast gel cassette adoption curves in pharmaceutical testing laboratories.
Material uncertainties — cotton linter commodity price volatility, fluoropolymer resin supply disruption, and EMA companion diagnostic timeline acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and CRO procurement consolidation trajectories. Recalibration cycles align with material shifts in REACH authorization timelines and companion diagnostic validation protocol proliferation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Nafion Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Europe Gas Barrier Membrane Market