
 Hexyl Acetate Market | 2026-2036
Hexyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Hexyl Acetate Market Foresight
A widening capital-intensity gap between integrated petrochemical giants and specialty ester producers is bifurcating competitive dynamics in hexyl acetate supply. BASF SE leverages its Ludwigshafen Verbund complex to secure backward integration into n-hexanol and acetic acid feedstocks, insulating margin structures from raw material volatility. International Flavors & Fragrances anchors its position through dedicated fragrance-grade ester distillation capacity aligned with IFRA compliance protocols. Augustus Oils specializes in small-batch, high-purity cosmetic-grade hexyl acetate for niche European perfumers, competing on specification flexibility rather than scale.
Hexyl acetate is a saturated aliphatic ester formed from n-hexanol and acetic acid, typically presenting as a colorless liquid with a fruity, apple-like odor profile and boiling point near 171 degrees Celsius, synthesized via Fischer esterification or carbonylation routes for use as a flavoring agent, fragrance modifier, and industrial solvent. Food-grade hexyl acetate sustains the largest volume share as beverage and confectionery formulators standardize on GRAS-listed esters for authentic fruit top notes, while pharmaceutical-grade production commands superior unit economics due to USP and EP compliance burdens that limit qualified suppliers. Cosmetic-grade demand is accelerating fastest among the product categories as clean-label perfume brands substitute synthetic esters for restricted natural extracts, though industrial-grade applications in coatings and adhesives remain structurally mature with thin margin pools.
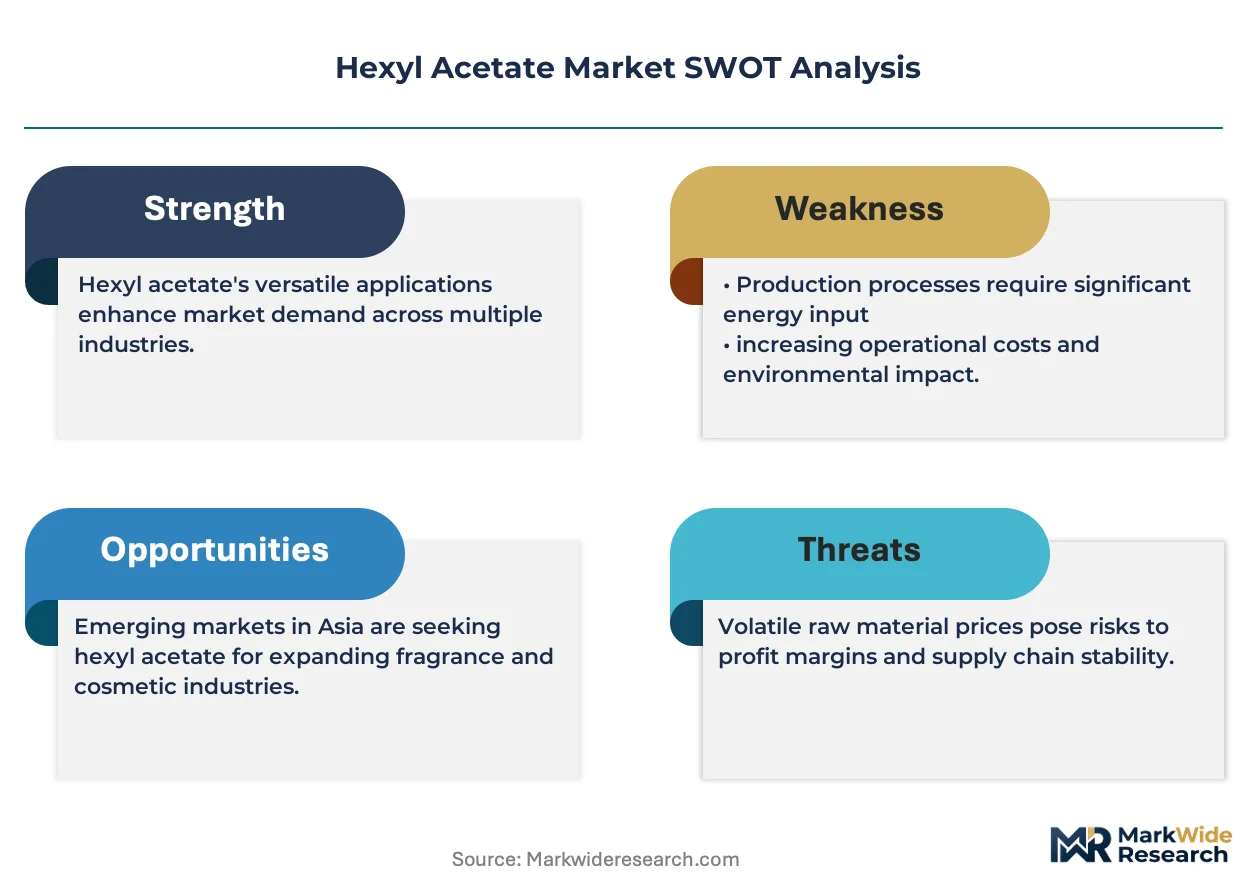
EPA oversight under the Toxic Substances Control Act and REACH registration requirements through ECHA impose purity and impurity profiling obligations that elevate compliance costs for hexyl acetate entering consumer applications. FDA food additive regulations and IFRA standards for fragrance materials further constrain formulation flexibility, channeling demand toward suppliers with documented toxicological dossiers and analytical certification capabilities. Stakeholders must monitor evolving restrictions on volatile organic compound emissions in industrial coatings and emerging biobased ester alternatives that could displace petroleum-derived hexyl acetate in sustainability-sensitive segments.
Market Dynamics
REACH registration requirements and EPA Toxic Substances Control Act enforcement are compressing the supplier base for hexyl acetate, forcing fragrance compounders to consolidate procurement around certified producers with documented toxicological dossiers.
Growth Catalysts
- Clean-label perfume formulations:Cosmetic brands are substituting synthetic esters for restricted natural extracts, expanding hexyl acetate demand in IFRA-compliant fragrance modifications.
- India's domestic personal care manufacturing:Regional fragrance compounders in Mumbai and Hyderabad are scaling production to serve local cosmetic brands, concentrating procurement volumes.
- Fischer esterification optimization:Continuous reactor designs are reducing acetic acid waste streams, improving process economics for food-grade ester producers.
Market Restraints
- N-hexanol feedstock volatility:Crude oil-linked pricing for petrochemical alcohols creates margin compression for non-integrated hexyl acetate manufacturers.
- Biobased ester substitution:Fermentation-derived ethyl acetate and natural isolates are capturing sustainability-sensitive segments in European cosmetics.
- REACH authorization timelines:ECHA's extended substance evaluation periods delay market entry for new hexyl acetate suppliers lacking legacy registration data.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP compliance capabilities unlock superior unit economics in parenteral drug formulations with limited qualified competition.
- China's regional fragrance clusters:Guangdong and Zhejiang province cosmetic manufacturers are localizing supply chains, creating captive offtake opportunities.
- ISO 16128 natural origin claims:Biotechnological hexyl acetate from sugar fermentation qualifies for natural cosmetic indexing, accessing premium positioning.
Industry Challenges
- Analytical certification capabilities:Gas chromatography-mass spectrometry impurity profiling requires capital investment that small-batch producers struggle to fund.
- Cross-contamination prevention:Multi-grade facilities must segregate food-grade, cosmetic-grade, and industrial-grade production lines, complicating capacity allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexyl Acetate Market |
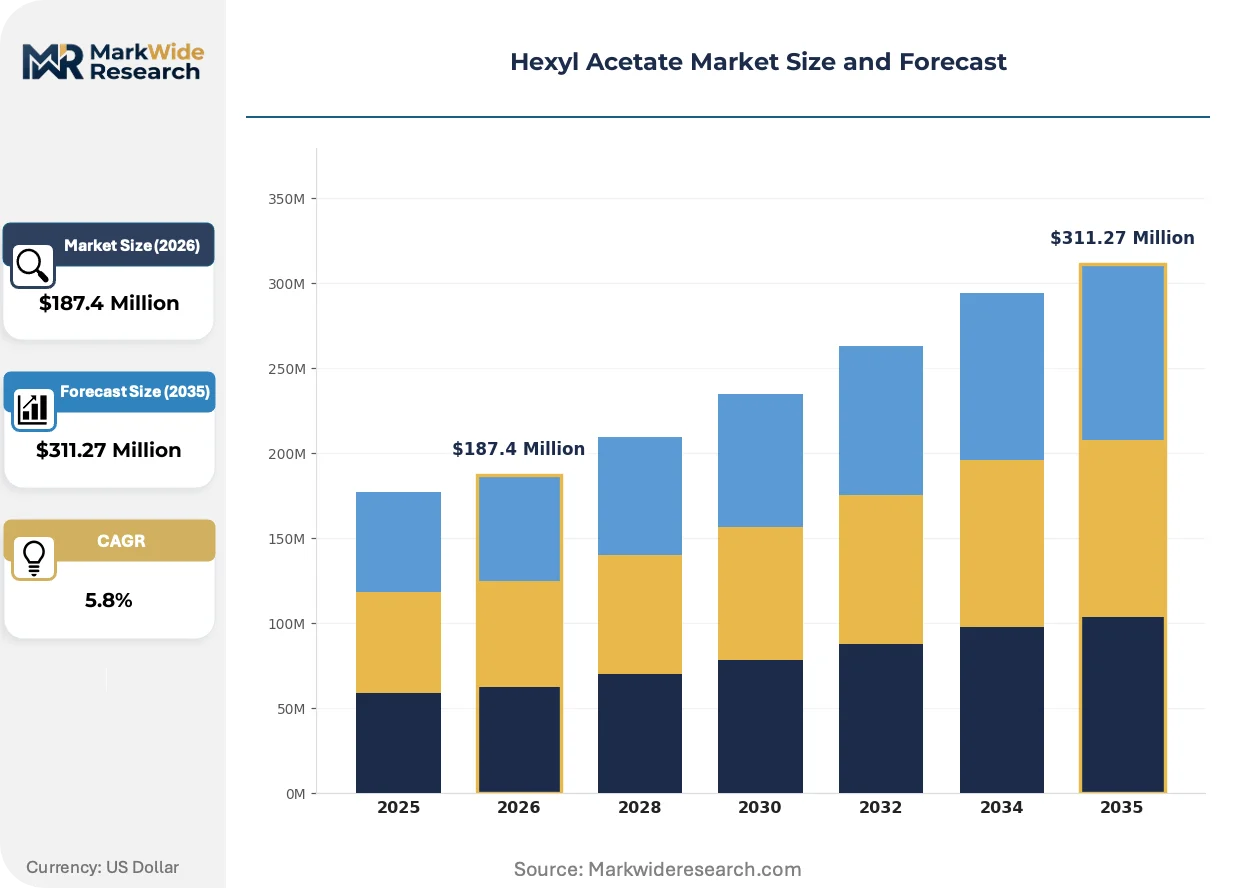
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Paints Packaging Type: Drums, Bottles, Bulk Containers, Pails Delivery Mode: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | LyondellBasell Industries, International Flavors & Fragrances, BASF SE, Advanced Biotech, Merck KGaA, Eastman Chemical Company, Celanese Corporation, Augustus Oils, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexyl Acetate Market Shifts & Advancements
Biotechnological production routes and tightening purity specifications are restructuring competitive advantage in hexyl acetate supply, favoring producers with analytical capabilities and fermentation expertise over conventional petrochemical processors.
Enzymatic esterification using immobilized lipase biocatalysts is displacing sulfuric acid-catalyzed Fischer routes in cosmetic-grade production. Fragrance houses in Grasse and Geneva are qualifying these batches for natural-origin claims under ISO 16128. The technology is compressing capital requirements for small-scale producers while eliminating neutralization waste streams.
REACH's revised restriction proposals on skin-sensitizing impurities are forcing reformulation of legacy hexyl acetate stocks. ECHA's 2023 guidance on ester impurity thresholds has triggered re-qualification campaigns among European fragrance compounders. Suppliers without documented toxicological dossiers are exiting cosmetic applications, concentrating volumes among compliant producers.
Direct contracting between fragrance houses and ester manufacturers is eliminating regional distributor layers. Specialty chemical distributors in Frankfurt and Singapore are losing hexyl acetate volumes as IFF and Givaudan establish direct supplier audits. This disintermediation is most advanced in European perfume compounding, where supply chain transparency requirements favor verified direct relationships.
Hexyl Acetate Market Segmentation
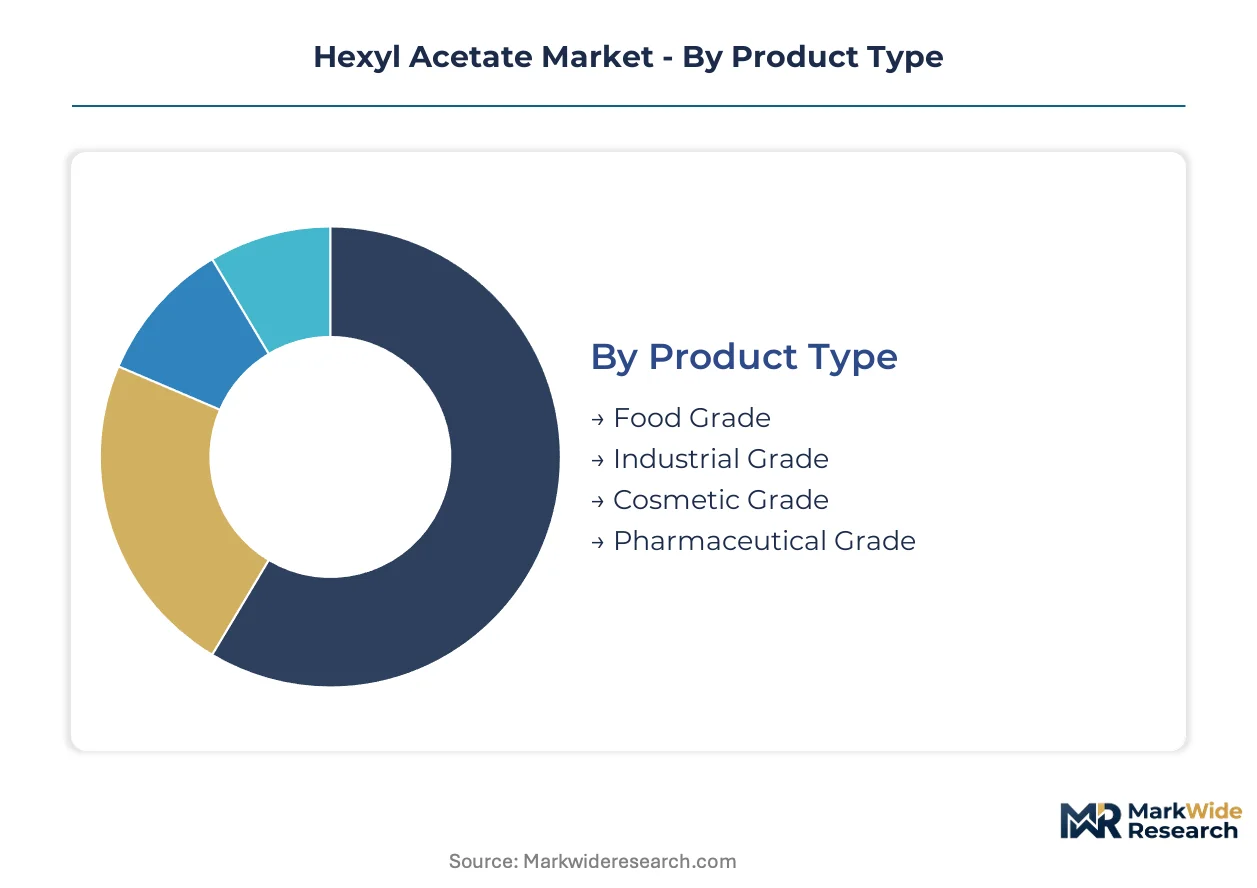
Hexyl acetate procurement patterns diverge sharply across purity grades and end-use specifications, with regulatory thresholds fragmenting supplier capabilities and regional manufacturing clusters driving channel preferences. Understanding these segment boundaries reveals where margin pools concentrate and which certification barriers protect incumbent positions.
Product Type:
Domestic consumption dominates food-grade and industrial-grade volumes in China and India, while cosmetic-grade and pharmaceutical-grade production serves export markets bound for European fragrance houses and US drug formulators.
- Food Grade:GRAS-listed ester meeting FDA and FSSAI specifications for beverage and confectionery applications. Procurement concentrates among integrated flavor houses in Guangdong and Maharashtra seeking consistent fruit-top-note performance for carbonated drinks and hard candies.
- Cosmetic Grade:High-purity batches qualified under IFRA standards and REACH registration for fragrance compounding. Demand is climbing fastest among clean-label perfume brands in Grasse and Geneva substituting synthetic esters for restricted natural extracts.
- Industrial Grade:Technical specification solvent for coatings and adhesives with thinner margin structures. Applications remain structurally mature across Asian manufacturing clusters serving automotive and furniture finishing sectors.
- Pharmaceutical Grade:USP and EP compliance for parenteral drug formulations with limited qualified supplier base. Unit economics exceed other grades due to toxicological dossier requirements and impurity profiling obligations.
Food Grade holds the largest share; momentum sits with Cosmetic Grade.
End Use Industry:
Cost tier stratification separates premium formulation applications from commodity solvent consumption, with certification burdens determining supplier eligibility across each vertical.
- Food & Beverage:Standardized procurement of GRAS-listed esters by multinational flavor houses and regional beverage compounders. Volume concentration in China, India, and Brazil supports integrated ester producers with backward feedstock control.
- Cosmetics:Fragrance-grade specifications for perfume, skincare, and personal care formulations. European and Japanese fragrance houses drive qualification protocols, with direct contracting eliminating distributor layers.
- Pharmaceuticals:Parenteral and topical drug delivery applications requiring documented impurity profiles. USP and EP compliance limits qualified suppliers to established pharmaceutical excipient manufacturers.
- Paints:Industrial solvent consumption in coatings and adhesives with volatile organic compound emission constraints. Regulatory pressure from EPA and MEE is compressing demand in favor of lower-VOC alternatives.
Food & Beverage commands volume leadership; Cosmetics exhibits the steepest expansion trajectory.
Packaging Type:
Customer scale and application sensitivity dictate container selection, with multi-grade facilities requiring segregation protocols that elevate handling costs for smaller formats.
- Drums:Standard 200-liter steel packaging for mid-volume cosmetic and food-grade shipments. Preferred by fragrance compounders in Hyderabad and Mumbai with batch-scale formulation requirements.
- Bulk Containers:ISO tank and flexitank configurations for integrated flavor houses and industrial coatings manufacturers. Direct port-to-plant logistics reduce handling costs for high-volume purchasers in Rotterdam and Shanghai.
- Bottles:Smaller-format glass and fluorinated polymer containers for pharmaceutical-grade and high-purity cosmetic samples. Laboratory and R&D procurement in Basel and Boston favors this format for qualification testing.
- Pails:20-25 liter plastic pails for artisanal food producers and niche perfumers. Augustus Oils and similar specialty suppliers utilize this format for small-batch European cosmetic-grade distribution.
Bulk Containers dominate procurement tonnage; Bottles capture premium positioning.
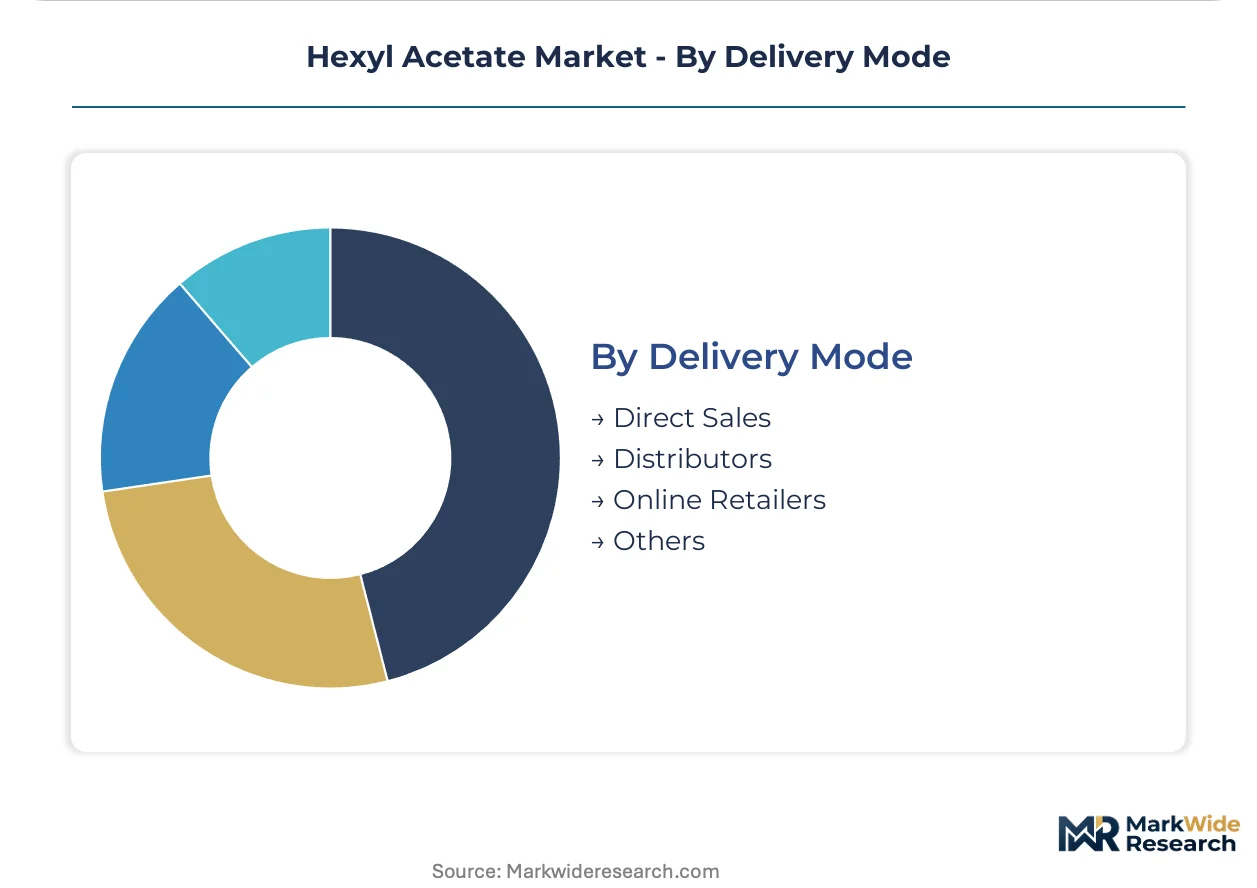
Delivery Mode:
Supply chain transparency requirements and certification documentation needs are restructuring channel economics, favoring verified direct relationships over traditional distribution layers.
- Direct Sales:Contracted supply agreements between ester manufacturers and fragrance houses or pharmaceutical formulators. IFF and Givaudan have established direct supplier audits, bypassing Frankfurt and Singapore distributors.
- Distributors:Regional chemical distributors serving fragmented industrial-grade and food-grade purchasers. Channel share is compressing as procurement consolidation and compliance documentation requirements favor direct sourcing.
- Online Retailers:E-commerce platforms for small-volume laboratory and R&D procurement. Emerging channel for sample-grade pharmaceutical and cosmetic specifications in North American and European markets.
- Others:Agent-mediated transactions and trading house arrangements for spot industrial-grade purchases. Concentrated in Asian coatings and adhesives markets with price-sensitive procurement patterns.
Direct Sales holds expanding share; Online Retailers is gaining traction fastest among qualification-stage buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in industrial coatings applications exhibit acute price sensitivity to n-hexanol feedstock swings, while fragrance compounders in Grasse and Geneva absorb premium pricing for IFRA-compliant certification documentation.
United States
Pharmaceutical formulators in New Jersey and Massachusetts drive USP-grade procurement for parenteral drug delivery systems. EPA enforcement under the Toxic Substances Control Act elevates impurity profiling costs for cosmetic-grade suppliers entering consumer markets. The Gulf Coast petrochemical corridor sustains backward-integrated hexyl acetate output serving domestic flavor houses.
Germany
BASF's Ludwigshafen Verbund complex anchors European supply through captive n-hexanol and acetic acid integration. REACH registration requirements through ECHA compress the qualified supplier base for fragrance applications. Specialty ester distillers in the Rhine-Neckar region serve IFRA-compliant cosmetic compounders with documented toxicological dossiers.
China
Guangdong and Zhejiang province cosmetic manufacturers localize supply chains for domestic personal care brands expanding production capacity. MEE oversight on volatile organic compound emissions constrains industrial-grade applications in coatings sectors. Yangtze River Delta flavor houses standardize on GRAS-listed esters for beverage formulations targeting Southeast Asian export markets.
India
Fragrance compounders in Mumbai and Hyderabad scale manufacturing to serve regional cosmetic brands reducing import dependency. FSSAI food additive regulations align procurement specifications with multinational flavor house requirements. Maharashtra-based integrated ester producers leverage domestic n-hexanol supply to capture share from Chinese imports.
Switzerland
Geneva-based fragrance houses drive qualification protocols for high-purity cosmetic-grade specifications with direct supplier auditing requirements. Swissmedic pharmaceutical oversight creates parallel compliance tracks for excipient-grade esters entering drug formulations. Basel laboratory clusters source sample-grade hexyl acetate in fluorinated polymer containers for R&D qualification testing.
Hexyl Acetate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hexyl acetate supply, with petrochemical conglomerates controlling feedstock economics while boutique distillers capture specification premiums. The market structure rewards backward integration into n-hexanol and acetic acid, insulating margin positions from crude oil volatility. Three archetypes dominate: integrated petrochemical giants with Verbund-site advantages, fragrance-grade specialists with IFRA compliance capabilities, and pharmaceutical excipient manufacturers with USP documentation. Capacity expansion and direct contracting with fragrance houses represent the dominant competitive vectors, bypassing traditional distributor layers.
Among German-headquartered conglomerates, BASF SE exemplifies the integrated archetype through its Ludwigshafen complex. International Flavors & Fragrances occupies a position within the fragrance-grade specialist tier, representing the direct-contracting trend with established supplier audit protocols. Augustus Oils sits within the boutique specialist category, serving niche European perfumers through small-batch production with specification flexibility rather than scale economics.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| International Flavors & Fragrances |
| BASF SE |
| Advanced Biotech |
| Merck KGaA |
| Eastman Chemical Company |
| Celanese Corporation |
| Augustus Oils |
| Dow Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between integrated petrochemical producers and fragrance houses lock in supply access while providing price visibility across n-hexanol feedstock cycles. These arrangements insulate BASF and IFF from spot volatility in Ludwigshafen and Geneva procurement corridors.
Pricing Analysis
Service-level agreements and toxicological dossier maintenance drive lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates USP-compliant batches from IFRA-certified and technical specifications. Cost compression in industrial-grade tiers intensifies because coatings formulators prioritize VOC-compliant solvents over ester purity. Fragrance compounders in Grasse exhibit lowest price sensitivity; Asian coatings buyers absorb highest volatility.
Supply Chain Analysis
Port congestion on Rotterdam-Singapore trade lanes elevates inbound logistics costs for European fragrance houses sourcing from Yangtze River Delta producers. Manufacturing concentrates in Germany, China, and India. Feedstock draws from n-hexanol and acetic acid streams. Single-source vulnerability around BASF's Ludwigshafen Verbund creates concentration risk. Distribution runs through direct contracting channels bypassing Frankfurt and Singapore distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hexyl acetate supply functions as a platform economy where REACH registration data and IFRA compliance protocols create interoperability barriers. Fragmentation between integrated petrochemicals and boutique distillers accelerates ecosystem consolidation around certified data packages.
For Market Incumbents: Shield margin structures by deepening captive n-hexanol production in Ludwigshafen-scale complexes. Biobased ester substitution from fermentation-derived alternatives threatens petroleum-derived positions; counter through ISO 16128 natural-origin certification investment.
For New Entrants and Emerging Players: Differentiate on enzymatic esterification routes qualifying for natural cosmetic indexing. India's domestic personal care manufacturing presents most penetrable geography. Pursue direct supplier audits with Mumbai and Hyderabad fragrance compounders.
For Investors and Strategic Acquirers: Boutique IFRA-compliant distillers with documented toxicological dossiers represent priority acquisition archetypes. Long-term viability hinges on regulatory data moats rather than scale economies. Watch ECHA substance evaluation timelines as inflection indicator for supplier base compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-Hexanol | BASF's Ludwigshafen complex secures feedstock autonomy against crude-linked volatility. |
| Enzymatic Esterification Scale-Up | Immobilized lipase routes unlock ISO 16128 natural-origin claims for Grasse perfumers. |
| Direct Supplier Audit Programs | IFF and Givaudan bypass Frankfurt distributors for supply chain transparency compliance. |
| Pharmaceutical-Grade Certification | USP and EP compliance opens parenteral drug formulation markets with limited competition. |
| Regional Production Localization | Guangdong and Zhejiang manufacturers capture captive offtake from domestic cosmetic brands. |
Research Methodology
Initial hypotheses were tested against primary input from fragrance compounders, pharmaceutical formulators, petrochemical procurement leads, and specialty ester distillers and refined through customs trade data, ECHA registration databases, SEC chemical sector filings, and IFRA compliance disclosures. Bottom-up grade-tier volume estimates triangulated with top-down end-use industry consumption models.
Variance decomposition across pharmaceutical, cosmetic, food-grade, and industrial segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth differentials weighted by purity-grade pricing premiums. Modeled inputs included REACH authorization timelines, n-hexanol feedstock cost trajectories, and enzymatic route capacity buildouts.
Material uncertainties — biobased substitution rates, ECHA impurity threshold revisions, and MEE VOC enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and fermentation technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global PVC Stabilizer Market
Additives
Crosslinking Agents Market
Additives
Coating Additives Market
Additives
Asia-Pacific Fuel Additives Market
Additives
North America Pectin Market
Additives
Hydroxyethyl Cellulose Market
Additives
Metal Deactivators Market
Additives
Clouding Agents Market
Additives
Global Polyurethane Additives Market
Additives
Ruminant Feed Additive Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Europe Citric Acid Market
Additives
Impact Modifier Market
Additives
Sodium Metabisulfite Market
Additives
Flux Injection System Market