
 Global Feed Acidifiers Market | 2026-2036
Global Feed Acidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Acidifiers Market Analysis
The EU Green Deal's Farm to Fork strategy is restructuring procurement criteria for livestock feed additives across European supply chains. BASF SE leverages its organic acid production scale to anchor supply agreements with integrated poultry processors. Cargill competes through backward integration into fermentation-based acidifier manufacturing. Novus International differentiates via mineral-chelated acid blends tailored to ruminant gut pH modulation.
Feed acidifiers comprise organic acids, inorganic acids, and their salts or blends added to animal feed typically at inclusion rates of 0.5% to 3.0% to reduce gastric pH, inhibit pathogenic bacterial colonization, and improve nutrient digestibility. Organic acids dominate value contribution due to higher unit pricing and established efficacy documentation in poultry and swine diets. Powder formulations lead volume throughput for premix integration, while liquid acidifiers represent the fastest-growing form segment driven by automated dosing systems in modern feed mills. Aquaculture end-use trails terrestrial livestock but commands premium pricing for species-specific acidifier complexes targeting shrimp and salmonid gut health.
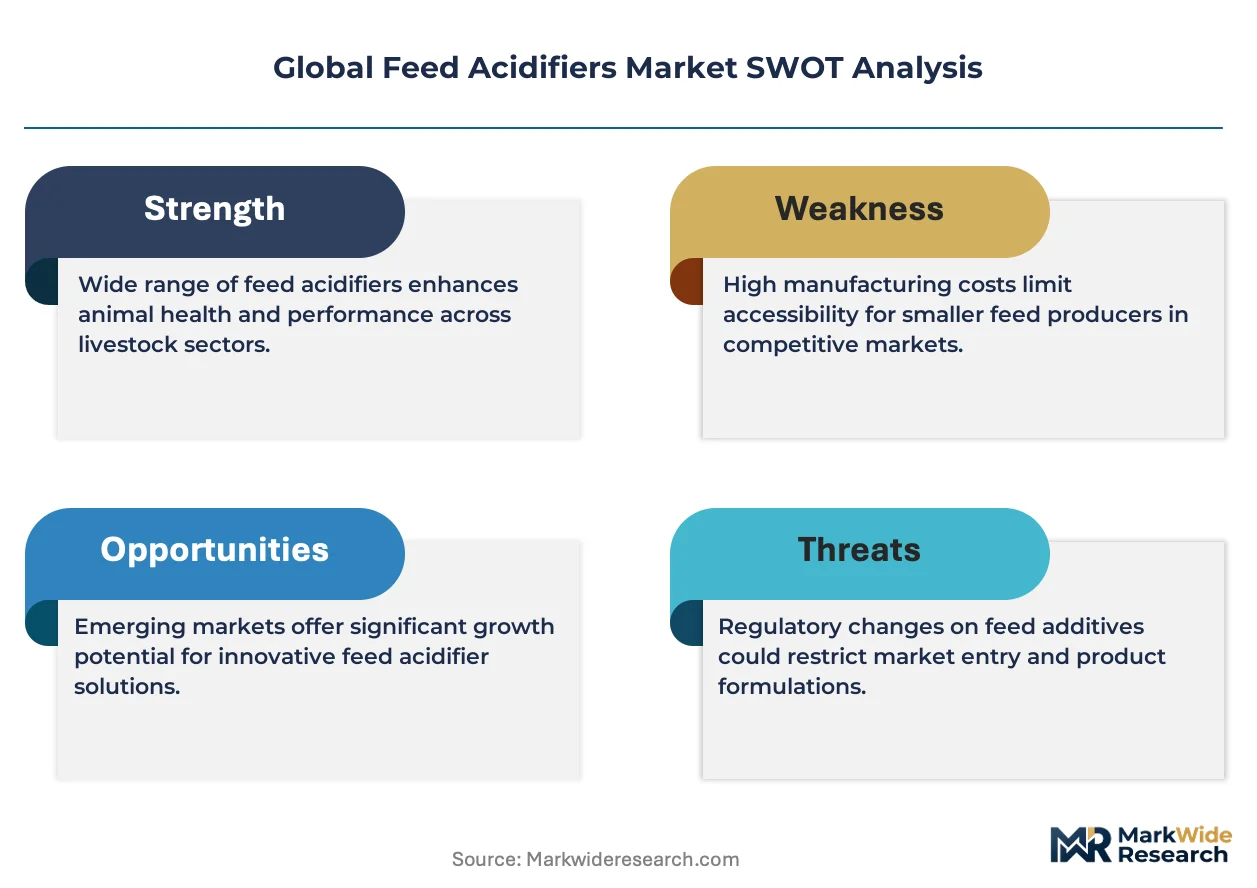
The European Food Safety Authority mandates full toxicological dossiers for new feed acidifier authorizations under Regulation 1831/2003, extending development timelines and favoring incumbents with established regulatory infrastructure. The FDA's Center for Veterinary Medicine oversees Generally Recognized as Safe determinations for acidifiers in US livestock feeds, while China's Ministry of Agriculture and Rural Affairs enforces GB standard compliance for imported acidifier products. Stakeholders must monitor evolving residue monitoring protocols in major import markets and align formulation investments with jurisdiction-specific approval statuses rather than assuming regulatory equivalence across borders.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing approval timelines for novel acidifier formulations while simultaneously mandating full toxicological dossiers, creating a bifurcated competitive landscape where incumbents with established regulatory infrastructure capture disproportionate share of new contract volumes.
Growth Catalysts
- Antibiotic-free production mandates:Poultry integrators across Brazil, China, and the Netherlands are expanding acidifier programs to meet processor commitments, pulling demand from therapeutic alternatives into documented gut-health solutions.
- Regulation 1831/2003 compliance infrastructure:The European Food Safety Authority's authorization pathway, despite its dossier burden, creates durable competitive moats for suppliers with in-house toxicological capabilities and established safety data packages.
- Automated dosing system penetration:Modern feed mills in Southeast Asia's contract farming zones are retrofitting liquid acidifier infrastructure, converting powder-dominant operations toward precision inclusion rate control.
Market Restraints
- Propionic acid feedstock volatility:Organic acid production depends on petrochemical-derived substrates and agricultural fermentation feedstocks, exposing margin structures to crude oil and grain price oscillations without long-term supply contracts.
- Regulatory equivalence fragmentation:China's Ministry of Agriculture and Rural Affairs enforces GB standard compliance for imported acidifiers that diverges from FDA Generally Recognized as Safe determinations, forcing formulation variants and duplicative registration investments.
- Enzyme-probiotic substitution:Direct-fed microbials and exogenous enzyme complexes are capturing budget allocation in swine diets where acidifier efficacy documentation remains less established relative to poultry applications.
Strategic Opportunities
- Aquaculture premium positioning:Shrimp and salmonid gut-health acidifier complexes command pricing multiples over terrestrial livestock formulations due to species-specific pH modulation requirements and limited supplier specialization.
- Backward integration into fermentation:Captive production of citric, fumaric, and lactic acid precursors insulates against merchant market volatility and enables customized blend ratios for integrated processor accounts.
- Residue monitoring protocol alignment:Major import markets are tightening analytical detection thresholds for acidifier metabolites, creating first-mover advantage for suppliers with validated withdrawal period data and third-party certification.
Industry Challenges
- Formulation chemist scarcity:The intersection of organic acid chemistry, animal nutrition science, and regulatory dossier preparation requires specialized talent pools concentrated among incumbent suppliers, constraining new entrant scale-up velocity.
- Legacy premix integration complexity:Powder acidifier formulations dominate existing feed mill infrastructure, and liquid system retrofits demand capital allocation that contract manufacturers resist without volume guarantees from anchor customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Acidifiers Market |
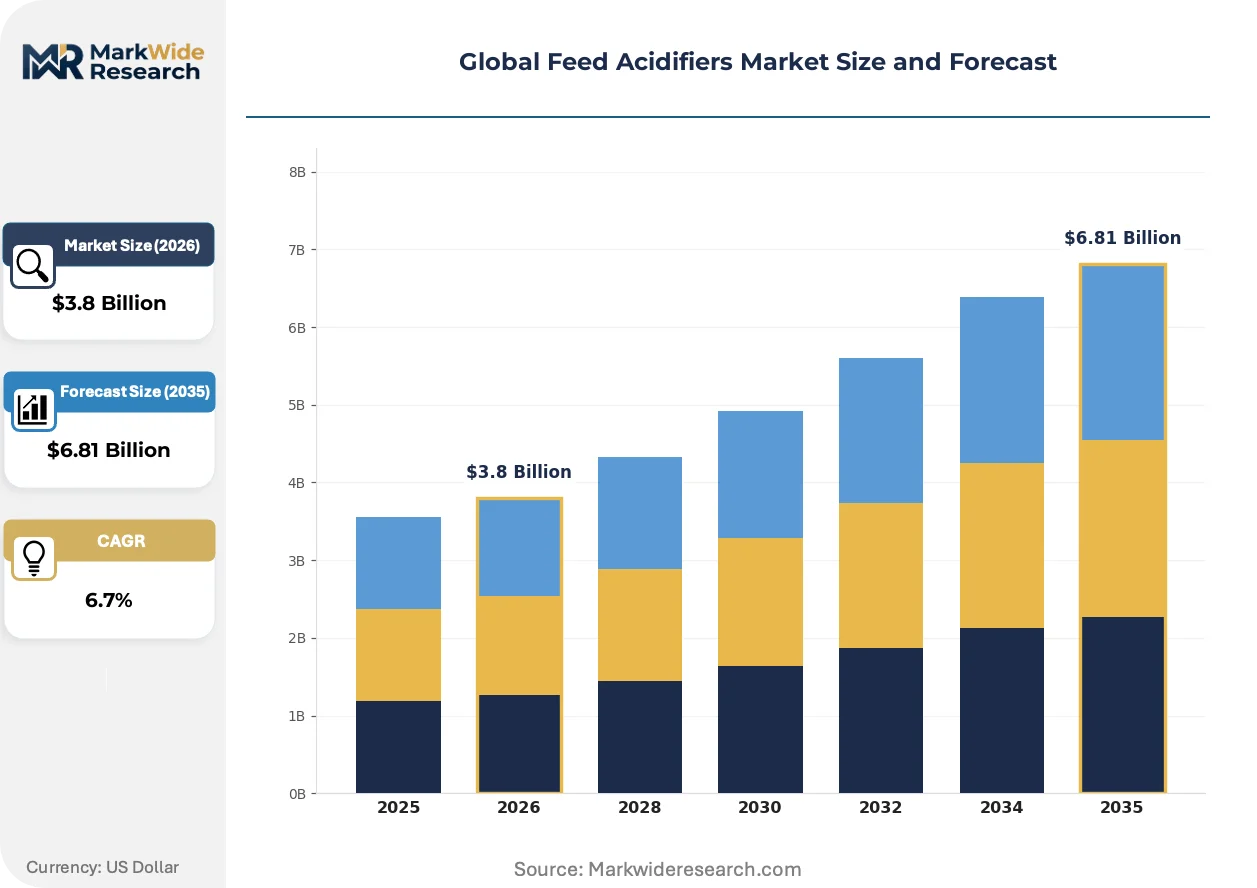
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Organic Acids, Inorganic Acids, Blends, Salts End User: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Direct Sales, Distributors, E-commerce, Retail Form: Powder, Liquid, Granules, Pellets |
| Companies Covered | BASF SE, Cargill, Novus International, Kemin Industries, Perstorp Holding AB, Adisseo, Nutreco, Biomin Holding GmbH, Impextraco NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Acidifiers Market Emerging Trajectories
Precision fermentation and automated inclusion control are redrawing technical boundaries between commodity organic acid supply and differentiated acidifier complex formulation, compressing the value capture available to standalone traders.
Encapsulation technology is decentralizing acidifier efficacy from inclusion rate brute force toward targeted release in specific gut segments. Poultry integrators in the Netherlands and Denmark are adopting pH-responsive polymer coatings for organic acids at accelerating pace. This technology is decentralizing competitive advantage from bulk acid production scale toward formulation science capabilities and veterinary nutrition partnerships.
REACH authorization timelines for novel acidifier salts are extending development cycles beyond five years for substances lacking existing food-contact approvals. The European Chemicals Agency's substance evaluation process now routinely requests additional mammalian toxicology data for feed-grade organic acid derivatives. Mineral-chelated acid blends targeting ruminant gut pH modulation face the most pronounced regulatory friction due to dual classification uncertainties between feed additive and veterinary medicinal product.
Processor-enforced feed protocol standardization is consolidating procurement authority within Southeast Asia's contract farming zones. Large aquafeed and poultry operations in Vietnam and Indonesia are mandating approved supplier lists that exclude non-certified acidifier traders, displacing spot-market purchasing with annual framework agreements tied to audit compliance. Thailand's integrated shrimp processors are the most advanced in this transition, with acidifier specification now embedded in grow-out contract terms.
Global Feed Acidifiers Market Segmentation
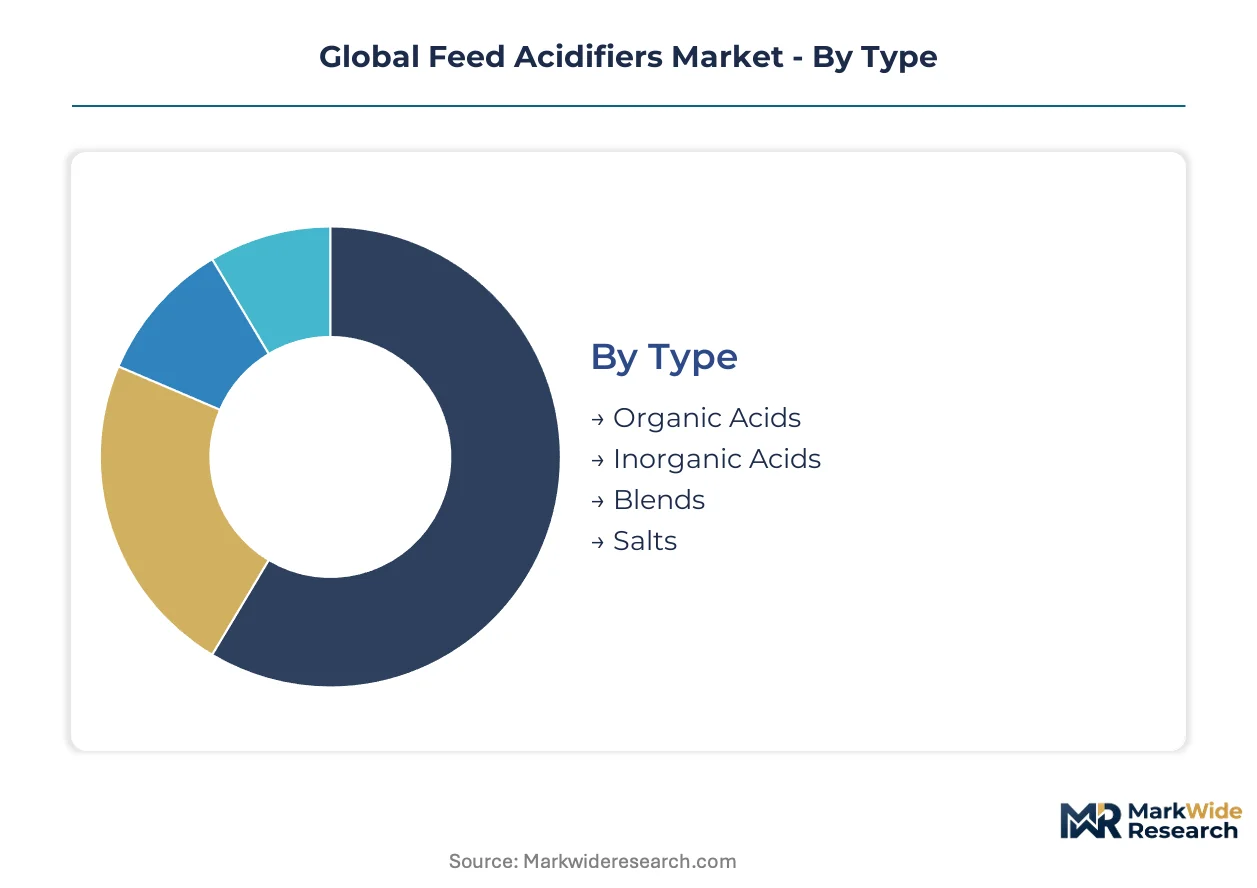
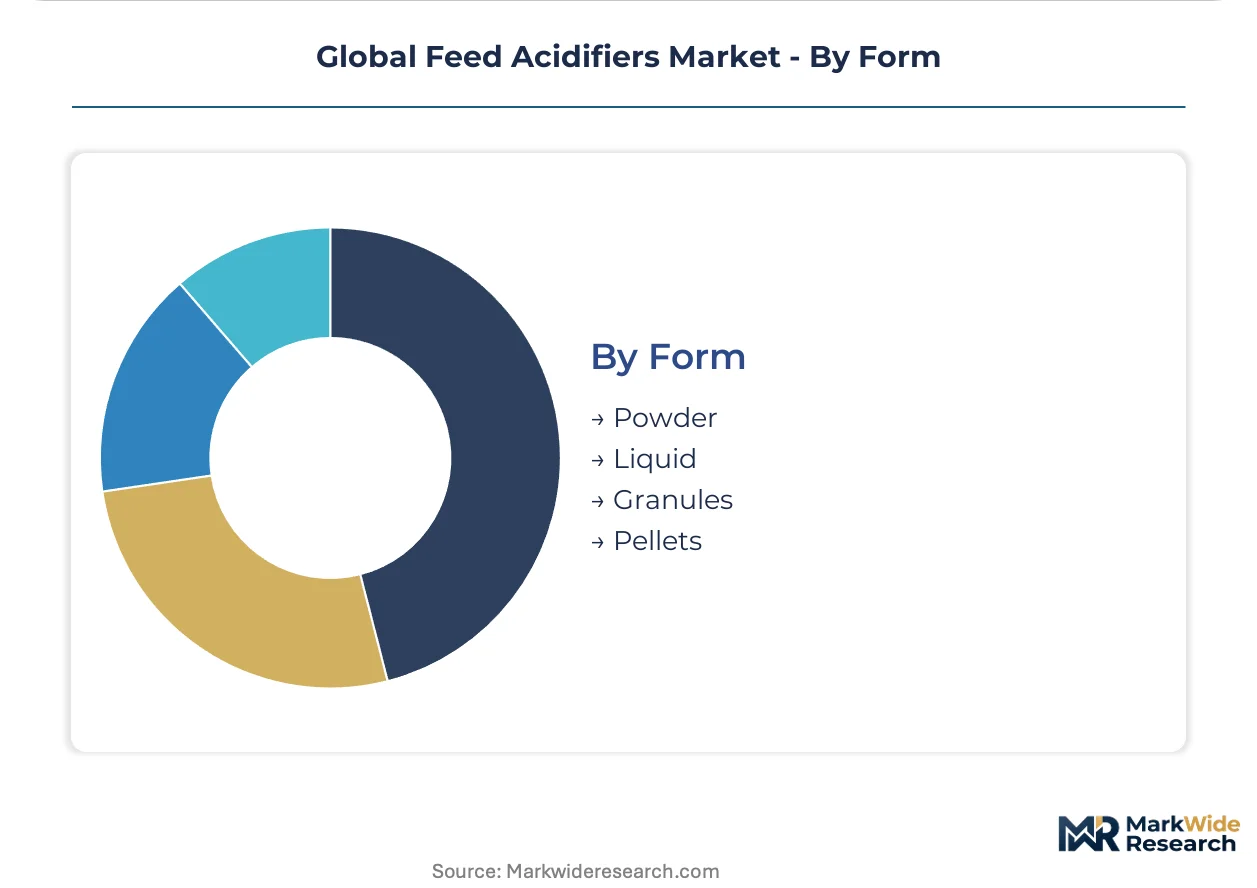
Feed acidifier suppliers structure product portfolios across four intersecting dimensions. Type and form determine manufacturing investment, while end-use and channel configuration dictate pricing power and customer retention mechanics.
Type:
Supply concentration clusters around fermentation-scale producers with captive organic acid capacity, while blend formulations attract specialized compounders lacking upstream chemical assets.
- Organic Acids:Citric, fumaric, and propionic acids constitute the core chemistry set. Poultry integrators in the Netherlands and Denmark specify organic acid programs for antibiotic-free production commitments, pulling volume from inorganic alternatives.
- Blends:Multi-acid complexes with mineral chelation or encapsulation technology command formulation premiums. Southeast Asian contract farming zones standardize on processor-approved blend specifications, displacing single-acid commodity purchasing.
- Inorganic Acids:Phosphoric and hydrochloric acid derivatives serve cost-sensitive ruminant applications with simpler pH modulation requirements.
- Salts:Calcium formate and sodium benzoate derivatives offer handling safety and premix compatibility for legacy feed mill infrastructure.
Today's leader: Organic Acids. Tomorrow's challenger: Blends.
End User:
Application-driven margin tiers separate species with documented gut-health efficacy from those where acidifier value remains unproven.
- Poultry:Broiler and layer operations generate the highest acidifier inclusion rates with established performance documentation. Brazil's integrated processors enforce standardized acidifier protocols across grow-out operations.
- Swine:Nursery and grower phase applications concentrate demand, though enzyme-probiotic competition constrains budget allocation relative to poultry.
- Aquaculture:Shrimp and salmonid acidifier complexes command premium multiples due to species-specific pH requirements and limited supplier specialization.
- Ruminants:Mineral-chelated acid blends target rumen pH modulation, though regulatory classification uncertainty between feed additive and veterinary medicinal product slows adoption.
Poultry anchors current procurement volume. Aquaculture offers the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects customer scale and technical service intensity requirements.
- Direct Sales:Integrated poultry and aquafeed processors negotiate annual framework agreements with acidifier manufacturers. Thailand's shrimp processors embed specifications directly in grow-out contracts.
- Distributors:Regional feed compounders and independent premix manufacturers rely on distributor inventory and technical support.
- E-commerce:Automated reordering platforms penetrate Southeast Asian contract farming zones with standardized product codes and audit-compliant documentation.
- Retail:Smallholder livestock operations in fragmented markets access acidifiers through agricultural supply cooperatives.
Direct Sales dominates value capture. E-commerce is gaining share fastest in standardized procurement environments.
Form:
Physical form determines feed mill capital requirements and inclusion precision.
- Powder:Dominates existing premix infrastructure with straightforward handling and metering. Legacy operations across Brazil and China maintain powder-dominant workflows.
- Liquid:Automated dosing systems in modern feed mills enable precision inclusion rate control. Vietnamese and Indonesian operations retrofit liquid infrastructure at accelerating pace.
- Granules:Flowability-optimized for bulk handling in large-scale ruminant feed operations.
- Pellets:Protected acid release for specific gut segment targeting, typically combined with encapsulation technology.
Powder retains volume leadership. Liquid represents the fastest-growing form segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed acidifier commercialization traces its industrial roots to post-war European chemical manufacturing, where German and Dutch organic acid producers first adapted citric and propionic acid streams for livestock feed applications. That European technical foundation now underpins global formulation standards, though production capacity and demand growth have dispersed across multiple continents.
United States
Integrated poultry processors in Georgia and Arkansas enforce antibiotic-free protocols that pull acidifier volume into documented gut-health programs. The FDA's Center for Veterinary Medicine oversees Generally Recognized as Safe determinations, creating a distinct compliance pathway from European dossier requirements. Iowa and North Carolina swine operations concentrate nursery-phase acidifier demand, though enzyme-probiotic competition constrains budget allocation relative to poultry applications.
Germany
The EFSA authorization pathway under Regulation 1831/2003 extends development timelines beyond five years, favoring incumbents with established toxicological infrastructure. BASF SE leverages its Ludwigshafen organic acid production scale to anchor supply agreements with integrated poultry processors across Lower Saxony and North Rhine-Westphalia. The country's national chemical regulator enforces REACH compliance for novel acidifier salts, adding registration friction for imported formulations.
China
The Ministry of Agriculture and Rural Affairs enforces GB standard compliance for imported acidifiers that diverges from FDA and EFSA frameworks, forcing formulation variants and duplicative registration investments. Shandong and Jiangsu provinces concentrate domestic organic acid fermentation capacity, with provincial agricultural departments mandating residue monitoring protocols for contract farming zones. Brazilian-owned poultry integrators operating in Guangdong and Fujian are expanding acidifier programs to meet export-market antibiotic-free commitments.
Brazil
Integrated poultry processors in Paraná and Santa Catarina enforce standardized acidifier protocols across grow-out operations, displacing therapeutic antibiotic use. ANVISA coordinates with the Ministry of Agriculture on feed additive import registration, though approval timelines remain shorter than European equivalents. São Paulo state's feed compounders are retrofitting liquid acidifier infrastructure at accelerating pace to serve automated dosing systems in modern feed mills.
Netherlands
Poultry integrators in Gelderland and North Brabant specify pH-responsive encapsulated organic acids for antibiotic-free production commitments. The EU Green Deal's Farm to Fork strategy accelerates demand for documented gut-health solutions, with Dutch agricultural cooperatives embedding acidifier specifications in processor-grower contracts. Wageningen University research clusters drive encapsulation technology adoption, decentralizing competitive advantage from bulk acid production toward formulation science capabilities.
Global Feed Acidifiers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the feed acidifier value chain. Fermentation-scale organic acid manufacturers with captive citric, fumaric, and propionic acid capacity face specialized compounders lacking upstream chemical assets but commanding formulation premiums through encapsulation and mineral-chelation technology. Three archetypes dominate: integrated chemical-nutrition conglomerates with backward integration into acid precursors; specialized feed additive formulators with veterinary nutrition partnerships; and regional distributors with technical service capabilities but no manufacturing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with incumbents locking in multi-year supply agreements with integrated processors.
Within the integrated chemical-nutrition tier, BASF SE and Cargill exemplify divergent strategic positions. BASF SE anchors its competitive stance on organic acid production scale and European regulatory infrastructure. Cargill occupies a position emphasizing backward integration into fermentation-based manufacturing and direct processor relationships. Among specialized formulators, Novus International represents the mineral-chelated acid blend archetype targeting species-specific gut pH modulation. These three companies illustrate how technical specialization and supply chain configuration determine value capture in a market where regulatory dossier capabilities create durable competitive moats.
| Leading Market Players |
|---|
| BASF SE |
| Cargill |
| Novus International |
| Kemin Industries |
| Perstorp Holding AB |
| Adisseo |
| Nutreco |
| Biomin Holding GmbH |
| Impextraco NV |
| Others |
Supply Flow & Price Mechanics
Propionic acid feedstock volatility traces from petrochemical-derived substrates through agricultural fermentation inputs into tiered pricing structures downstream. Crude oil oscillations and grain price swings compress margins for non-integrated compounders while rewarding captive acid producers with long-term supply contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates encapsulated organic acid complexes from single-acid commodity powders and unbranded inorganic derivatives. Certification grade under EFSA Regulation 1831/2003 and volume scale commitments to integrated poultry processors drive price differentiation. Cost compression in standard-tier blends is intensifying because enzyme-probiotic substitutes capture swine diet budgets. Spot-market traders exhibit highest price sensitivity; Dutch and Thai integrators with processor-embedded contracts demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for acidifier packaging and dosing equipment refurbishment concentrate service revenue in regional distributor networks. Manufacturing gravity centers on Germany, China, and Brazil where BASF, Shandong fermentation clusters, and ANVISA-registered importers anchor production. Supply draws from citric acid fermentation feedstocks, propionic acid petrochemical streams, and mineral chelation precursors. Single-source vulnerability persists for encapsulated polymer coatings sourced from specialized chemical suppliers. Distribution runs through direct annual framework agreements with integrated processors in Southeast Asian contract farming zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork strategy compounds regulatory tailwinds for documented gut-health solutions, with EFSA authorization timelines creating durable competitive moats for dossier-capable suppliers.
For Market Incumbents: To counter enzyme-probiotic substitution in swine diets, deepen captive fermentation capacity for citric and fumaric acid precursors in Jiangsu and Lower Saxony. Lock multi-year supply agreements with Vietnamese and Indonesian processors retrofitting liquid dosing infrastructure. Certification investment under REACH authorization pathways for novel acidifier salts reinforces regulatory moats against emerging Asian compounders.
For New Entrants and Emerging Players: Enter via aquaculture premium positioning for shrimp and salmonid gut-health complexes where species-specific pH modulation requirements limit incumbent specialization. Target Thailand's integrated shrimp processors with encapsulated acid formulations embedded in grow-out contract terms. White-space exists in automated e-commerce reordering platforms for Southeast Asian contract farming zones with audit-compliant documentation.
For Investors and Strategic Acquirers: Roll-up economics work for specialized mineral-chelated acid blend formulators because ruminant gut pH modulation faces regulatory classification uncertainty between feed additive and veterinary medicinal product that constrains new entrant scale-up. Acquire targets with validated EFSA toxicological dossiers and established third-party residue monitoring certifications. Monitor ECHA substance evaluation requests for additional mammalian toxicology data as inflection indicator for development cycle extensions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive citric acid production insulates BASF against merchant market volatility in Ludwigshafen. |
| Encapsulation Technology Partnership | pH-responsive polymer coatings shift competitive advantage from bulk production to Wageningen formulation science. |
| Regulatory Dossier Expansion | EFSA authorization under Regulation 1831/2003 creates five-year development barriers for non-incumbents. |
| Liquid Dosing Infrastructure Retrofit | Automated systems in Vietnamese feed mills convert powder-dominant operations toward precision inclusion control. |
| Aquaculture Species-Specific Complex | Shrimp and salmonid formulations command premium multiples due to limited supplier specialization. |
Methodological Framework
Multiple input streams — regulatory filing databases, customs trade records, and processor procurement disclosures — were reconciled with primary interviews across the analysis window. Conversations with EFSA regulatory affairs leads, Dutch poultry integrator nutritionists, Shandong fermentation plant managers, Thai shrimp processor procurement heads, and Brazilian feed compounder technical directors informed demand-side validation. Secondary sources included EMA feed additive submissions, ANVISA import registration logs, GB standard compliance filings, and SEC 10-K disclosures from listed chemical-nutrition conglomerates. Bottom-up volume estimates by species and form were triangulated against top-down market sizing from trade flow analysis.
Cross-referencing historical authorization timelines against expert panel inputs anchored the projection framework across the modeling period. Segmentation dimensions modeled include acid type, physical form, end-use species, and distribution channel configuration. CAGRs were derived from weighted scenario analysis incorporating antibiotic-free production mandate adoption curves, automated dosing system penetration rates, and regulatory approval velocity differentials by jurisdiction. Industry-specific forecast inputs captured encapsulation technology adoption rates in Netherlands poultry operations and residue monitoring protocol tightening in Chinese contract farming zones.
Inputs from EFSA and FDA pre-submission meetings were available through the study window; gaps in emerging market regulatory enforcement data introduce uncertainty bands around Southeast Asian volume estimates. Forecasts reflect assumptions regarding Farm to Fork strategy implementation pace and processor contract standardization velocity. Practitioners should monitor ECHA substance evaluation backlog expansion and propionic acid feedstock price volatility for early signals of margin compression or development cycle extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Global Ester Gum Market
Additives
Crystal Growth Modifier Market
Additives
Marine Fuel Additives Market
Additives
Disodium Inosinate Market
Additives
Global Performance Additives Market
Additives
Gelatin Peptones Market
Additives
Adjustive Agents Market
Additives
Global Anti-Fog Additives Market
Additives
Antimicrobial Additives Market
Additives
Citric Acid Market
Additives
Spain Anti Caking Market
Additives
Global Sizing Agents Market
Additives
North America Fuel Additives Market
Additives
Calcium Stearate Market
Additives
Anti-Wear Additives Market