
 Engine Oil Additive Market | 2026-2036
Engine Oil Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Oil Additive Market Analysis
Heavy-duty equipment usage is hardening as the dominant demand vector for engine oil additives, displacing traditional passenger vehicle growth curves. Lubrizol Corporation leverages its backward integration into detergent chemistry to control raw material costs across North American supply chains. Infineum International Ltd anchors its position through R&D intensity focused on low-viscosity formulations for commercial fleets. Afton Chemical Corporation competes via specialized friction modifier portfolios tailored to emerging market OEM specifications.
Engine oil additives comprise chemically engineered compounds—typically organometallic detergents, polymeric dispersants, and molybdenum-based friction modifiers—blended at 5-25% treat rates into base oils to prevent deposit formation, reduce wear, and maintain viscosity stability across temperature extremes. Viscosity index improvers command the largest margin pool as OEMs mandate thinner lubricants for fuel economy compliance. Detergents and dispersants represent mature, high-volume categories where manufacturing scale determines cost position. Synthetic technology segments attract premium pricing as fleet operators prioritize extended drain intervals and cold-start protection.
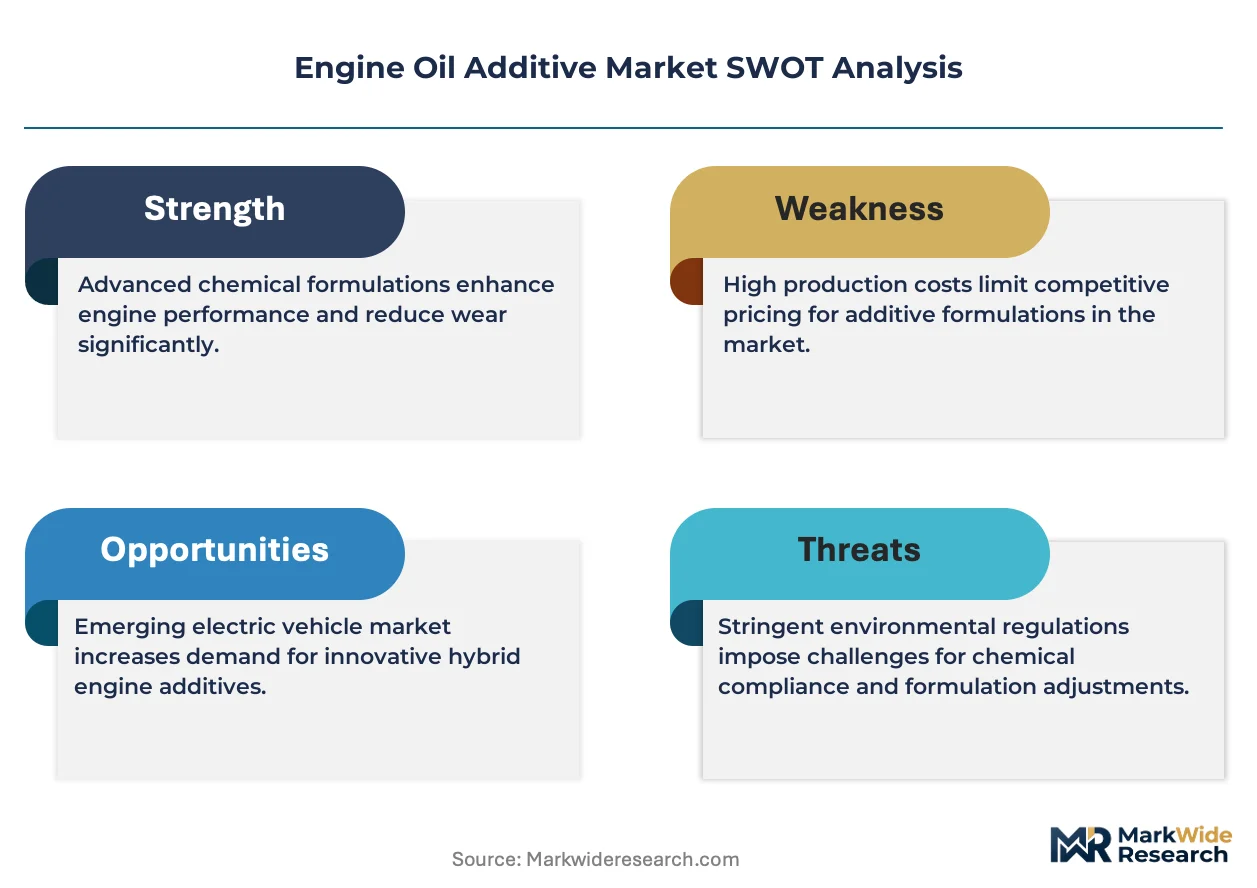
EPA emission standards and Euro VI regulations compel additive suppliers to reformulate for compatibility with exhaust aftertreatment systems, particularly low-SAPS (sulfated ash, phosphorus, sulfur) packages. China's MIIT enforces GB standards that increasingly mirror ACEA sequences, creating technical convergence pressures for multinational suppliers. India's BIS adoption of BS-VI norms accelerates local blending capacity investments. Stakeholders must monitor regulatory divergence between sulfur limits and ash caps as these specifications fragment formulation strategies across major automotive markets.
Market Dynamics
Low-SAPS formulation mandates from EPA and Euro VI are compressing additive treat rates while simultaneously elevating R&D intensity, forcing suppliers to reconcile performance loss with aftertreatment compatibility.
Growth Catalysts
- Commercial Fleet Electrification Lag:Extended service intervals for internal combustion engines in heavy-duty trucks sustain additive consumption as battery-electric penetration remains concentrated in light-duty segments.
- EPA Tier 4 and Euro VI Phase D:Tightened particulate and NOx limits compel OEMs to specify lower-viscosity oils with enhanced thermal stability, expanding demand for viscosity index improvers.
- China's GB 11122-2019 Alignment:Convergence with ACEA E sequences opens technical pathways for multinational additive suppliers to displace local blenders in premium commercial lubricant formulations.
Market Restraints
- Molybdenum Disulfide Price Volatility:Friction modifier costs fluctuate with mining output concentrated in Chile and Peru, compressing margins for mid-tier additive packages.
- Polyisobutylene Supply Concentration:Viscosity index improver feedstock production clusters in US Gulf Coast and Northwest European petrochemical corridors, exposing formulators to hurricane and refinery outage risks.
- Low-SAPS Performance Ceiling:Sulfated ash caps below 0.8% degrade detergent effectiveness in extended-drain applications, limiting market penetration in severe-service mining and construction equipment.
Strategic Opportunities
- India BS-VI Stage II Implementation:Tighter particulate limits for commercial vehicles create first-mover advantages for suppliers establishing local blending capacity ahead of 2027 enforcement.
- Synthetic Base Oil Convergence:Group III and Group IV base stocks enable additive packages optimized for cold-start protection in Nordic and Canadian Arctic fleet operations.
- Direct Fleet Procurement Models:Large logistics operators in Germany and the Netherlands are bypassing traditional distributors to negotiate additive specifications directly with formulators.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in organometallic detergent synthesis and tribology testing has contracted as petrochemical engineering programs pivot toward renewable energy curricula.
- OEM Approval Timeline Compression:ACEA and API sequence updates now cycle every 18-24 months, forcing additive houses to maintain parallel certification tracks with divergent test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Oil Additive Market |
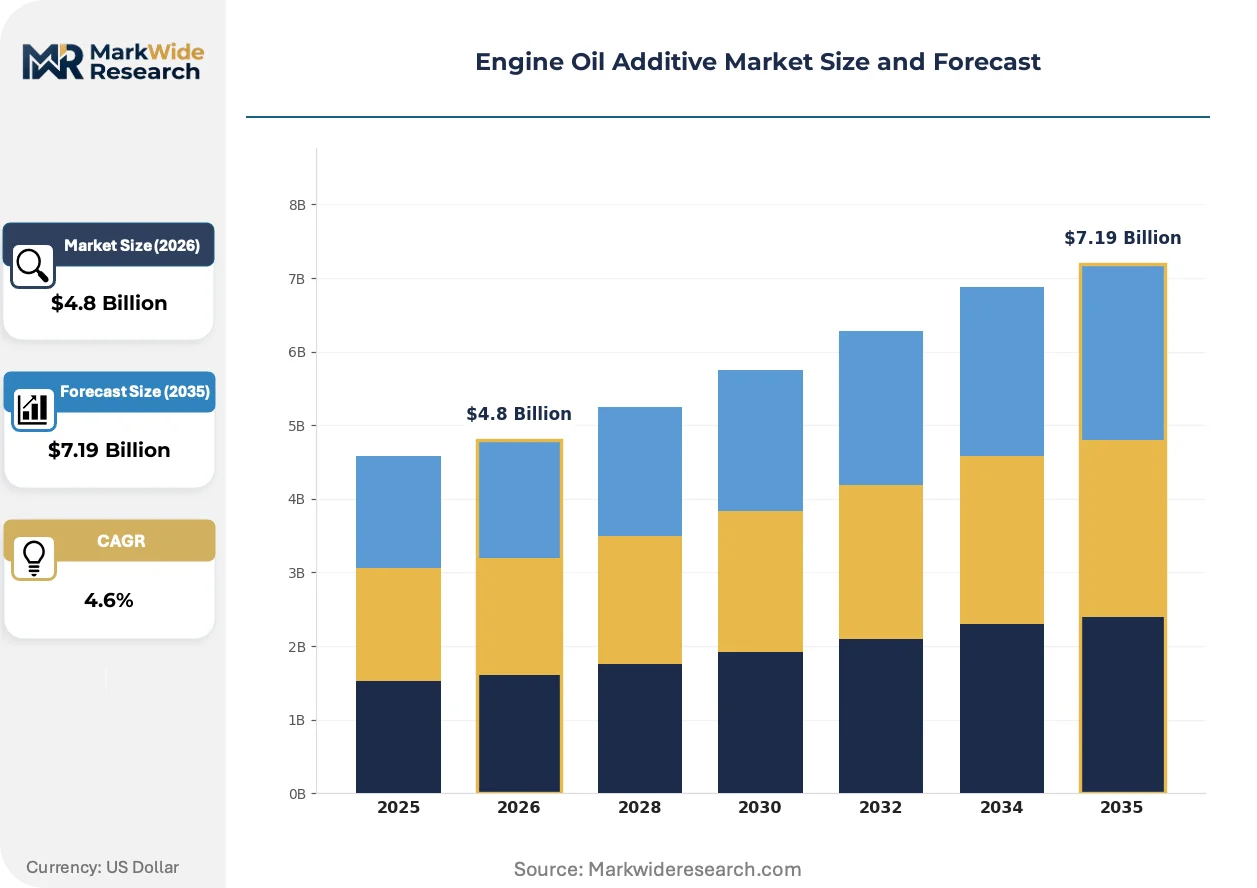
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Dispersants, Friction Modifiers, Viscosity Index Improvers End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Usage: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Equipment, Motorcycles Technology: Synthetic, Semi-Synthetic, Mineral, Bio-Based |
| Companies Covered | Lubrizol Corporation, Infineum International Ltd, Afton Chemical Corporation, BASF SE, Evonik Industries AG, Chevron Oronite Company LLC, LANXESS AG, Croda International Plc, Vanderbilt Chemicals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Oil Additive Market Emerging Trajectories
Additive chemistry is pivoting toward molecular architecture precision as binary performance trade-offs—deposit control versus aftertreatment protection—yield to multi-functional molecule design.
Boron-based friction modifiers are consolidating technical preference in passenger vehicle formulations seeking fuel economy credits under CAFE standards. Japanese and South Korean OEMs have accelerated qualification timelines for these chemistries, compressing adoption cycles from five years to eighteen months. The technology is consolidating supplier R&D roadmaps around single-molecule solutions that replace dual-component packages.
REACH Annex XVII restrictions on boron compounds in consumer applications are spilling into industrial lubricant classifications, forcing reformulation of legacy transmission and hydraulic fluids. ECHA's 2023 substance evaluation roadmap has flagged zinc dialkyldithiophosphate for additional scrutiny, elevating ashless phosphorus alternatives in European commercial vehicle specifications. German and French additive blenders are accelerating substitution programs to preempt authorization requirements.
Fleet maintenance departments are unbundling lubricant procurement from full-service leasing contracts, creating direct specification authority previously held by OEM captive finance arms. This shift concentrates buying power among top-ten logistics operators in the Netherlands, Belgium, and northern Italy. Channel disintermediation is most visible in long-haul trucking segments where total cost of ownership modeling has displaced brand loyalty in supplier selection criteria.
Engine Oil Additive Market Segmentation
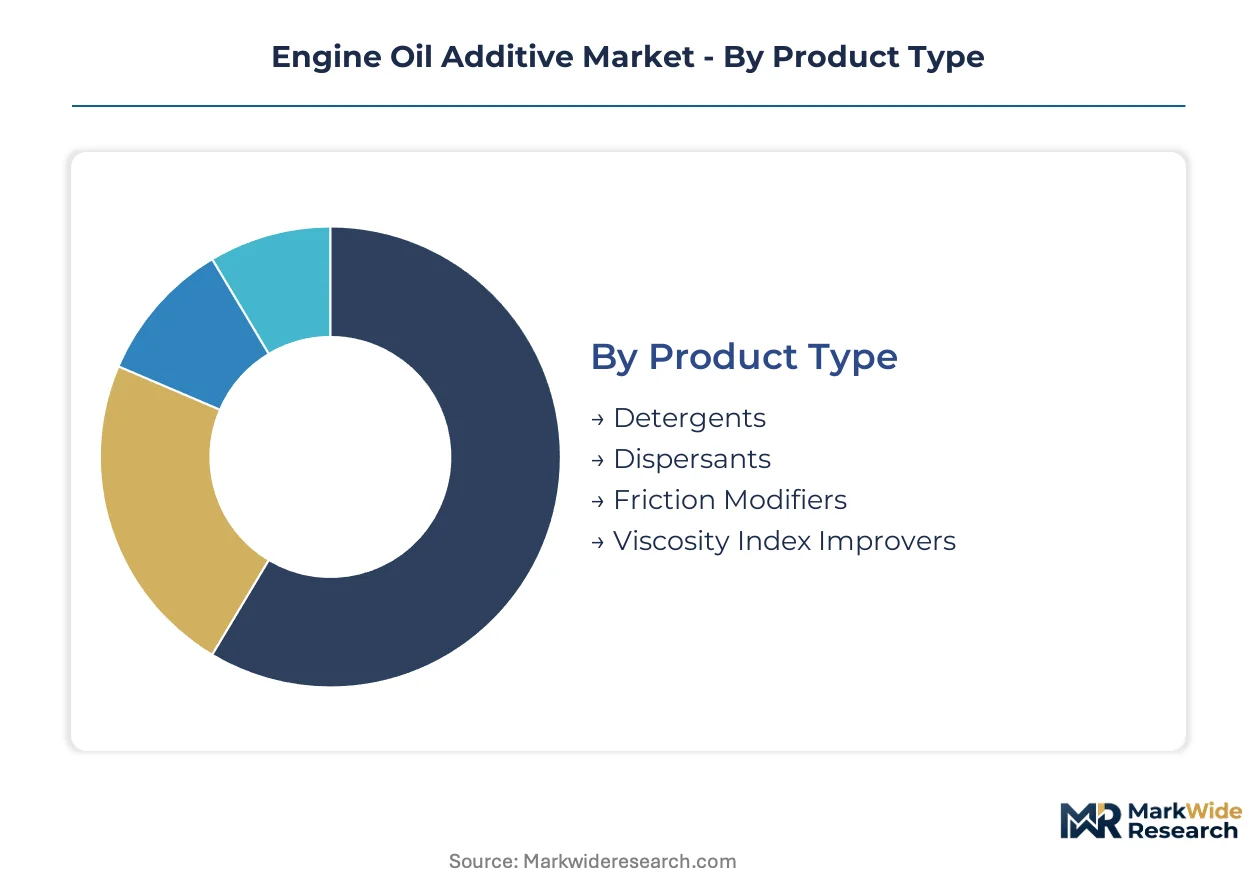
Additive chemistry heterogeneity demands granular segmentation to isolate margin drivers. Each axis—chemical function, customer procurement authority, equipment severity, and base oil compatibility—reveals distinct competitive dynamics and formulation requirements.
Product Type:
Technical specification hierarchies separate commodity detergents from precision-engineered friction modifiers, with treat rates and raw material intensity defining cost structures.
- Detergents:Organometallic calcium and magnesium sulfonates neutralize combustion acids and suspend deposits at treat rates of 3-8%. Fleet operators in China and India specify high-base-number variants for extended drain intervals in commercial diesel engines, though sulfated ash limits under Euro VI constrain formulation flexibility.
- Viscosity Index Improvers:Polymeric olefin copolymers and polymethacrylates expand lubricant viscosity range across temperature extremes. OEMs in Germany and the US mandate these additives for 0W-20 and 5W-30 grades that satisfy CAFE and EPA fuel economy targets, with premium pricing tied to shear stability performance.
- Dispersants:Polyisobutylene succinimides prevent soot agglomeration in diesel crankcase oils.
- Friction Modifiers:Molybdenum dithiocarbamates and organic borates reduce boundary friction in passenger vehicle formulations.
Viscosity Index Improvers leads on scale; Friction Modifiers leads on momentum.
End User:
Procurement authority concentration varies sharply across customer types, with fleet operators consolidating specification power faster than fragmented individual channels.
- Fleet Operators:Large logistics and mining companies in the Netherlands and Germany negotiate direct additive specifications with formulators, bypassing traditional distributors. Total cost of ownership modeling drives selection toward synthetic packages with 100,000-kilometer drain intervals, compressing mid-tier supplier margins.
- OEMs:Factory-fill agreements with lubricant blenders lock in additive chemistry years ahead of production ramp. Ford, Volkswagen, and Toyota qualify specific additive packages through ACEA and proprietary sequences, creating certification barriers that protect incumbent suppliers.
- Aftermarket Providers:Independent distributors and service chains purchase packaged additive systems for bulk blending.
- Individual Consumers:Retail quart and gallon purchases through automotive supply chains exhibit extreme price sensitivity.
Fleet Operators concentrates buying power fastest; OEMs maintains the deepest technical lock-in.
Usage:
Equipment duty cycles and operating environments dictate additive treat rates, with severe-service applications demanding enhanced thermal stability and deposit control.
- Heavy-Duty Equipment:Mining trucks, construction machinery, and agricultural equipment operate under sustained high-load conditions with intermittent cold starts. Operators in Brazil and Australia specify high-detergent, high-dispersant packages at 12-18% treat rates to manage soot loading and acid neutralization across 500-hour service intervals.
- Commercial Vehicles:Long-haul trucking fleets in the US and Europe drive demand for low-SAPS formulations compatible with diesel particulate filters and selective catalytic reduction systems. Extended drain programs at 150,000 kilometers require antioxidant and antiwear chemistry optimized for Group III base stocks.
- Passenger Vehicles:Light-duty gasoline and diesel engines prioritize fuel economy through low-viscosity lubricants.
- Motorcycles:Wet clutch compatibility constraints limit friction modifier selection in two-wheeler formulations.
Heavy-Duty Equipment commands the highest treat rates; Commercial Vehicles shows the steepest expansion trajectory.
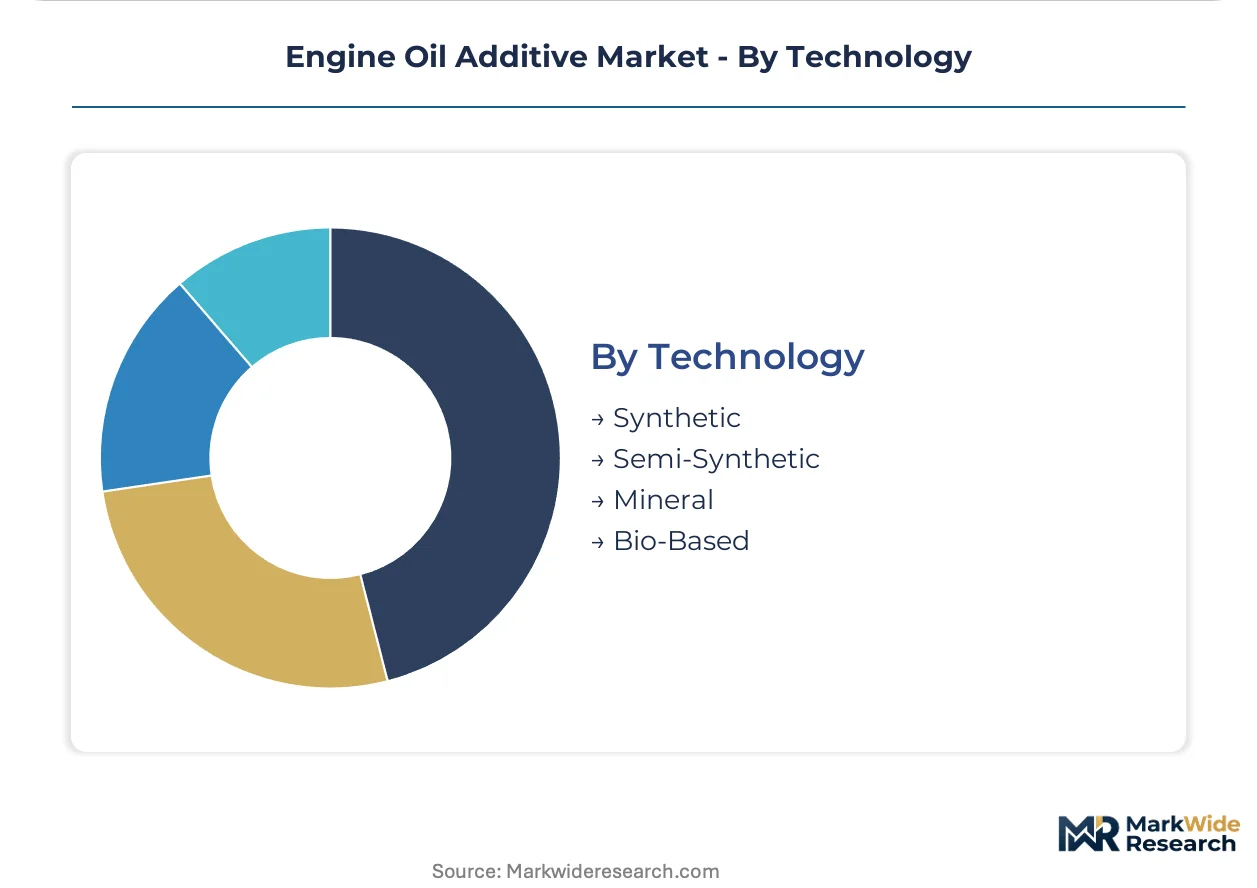
Technology:
Base oil quality tiers cascade into additive package design, with synthetic and bio-based segments requiring specialized solubility and compatibility engineering.
- Synthetic:Group III, Group IV (PAO), and Group V (ester) base stocks enable additive chemistries optimized for thermal oxidative stability and cold-crank viscosity. Arctic fleet operators in Canada and Nordic countries specify synthetic packages for -40°C pumpability, with additive suppliers reformulating dispersant polarity for ester compatibility.
- Semi-Synthetic:Group II-plus and Group III blends dominate mid-tier commercial lubricants in India and Southeast Asia.
- Mineral:Group I and Group II base stocks retain volume in emerging market price-sensitive segments.
- Bio-Based:Vegetable oil and synthetic ester feedstocks from rapeseed and palm sources attract regulatory preference under EU Green Deal procurement guidelines.
Synthetic dominates value capture; Bio-Based gains share fastest on regulatory preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing additive formulation capacity toward jurisdictions with converging emission standards but divergent enforcement costs. Suppliers are relocating blending operations to exploit technical equivalence between EPA Tier 4, Euro VI, and China's GB standards while minimizing compliance overhead.
United States
Heavy-duty fleet electrification lag sustains additive demand for Class 8 trucks operating on 15W-40 and 10W-30 formulations. EPA Tier 4 Final and upcoming Phase 2 greenhouse gas rules compel low-SAPS packages compatible with diesel particulate filters. The Houston Ship Channel petrochemical corridor concentrates polyisobutylene feedstock production for viscosity index improvers, exposing formulators to hurricane-season supply disruptions.
Germany
Commercial logistics operators in the Rhine-Ruhr and Baden-Württemberg regions negotiate direct additive specifications, bypassing traditional distributors. KBA enforcement of Euro VI Phase D particulate limits drives 0W-20 and 5W-30 adoption for fuel economy compliance. The Ludwigshafen chemical cluster anchors European detergent and dispersant manufacturing, with integrated producers controlling backward positions in calcium sulfonate chemistry.
China
MIIT's GB 11122-2019 alignment with ACEA E sequences opens technical pathways for multinational suppliers to displace local blenders in premium commercial lubricants. Extended drain intervals for mining trucks in Inner Mongolia and Shanxi Province drive high-treat-rate packages. The Yangtze River Delta blending corridor concentrates domestic additive capacity, though quality tiering separates state-owned from foreign-invested producers.
India
BIS adoption of BS-VI norms accelerates local blending investments ahead of Stage II particulate tightening in 2027. Commercial vehicle parc expansion in Maharashtra and Gujarat sustains demand for high-base-number detergents in severe-service applications. The Chennai-Ennore petrochemical belt is emerging as a regional hub for polymeric dispersant manufacturing serving Southeast Asian export markets.
Brazil
Agricultural and mining equipment operators in Minas Gerais and Mato Grosso specify elevated treat rates for acid neutralization in high-sulfur diesel environments. ANVISA-aligned environmental regulations are tightening lubricant disposal protocols, indirectly favoring extended-drain synthetic formulations. The São Paulo-Guarulhos industrial corridor hosts blending capacity serving Mercosur's commercial vehicle aftermarket.
Engine Oil Additive Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated compounders commanding factory-fill agreements while toll blenders serve fragmented aftermarket channels. The supplier base concentrates around three strategic tiers: petrochemical majors with captive detergent chemistry, independent additive houses with R&D-intensive friction modifier portfolios, and regional blenders competing on logistics proximity. Consolidation pressures favor backward integration into raw material production and direct procurement relationships with fleet operators.
Within the integrated chemistry tier, Lubrizol Corporation exemplifies petrochemical-backed scale advantages through its position in detergent synthesis. Infineum International Ltd and Afton Chemical Corporation occupy positions as independent specialists with concentrated R&D footprints in low-viscosity and friction-modifier formulations respectively. These three anchors represent divergent competitive models: captive raw material control versus formulation-intensive service models versus OEM specification tailoring.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Infineum International Ltd |
| Afton Chemical Corporation |
| BASF SE |
| Evonik Industries AG |
| Chevron Oronite Company LLC |
| LANXESS AG |
| Croda International Plc |
| Vanderbilt Chemicals LLC |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 and Euro VI low-SAPS mandates gate qualified additive supply and premium-tier pricing access, as only backward-integrated compounders with detergent chemistry control can meet ash caps below 0.8% while maintaining extended-drain performance. Fleet operators in Germany and the Netherlands now demand direct procurement contracts that compress distributor margins and shift pricing power toward formulators with captive raw material positions.
Pricing Analysis
Distributor margin compression runs through European commercial lubricant channels as large logistics operators negotiate direct additive specifications with Lubrizol and Infineum. Three-tier pricing structure across premium synthetic, standard mineral, and economy blended packages separates factory-fill OEM agreements from aftermarket quart sales. Pricing pressure stems from molybdenum disulfide feedstock volatility concentrated in Chilean mining output. Individual retail consumers exhibit extreme price sensitivity, while fleet operators prioritize total cost of ownership over per-liter expenditure.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs mandate multi-supplier qualification for detergent and viscosity index improver feedstocks, preventing single-source dependence despite concentration. Polyisobutylene production clusters in the US Gulf Coast and Northwest European petrochemical corridors, with organometallic detergent synthesis anchored in Ludwigshafen and Houston. Supply chain risk centers on hurricane-season disruptions to viscosity modifier feedstock availability. Distribution runs through integrated compounders for factory-fill, toll blenders for regional aftermarket, and direct procurement for top-ten fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as heavy-duty fleet electrification lag extends internal combustion service intervals, shifting demand toward premium synthetic formulations with 100,000-kilometer drain capabilities.
For Market Incumbents: Extend backward integration into calcium sulfonate detergent chemistry to defend margin position against molybdenum price volatility and emerging local blenders in India. Lock in direct procurement relationships with Rhine-Ruhr logistics operators before channel disintermediation accelerates. Prioritize R&D intensity in low-SAPS formulations compatible with BS-VI Stage II enforcement.
For New Entrants and Emerging Players: Begin with specialized friction modifier portfolios targeting Japanese and South Korean OEM qualification timelines for boron-based fuel economy chemistries. White-space exists in bio-based additive packages for EU Green Deal procurement guidelines, with Nordic Arctic fleet operators seeking cold-crank viscosity solutions. Pursue toll-blending partnerships with established compounders to bypass ACEA certification barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional toll blenders with logistics proximity to Brazil's agricultural equipment operators because fleet unbundling of lubricant procurement concentrates buying power among operators seeking local specification authority. Five-to-ten year viability hinges on synthetic base oil convergence enabling premium additive packages. Monitor India's BS-VI Stage II enforcement timeline as inflection indicator for local blending capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detergent Chemistry | Captive calcium sulfonate production insulates Lubrizol from raw material cost swings in North American supply chains. |
| Direct Fleet Procurement Contracts | Bypassing distributors concentrates specification authority with German logistics operators pursuing total cost of ownership models. |
| Low-SAPS Formulation Certification | ACEA and API sequence alignment enables aftermarket penetration in Euro VI and EPA Tier 4 compliant commercial vehicles. |
| Synthetic Base Oil Convergence | Group III and Group IV compatibility opens Arctic fleet segments in Canada requiring -40°C pumpability specifications. |
| Local Blending Capacity Investment | Chennai-Ennore hub construction serves India BS-VI demand and Southeast Asian polymeric dispersant export markets. |
Methodological Framework
Direct dialogue with additive formulators, fleet procurement directors, OEM lubricant specification engineers, and petrochemical plant managers grounded qualitative findings, cross-referenced with customs trade data, ACEA oil sequence documentation, SEC filings from integrated compounders, and MIIT GB standard releases. Bottom-up and top-down triangulation validated volume estimates across detergent, dispersant, and friction modifier chemistry segments.
Bottom-up modeling anchored projections in treat rate assumptions by equipment severity class and base oil technology tier, while top-down verification checked aggregate consumption against commercial vehicle parc expansion and mining equipment utilization rates across Brazil, Australia, and China's Inner Mongolia province. CAGRs were derived from regression analysis of historical additive consumption intensity correlated with extended drain interval adoption patterns.
Several conditions sit outside the modeled scope, including breakthrough battery-electric heavy-duty truck penetration rates, REACH authorization requirements for zinc dialkyldithiophosphate alternatives, and geopolitical disruption to Chilean molybdenum concentrate exports. Deviation in fleet electrification timelines or low-SAPS performance ceiling constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Silicone Additives Market
Additives
Crystal Growth Modifier Market
Additives
China Sodium Reduction Ingredient Market
Additives
Defoaming Coating Additives Market
Additives
Saudi Arabia Feed Additives Market
Additives
Global Slip Additives Market
Additives
Tocopheryl Acetate Market
Additives
Middle East Lubricant Additives Market
Additives
Impact Modifier Market
Additives
Liquid Thickeners Market
Additives
Fluoropolymer Additives Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Global Feed Acidulants Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Grease Additives Market