
 Global Hindered Amine Light Stabilizers Market | 2026-2036
Global Hindered Amine Light Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
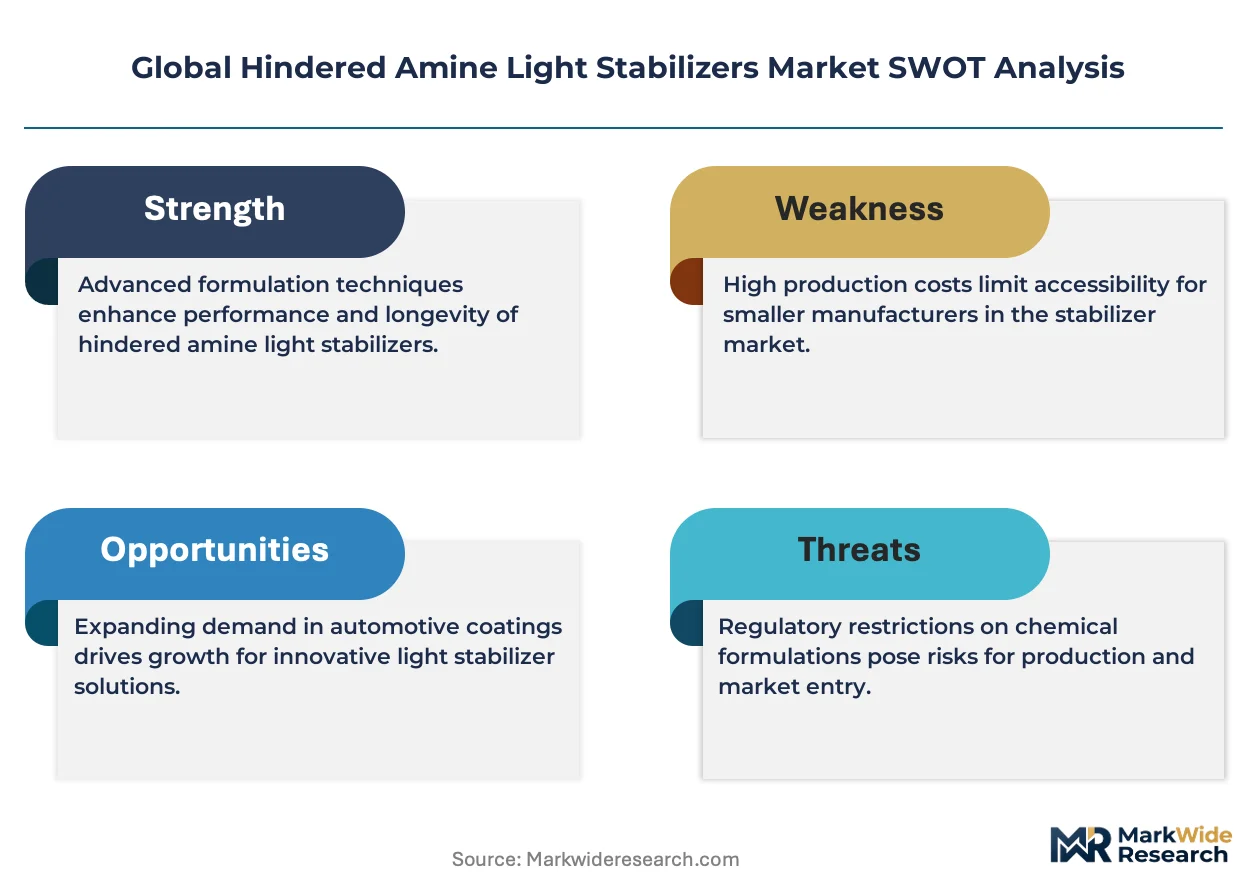
Global Hindered Amine Light Stabilizers Market Analysis
Modular additive packages is decoupling procurement decisions from traditional bundled polymer systems, forcing buyers to evaluate hindered amine light stabilizers as standalone performance inputs. BASF SE leverages its integrated polymer science portfolio to anchor long-term supply relationships with tier-one compounders. Songwon Industrial Co., Ltd. competes through specialized photostabilization technology leadership in Asia-Pacific manufacturing hubs. SABO S.p.A. differentiates via backward integration into key intermediates, sustaining margin control across volatile raw material cycles.
Hindered amine light stabilizers are nitrogen-containing organic compounds, typically based on 2,2,6,6-tetramethylpiperidine derivatives, that function by scavenging free radicals generated during UV-induced polymer degradation to extend material service life. Polymeric grades dominate volume demand in automotive and construction films where migration resistance and long-term thermal stability prove critical. Low molecular weight variants retain cost advantages in short-lifecycle packaging applications, though biodegradable technology segments are gaining formulation share as sustainability mandates intensify across European and North American supply chains.
REACH registration requirements and RoHS substance restrictions in Europe, alongside EPA chemical management frameworks in the United States, collectively elevate compliance costs while accelerating substitution toward next-generation stabilizer chemistries. China's GB standards and evolving MEE environmental enforcement are reshaping local production specifications and export qualification protocols. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and secure dual-registered product portfolios before compliance deadlines phase in.
Market Dynamics
Modular additive procurement is decoupling hindered amine light stabilizers from bundled polymer systems, forcing compounders to evaluate photostabilizers as standalone performance inputs rather than embedded cost centers.
Growth Catalysts
- Automotive exterior coatings:Electrification trends extend vehicle lifecycles, intensifying UV protection requirements for polycarbonate headlamp housings and body panels across German and Japanese manufacturing clusters.
- REACH substance registration:Compliance deadlines for high-volume stabilizer intermediates are accelerating reformulation toward polymeric grades with superior migration resistance in construction films.
- China GB standard harmonization:Evolving MEE environmental enforcement protocols are qualifying domestic producers for export-grade polymer stabilizer production, expanding qualified supply base availability.
Market Restraints
- 2,2,6,6-tetramethylpiperidine feedstock volatility:Acetone and ammonia price swings compress margin predictability for low molecular weight stabilizer producers without captive intermediate supply.
- European supply concentration:REACH-registered polymeric HALS production clusters heavily in Germany and Italy, creating geographic single-source exposure for North American compounders seeking EU-qualified material.
- Biodegradable polymer incompatibility:Conventional nitroxyl radical scavenging mechanisms degrade PLA and PHA chain integrity, limiting addressable market in compostable packaging segments.
Strategic Opportunities
- India automotive compounding:PLI scheme incentives for domestic polymer processing are creating qualified demand for UV stabilizer technical support and localized blending operations.
- Agrivoltaic film applications:Dual-use solar greenhouse installations require 20-25 year weathering guarantees, opening specification opportunities for high-performance stabilizer packages.
- EU Green Deal circularity mandates:Design-for-recycling requirements favor stabilizer chemistries compatible with mechanical reprocessing streams, rewarding reformulation investment with preferential procurement status.
Industry Challenges
- Dual-registration compliance timelines:Simultaneous EPA TSCA and REACH dossier preparation strains regulatory affairs capacity at mid-size stabilizer producers, delaying market entry.
- Photostabilization-mechanism skill scarcity:Nitroxyl radical chemistry expertise concentrates among senior formulators approaching retirement, constraining technical service expansion.
- Legacy compounding equipment integration:High-viscosity polymeric HALS grades require modified extrusion parameters, complicating retrofit adoption at established automotive tier-one processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hindered Amine Light Stabilizers Market |
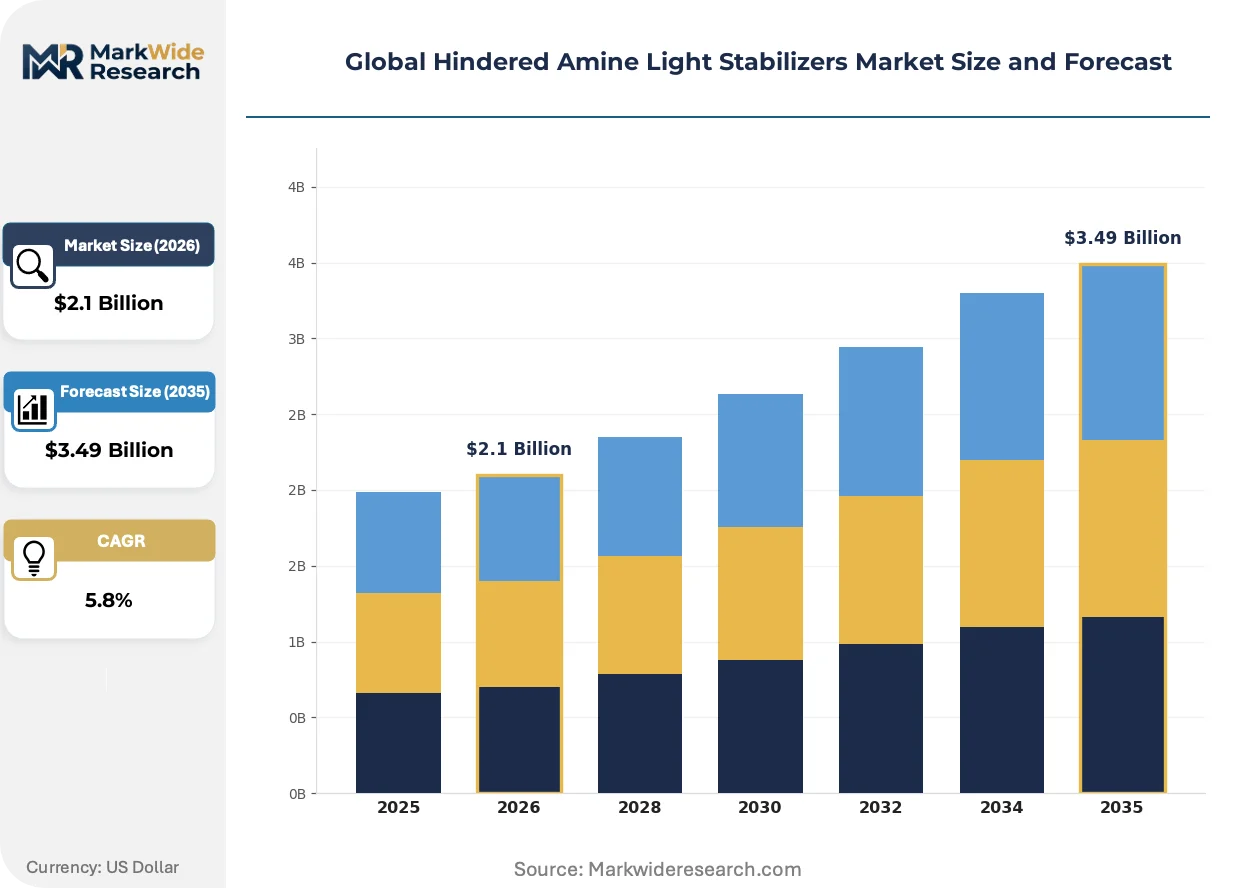
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
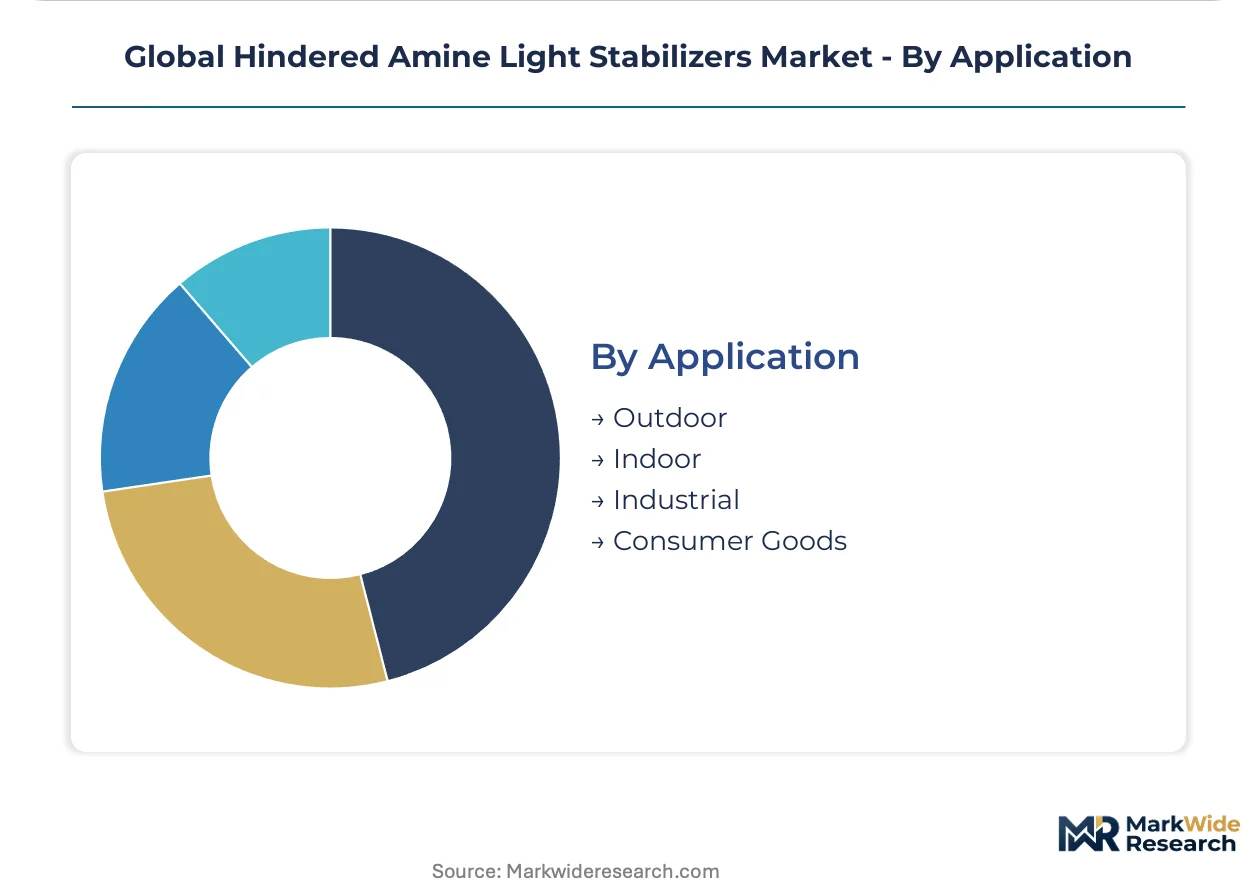
| Segmentation | Product Type: Polymeric, Low Molecular Weight, Plastic Additives, Coatings End User: Automotive, Construction, Electronics, Packaging Technology: Biodegradable, Non-Biodegradable, UV Stabilization, Photostabilization Application: Outdoor, Indoor, Industrial, Consumer Goods |
| Companies Covered | BASF SE, ADEKA Corporation, SABO S.p.A., Solvay, SI Group, Rianlon Corporation, Clariant, Arkema, Songwon Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hindered Amine Light Stabilizers Market Emerging Trajectories
Reactive HALS grafting technologies are displacing conventional physical blending approaches, enabling covalent attachment to polymer backbones and eliminating migration-driven performance decay in long-service applications.
Polymeric hindered amine architectures is overtaking oligomeric alternatives in automotive specification sheets. These macromolecular stabilizers form permanent network structures within polycarbonate and polyamide matrices. Tier-one German and Japanese automakers now mandate polymeric grades for exterior lighting and mirror housings. The shift is compressing demand for conventional low molecular weight variants in 10-15 year lifecycle applications.
REACH authorization list expansion is forcing substitution timelines for certain phenolic antioxidant co-stabilizers. ECHA's 2024-2025 candidate list reviews specifically target substances used in agricultural film formulations. Compounders serving French and Italian greenhouse operators are accelerating NOR HALS and hydroxyphenylbenzotriazole hybrid package validation to maintain market access.
Compounders in China and India increasingly specify stabilizer packages through direct technical partnerships rather than distributor intermediaries. BASF and Songwon field application teams now embed with major polymer processors in Shanghai and Mumbai to co-develop film and coating formulations. This channel compression concentrates procurement influence among technical-qualified buyers and marginalizes traditional trading house relationships in high-volume segments.
Global Hindered Amine Light Stabilizers Market Segmentation
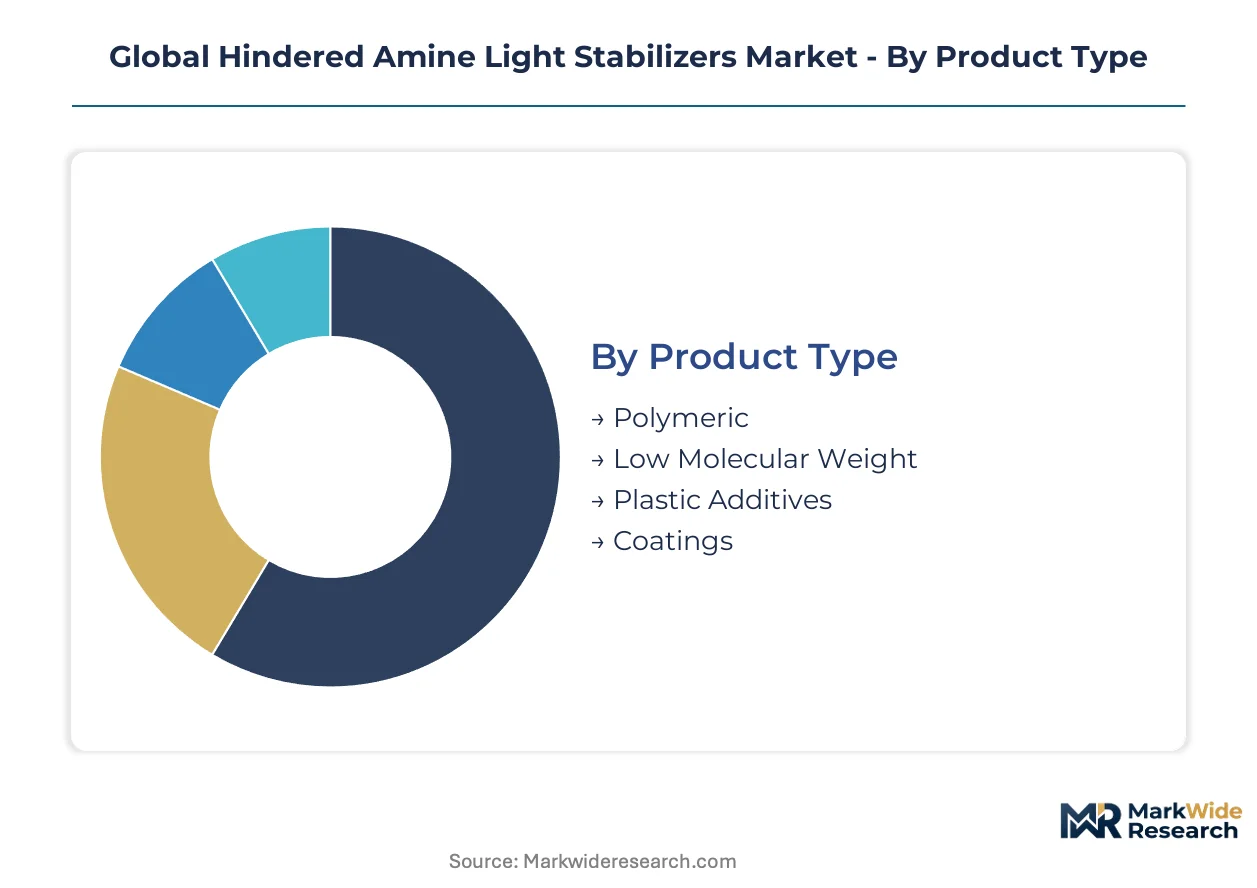
Hindered amine light stabilizers serve divergent performance requirements across polymer systems, coating chemistries, and lifecycle expectations. Segmentation reveals where formulation complexity, regulatory burden, and technical service intensity concentrate margin capture.
Product Type:
Capital intensity varies sharply across production routes, with polymeric grades demanding multi-reactor continuous systems while low molecular weight variants run on batch infrastructure with lower fixed asset thresholds.
- Polymeric:These macromolecular architectures incorporate 2,2,6,6-tetramethylpiperidine units into oligomeric or polymeric backbones, delivering permanent network integration and zero migration in polycarbonate automotive lighting housings. German and Japanese OEMs now mandate polymeric HALS for exterior applications exceeding 10-year service life, compressing specification windows for conventional alternatives.
- Low Molecular Weight:Monomeric and dimeric piperidine derivatives offer cost positioning in short-lifecycle packaging films where extraction limits are less stringent. Volatility in acetone and ammonia feedstock costs erodes margin predictability for producers lacking captive intermediate supply.
- Plastic Additives:Masterbatch concentrates and direct polymer compounding grades dominate volume throughput in extrusion operations across Chinese and Indian processing hubs.
- Coatings:Solvent-borne and water-dispersible formulations serve automotive clearcoat and industrial maintenance applications with specialized rheology requirements.
Polymeric grades absorb the bulk of installed capacity; plastic additives are expanding most quickly.
End User:
Customer concentration patterns separate segments with consolidated procurement functions from fragmented specification environments.
- Automotive:Electrification extends vehicle design lifecycles to 15-20 years, intensifying UV protection requirements for polycarbonate headlamp housings, body panels, and interior trim across German and Japanese manufacturing clusters. Tier-one compounders now embed technical teams directly with OEM formulation labs.
- Construction:Roofing membranes, geomembranes, and window profiles require 20-25 year weathering guarantees, favoring high-performance stabilizer packages with NOR HALS hybridization for agricultural greenhouse films in France and Italy.
- Electronics:Miniaturized device housings and display components demand thermal stability alongside photostabilization in polycarbonate and polyamide matrices.
- Packaging:Food-contact compliance and migration limits constrain stabilizer selection in flexible and rigid packaging segments, with biodegradable polymer incompatibility limiting addressable market in compostable formats.
Automotive commands the highest technical service intensity; construction is climbing the fastest on agrivoltaic and infrastructure investment cycles.
Technology:
Intellectual property density and regulatory qualification burden differentiate technology platforms, with biodegradable routes requiring novel mechanistic approaches.
- Biodegradable:Next-generation stabilizers compatible with PLA and PHA matrices avoid nitroxyl radical mechanisms that degrade chain integrity in compostable polymers. ECHA authorization timelines for conventional co-stabilizers accelerate substitution investment.
- Non-Biodegradable:Conventional radical scavenging chemistry retains cost advantage in fossil-based polymer systems with established performance validation.
- UV Stabilization:Hydroxyphenylbenzotriazole and benzophenone absorber combinations with HALS synergists dominate outdoor durability specifications.
- Photostabilization:Reactive grafting technologies enable covalent attachment to polymer backbones, eliminating migration-driven performance decay in long-service applications.
Non-biodegradable platforms retain volume dominance; biodegradable routes are gaining share fastest on EU Green Deal circularity mandates.
Application:
Environmental exposure severity and performance warranty terms segment application requirements across installation environments.
- Outdoor:Solar radiation, moisture, and thermal cycling demand maximum stabilizer loading in agricultural films, automotive exterior components, and building materials. Agrivoltaic dual-use installations require 20-25 year weathering guarantees.
- Indoor:Fluorescent and LED artificial light exposure drives stabilizer demand in display housings, interior automotive trim, and architectural applications with indirect window exposure.
- Industrial:Chemical process equipment, storage tanks, and piping systems combine UV exposure with aggressive chemical environments.
- Consumer Goods:Furniture, sporting equipment, and household products balance cost sensitivity with aesthetic durability requirements.
Outdoor applications concentrate premium formulation value; indoor segments are expanding most quickly on electronics and automotive interior specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free-Trade Zone incentives concentrate polymer additive technical operations for multinational suppliers serving Asia-Pacific automotive and construction demand.
Germany
Automotive electrification extends vehicle design lifecycles to 15-20 years, intensifying UV protection specifications for polycarbonate headlamp housings. REACH registration deadlines for high-volume stabilizer intermediates accelerate reformulation toward polymeric grades. The Rhine-Ruhr industrial corridor hosts concentrated compounding operations serving BMW, Mercedes-Benz, and Volkswagen formulation labs.
China
Domestic automotive production and agrivoltaic greenhouse installations drive specification demand for 20-25 year weathering guarantees. MEE environmental enforcement protocols under evolving GB standards qualify local producers for export-grade polymer stabilizer production. Yangtze River Delta processing hubs in Jiangsu and Zhejiang provinces anchor technical service teams from global suppliers.
United States
EPA TSCA chemical management frameworks elevate compliance costs while accelerating substitution toward next-generation stabilizer chemistries. Infrastructure investment cycles support construction film and roofing membrane demand requiring long-term thermal stability. Gulf Coast petrochemical corridors sustain captive intermediate supply for integrated HALS producers.
India
PLI scheme incentives for domestic polymer processing create qualified demand for UV stabilizer technical support and localized blending operations. BIS certification requirements reshape import qualification protocols for construction and automotive applications. Maharashtra and Gujarat industrial zones concentrate new extrusion and compounding capacity.
Japan
METI carbon neutrality roadmaps pressure polymer processors toward design-for-recycling specifications favoring stabilizer chemistries compatible with mechanical reprocessing streams. JIS standards govern automotive exterior component durability requirements. Kansai manufacturing clusters around Osaka maintain precision compounding operations for tier-one automotive suppliers.
Global Hindered Amine Light Stabilizers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base organizes around three strategic archetypes: integrated chemical majors with captive intermediate supply, regional specialists leveraging technical service proximity, and emerging Asian producers competing on cost-positioning. Dominant competitive moves include backward integration into 2,2,6,6-tetramethylpiperidine intermediates and direct technical partnerships with tier-one compounders displacing distributor channels.
Within the integrated chemical major tier, BASF SE anchors long-term supply relationships through polymer science portfolio breadth. Songwon Industrial Co., Ltd. exemplifies Asia-Pacific technical specialization with embedded application teams in Shanghai and Mumbai. SABO S.p.A. occupies a position sustained by backward integration into key intermediates, enabling margin control across volatile raw material cycles.
| Leading Market Players |
|---|
| BASF SE |
| ADEKA Corporation |
| SABO S.p.A. |
| Solvay |
| SI Group |
| Rianlon Corporation |
| Clariant |
| Arkema |
| Songwon Industrial Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Tier-one automotive compounders in Germany and Japan concentrate procurement influence through direct technical partnerships, anchoring contract-based long-term offtake agreements that trade price certainty for specification loyalty. This buyer consolidation rewards REACH-registered polymeric HALS producers with pricing power while squeezing spot-market traders serving fragmented packaging segments.
Pricing Analysis
Short lead-time premiums of 15-20% apply to emergency orders from automotive tier-one processors facing line-down risks, while spot inventory discounts attract cost-sensitive Chinese packaging converters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with REACH-registered polymeric grades commanding sustained premiums over low molecular weight alternatives. Pricing pressure stems from acetone and ammonia feedstock volatility compressing margins for non-integrated producers. Packaging compounders exhibit highest price sensitivity, while German OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
REACH registration and EPA TSCA qualification gates restrict qualified supply to producers with dossier completion, concentrating production in Germany, Italy, and China. Feedstock dependencies center on acetone, ammonia, and 2,2,6,6-tetramethylpiperidine intermediates sourced from Gulf Coast and Rhine-Ruhr petrochemical corridors. Single-source vulnerability concentrates in European polymeric HALS clusters serving North American automotive qualification requirements. Distribution runs through direct technical partnerships displacing traditional distributor channels in high-volume Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as reactive HALS grafting technologies displace conventional physical blending approaches, forcing legacy producers to retool or cede long-service applications.
For Market Incumbents: Deepen backward integration into 2,2,6,6-tetramethylpiperidine intermediates to insulate margins from acetone and ammonia volatility. Lock in dual-registration compliance for EPA TSCA and REACH dossiers before candidate list expansion accelerates substitution timelines. Prioritize technical service embedding with tier-one automotive compounders to defend channel position against emerging Asian cost competitors. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian automotive compounding offers white-space entry for BIS-certified producers with localized blending operations. Target agrivoltaic film specifications requiring 20-25 year weathering guarantees where technical validation barriers exceed incumbent cost advantages. Pursue direct technical partnerships with Maharashtra and Gujarat polymer processors to bypass established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size European producers with captive intermediate supply and REACH registration assets in Germany and Italy. Five-to-ten year viability hinges on biodegradable HALS compatibility development for EU Green Deal circularity mandates. Watch ECHA authorization list expansion as the inflection signal for phenolic antioxidant co-stabilizer substitution investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piperidine Intermediates | Captive acetone and ammonia supply insulates margin from feedstock volatility cycles. |
| REACH-EPA Dual Registration Investment | Dual-registered portfolios secure access to German automotive and US construction demand pools. |
| Reactive Grafting Technology Deployment | Covalent attachment eliminates migration-driven performance decay in polycarbonate automotive lighting. |
| India Technical Service Localization | Embedded application teams in Maharashtra capture PLI scheme polymer processing incentives. |
| Biodegradable HALS R&D Partnership | PLA and PHA compatibility opens EU compostable packaging segments closed to conventional nitroxyl chemistry. |
Methodological Framework
Independent corroboration across regulatory filings, customs trade data, and plant-level production disclosures underwrites the qualitative findings in this study. Primary interviews with HALS plant managers, automotive tier-one procurement leads, and polymer compounding technical directors combined with secondary validation from ECHA registration databases, EPA TSCA submissions, and ACC industry reports. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across product grades and end-use applications.
Comparable-period anchoring to historical automotive production cycles and construction investment waves grounds the projection framework across the analysis window. Segmentation dimensions modeled include product architecture (polymeric versus low molecular weight), end-use industry concentration (automotive, construction, packaging, electronics), and regional regulatory cluster alignment. CAGRs derive from fitted growth curves calibrated to OEM specification timelines and MEE enforcement protocol evolution in China. Feedstock cost indices and REACH registration completion rates serve as industry-specific forecast inputs.
Underlying measurement precision varies by segment; polymeric HALS automotive specifications carry tighter precision than fragmented packaging grades due to consolidated buyer disclosure. Forecasts reflect assumptions about electrification-driven vehicle lifecycle extension and EU Green Deal circularity mandate implementation pace. A model refresh is warranted upon material change in ECHA authorization list expansion timing or MEE environmental enforcement intensity in Chinese processing hubs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Benzoates Market
Additives
Defoaming Coating Additives Market
Additives
Global Isononanoic Acid Market
Additives
Global PVC Additives Market
Additives
South America Concrete Admixtures Market
Additives
Global UV Absorbers Market
Additives
Tricalcium Citrate Market
Additives
Isobutyl Acetate Market
Additives
Thermal Conductive Additives Market
Additives
Antiblock Agents Market
Additives
Hexyl Acetate Market
Additives
High Performing Matting Agents Market
Additives
Global Sizing Agents Market
Additives
Europe Anti-Caking Market
Additives
Phthalate Plasticizer Market
Additives
Antimicrobial Ingredients Market