
 Global Sodium Metabisulphite Market | 2026-2036
Global Sodium Metabisulphite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Metabisulphite Market Foresight
Potassium metabisulphite is recalibrating product economics across beverage preservation segments as wineries and breweries evaluate cost-performance tradeoffs. BASF SE leverages backward integration into sulphur chemistry to sustain margin control across European supply chains. Aditya Birla Chemicals anchors South Asian production capacity through captive chlor-alkali feedstock access. Esseco USA specializes in food-grade certification protocols that differentiate its position against commodity imports.
Sodium metabisulphite is an inorganic sodium salt of disulphurous acid, commercially available as white crystalline powder or flakes with minimum assay specifications typically exceeding 97% Na2S2O5 and sulphur dioxide release upon acidification serving as its functional mechanism. The compound functions primarily as an oxygen scavenger, antimicrobial agent, and reducing bleach across industrial and food systems. Powder and flake formulations dominate volume flows, with powder commanding premium pricing in pharmaceutical and food applications where dissolution kinetics matter. Water treatment and food preservatives represent the fastest-expanding application clusters, while pulp and paper constitutes a mature demand pool with limited growth upside. Mining firms and beverage producers concentrate the highest-margin end-user segments due to stringent purity requirements and contractual volume commitments.
EPA standards for sulphur dioxide emissions in US chemical manufacturing shape process technology investments and product qualification thresholds. REACH registration requirements and EU F-Gas Regulation indirectly influence sulphur-based chemical handling protocols across European production sites. China's MEE enforces dual carbon compliance thresholds that constrain older sulphur-burning process configurations. Stakeholders must monitor regulatory divergence between food-grade and industrial-grade certification pathways as jurisdictions tighten contaminant limits without harmonizing test methodologies.
Market Dynamics
China's MEE dual carbon mandates are forcing sulphur-burning process retrofits across legacy sodium metabisulphite plants, compressing supply elasticity while beverage and water treatment demand accelerates across Asia-Pacific and Latin America.
Growth Catalysts
- Food-grade certification expansion:India's FSSAI tightened preservative purity standards for packaged beverages, compelling domestic manufacturers to upgrade assay specifications above 97.5% Na2S2O5.
- Municipal water treatment mandates:Indonesia's national drinking water program designated sodium metabisulphite for dechlorination in district-scale distribution networks across Java and Sumatra.
- Sulphur dioxide recovery technology:Closed-loop scrubber systems in Chinese chemical parks now capture SO2 for metabisulphite regeneration, lowering feedstock cost volatility.
Market Restraints
- Elemental sulphur price volatility:Sulphur derived from oil refining and natural gas processing fluctuates with energy markets, squeezing margin predictability for non-integrated producers.
- Potassium metabisulphite substitution:Wineries in premium segments substitute potassium salt where sodium content conflicts with low-sodium positioning, fragmenting volume commitments.
- REACH registration friction:ECHA's dossier requirements for sulphite compounds create compliance cost barriers for exporters serving EU food and pharmaceutical end-uses.
Strategic Opportunities
- Brazilian mining sector penetration:Gold and copper extraction operations in Minas Gerais seek oxygen scavengers for cyanide leach circuits, creating industrial-grade demand outside traditional food channels.
- Pharmaceutical-grade synthesis:USP and EP certification for injectable applications opens pricing premiums three to four tiers above technical grades in oncology and diagnostic reagent supply chains.
- Direct-to-brewery distribution:Specialty chemical distributors bypass commodity traders to contract directly with craft breweries for precise SO2 dosing equipment and chemical bundles.
Industry Challenges
- Process safety engineering scarcity:Sulphur dioxide handling expertise concentrates among aging specialists, complicating plant expansion timelines and MEE compliance audits.
- Food-grade audit duration:FSSC 22000 and BRC certification cycles extend 14-18 months for greenfield Asian facilities, delaying revenue recognition against committed offtake agreements.
- Legacy chlor-alkali integration:Captive caustic and chlorine supply chains require simultaneous sulfuric acid balancing, constraining output flexibility when pulp and paper demand weakens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Metabisulphite Market |
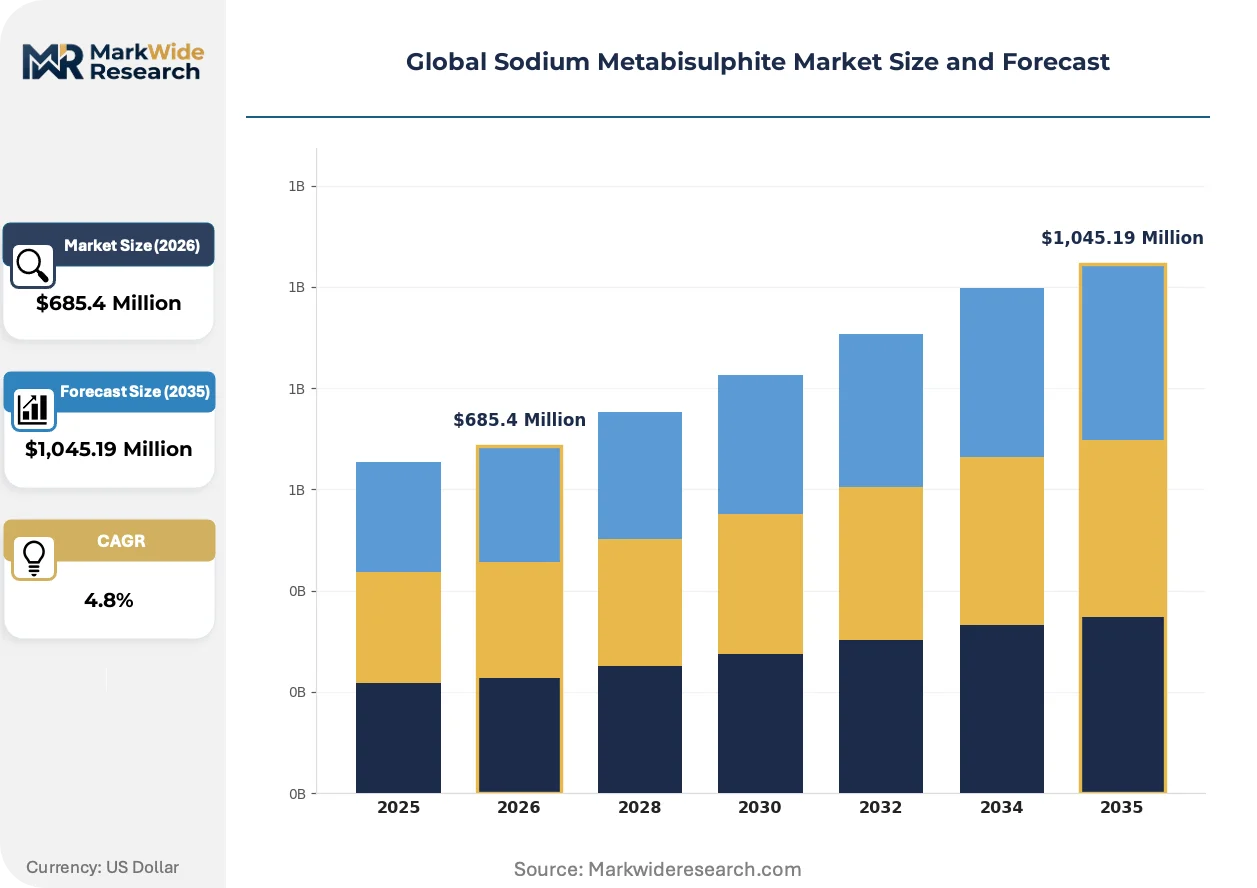
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Powder, Granules, Liquid, Tablets Application: Water Treatment, Textile Processing, Food Preservatives, Pulp & Paper, Chemical Intermediates End User Industry: Mining Firms, Beverage Producers, Leather Tanneries, Pharmaceutical Manufacturers, Photographic Labs Packaging Type: 25 kg Bags, 50 kg Bags, Bulk Containers, Drums, Sacks |
| Companies Covered | BASF SE, Aditya Birla Chemicals, FMC Corporation, Esseco USA, INEOS Calabrian, Solvay, Grillo-Werke AG, Hydrite Chemical, Shandong Kailong Chemical Technology Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Metabisulphite Market Shifts & Advancements
Process intensification and regulatory chemistry are compressing production footprints while digital dosing systems reshape how end-users specify and contract for sulphite preservation.
Membrane electrolysis for sulphur dioxide absorption is electrifying traditional sulphur-burning metabisulphite synthesis, cutting energy intensity per tonne by enabling direct electrochemical conversion without combustion intermediates. German chemical parks pilot this configuration for pharmaceutical-grade output. The technology is electrifying competitive positioning by decoupling production from regional natural gas pricing, permitting modular plant siting near sulphur sources rather than energy hubs.
REACH's 2023 update to restriction entries for sulphite respiratory sensitizers tightened occupational exposure limits across EU manufacturing sites, forcing automation investments in packaging and material handling. Plants in Belgium and the Netherlands now deploy robotic palletizing for powder grades. Food-grade exporters to Germany and France absorb disproportionate compliance costs, accelerating consolidation among sub-scale toll manufacturers.
Beverage producers now specify dissolved oxygen reduction performance rather than chemical purity alone, unbundling traditional commodity contracts into chemical-plus-equipment service agreements. Australian wineries and Thai juice processors lead this specification shift. Southeast Asian distributors respond by hiring process engineers to calibrate dosing systems on-site, converting transactional chemical sales into recurring technical service revenue.
Global Sodium Metabisulphite Market Segmentation
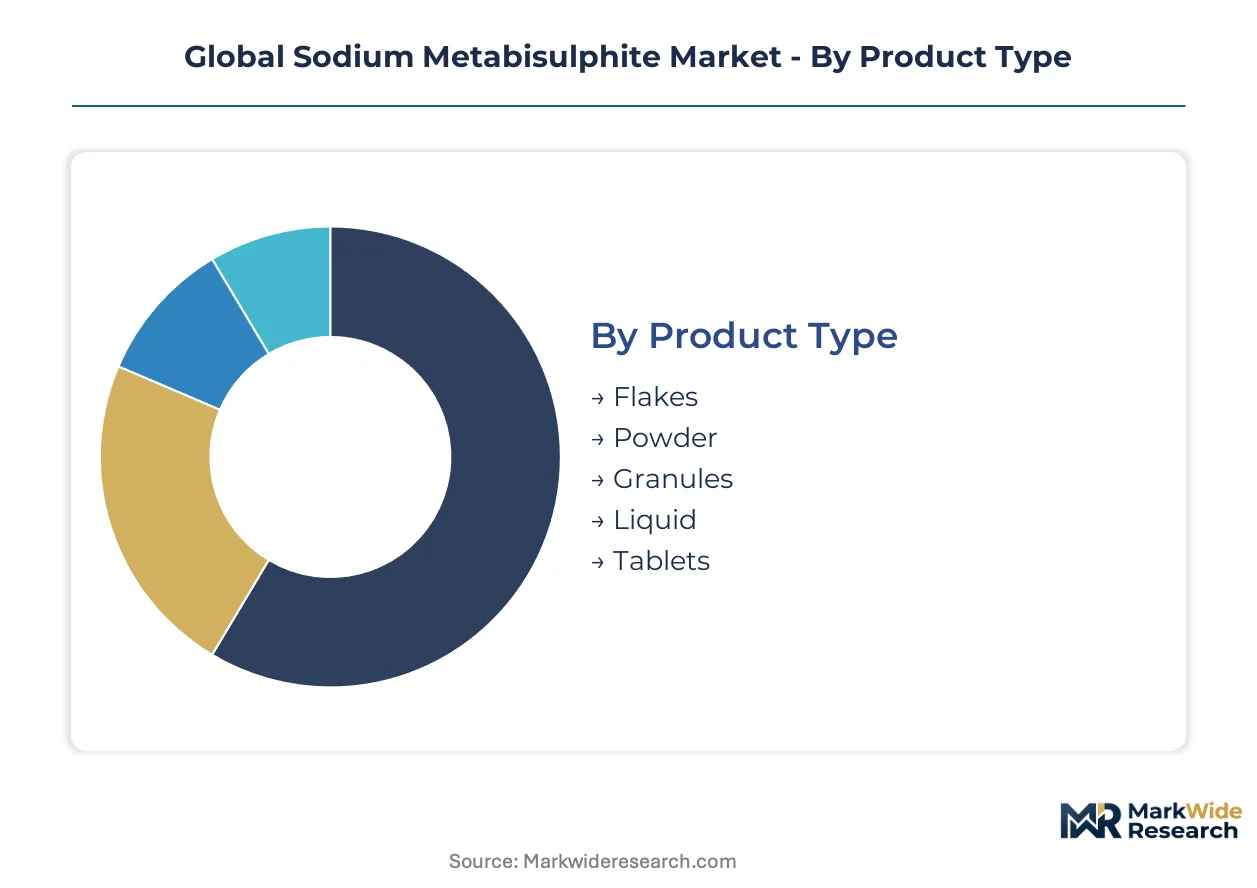
Sodium metabisulphite's functional versatility across oxygen scavenging, antimicrobial action, and reducing bleaching creates distinct specification requirements by product form and end-use. Segmentation reveals how purity thresholds, dissolution kinetics, and packaging logistics fragment what appears chemically uniform into commercially differentiated tiers.
Product Type:
Upgrade cycles in processing equipment and dosing automation are reshaping which physical forms command procurement preference across industrial and food-grade channels.
- Flakes:Crystalline plate morphology with moderate dissolution rates suits bulk handling systems in water treatment plants and mining operations. Indonesian municipal dechlorination networks and Brazilian cyanide leach circuits concentrate flake demand where rapid dispersion matters less than storage stability.
- Powder:Fine particulate structure below 150 microns delivers fastest dissolution kinetics, commanding premium positioning in pharmaceutical synthesis and precision beverage dosing. India's FSSAI-mandated purity upgrades above 97.5% Na2S2O5 concentrate powder procurement for packaged juice preservation.
- Granules:Intermediate particle size reduces dust exposure during handling, finding niche placement in leather tanneries and textile bleaching operations where operator safety protocols prioritize flowability over dissolution speed.
- Liquid:Pre-dissolved aqueous solutions eliminate dissolution equipment capital for small-scale users, penetrating craft breweries and photographic labs with limited chemical handling infrastructure.
- Tablets:Compressed solid forms enable precise unit dosing in remote mining camps and mobile water treatment units where weighing equipment is unavailable.
Volume placements concentrate in Flakes; the faster expansion belongs to Powder.
Application:
Regulatory mandates and process chemistry requirements split demand across maturity stages and margin profiles.
- Water Treatment:Dechlorination in municipal distribution systems and reverse osmosis pre-treatment drives specification toward assay consistency and low heavy-metal contamination. Indonesia's national drinking water program designated sodium metabisulphite for district-scale networks across Java and Sumatra.
- Food Preservatives:Wine, juice, and dried fruit applications require food-grade certification with sulphur dioxide release control. Asia-Pacific beverage producers expand procurement as India's FSSAI tightens preservative purity standards.
- Pulp & Paper:Bleaching sequences and tall oil recovery constitute mature demand with limited growth upside, constrained by digital substitution in printing and packaging.
- Textile Processing:Reductive bleaching of wool and synthetic fibers faces displacement from hydrogen peroxide systems in sustainability-focused European supply chains.
- Chemical Intermediates:Feedstock for thiosulphate, dithionite, and other sulphur derivatives links sodium metabisulphite demand to specialty chemical manufacturing clusters in Germany and China.
Water Treatment absorbs the largest volume commitments; Food Preservatives climb the fastest.
End User Industry:
Customer technical sophistication and contractual volume structures determine pricing power and service bundling requirements.
- Mining Firms:Gold and copper extraction operations in Minas Gerais and Western Australia specify industrial-grade oxygen scavengers for cyanide leach circuit efficiency, creating demand outside traditional food channels with stringent delivery reliability requirements.
- Beverage Producers:Wineries and juice processors now specify dissolved oxygen reduction performance rather than chemical purity alone, unbundling commodity contracts into chemical-plus-equipment service agreements.
- Pharmaceutical Manufacturers:USP and EP certification for injectable applications opens pricing premiums three to four tiers above technical grades in oncology and diagnostic reagent supply chains.
- Leather Tanneries:Beamhouse processing and bleaching sequences in India and Bangladesh consume standard industrial grades where cost minimization dominates procurement criteria.
- Photographic Labs:Declining silver halide processing compresses this legacy segment, with residual demand concentrating in archival and artistic printing niches.
Mining Firms anchor industrial volume; Pharmaceutical Manufacturers deliver the steepest margin expansion.
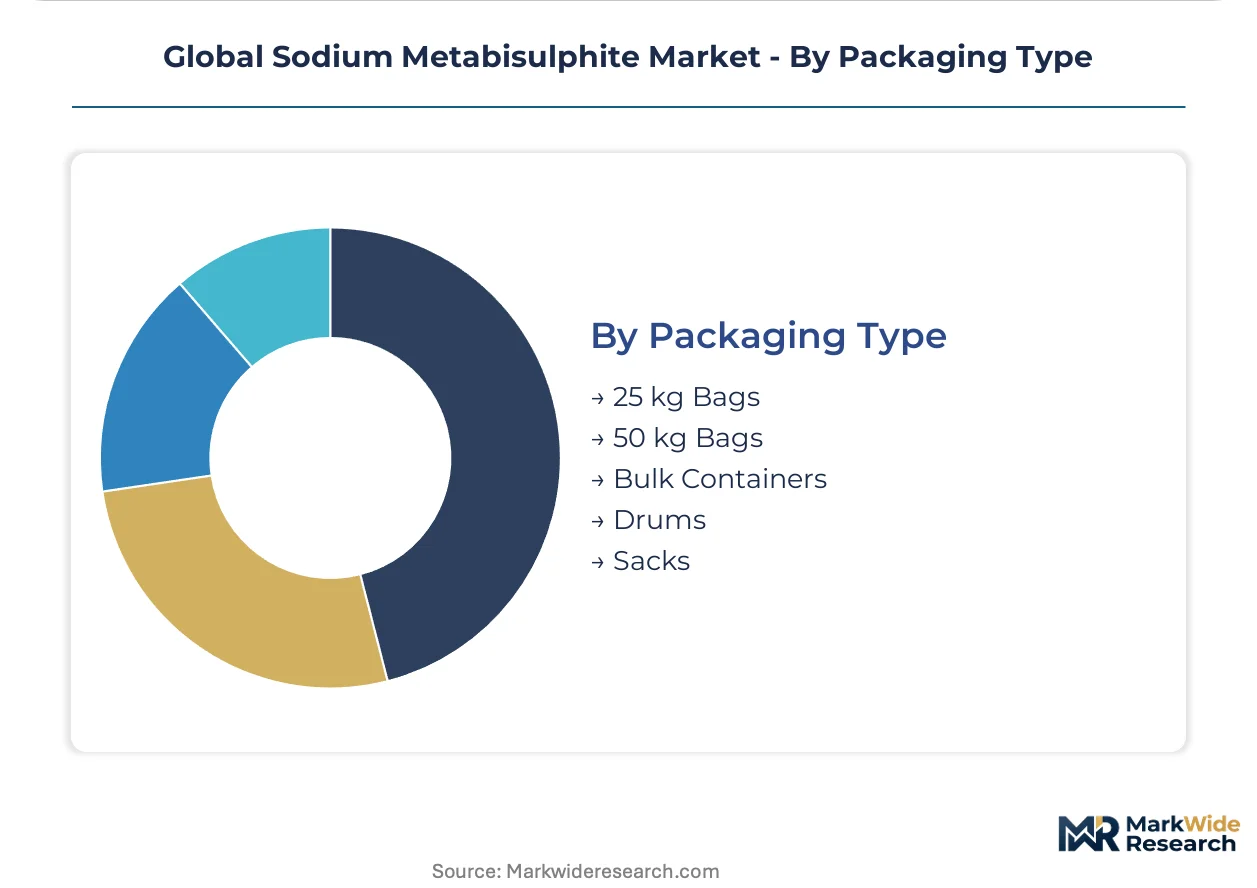
Packaging Type:
Logistics economics and handling automation investments differentiate procurement patterns by customer scale and geographic access.
- 25 kg Bags:Standard unit for food-grade distribution to small and mid-size beverage producers, compatible with manual handling and warehouse racking systems.
- 50 kg Bags:Preferred industrial format for water treatment and textile operations with mechanical handling equipment, optimizing transport cube utilization.
- Bulk Containers:Intermediate bulk containers and flexible tank systems serve large municipal water authorities and mining operations with dedicated storage infrastructure.
- Drums:Liquid and hygroscopic powder grades require sealed steel or polymer drums for moisture protection during ocean freight to humid climates.
- Sacks:Multi-wall paper or woven polypropylene sacks with polyethylene liners balance cost and protection for standard industrial grades.
50 kg Bags dominate shipment counts; Bulk Containers gain share fastest in mining and municipal verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's chemical park special economic zones concentrate sodium metabisulphite production capacity, with MEE dual carbon mandates forcing process retrofits that compress regional supply elasticity while Asia-Pacific beverage demand accelerates.
China
Beverage producers in Shandong and Jiangsu provinces expand food-grade procurement for wine and juice preservation. MEE enforces dual carbon compliance thresholds that constrain older sulphur-burning process configurations. Closed-loop scrubber systems in chemical parks now capture SO2 for metabisulphite regeneration, lowering feedstock cost volatility near Qingdao industrial clusters.
United States
Gold and copper extraction operations in Nevada and Arizona specify industrial-grade oxygen scavengers for cyanide leach circuit efficiency. EPA standards for sulphur dioxide emissions shape process technology investments and product qualification thresholds. Esseco USA anchors food-grade certification protocols that differentiate against commodity imports through Midwest distribution networks.
Germany
Pharmaceutical manufacturers in Ludwigshafen and Leverkusen clusters seek USP and EP certification for injectable applications. ECHA's REACH registration requirements create compliance cost barriers for exporters serving EU food and pharmaceutical end-uses. Membrane electrolysis pilots in chemical parks electrify traditional synthesis for pharmaceutical-grade output.
India
Packaged beverage manufacturers in Maharashtra and Gujarat respond to FSSAI tightened preservative purity standards above 97.5% Na2S2O5. Aditya Birla Chemicals anchors South Asian production capacity through captive chlor-alkali feedstock access. Municipal water treatment programs in Karnataka and Tamil Nadu drive district-scale dechlorination procurement.
Brazil
Gold and copper extraction operations in Minas Gerais seek oxygen scavengers for cyanide leach circuits outside traditional food channels. ANVISA pharmaceutical regulations shape import qualification for technical-grade materials. Mining logistics corridors through Belo Horizonte industrial zones concentrate delivery reliability requirements for bulk flake procurement.
Global Sodium Metabisulphite Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with food-grade certification holders commanding premium positioning against commodity traders in beverage and pharmaceutical channels. Three archetypes dominate: integrated chemical conglomerates with captive sulphur chemistry, regional specialists leveraging backward integration into chlor-alkali feedstocks, and toll manufacturers serving geographic niches. Capacity expansion and certification protocol differentiation represent the dominant competitive moves, as MEE compliance costs and REACH friction filter sub-scale participants.
Among European integrated chemical conglomerates, BASF SE and Solvay exemplify archetypes sustaining margin control through sulphur chemistry integration. Aditya Birla Chemicals represents the regional specialist model with captive feedstock positioning. These three occupy positions across distinct geographic and certification tiers, with Esseco USA anchoring the food-grade specialist segment.
| Leading Market Players |
|---|
| BASF SE |
| Aditya Birla Chemicals |
| FMC Corporation |
| Esseco USA |
| INEOS Calabrian |
| Solvay |
| Grillo-Werke AG |
| Hydrite Chemical |
| Shandong Kailong Chemical Technology Development |
| Others |
Supply & Pricing Matrix
Food-grade versus industrial-grade assay divergence above 97.5% Na2S2O5 creates parallel pricing tracks that reshape procurement patterns across beverage preservation and water treatment verticals. China's MEE dual carbon mandates compress supply elasticity from legacy sulphur-burning plants while Indonesia's municipal dechlorination programs and Brazil's mining oxygen scavenger demand pull pricing premiums in divergent directions.
Pricing Analysis
Volume-driven flake procurement for municipal water treatment in Indonesia and Minas Gerais mining circuits operates on thin margins, while powder grades certified above 97.5% Na2S2O5 for India's FSSAI-compliant beverage producers capture three-to-four-tier premiums. Price differentiation hinges on certification tier and dissolution kinetics performance. Cost compression in industrial-grade channels intensifies as elemental sulphur feedstock volatility squeezes non-integrated producers. Small-scale craft breweries exhibit highest price sensitivity; pharmaceutical manufacturers seeking USP and EP certification show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese chemical park concentration where MEE compliance retrofits constrain output flexibility. Manufacturing gravity centers on China, India, and Germany, with captive chlor-alkali integration at Aditya Birla and BASF SE anchoring regional supply security. Feedstock dependency on elemental sulphur from oil refining and natural gas processing, plus caustic soda from membrane cell chlor-alkali operations, exposes margins to energy market swings. Tariff exposure from REACH registration friction filters sub-scale EU exporters. Distribution runs through specialty chemical distributors contracting directly with beverage producers for dosing equipment bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium metabisulphite production is transitioning from sulphur-burning combustion to membrane electrolysis electrification, with German chemical parks piloting direct electrochemical conversion that decouples output from regional natural gas pricing.
For Market Incumbents: Deepen backward integration into sulphur chemistry to sustain margin control against potassium metabisulphite substitution in premium wine segments. Expand food-grade certification protocols beyond FSSC 22000 to BRC standards, compressing 14-18 month audit cycles through pre-qualified facility investments. Prioritize captive SO2 recovery scrubber deployment in Chinese chemical parks to neutralize MEE dual carbon compliance cost pressure. For New Entrants and Emerging Players: Capture Brazilian mining sector oxygen scavenger demand outside traditional food channels, where gold and copper extraction operations in Minas Gerais seek industrial-grade flake with delivery reliability requirements unmet by commodity traders. Penetrate pharmaceutical-grade synthesis for USP and EP certification in oncology and diagnostic reagent supply chains. Lead with direct-to-brewery distribution bundling precise SO2 dosing equipment with chemical supply contracts. For Investors and Strategic Acquirers: Re-rating potential sits with membrane electrolysis technology adopters given MEE decarbonization mandates and EU F-Gas Regulation alignment. Long-term viability favors producers with captive chlor-alkali feedstock and food-grade certification moats. Watch for inflection when beverage procurement shifts decisively from purity-based to dissolved oxygen reduction performance specifications, unbundling commodity contracts into chemical-plus-equipment service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulphur Chemistry | BASF SE's captive feedstock access insulates margin control from elemental sulphur price volatility. |
| Food-Grade Certification Expansion | FSSC 22000 and BRC protocols differentiate Esseco USA positioning against commodity imports. |
| Membrane Electrolysis Pilot Deployment | German chemical parks electrify synthesis for pharmaceutical-grade output without combustion intermediates. |
| Direct-to-Brewery Distribution | Australian wineries and Thai juice processors now contract for chemical-plus-equipment service bundles. |
| Closed-Loop SO2 Recovery Installation | Qingdao industrial clusters capture sulphur dioxide for metabisulphite regeneration, lowering feedstock cost exposure. |
Research Methodology
Independent corroboration across plant managers at sodium metabisulphite production facilities, procurement leads at Indonesian municipal water authorities and Brazilian mining operations, distribution channel partners in European beverage supply chains, and technical R&D directors at chlor-alkali integrated complexes underwrites the qualitative findings. Secondary validation draws from Chinese MEE environmental compliance disclosures, Indian FSSAI regulatory filings, ECHA REACH registration databases, and ACC/Cefic chemical trade reports. Bottom-up volume modeling triangulates against top-down industry sizing across grade tier, end-use industry, packaging format, and regional production hub segmentation.
Comparable-period anchoring to historical sulphur-burning process economics and membrane electrolysis pilot data shapes the projection horizon. The analytical framework models powder, flake, granule, liquid, and tablet product forms against water treatment, food preservative, pulp and paper, textile processing, and chemical intermediate applications. CAGRs derive from segment-level demand elasticity calibrated to regulatory mandate timing and technology substitution curves. Forecast inputs incorporate MEE dual carbon compliance cost trajectories and FSSAI purity standard enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to membrane electrolysis scale-up rates and potassium metabisulphite substitution velocity in premium beverage segments. Forecasts reflect documented assumptions about regulatory enforcement consistency and feedstock price correlation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Fumigant Products Market
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Artificial Preservatives Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Antibacterial Products Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market