
 Dishwashing Additives Market | 2026-2036
Dishwashing Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Dishwashing Additives Market Outlook
Commercial foodservice demand is shifting toward concentrated rinse aid and quick-dry formulations as restaurants, hotels, and catering operations prioritize machine throughput and reduced manual drying labor. Henkel AG & Co. KGaA dominates the European institutional channel with specialized dispensing systems and service contracts. Procter & Gamble Co. leverages its North American retail scale to sustain shelf presence across multiple form factors and price tiers. Unilever competes aggressively in emerging markets through localized brand portfolios and regional manufacturing.
Dishwashing additives encompass surfactant-based, enzymatic, and polymeric formulations designed to enhance water sheeting, prevent spotting, accelerate drying, and maintain machine hygiene in both consumer and commercial dishwashers, typically dosed at 1-5 milliliters per wash cycle depending on water hardness and machine specification. Rinse aid formulations lead value contribution due to recurring purchase frequency and premium positioning in hard-water regions, while tablet formats are displacing powder in residential settings as convenience and pre-measured dosing reduce consumer error. The commercial customer segment anchors margin pools through long-term supply agreements and integrated machine-chemistry service models, though eco-friendly feature claims are reshaping procurement criteria across all customer types.
EPA Safer Choice certification and EU Ecolabel standards are restricting phosphorus content and volatile organic compound thresholds in rinse aid and cleaner formulations, compelling reformulation investments across the supply base. BIS standards in India and China's GB standards for household chemicals add compliance layers for multinational suppliers entering Asian markets. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation platforms that can adapt to tightening toxicity thresholds without sacrificing performance benchmarks.
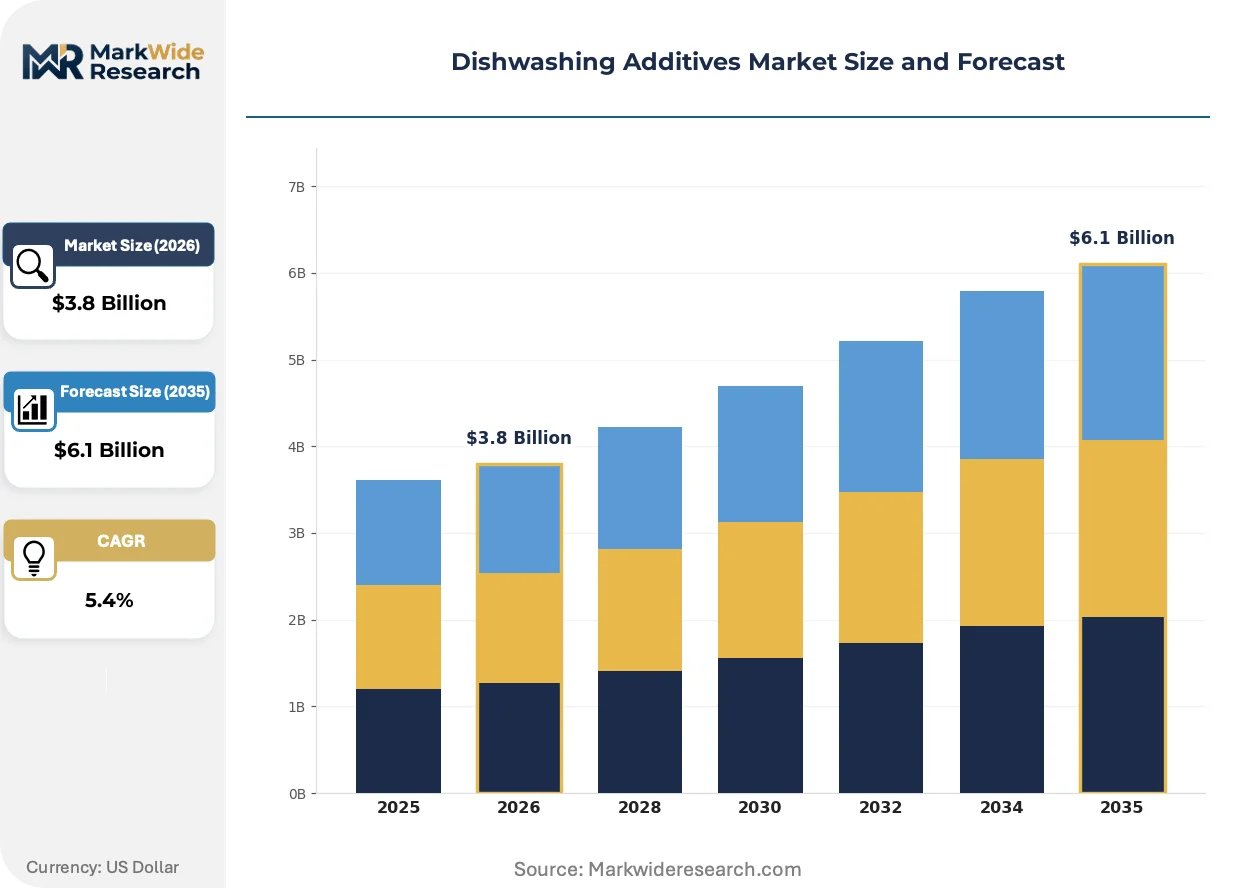
Market Dynamics
Commercial foodservice operators are consolidating chemical procurement around integrated machine-chemistry service contracts, compressing supplier margins while locking in volume commitments through multi-year agreements. This structural shift toward bundled supply models is redrawing competitive boundaries between standalone additive manufacturers and full-service hygiene providers.
Growth Catalysts
- REACH Phase-Down of Hazardous Surfactants:The European Union's tightening Ecolabel criteria and REACH restrictions on phosphorus content are accelerating manufacturer investment in bio-based enzymatic formulations that meet toxicity thresholds without performance degradation.
- Quick-Dry Formulation Demand:High-throughput restaurants and hotel chains in Germany and France are specifying concentrated rinse aids that reduce manual drying labor as wage pressures intensify across the foodservice sector.
- Tablet Format Convenience Premium:Residential consumers are migrating from powder to pre-measured tablet and gel formats that eliminate dosing error and align with premium eco-friendly positioning in hard-water regions.
Market Restraints
- Petrochemical Feedstock Volatility:Surfactant and polymer input costs fluctuate with crude oil derivatives, compressing formulation margins and complicating annual contract pricing for institutional buyers.
- Supplier Concentration in Western Europe:Specialty chemical production for institutional-grade rinse aids clusters in Germany and the Netherlands, creating geographic vulnerability to energy cost spikes and logistics disruptions.
- Performance Ceiling in Cold-Water Formulations:Enzymatic additives face efficacy limitations below 45°C water temperature, restricting adoption in energy-conscious commercial installations seeking to reduce heating loads.
Strategic Opportunities
- Underpenetrated Indian Institutional Channel:BIS standards alignment and localized manufacturing investments can capture share in India's expanding hotel and quick-service restaurant sector as commercial dishwasher penetration accelerates in tier-2 cities.
- EU Green Deal Procurement Mandates:Public sector catering contracts across Germany, France, and Italy are incorporating mandatory Ecolabel compliance, creating preferential market access for certified bio-based formulation suppliers.
- Smart Dispensing System Integration:IoT-enabled dosing hardware combined with predictive reorder algorithms is absorbing recurring chemical supply into capital equipment financing models, embedding additive suppliers deeper in customer operations.
Industry Challenges
- Reformulation Timeline Compression:EPA Safer Choice and EU Ecolabel revisions are shortening certification cycles, forcing R&D teams to validate alternative chemistries under accelerated performance benchmarking protocols.
- Cross-Border Regulatory Divergence:China's GB standards for household chemicals, India's BIS requirements, and California's Proposition 65 create fragmented compliance obligations that strain formulation platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dishwashing Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rinse Aid, Pre-Wash, Cleaner, Spot Remover Form: Liquid, Powder, Gel, Tablet Customer Type: Residential, Commercial, Industrial, Institutional Feature: Eco-Friendly, Antibacterial, Quick-Dry, Non-Toxic |
| Companies Covered | Procter & Gamble Co., Reckitt Benckiser Group, Unilever, Henkel AG & Co. KGaA, Colgate-Palmolive Company, The Clorox Company, Kao Corporation, Ecolab Inc., Seventh Generation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dishwashing Additives Market Strategic Shifts
Formulation science and digital distribution infrastructure are converging to reshape how dishwashing chemistry reaches end-users. Three developments are compressing legacy supply models while opening specialized niches for adaptive competitors.
Enzymatic rinse aid formulations leveraging protease and lipase blends are absorbing market share from traditional surfactant-heavy chemistries in premium residential and institutional segments. German and French buyers are specifying these formulations at accelerating rates as Ecolabel compliance becomes a procurement gate. The technology is absorbing margin from commodity surfactant suppliers while enabling performance claims around low-temperature efficacy.
REACH authorization requirements for specific surfactant categories are compelling manufacturers to rebuild formulation platforms around bio-based alternatives. The industrial consequence is a bifurcation between compliant suppliers with validated replacement chemistries and stranded legacy producers facing market exclusion. Tablet and gel formats containing reduced phosphorus content are absorbing disproportionate investment as the most affected product category, with German retailers leading shelf-space reallocation.
Foodservice procurement teams are consolidating chemical spend under integrated facility management contracts that bundle dishwashing additives with equipment service and water treatment. This behavior shift is displacing standalone chemical distributors in the commercial channel, with contract catering groups and hotel chains in France and the UK most visibly adopting consolidated supply models. The geography where this compression is most advanced reflects mature outsourced foodservice infrastructure and centralized procurement functions.
Dishwashing Additives Market Segmentation
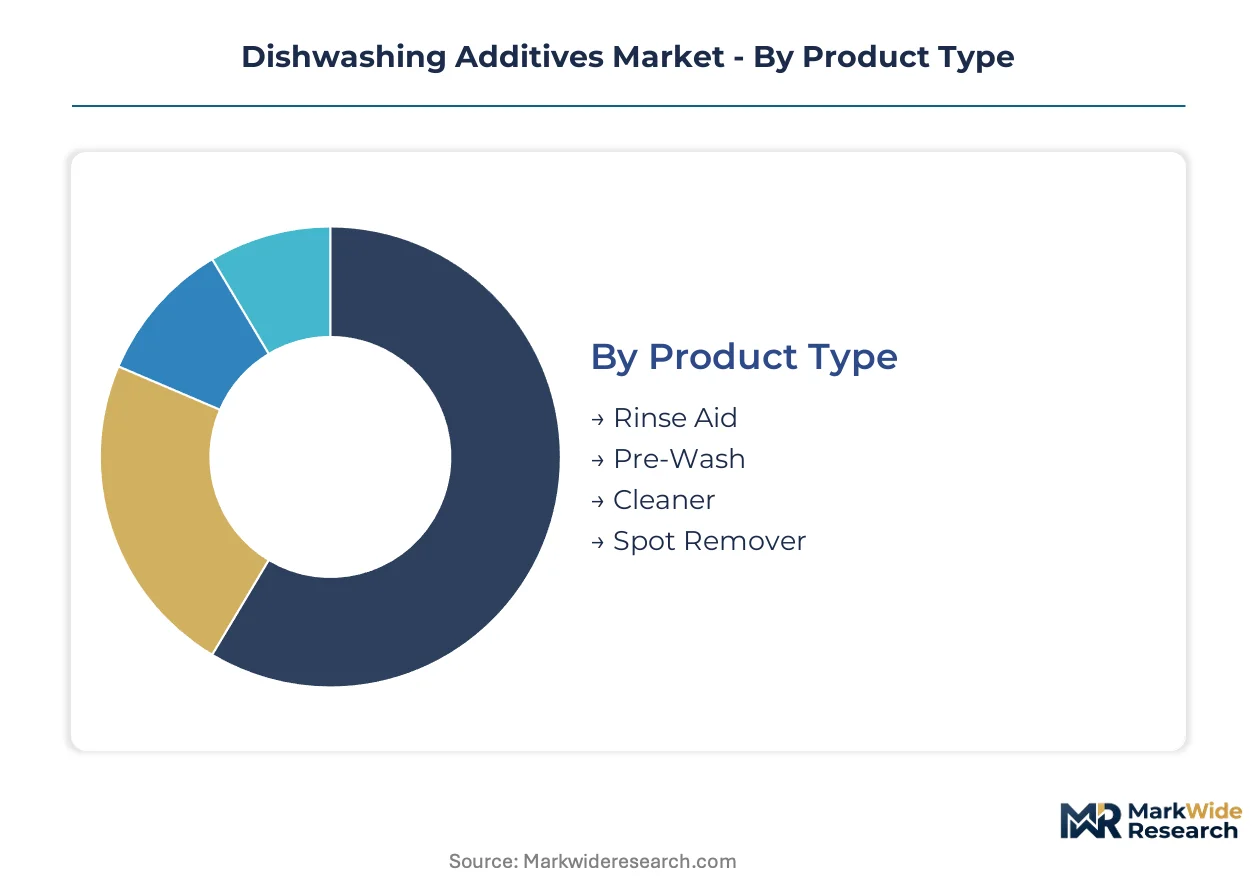
Dishwashing additives fragment across formulation chemistry, physical form, and procurement context. Each axis reveals distinct margin structures and competitive dynamics that shape supplier positioning and channel strategy.
Product Type:
Rinse aid formulations command premium positioning through recurring purchase frequency, while cleaners and specialty treatments occupy discrete application niches with lower replenishment rates.
- Rinse Aid:Surfactant-polymer blends engineered for water sheeting and spot prevention dominate value pools in hard-water geographies. German and French foodservice operators specify concentrated variants to eliminate manual drying labor as wage pressures mount across the sector.
- Pre-Wash:Enzymatic soak formulations targeting baked-on soil removal are gaining traction in institutional kitchens with extended wash cycles. Commercial operators in high-throughput environments prioritize these chemistries to reduce rewash rates and protect tableware longevity.
- Cleaner:Machine hygiene formulations prevent biofilm accumulation and limescale buildup in dishwasher sumps and spray arms. Scheduled maintenance dosing creates predictable replenishment patterns among contract catering groups.
- Spot Remover:Targeted treatments for etched glassware and mineral deposits serve premium hospitality segments with visible quality standards. Boutique hotels and fine-dining establishments absorb disproportionate volume despite limited household penetration.
Today's leader: Rinse Aid. Tomorrow's challenger: Pre-Wash.
Form:
Physical format determines dosing precision, storage economics, and compatibility with dispenser infrastructure across residential and commercial installations.
- Liquid:Pourable formulations compatible with adjustable reservoir systems remain standard in commercial machine configurations. Variable dosing flexibility suits operations with fluctuating water hardness and soil load profiles.
- Powder:Granular chemistries retain cost advantage in price-sensitive bulk procurement but face displacement as pre-measured alternatives reduce dosing error and packaging waste.
- Gel:Viscous formulations dissolve rapidly across temperature ranges and enable concentrated active loading in compact packaging. German retailers are reallocating shelf space toward gel variants as Ecolabel-compliant positioning resonates with environmentally conscious households.
- Tablet:Pre-measured unit doses eliminate consumer measurement error and align with convenience positioning in premium residential segments. REACH-driven phosphate restrictions are accelerating tablet format investment as manufacturers reformulate around compliant surfactant platforms.
Tablet formats are climbing the fastest as convenience and regulatory alignment converge.
Customer Type:
Procurement sophistication and contract structure vary sharply between fragmented household demand and concentrated institutional purchasing power.
- Residential:Individual households purchasing through retail and e-commerce channels prioritize convenience features and eco-friendly claims. German consumers demonstrate elevated willingness to pay for Ecolabel-certified tablet and gel formats.
- Commercial:Independent restaurants and small hotel operations negotiate spot purchases or short-term supply agreements with regional distributors. Price sensitivity runs higher than in institutional segments with less centralized procurement.
- Industrial:Large-scale food manufacturing and processing facilities with captive dishwashing operations specify bulk chemistries through tender processes. Volume concentration enables supplier margin compression in exchange for multi-year commitments.
- Institutional:Contract catering groups, hospital networks, and educational facilities are consolidating chemical spend under integrated facility management contracts. France and the UK exhibit the most advanced bundled procurement models combining additives with equipment service.
Institutional contracts deliver the steepest expansion trajectory as bundled service models displace standalone chemical distribution.
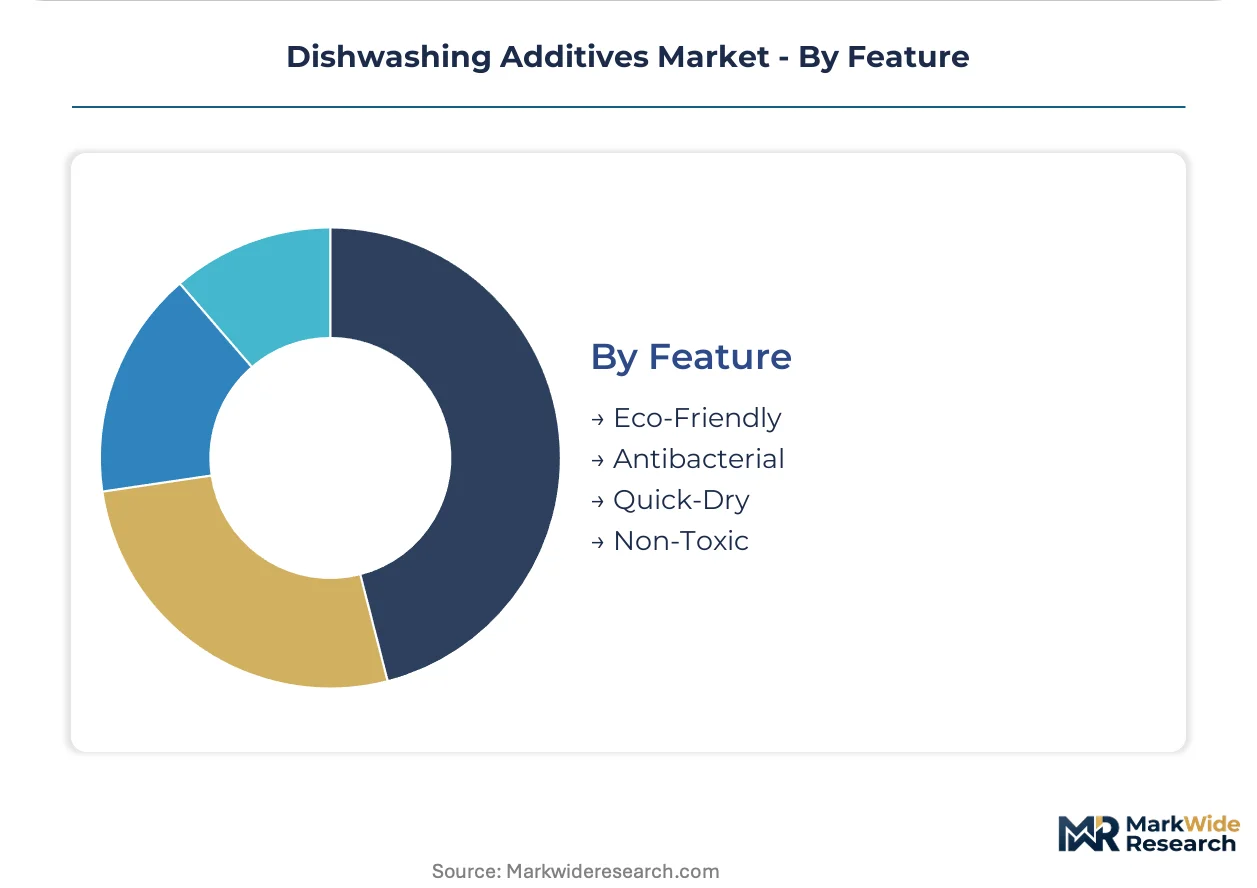
Feature:
Performance claims and certification status increasingly gate procurement decisions across regulatory jurisdictions and customer risk profiles.
- Eco-Friendly:Bio-based enzymatic formulations meeting EU Ecolabel and EPA Safer Choice thresholds are absorbing investment as REACH restrictions eliminate legacy surfactant options. Public sector catering mandates in Germany, France, and Italy now require compliant chemistry.
- Antibacterial:Sanitizing additives targeting pathogen reduction in healthcare and childcare foodservice settings face efficacy validation requirements under national biocide regulations. Claims substantiation costs limit supplier participation.
- Quick-Dry:Accelerated water sheeting chemistries reduce manual drying labor in high-throughput restaurants and hotel banquet operations. French hotel chains specify these formulations as wage inflation intensifies.
- Non-Toxic:Reduced hazard classifications appeal to residential consumers with skin sensitivity concerns and institutional buyers with occupational safety obligations. Formulation platforms must balance toxicity reduction with hard-water performance maintenance.
Eco-Friendly certification is becoming table stakes; Quick-Dry performance separates premium suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between REACH-compliant Europe and less stringent Asian jurisdictions is redirecting formulation investment toward Germany and the Netherlands, while Indian and Chinese producers exploit compliance-cost arbitrage to capture contract manufacturing volumes.
Germany
Institutional buyers in Bavaria and North Rhine-Westphalia are consolidating chemical procurement under EU Green Deal mandates that require Ecolabel-certified rinse aids in public sector catering. REACH Phase-Down restrictions on hazardous surfactants have concentrated compliant formulation R&D in the Cologne-Düsseldorf chemical cluster, where Henkel AG & Co. KGaA anchors bio-based enzymatic production platforms.
France
Hotel chains and contract catering groups in Île-de-France are specifying quick-dry rinse aid formulations as minimum wage pressures intensify across the foodservice sector. ANSM biocide regulations limit antibacterial additive claims, pushing suppliers toward performance-based positioning around water sheeting and spot prevention. The Lyon-Grenoble corridor hosts specialty chemical production serving institutional channels.
United States
EPA Safer Choice certification requirements in California and Proposition 65 litigation risk are compressing phosphorus content thresholds for rinse aids sold through retail and commercial channels. Foodservice operators in Texas and Florida are adopting concentrated formulations to reduce packaging waste and storage footprint. Midwest institutional buyers negotiate multi-year supply agreements with integrated facility management providers.
India
BIS standards alignment for household chemicals is accelerating as commercial dishwasher penetration expands in tier-2 cities across Maharashtra and Karnataka. Quick-service restaurant chains in Mumbai and Bangalore are specifying institutional-grade additives through centralized procurement functions. Gujarat's chemical manufacturing belt is attracting contract formulation investment from multinational suppliers seeking cost-competitive production bases.
China
GB standards for household chemicals and dual carbon goals are tightening surfactant discharge requirements in the Yangtze River Delta manufacturing zone. Domestic hotel chains in Shanghai and Guangzhou are importing Ecolabel-compliant formulations to meet sustainability commitments. The Pearl River Delta retains concentration in commodity surfactant production serving Southeast Asian export markets.
Dishwashing Additives Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consumer retail consolidating around multinational FMCG portfolios while commercial channels fragment between integrated hygiene providers and standalone additive suppliers. Three archetypes dominate: full-service facility management contractors bundling chemistry with equipment service, branded formulation specialists competing on Ecolabel certification, and regional private-label manufacturers serving price-sensitive institutional buyers. Capacity expansion in enzymatic formulation platforms and strategic partnerships between chemical suppliers and smart dispensing hardware vendors represent the dominant competitive moves reshaping channel access.
Among the multinational branded tier, Procter & Gamble Co., Henkel AG & Co. KGaA, and Unilever exemplify divergent geographic strategies. Cincinnati-based Procter & Gamble Co. occupies a position anchored in North American retail scale across multiple form factors. Düsseldorf-headquartered Henkel AG & Co. KGaA represents the European institutional channel specialist with integrated dispensing systems and service contract penetration. Anglo-Dutch Unilever exemplifies emerging market localization through regional manufacturing footprints and brand portfolio adaptation. These three entities collectively illustrate how scale, regional regulatory alignment, and channel integration separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Reckitt Benckiser Group |
| Unilever |
| Henkel AG & Co. KGaA |
| Colgate-Palmolive Company |
| The Clorox Company |
| Kao Corporation |
| Ecolab Inc. |
| Seventh Generation Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized enzymatic formulation chemists concentrated in the Cologne-Düsseldorf corridor command wage premiums that widen spreads between Ecolabel-certified premium tiers and commodity surfactant alternatives. Labor-cost differentials between German R&D hubs and contract manufacturing zones in Gujarat directly feed into three-tier pricing structures across institutional procurement channels.
Pricing Analysis
Distributor margin layers of 18-25 percent separate bulk institutional contracts from spot retail purchases in fragmented commercial channels. Three-tier pricing structure across premium Ecolabel-certified, standard compliant, and economy phosphate-containing formulations reflects certification investment recovery and water-hardness performance guarantees. Cost compression in economy powder segments is intensifying because Indian and Chinese producers exploit feedstock arbitrage on petrochemical surfactants. Quick-service restaurant chains exhibit highest price sensitivity, while German hospital networks absorbing bundled service contracts show least elasticity.
Supply Chain Analysis
India's BIS localization mandates for household chemicals are reshaping sourcing patterns as multinational suppliers establish compounding operations in Gujarat to serve domestic institutional channels. Specialty enzymatic production draws from German biotechnology clusters, Dutch surfactant synthesis infrastructure, and Indian contract formulation capacity. Supply chain risk centers on single-source vulnerability for protease and lipase enzyme strains produced by limited fermentation facilities. Distribution runs through integrated facility management contractors in France and the UK, displacing standalone chemical distributors in commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dishwashing additives market functions as a stable compounder anchored by recurring institutional replenishment cycles and regulatory-mandated reformulation waves that sustain premium pricing power.
For Market Incumbents: Anchor Ecolabel certification leadership through captive enzyme fermentation capacity in the Cologne-Düsseldorf corridor, defending against stranded-asset risk from REACH Phase-Down restrictions on legacy surfactant platforms. Deepen backward integration into bio-based feedstock supply through partnerships with European agricultural processors to secure non-petrochemical polymer inputs. For New Entrants and Emerging Players: Enter via India's tier-2 city institutional channel where BIS standards alignment creates technical barriers for unlocalized competitors, capturing share in Mumbai and Bangalore quick-service restaurant chains. Target white-space in smart dispensing system integration by partnering with IoT hardware vendors to embed predictive reorder algorithms into capital equipment financing models. For Investors and Strategic Acquirers: Valuations sit cheapest among regional private-label manufacturers serving price-sensitive Indian and Southeast Asian institutional buyers, where consolidation premiums remain unrealized. Watch enzymatic formulation patent filing velocity as the inflection signal separating compliant platform investments from stranded legacy chemistry exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Investment | REACH Phase-Down compliance secures German institutional channel access against surfactant restrictions. |
| Smart Dispensing Integration | IoT-enabled dosing hardware embeds Henkel and Ecolab deeper in customer operations through predictive reorder. |
| India Localization Buildout | BIS-aligned Gujarat manufacturing captures tier-2 city commercial dishwasher penetration in Maharashtra. |
| EU Green Deal Certification | Ecolabel compliance gates public sector catering contracts across Germany, France, and Italy procurement. |
| Backward Feedstock Integration | Captive bio-based polymer supply insulates margin from petrochemical derivative volatility in surfactant inputs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation R&D directors, institutional procurement managers at contract catering groups, chemical distribution channel heads, and regulatory affairs leads at multinational suppliers with secondary validation against ECHA REACH registration databases, EU Ecolabel product registries, BIS certification records, and customs trade flow data. Bottom-up volume builds from dishwasher installation rates and per-cycle dosing norms triangulated against top-down chemical industry production disclosures.
Segment-weighting across formulation chemistry, physical form, and procurement context dimensions drove analytical framework construction over the projection horizon. CAGRs derived from elasticity modeling of institutional contract renewal rates, residential format migration curves, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporated water hardness geospatial mapping and commercial foodservice labor cost indices.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time institutional contract pricing transparency introduce uncertainty bands around commercial segment value estimates. Forecasts reflect documented assumptions on REACH enforcement timing and enzymatic efficacy validation protocols. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Engine Oil Additive Market
Additives
Inorganic Rheology Modifiers Market
Additives
Global Sodium Acetate Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Tragacanth Market
Additives
Pearlizers Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Sodium Caprylate Market
Additives
Organic Friction Modifier Additives Market
Additives
1,4 Butanediol Derivatives Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Feed Additives Market