
 Micronized Powder Market | 2026-2036
Micronized Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Micronized Powder Market Analytics
Specialty pharmaceutical formulators are bifurcating from commodity filler buyers as micronized powder procurement criteria diverge by end-use. BASF SE leverages its integrated pigment and additive portfolio to serve coating applications with tight particle-size distribution. Micro Powders, Inc. anchors its position through proprietary wax and polymer micronization technology for surface modification. Clariant competes via specialty chemical expertise in controlled-release pharmaceutical excipients.
Micronized powder refers to particulate material processed to median diameters typically below 10 micrometers, achieved through jet milling, air classification, or mechanical grinding to enhance surface area, dispersibility, and reactivity in downstream formulations. Titanium Dioxide dominates coating and sunscreen applications where UV attenuation depends on sub-micron particle engineering, while Nano-sized grades command premium positioning in pharmaceutical solubility enhancement despite higher processing costs. The Fillers application segment sustains volume leadership in plastics compounding, though Additives targeting rheology modification is outpacing baseline growth in advanced polymer systems.
EPA oversight of titanium dioxide nanoparticle environmental release shapes manufacturing site permitting and wastewater treatment investments in the United States. ECHA REACH registration requirements for nanoform substances mandate enhanced toxicity dossiers that filter out smaller European suppliers lacking analytical capabilities. FDA guidance on quality attributes for nanomaterial-containing drug products tightens documentation burdens for pharmaceutical-grade micronized inputs. Stakeholders must weigh the capital intensity of particle-size analytics against the margin premium of certified pharmaceutical supply chains.
Market Dynamics
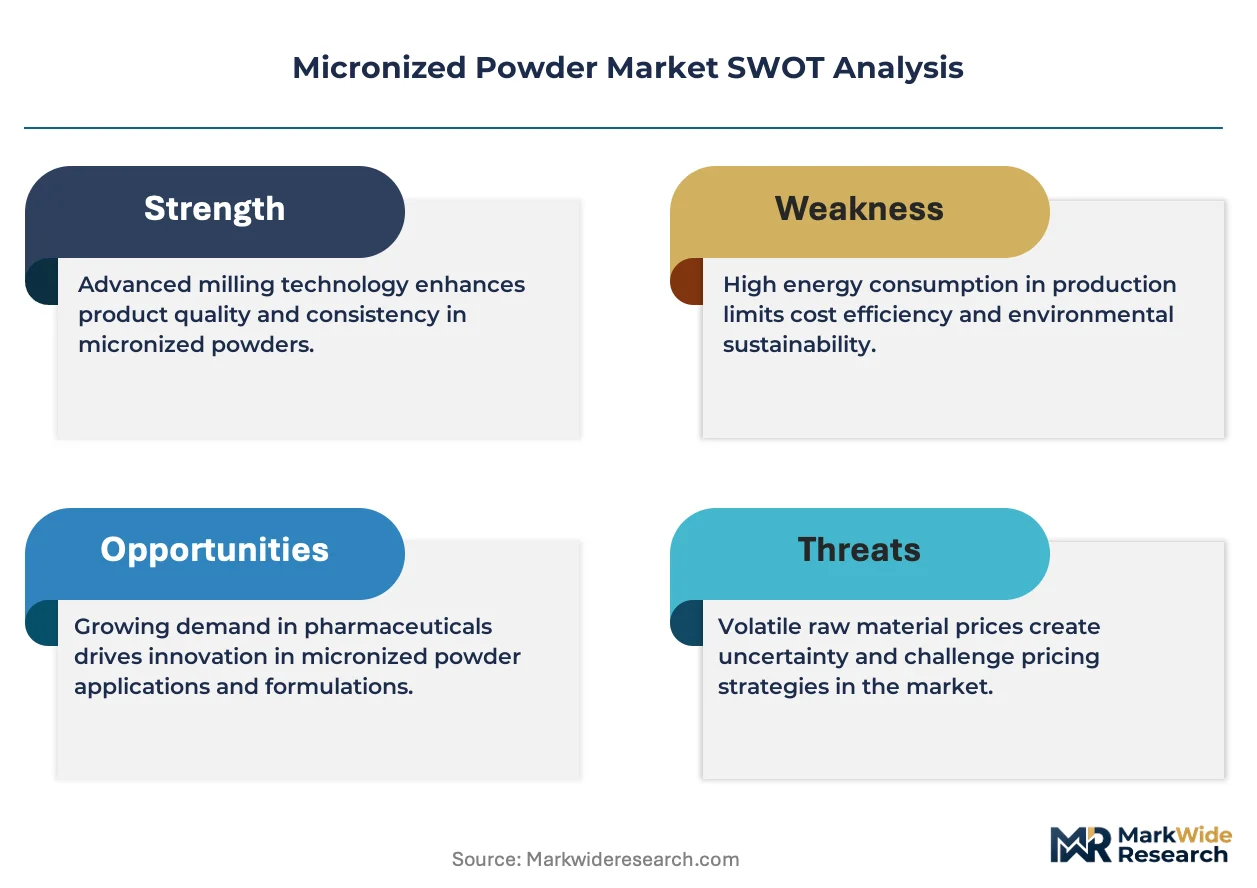
Pharmaceutical solubility enhancement is pulling micronized powder specifications toward sub-5-micron medians, forcing capital upgrades across legacy milling infrastructure and bifurcating supplier tiers by analytical certification depth.
Growth Catalysts
- Inhalable drug delivery expansion:Dry powder inhaler formulations demand engineered particle morphology for lung deposition, drawing micronized lactose and API carriers into respiratory pipelines.
- REACH nanoform registration:ECHA's enhanced toxicity dossier requirements for sub-100nm materials are filtering out uncertified suppliers, consolidating procurement toward analytical-capable mills in Germany and Switzerland.
- Jet milling throughput gains:Spiral fluidized bed designs with integrated air classification are compressing batch cycle times for titanium dioxide sunscreen grades, unlocking volume elasticity in personal care supply chains.
Market Restraints
- Titanium feedstock volatility:Chloride process pigment-grade ore concentration in Chinese smelters exposes coating-formulator margins to energy-driven price swings and export quota unpredictability.
- Analytical capex barriers:Laser diffraction and scanning electron microscopy suites required for pharmaceutical particle-size validation exceed $800K per installation, excluding regional mills from certified supply chains.
- Substitution by precipitated silica:Matte coating applications are pivoting toward fumed and precipitated silica for scratch resistance, compressing micronized wax additive volumes in automotive clearcoats.
Strategic Opportunities
- India pharmaceutical excipient localization:CDSCO's phased API and KSM manufacturing incentives are pulling micronized cellulose and starch derivative production toward Gujarat and Hyderabad clusters.
- Biodegradable mulch films:Micronized mineral loads in polylactic acid matrices for agricultural disintegration control represent an emerging tonnage channel with limited incumbent supply.
- EU Green Deal carbon border adjustments:Electricity-intensive jet milling operations in Nordic hydroelectric zones gain cost advantage over gas-dependent Southern European competitors as CBAM phases in.
Industry Challenges
- Particle metrology talent scarcity:Operators capable of interpreting Fraunhofer versus Mie scattering models for irregular pigment morphologies command 40% wage premiums, constraining QC lab scaling.
- Cross-contamination protocol complexity:Pharmaceutical-grade facilities face 18-month validation timelines for equipment changeovers between cytotoxic and non-cytotoxic API micronization campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micronized Powder Market |
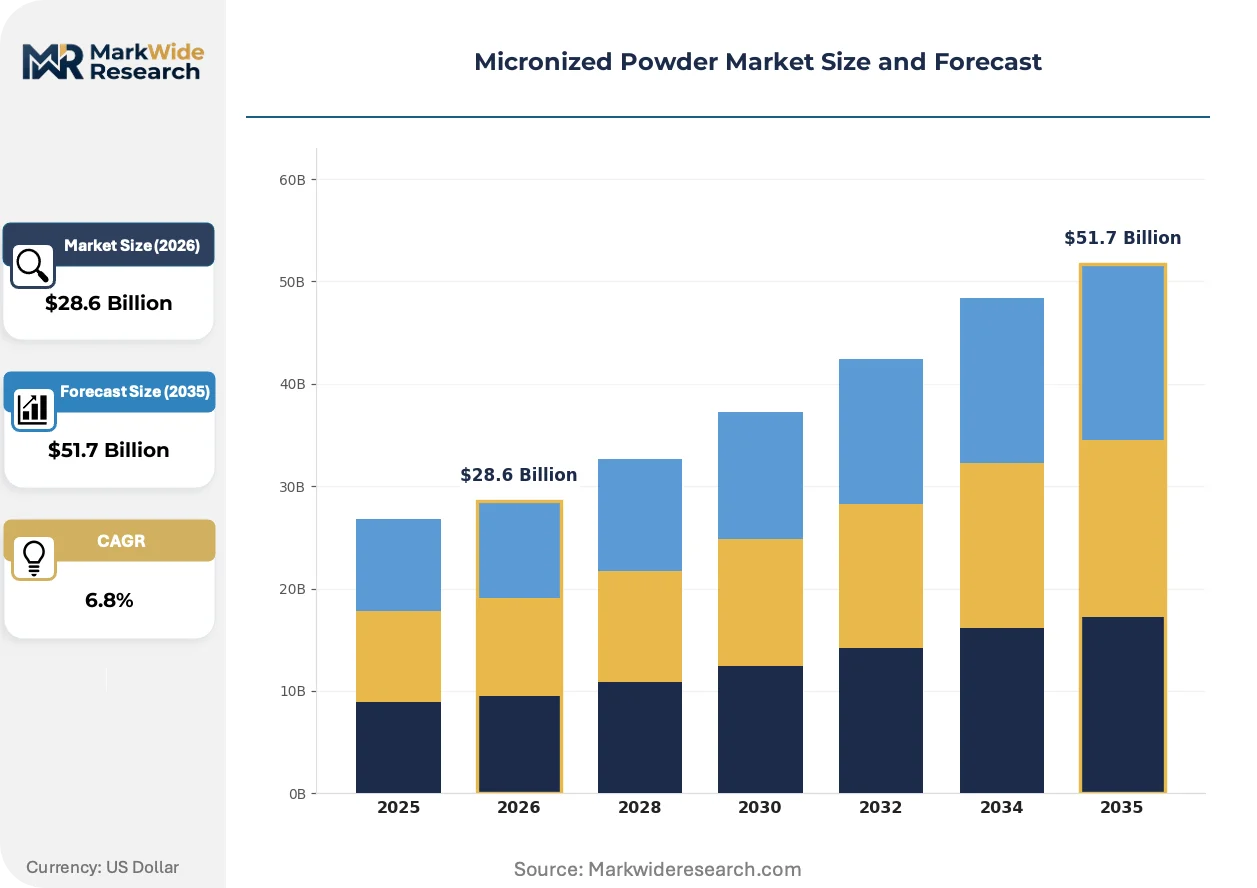
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Talc, Titanium Dioxide, Magnesium Hydroxide End Use Industry: Pharmaceuticals, Plastics, Chemicals, Food & Beverage Application: Coatings, Compounding, Additives, Fillers Size: Micro, Nano, Sub-Micron, Ultrafine |
| Companies Covered | BASF SE, Micro Powders, Inc., Clariant, The Chemours Company, Daikin Industries, Ltd., 3M, Imerys, Asbury Carbons, AMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micronized Powder Market Evolving Landscape
Active pharmaceutical ingredient engineering and regulatory nanoform classification are compressing particle-size targets while fragmenting supplier qualification protocols across end-use verticals.
Supercritical CO2 micronization is miniaturizing thermolabile API crystals without mechanical shear degradation. Specialty injectable formulators in Switzerland and Massachusetts are adopting this for biologic solubility enhancement. The technology is miniaturizing batch-scale requirements, enabling distributed production closer to fill-finish sites rather than centralized bulk milling.
EPA's TSCA Section 8(a) reporting rule for nanoscale substances is tightening manufacturing record-keeping for titanium dioxide and zinc oxide producers. Facilities must now quantify environmental release rates and worker exposure bands. Coating manufacturers serving US architectural markets are responding by dual-sourcing from EPA-registered domestic mills and validated EU imports to hedge permitting delays.
Long-term offtake contracting is displacing spot purchasing for pharmaceutical-grade micronized excipients. Multinational drug manufacturers are locking three-to-five-year supply agreements with dedicated milling capacity, bypassing traditional distributor inventories. This pattern concentrates most visibly in Germany's Rhein-Main corridor, where BASF and specialty chemical clusters anchor captive supply relationships with oral solid dosage leaders.
Micronized Powder Market Segmentation
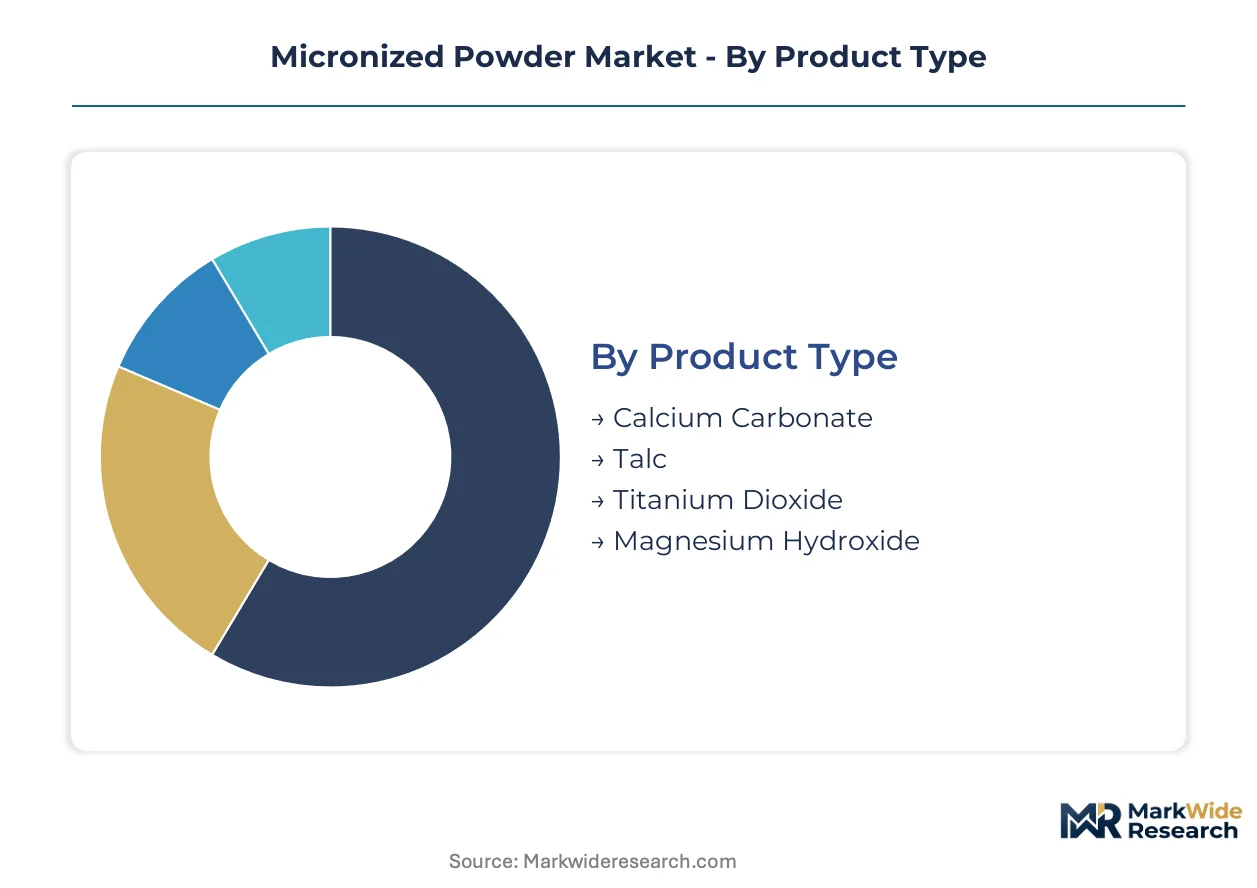
Micronized powder procurement channels diverge sharply by particle specification and end-use certification burden. Pharmaceutical formulators demand dedicated supply chains with validated particle-size documentation, while commodity fillers flow through distributor networks with minimal technical support.
Product Type:
Channel mix varies by mineral chemistry: titanium dioxide and magnesium hydroxide move predominantly through direct mill relationships, while calcium carbonate and talc retain stronger distributor presence due to broader customer fragmentation.
- Titanium Dioxide:Chloride-process rutile grades dominate coating applications requiring UV attenuation below 400nm. Pharmaceutical solubility projects in Germany and Switzerland are pulling anatase nano-grades into dedicated supply agreements with analytical-capable mills.
- Calcium Carbonate:Precipitated PCC variants engineered to 0.7-2.0 micron medians serve as functional fillers in polymer compounding. Plastics compounders in Gujarat and Ohio are consolidating procurement toward vertically integrated suppliers with captive limestone sourcing.
- Talc:Lamellar platy morphologies from Vermont and Luzenac deposits serve barrier applications in food packaging films.
- Magnesium Hydroxide:Halogen-free flame retardant specifications are displacing antimony trioxide in wire and cable sheathing across EU markets under RoHS constraints.
By volume, calcium carbonate leads. By growth pace, titanium dioxide nano-grades are climbing the fastest.
End Use Industry:
Customer type determines margin structure: pharmaceutical buyers absorb 40-60% price premiums for certified supply chains, while plastics processors negotiate on delivered cost per kilogram.
- Pharmaceuticals:Inhalable dry powder formulations demand engineered lactose carriers with tight particle-size distribution. CDSCO's manufacturing incentives are pulling micronized excipient production toward Hyderabad and Ahmedabad clusters.
- Plastics:Polypropylene and polyethylene compounding sustains baseline tonnage for calcium carbonate and talc fillers. Automotive lightweighting projects in Stuttgart and Detroit are specifying sub-5-micron grades for nucleation efficiency.
- Chemicals:Specialty catalyst supports and rheology modifiers require surface-modified powders with silane coupling agent treatments.
- Food & Beverage:Anti-caking applications for sodium bicarbonate and calcium silicate face tightening EFSA purity thresholds for heavy metal content.
Plastics commands the largest shipment volumes. Pharmaceuticals generates the steepest margin expansion trajectory.
Application:
Application focus dictates equipment investment: coating formulators prioritize jet milling capacity for pigment dispersion, while filler buyers emphasize air classification throughput.
- Fillers:Volume leadership in thermoplastic compounding depends on cost-efficient mechanical grinding rather than energy-intensive jet milling. Polypropylene automotive interior panels in Wolfsburg and Chattanooga specify 3-10 micron calcium carbonate for dimensional stability.
- Additives:Surface-modified wax and polymer micronizations for scratch resistance and slip control command premium positioning. Automotive clearcoat formulators are pivoting toward silica alternatives, compressing micronized wax volumes.
- Coatings:Titanium dioxide dispersion efficiency determines hiding power in architectural paints.
- Compounding:Masterbatch producers integrate micronized loads for color consistency and UV stabilization.
Fillers anchor volume throughput. Additives for advanced polymer systems are gaining share fastest.
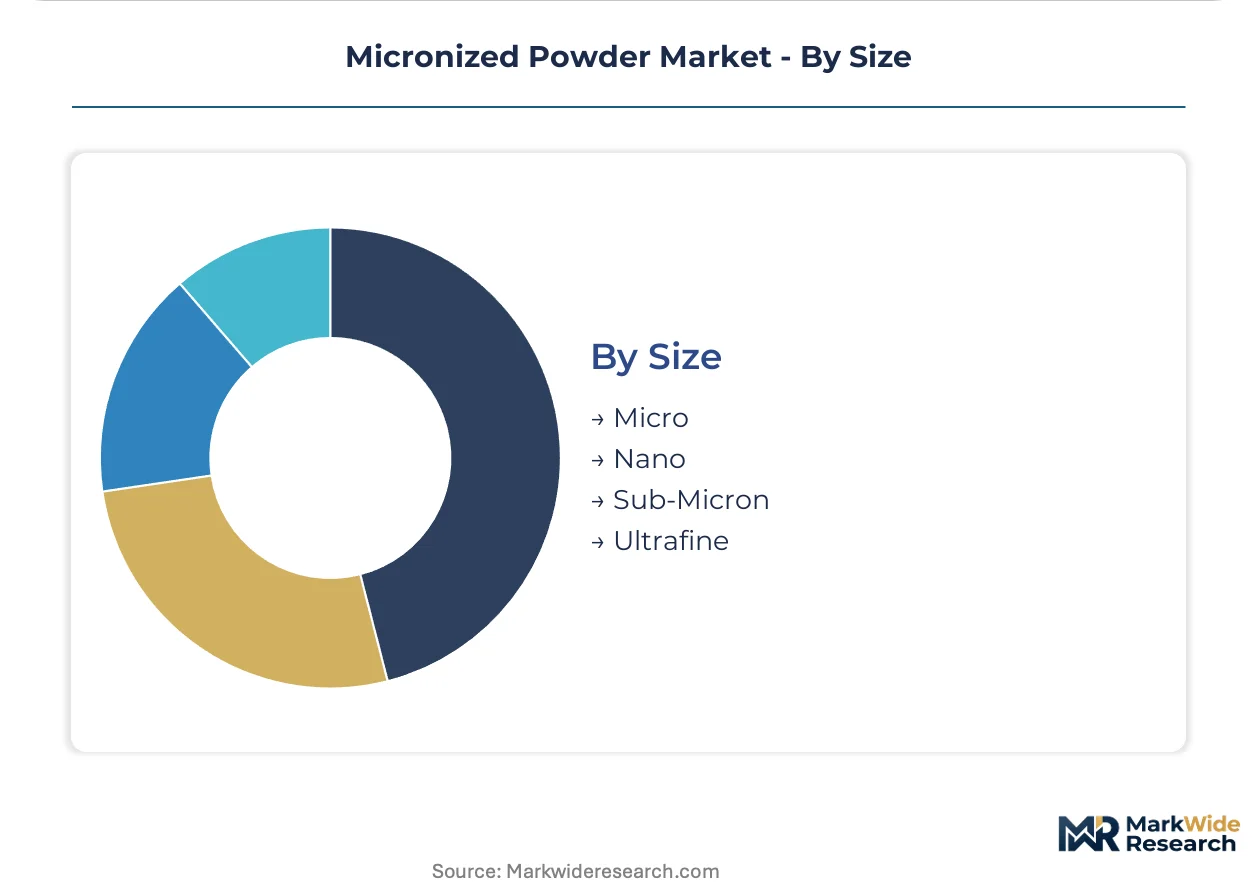
Size:
Size classification fragments supplier tiers: nano and sub-micron grades require capital-intensive analytical suites that exclude regional mills from pharmaceutical qualification.
- Nano:Sub-100nm materials trigger ECHA REACH nanoform registration with enhanced toxicity dossiers. Swiss and German analytical-capable mills are consolidating supply for pharmaceutical solubility enhancement.
- Sub-Micron:0.1-1.0 micron medians serve coating opacity and pharmaceutical bioavailability without full nanoform regulatory burden. Personal care sunscreen manufacturers in France and California specify this tier for UV attenuation compliance.
- Micro:1-10 micron grades dominate commodity filler applications with minimal regulatory overhead.
- Ultrafine:Precision-cut boundaries below 5 microns target inhalable drug delivery and specialty coating markets.
Micro grades dominate shipment volumes. Nano specifications are expanding most quickly under pharmaceutical demand pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor's high-voltage grid interconnect and chemical pipeline networks underpin Germany's dominance in pharmaceutical-grade micronized powder processing. Jet milling clusters in Hesse and Baden-Württemberg leverage this infrastructure for dedicated excipient supply to oral solid dosage manufacturers.
United States
Dry powder inhaler formulation demand from Boston and Research Triangle Park biotech clusters drives micronized lactose carrier specifications. EPA's TSCA Section 8(a) reporting rule for nanoscale substances tightens manufacturing record-keeping for titanium dioxide producers. Coating formulators in Ohio and Pennsylvania dual-source from EPA-registered domestic mills and validated EU imports to hedge permitting delays.
Germany
Specialty chemical demand from Stuttgart automotive lightweighting projects specifies sub-5-micron calcium carbonate for polypropylene nucleation. ECHA REACH registration requirements for nanoform substances mandate enhanced toxicity dossiers that filter out smaller suppliers. The Rhein-Main corridor anchors captive supply relationships between analytical-capable mills and multinational drug manufacturers through three-to-five-year offtake contracts.
India
CDSCO's phased API and excipient manufacturing incentives pull micronized cellulose and starch derivative production toward Gujarat and Hyderabad clusters. BIS standards for pharmaceutical-grade mineral excipients are tightening purity thresholds for heavy metal content. Ahmedabad's specialty chemical infrastructure is upgrading laser diffraction and electron microscopy suites to meet export certification requirements.
Switzerland
Specialty injectable formulators in Basel and Zurich adopt supercritical CO2 micronization for thermolabile API crystals. Swissmedic guidance on nanomaterial-containing drug products tightens documentation burdens for pharmaceutical-grade inputs. The country's precision milling infrastructure consolidates supply for pharmaceutical solubility enhancement under ECHA REACH nanoform compliance.
China
Chloride-process pigment-grade titanium dioxide concentration in coastal smelters exposes coating-formulator margins to energy-driven price swings. MEE oversight of nanoparticle environmental release shapes manufacturing site permitting and wastewater treatment investments. Shandong and Jiangsu provinces house vertically integrated suppliers with captive limestone sourcing for calcium carbonate filler production.
Micronized Powder Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialty milling specialists. The supplier base fragments across three tiers: integrated pigment and additive producers, proprietary technology specialists, and regional mechanical grinding operations. Two strategic archetypes dominate: analytical-capable mills serving pharmaceutical certification chains, and volume-driven fillers suppliers for plastics compounding. Competitive moves center on long-term offtake contracting for dedicated capacity and supercritical CO2 technology licensing for thermolabile applications.
Among diversified chemical conglomerates, BASF SE and Clariant exemplify the integrated archetype with positions spanning pigment, additive, and excipient portfolios. Micro Powders, Inc. occupies a specialist tier focused on proprietary wax and polymer micronization technology. These three entities represent the competitive spectrum from scale-driven commodity supply to precision-certified pharmaceutical channels.
| Leading Market Players |
|---|
| BASF SE |
| Micro Powders, Inc. |
| Clariant |
| The Chemours Company |
| Daikin Industries, Ltd. |
| 3M |
| Imerys |
| Asbury Carbons |
| AMG |
| Others |
Value Network & Pricing Analysis
ECHA REACH nanoform registration requirements gate both pharmaceutical-grade supplier qualification and the 40-60% price premiums that certified mills command over commodity filler producers, compressing procurement toward analytical-capable operations in Germany and Switzerland while regional mechanical grinding operations compete on delivered cost per kilogram.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and particle-size specification. Pharmaceutical formulators absorb steep premiums for validated supply chains with laser diffraction documentation, while plastics compounders negotiate on volume scale and geographic delivery cost. Price erosion runs through commodity calcium carbonate fillers as vertically integrated suppliers with captive limestone sourcing compress regional mill margins. Coating formulators exhibit highest price sensitivity due to titanium feedstock volatility, whereas inhalable drug developers show least sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
China and Germany anchor titanium dioxide pigment production, with chloride-process concentration in Chinese coastal smelters and pharmaceutical-grade nano milling clustered in the Rhein-Main corridor. Raw material dependencies center on rutile ore feedstock, halogen-free flame retardant precursors, and lamellar talc deposits. Single-source vulnerability concentrates in Chinese titanium smelter concentration exposed to energy-driven export quota unpredictability. Distribution runs through direct mill relationships for certified pharmaceutical grades and distributor networks for commodity fillers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical excipient supply chains are consolidating around dedicated milling capacity, creating platform-economics dynamics where EFSA and Swissmedic interoperability on nanomaterial documentation standards enables cross-border supplier qualification portability.
For Market Incumbents: Shield analytical-capable capacity through three-to-five-year offtake contracting with oral solid dosage leaders, locking out commodity competitors from pharmaceutical certification chains. Deepen backward integration into captive limestone sourcing for calcium carbonate fillers to defend against precipitated silica substitution in coating applications. For New Entrants and Emerging Players: Contract micronization services for thermolabile APIs represent the most penetrable white-space, as Swiss and Massachusetts injectable formulators adopt supercritical CO2 technology without in-house milling infrastructure. Target Gujarat and Hyderabad clusters where CDSCO manufacturing incentives are localizing excipient production ahead of analytical suite upgrades. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty milling specialists possessing ECHA REACH nanoform registration but lacking pharmaceutical customer relationships. Five-to-ten-year viability hinges on long-term offtake contract coverage ratios. Watch EPA TSCA Section 8(a) enforcement intensity as signal for US domestic capacity valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Captive pharmaceutical-grade capacity locks three-to-five-year offtake with oral solid dosage manufacturers in Germany. |
| Backward Integration | Captive limestone sourcing insulates calcium carbonate filler margins from regional raw material price volatility. |
| Green Manufacturing Transition | Nordic hydroelectric-powered jet milling gains cost advantage under EU Green Deal carbon border adjustment mechanisms. |
| Capacity Expansion | Dedicated excipient milling lines in Gujarat and Hyderabad capture CDSCO localization incentives for export certification. |
| Joint Venture | Swiss supercritical CO2 technology licensing partnerships enable distributed thermolabile API production near fill-finish sites. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at jet milling facilities, procurement leads at pharmaceutical formulators, and technical R&D directors at coating manufacturers; and secondary validation through ECHA REACH registration databases, FDA guidance documents on nanomaterial-containing drug products, and customs trade data on titanium dioxide pigment flows. Bottom-up capacity modeling triangulated against top-down end-use demand aggregation across pharmaceutical, plastics, and coating verticals.
Across the analysis window, value and volume outputs reflect segmented modeling by product type, end-use industry, application, and particle-size classification tier. CAGRs were derived from regression-based trajectory fitting against pharmaceutical pipeline expansion and automotive lightweighting content-per-vehicle trends. Forecast inputs incorporated EFSA purity threshold revisions and EPA TSCA Section 8(a) reporting compliance timelines.
Material uncertainties — regulatory registration delays, titanium feedstock export quota disruptions, and particle metrology talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions on certification standard harmonization and supercritical CO2 technology adoption curves. Recalibration cycles align with material shifts in ECHA nanoform guidance and CDSCO manufacturing incentive phase transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
United States Citric Acid Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Drilling Fluid Additives Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Anti-Creasing Agent Market
Additives
Anti Crystallizing Agents Market
Additives
Monocalcium Phosphate Market
Additives
Alginic Acid Market
Additives
High Performing Matting Agents Market
Additives
Global UV Absorbers Market
Additives
Volatile Corrosion Inhibitors Market
Additives
China Sodium Reduction Ingredient Market
Additives
Cetane Improver Additives Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Organic Friction Modifier Additives Market