
 Feedstuff Additives Market | 2026-2036
Feedstuff Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Feedstuff Additives Market Analytics
Direct procurement channels between additive manufacturers and integrated livestock operations is reshaping traditional distributor relationships in the feedstuff additives sector. Cargill, Incorporated leverages its captive grain supply chains to bundle premix solutions with feed ingredients, locking in volume commitments from large poultry integrators. BASF anchors its position through advanced enzyme R&D pipelines, while DSM-Firmenich differentiates via its combined nutritional and sensory science capabilities.
Feedstuff additives comprise biologically active substances—vitamins, minerals, enzymes, amino acids, and microbial cultures—formulated at ppm to percent-level inclusion rates to optimize animal metabolism, gut health, and feed conversion efficiency. These compounds undergo spray-drying, microencapsulation, or fermentation-based production to ensure thermostability and intestinal release. Enzymes command the highest margin pools due to patent-protected strain development and dosage efficiency in phytase and non-starch polysaccharide applications. Probiotics represent the fastest-expanding category as regulatory pressure on antibiotic growth promoters intensifies across poultry and swine operations. Powder formulations dominate ruminant and swine premix blending, while liquid delivery gains traction in automated aquaculture feeding systems.
The EU Green Deal's Farm to Fork strategy and REACH chemical registration requirements constrain novel additive introduction timelines, while the FDA's Veterinary Feed Directive and China's Ministry of Agriculture GB standards govern antibiotic alternative claims and residue limits. Brazil's MAPA and India's FSSAI impose parallel import and safety certification regimes that fragment market access protocols. Stakeholders must monitor evolving strain registration pathways and dual-labeling requirements as regulatory divergence between major producing regions deepens.
Market Dynamics
Precision nutrition programs are forcing additive suppliers to recalibrate formulation services around real-time metabolic data streams from commercial livestock operations rather than static premix specifications.
Growth Catalysts
- EU Green Deal antibiotic reduction mandates:The Farm to Fork strategy tightens veterinary medicinal product restrictions, compelling poultry and swine integrators to accelerate enzyme and probiotic substitution timelines.
- Brazil's industrial feed expansion:Integrated producers in Mato Grosso and Paraná scale automated mill operations, concentrating demand for thermostable phytase and direct-fed microbial formulations.
- Microencapsulation advances:Spray-drying and lipid-coating technologies improve intestinal release profiles for acidifiers and essential oils, extending application into ruminant nutrition.
Market Restraints
- Feed-grade vitamin input volatility:Synthesis of choline chloride and vitamin E precursors depends on petrochemical and palm oil derivatives, exposing margins to energy commodity swings.
- Strain registration pathway fragmentation:Divergent approval timelines between EFSA novel food processes, FDA GRAS determinations, and China's Ministry of Agriculture GB standards delay multi-territory probiotic launches.
- Phytase commoditization pressure:Patent expiration on first-generation fungal and bacterial strains enables generic manufacturing, compressing margin pools for enzyme specialists.
Strategic Opportunities
- India's FSSAI feed safety modernization:Mandatory contaminant testing and GMP certification requirements create upgrade demand for quality-assured premix and additive suppliers.
- Aquaculture liquid delivery systems:Automated feeding platforms in Norwegian and Chilean salmon operations favor water-soluble enzyme and amino acid formulations over powder alternatives.
- Carbon accounting integration:CSRD and GHG Protocol alignment enables feed additive positioning around methane reduction claims for ruminant operations.
Industry Challenges
- Strain stability expertise scarcity:Formulation chemists capable of optimizing thermotolerance for pelleting temperatures above 85°C remain concentrated among legacy enzyme developers.
- Dual-labeling compliance burden:Simultaneous satisfaction of EU organic feed regulations and conventional safety certifications requires parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feedstuff Additives Market |
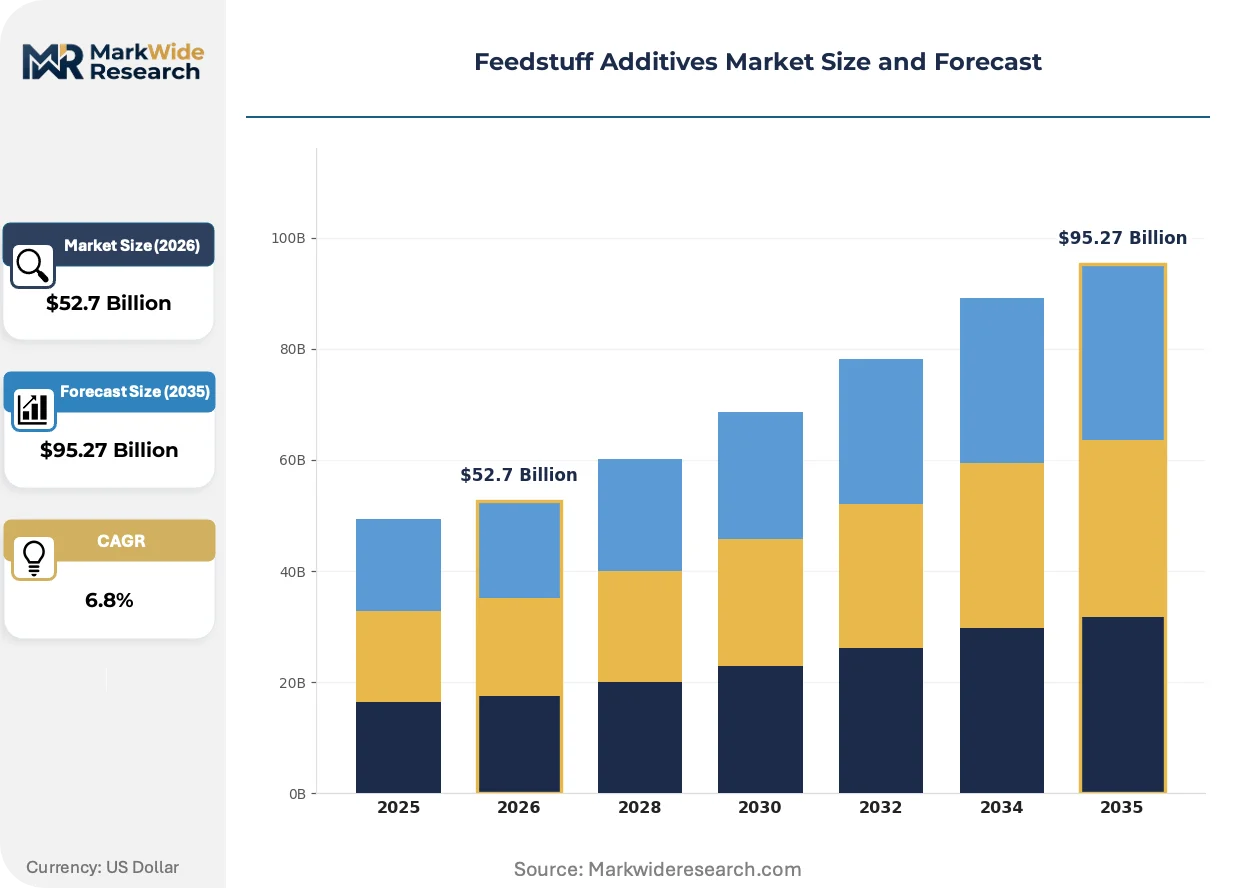
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Enzymes, Probiotics Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granular, Pellet Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Cargill, Incorporated, ADM, BASF, Evonik Industries AG, DSM-Firmenich, International Flavors & Fragrances Inc, Nutreco, Adisseo, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feedstuff Additives Market Evolving Landscape
Livestock integrators now demand additive solutions that integrate with precision feeding algorithms and environmental monitoring systems, collapsing the traditional separation between nutrition and data services.
CRISPR-edited microbial strains with enhanced bile acid resistance and substrate specificity are rendering obsolete first-generation probiotic cocktails that relied on undefined culture mixtures. Danish and Dutch swine integrators have adopted these next-generation formulations across nucleus and multiplier herds. The technology compresses the competitive window for suppliers lacking in-house strain development capabilities.
REACH chemical registration requirements and the EU F-Gas Regulation's fluorinated greenhouse gas phase-down are forcing reformulation of solvent-based extraction processes for natural antioxidant and pigment additives. Manufacturers must validate alternative carrier systems or face exclusion from European premix supply chains. This regulatory pressure falls most heavily on carotenoid and tocopherol suppliers sourcing from tropical botanicals.
Direct contracting between additive manufacturers and integrated livestock operations is disintermediating traditional distributor networks in Brazil's Center-West and Southeast feed corridors. Volume commitments now bundle multi-year premix supply with technical advisory services and on-farm formulation optimization. The shift concentrates procurement leverage among the ten largest poultry and swine producers in Paraná and Santa Catarina states.
Feedstuff Additives Market Segmentation
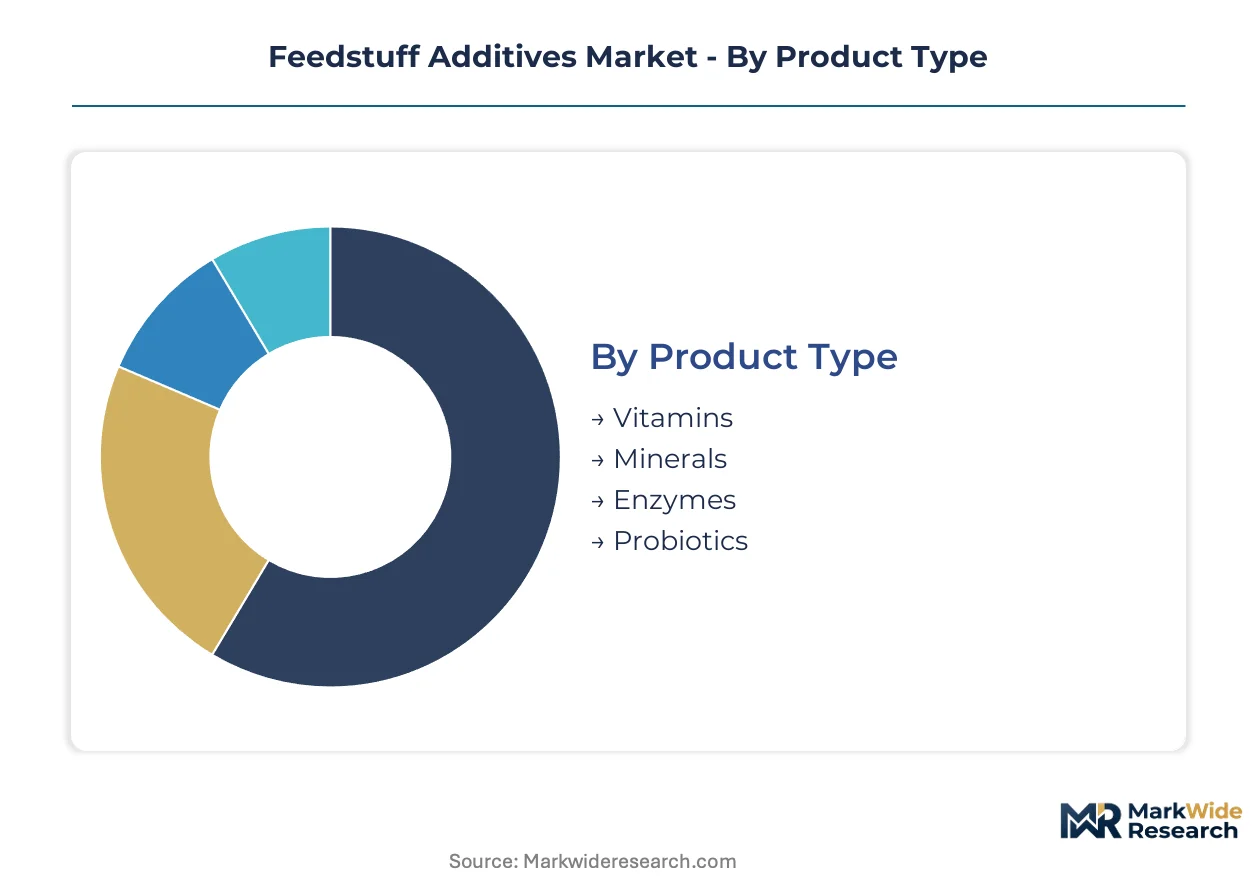
Feedstuff additive suppliers must align formulation portfolios against distinct metabolic requirements across livestock species and delivery constraints imposed by mill equipment and climate conditions. Segmentation discipline separates commodity vitamin premixes from high-margin enzyme technologies while mapping channel preferences that diverge between integrated operations and independent farms.
Product Type:
Mature vitamin and mineral categories face margin compression from Chinese synthesis capacity, while emerging enzyme and probiotic segments command premium positioning through strain IP and regulatory substitution tailwinds.
- Enzymes:Phytase and non-starch polysaccharide formulations deliver phosphorus release and fiber degradation at inclusion rates below 500 grams per ton. Poultry integrators in Brazil's Mato Grosso state concentrate procurement of thermostable variants that withstand conditioning temperatures above 85°C. Patent-protected bacterial strains sustain margin pools despite generic competition on first-generation fungal platforms.
- Probiotics:Direct-fed microbial cultures—Bacillus subtilis, Lactobacillus, and yeast-based formulations—colonize gut epithelium to displace antibiotic growth promoters. EU Green Deal antibiotic reduction mandates accelerate substitution timelines across Danish and Dutch swine operations. CRISPR-edited strains with enhanced bile acid resistance are displacing undefined culture cocktails in nucleus herd applications.
- Vitamins:Fat-soluble (A, D, E, K) and water-soluble (B-complex, C) premixes stabilize metabolic function at ppm inclusion rates.
- Minerals:Trace elements (zinc, copper, selenium) and macro-minerals (calcium, phosphorus) correct dietary deficiencies in region-specific soil-depletion contexts.
Enzymes handle the majority of throughput; probiotics are gaining share fastest on regulatory substitution demand.
Application:
Volume concentration varies by species intensity—poultry and swine operations drive formulation standardization, while ruminant and aquaculture applications demand customized delivery systems.
- Poultry:Broiler and layer operations consume phytase-dense premixes to maximize feed conversion ratios in high-density housing systems. Automated feed mills across Brazil's Paraná state standardize on powder enzyme blends.
- Swine:Nursery and grow-finish phases require acidifier and probiotic combinations to manage post-weaning gut integrity. EU antibiotic restrictions force reformulation of starter diets across German and Spanish integrators.
- Ruminants:Methane-reducing feed additives—3-nitrooxypropanol and red seaweed extracts—target dairy and beef operations under CSRD carbon accounting pressure.
- Aquaculture:Salmon and shrimp producers in Norway and Chile favor liquid amino acid and enzyme delivery through automated feeding platforms.
Poultry commands the largest volume base; aquaculture is climbing the fastest on intensive production expansion.
Form:
Physical presentation determines process compatibility—thermal stability requirements separate powder and granular formats from liquid systems.
- Powder:Spray-dried and microencapsulated formulations dominate premix blending for ruminant and swine applications where pelleting temperatures remain moderate.
- Liquid:Water-soluble concentrates integrate with automated aquaculture feeding systems and on-farm dosing equipment for acidifiers and essential oils.
- Granular:Agglomerated particles improve flowability and reduce dust exposure in high-throughput mill operations.
- Pellet:Pre-formed additive matrices withstand extreme conditioning temperatures in shrimp and fish feed extrusion.
Powder maintains the dominant share position; liquid is expanding most quickly on aquaculture automation adoption.
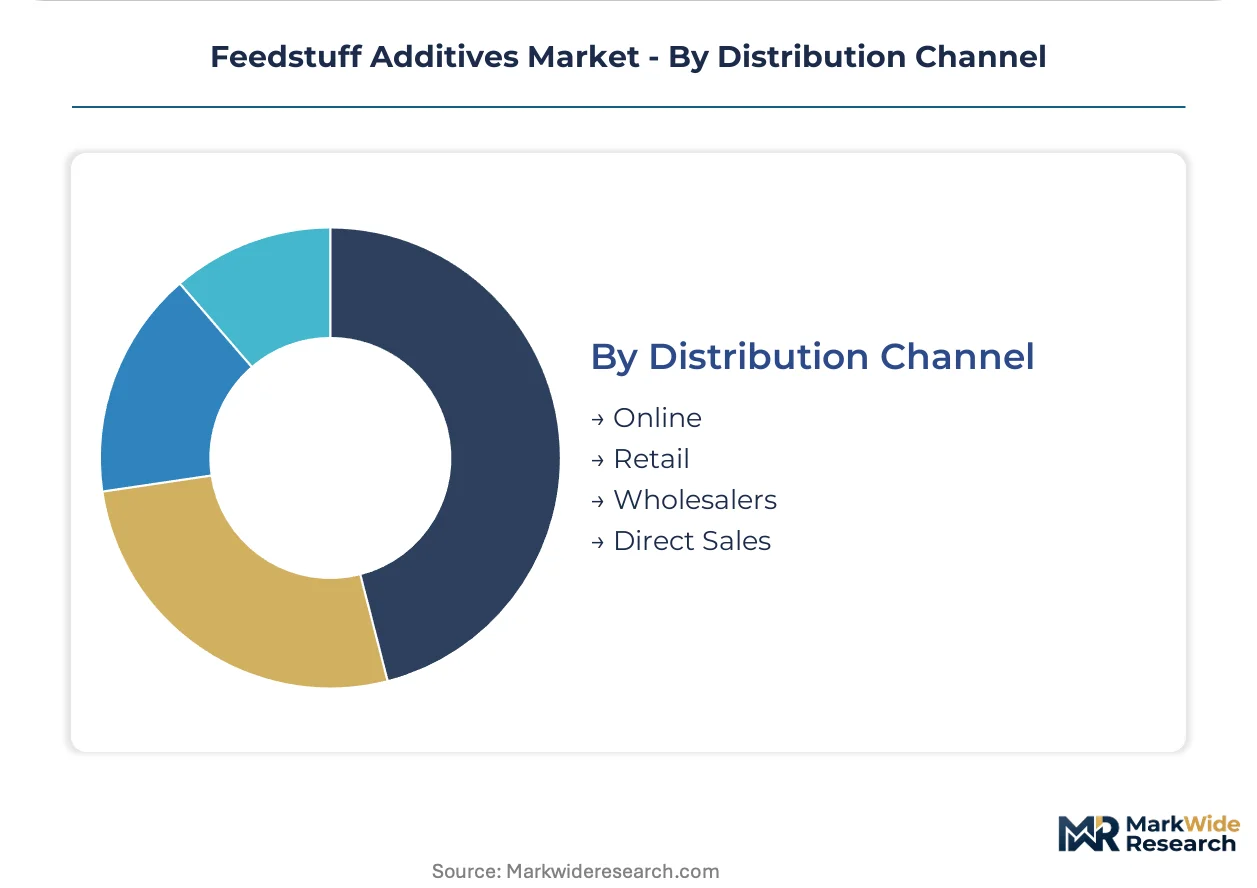
Distribution Channel:
Channel selection reflects customer scale—direct relationships concentrate among integrated operations while independent farms persist through wholesale and retail networks.
- Direct Sales:Additive manufacturers contract volume commitments with Brazil's ten largest poultry and swine integrators, bundling premix supply with technical advisory services.
- Wholesalers:Regional distributors serve independent feed mills and smaller livestock operations across India's FSSAI-regulated markets.
- Retail:Farm supply cooperatives and veterinary clinics supply micronutrient packs to hobby farmers and specialty breeders.
- Online:E-procurement platforms gain traction among mid-scale operations seeking price transparency on commodity vitamin and mineral premixes.
Direct sales capture the highest volume concentration; online channels are advancing fastest on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's feed additive import infrastructure, handling bulk enzyme and vitamin shipments for Mato Grosso and Paraná feed mill corridors. This maritime gateway concentrates procurement leverage among integrated poultry and swine operations.
Brazil
Industrial feed expansion in Mato Grosso and Paraná states concentrates thermostable phytase demand from automated mill operations. MAPA's import certification requirements fragment market access protocols for probiotic strain registrations. Direct contracting between additive manufacturers and the ten largest poultry integrators in Santa Catarina state is disintermediating traditional distributor networks.
United States
Precision nutrition programs across Iowa and North Carolina livestock belts force additive suppliers to recalibrate formulation services around real-time metabolic data streams. The FDA's Veterinary Feed Directive governs antibiotic alternative claims and residue limits in commercial operations. DSM-Firmenich and Cargill leverage captive grain supply chains to bundle premix solutions with feed ingredients in the Corn Belt.
Germany
EU Green Deal antibiotic reduction mandates accelerate enzyme and probiotic substitution timelines across Lower Saxony and Bavaria swine operations. EFSA novel food processes and REACH chemical registration requirements constrain novel additive introduction timelines. BASF anchors its position through advanced enzyme R&D pipelines in Ludwigshafen.
China
Feed-grade vitamin synthesis capacity in Shandong and Jiangsu provinces exposes margins to petrochemical and palm oil derivative swings. The Ministry of Agriculture's GB standards govern antibiotic alternative claims and residue limits. Strain registration pathway fragmentation between EFSA, FDA, and Chinese regulators delays multi-territory probiotic launches for domestic suppliers.
India
FSSAI feed safety modernization creates upgrade demand for quality-assured premix and additive suppliers across Maharashtra and Gujarat poultry belts. Mandatory contaminant testing and GMP certification requirements reshape procurement patterns among independent feed mills. Regional distributors serve smaller livestock operations in Haryana and Telangana through wholesale networks.
Feedstuff Additives Market Competitive Landscape
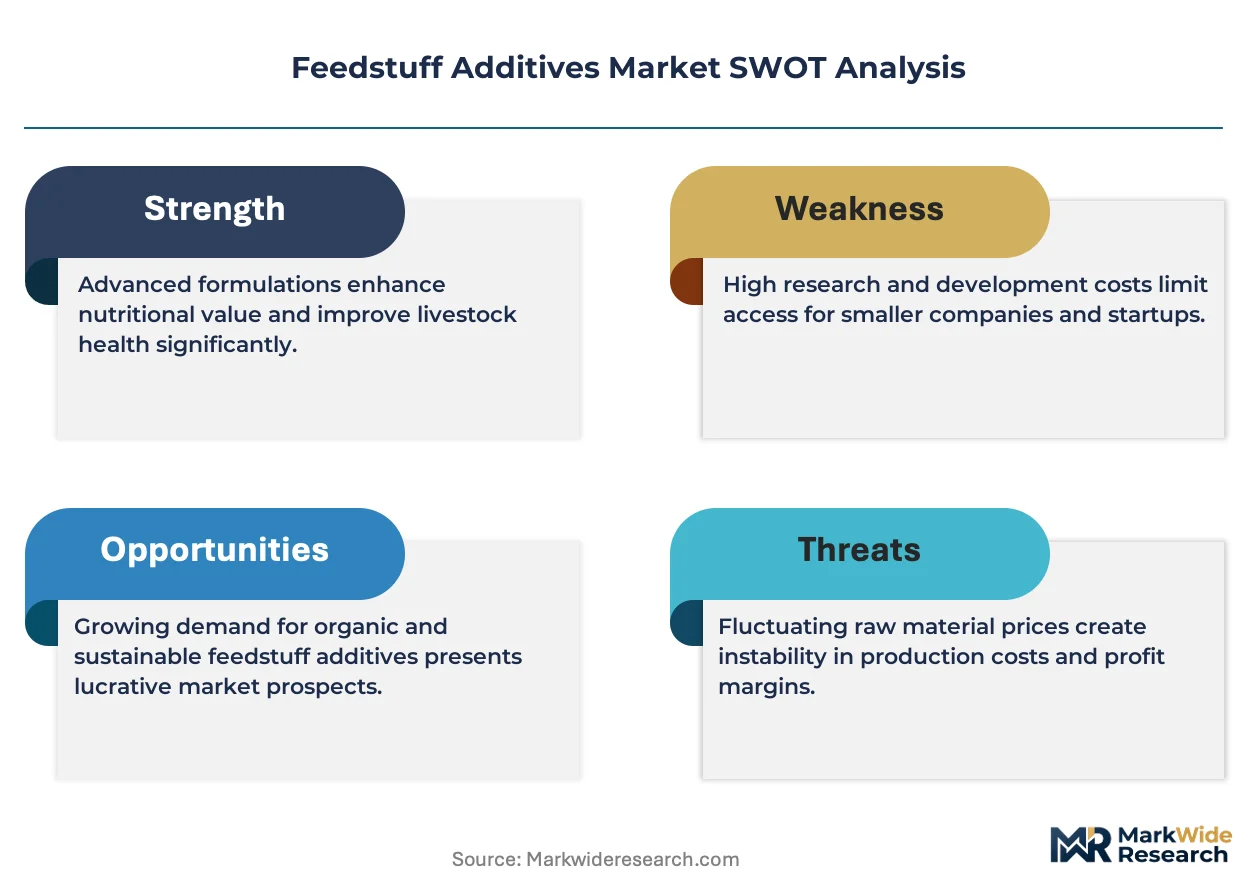
Platform integrators command the system tier; component specialists sit upstream with strain IP and dosage efficiency. The feedstuff additives sector consolidates around three strategic tiers: multinational nutrition platforms with captive supply chains, enzyme specialists with patent-protected bacterial strains, and regional premix blenders serving independent mills. Dominant competitive moves include direct contracting with integrated livestock operations and microencapsulation technology licensing for thermostability above 85°C.
Within the multinational platform tier, Cargill, Incorporated and BASF exemplify divergent strategic anchors. Cargill leverages its captive grain supply chains to bundle premix solutions with feed ingredients, locking in volume commitments from large poultry integrators. BASF occupies a position defined by advanced enzyme R&D pipelines and patent-protected strain development. Among specialty nutrition players, DSM-Firmenich represents the combined nutritional and sensory science capabilities archetype, differentiating through dual-domain expertise.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| BASF |
| Evonik Industries AG |
| DSM-Firmenich |
| International Flavors & Fragrances Inc |
| Nutreco |
| Adisseo |
| Alltech |
| Others |
Value Network & Pricing Analysis
Chinese synthesis capacity for feed-grade vitamins and amino acids anchors upstream supply, compressing margin pools for premix blenders in Europe and North America while concentrating pricing power among integrated nutrition platforms with captive fermentation assets.
Pricing Analysis
Volume-discount tiering structures separate procurement contracts for Brazil's ten largest poultry integrators from independent feed mill spot purchases. Three-tier pricing stratifies across patent-protected enzyme strains, quality-assured vitamin premixes, and commodity mineral blends. Pricing pressure stems from generic phytase manufacturing following patent expiration on first-generation fungal platforms. Independent mills exhibit highest price sensitivity due to working capital constraints, while integrated operations trade price for multi-year technical advisory bundles.
Supply Chain Analysis
Extended payment terms from integrated livestock operations strain working capital for regional premix blenders, forcing reliance on supply-chain finance facilities. Raw material sourcing draws from Chinese vitamin synthesis clusters, Indian botanical extractors for natural antioxidants, and Brazilian fermentation capacity for direct-fed microbials. Single-source vulnerability concentrates in thermostable strain development expertise held by legacy enzyme developers. Distribution runs through direct manufacturer contracts with industrial integrators alongside wholesale networks serving independent operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution by CRISPR-edited microbial strains displacing undefined probiotic cocktails, as regulatory pressure on antibiotic growth promoters accelerates formulation turnover.
For Market Incumbents: Build patent-protected strain moats through CRISPR-edited microbial development with enhanced bile acid resistance. Deepen backward integration into captive fermentation capacity to secure thermostable phytase supply. Lock in multi-year direct contracts with Brazil's largest poultry integrators before generic enzyme manufacturers capture volume.
For New Entrants and Emerging Players: Build out microencapsulation service capabilities targeting ruminant acidifier applications where thermotolerance requirements exceed 85°C. India's FSSAI modernization creates penetrable white space among independent feed mills seeking GMP-certified premix suppliers. Lead with contaminant testing compliance as the go-to-market wedge.
For Investors and Strategic Acquirers: Capital is best deployed toward enzyme specialists with patent-protected bacterial strain libraries and demonstrated EFSA novel food registration success. Long-term viability hinges on regulatory substitution tailwinds persisting across EU and Brazilian antibiotic reduction mandates. Watch for consolidation signals when MAPA strain registration delays force smaller probiotic developers toward exit.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Development Program | Patent-protected microbial engineering displaces undefined culture cocktails in EU swine operations. |
| Direct Contracting with Integrators | Brazil's ten largest poultry producers now bundle premix supply with technical advisory services. |
| Microencapsulation Technology Licensing | Thermostability above 85°C extends acidifier applications into ruminant pelleting processes. |
| FSSAI Certification Investment | Mandatory GMP compliance reshapes procurement among India's independent feed mill base. |
| Carbon Accounting Integration | CSRD alignment enables methane-reducing additive positioning for dairy operations under GHG Protocol. |
Research Methodology
Cross-validation between primary interviews with enzyme R&D directors, livestock integration nutritionists, and MAPA regulatory affairs specialists anchors the qualitative findings against secondary validation from EFSA novel food registrations, REACH chemical dossiers, and Brazilian customs trade data. Bottom-up triangulation across premix blender production volumes and top-down reconciliation against integrated livestock operation feed consumption estimates ensures segmentation integrity.
Calibration against historical patent expiration cycles and regulatory substitution timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, livestock species application, physical formulation, and distribution channel concentration. CAGRs derive from elasticity modeling of enzyme inclusion rates against feed grain price volatility and regulatory enforcement intensity in major producing regions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese vitamin synthesis clusters or accelerated CRISPR strain adoption by Danish swine integrators would shift outcomes. Macroeconomic commodity swings, divergent strain registration timelines between EFSA and FDA, or technological breakthroughs in methane-reducing feed additives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Performance Additives Market
Additives
Phthalate Plasticizer Market
Additives
China Sodium Reduction Ingredient Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
North America Pectin Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Anti-Block Additives Market
Additives
Organic Dispersants Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Organic Friction Modifier Additives Market
Additives
Green Polymer Additive Market
Additives
Friction Modifier Additives Market
Additives
Paint Additives Market
Additives
Fluoropolymer Additives Market
Additives
Butyrate Additives Market
Additives
United Kingdom Feed Additives Market