
 Global Phone Car Mounts Market | 2026-2036
Global Phone Car Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phone Car Mounts Market Outlook
Asset-light manufacturing through third-party OEM leasing is fragmenting competitive dynamics in the phone car mounts sector. iOttie leverages direct-to-consumer channel control to sustain premium positioning in North American markets. Baseus anchors cost-efficient aluminum vent mount production through Shenzhen-based contract networks. Spigen differentiates via material science specialization in silicone-dampened magnetic assemblies.
Phone car mounts are mechanical or magnetic retention devices engineered to secure mobile electronics to vehicle interiors, typically incorporating neodymium magnet arrays, thermoplastic elastomer grips, or vacuum-assisted suction mechanisms rated for temperature cycling between minus twenty and plus eighty degrees Celsius. Their primary commercial purpose is to enable compliant hands-free navigation and communication while reducing driver distraction. Magnetic mounts lead volume shipments due to Apple MagSafe ecosystem proliferation, while suction cup variants retain margin pools in commercial fleet retrofit applications. Aluminum material grades command pricing premiums over commodity ABS plastic in European aftermarket channels.
The EU General Safety Regulation and NHTSA distraction guidelines jointly shape product compliance requirements for dashboard placement geometry and release-force thresholds. China's SAMR enforces GB standard adherence for magnetic field exposure in consumer automotive accessories. Stakeholders must monitor evolving OEM embedded mount integration strategies as vehicle original equipment manufacturers internalize smartphone docking functionality.
Market Dynamics
Magnetic ecosystem standardization around neodymium arrays and MagSafe compatibility protocols is compressing product differentiation cycles while amplifying volume concentration among contract manufacturers with precision magnetization capabilities.
Growth Catalysts
- EU General Safety Regulation:Mandated hands-free device integration for new vehicle types creates compliant placement requirements that standardize mount geometry specifications across OEM supply chains.
- Ride-hailing fleet expansion:Southeast Asia's Grab, Gojek, and Bolt operators are deploying dual-mount configurations per vehicle to support driver-partner navigation and payment verification workflows.
- Thermoplastic elastomer grip advancement:Injection-molded TPE compounds rated for minus twenty to plus eighty degrees Celsius temperature cycling are extending product replacement intervals in extreme climate zones.
Market Restraints
- Neodymium supply concentration:Rare earth magnet processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing procurement to export quota volatility and geopolitical friction.
- GB standard magnetic field limits:China's SAMR enforces strict Tesla exposure thresholds for consumer automotive accessories, requiring redesign of high-strength magnetic arrays for domestic market entry.
- Embedded OEM integration:Vehicle manufacturers including BMW and Mercedes-Benz are internalizing smartphone docking into dashboard infotainment modules, displacing aftermarket attach rates in premium vehicle segments.
Strategic Opportunities
- Commercial fleet retrofit demand:Last-mile delivery operators in Brazil and Mexico are standardizing suction-cup mount specifications for vehicle model heterogeneity in aging fleet pools.
- Wireless charging convergence:Qi2 magnetic power transfer alignment is merging power delivery with mechanical retention, collapsing two accessory categories into unified product architectures.
- India BIS certification pathway:Mandatory quality control order implementation for automotive electronics accessories is creating first-mover advantage for certified suppliers in organized retail channels.
Industry Challenges
- Release-force calibration complexity:NHTSA distraction guidelines specify dashboard placement geometry and single-hand release thresholds that conflict with magnetic retention strength requirements in high-vibration commercial vehicles.
- Aluminum grade certification timelines:European aftermarket channels demand 6061-T6 alloy traceability documentation that extends supplier qualification cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phone Car Mounts Market |
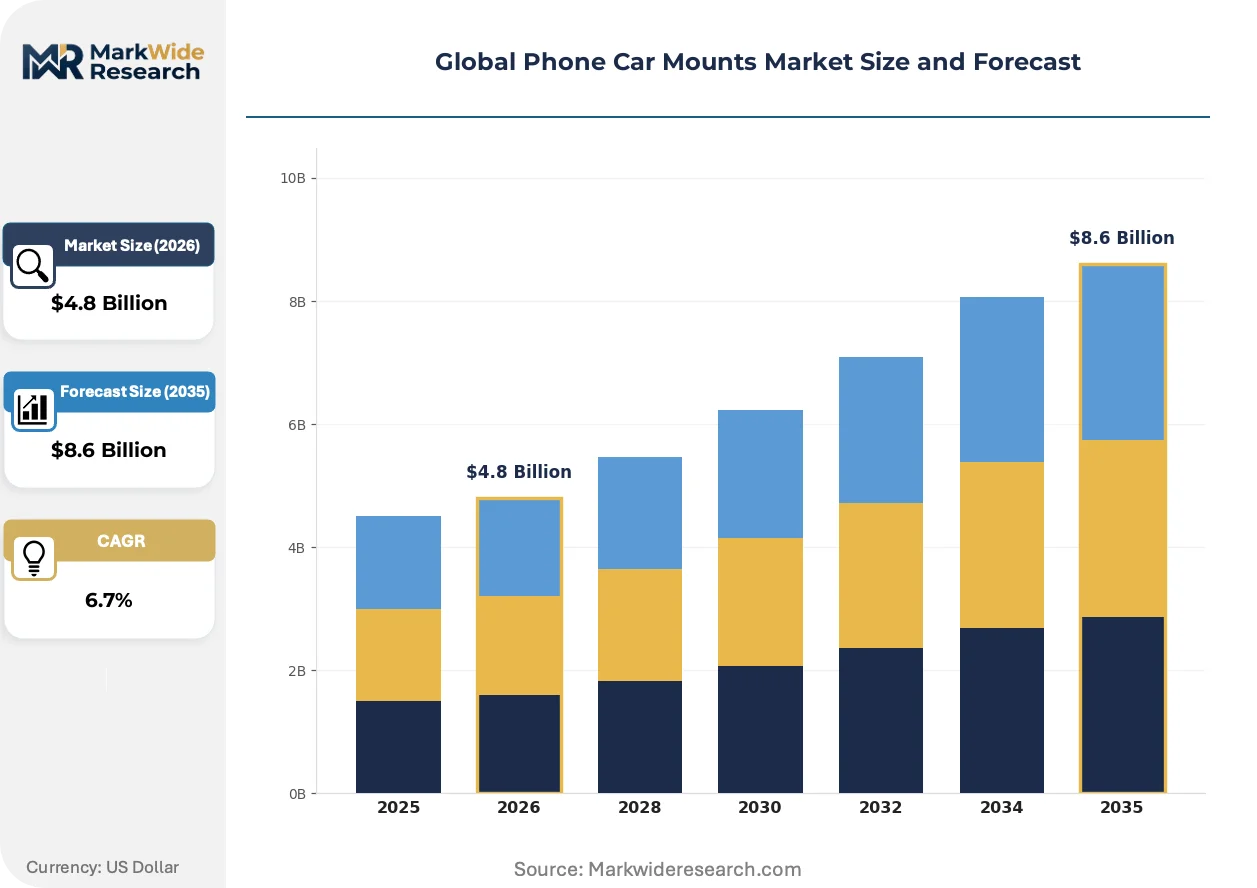
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Mounts, Suction Cup Mounts, CD Slot Mounts, Vent Mounts Material: Plastic, Aluminum, Silicone, Rubber Compatibility: Smartphones, GPS Devices, Tablets, Others Distribution Channel: Retail Stores, Online Channels, Wholesalers, Distributors |
| Companies Covered | Belkin, iOttie, Scosche Industries, Arkon Mounts, Spigen, Baseus, Xiaomi, National Products Inc., Kenu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phone Car Mounts Market Strategic Shifts
Mount architecture is converging around modular magnetic cores that detach from vehicle-specific base plates, enabling SKU reduction while preserving customization depth for regional vehicle parc diversity.
Neodymium magnet arrays paired with ferrite shielding layers are virtualizing the traditional clamp mechanism entirely. Fleet operators in Indonesia and Vietnam are adopting these contactless retention systems for sanitation protocols in shared-vehicle environments. The shift is compressing mechanical component counts by sixty to seventy percent while shifting value capture toward magnetization process IP.
REACH substance restriction updates are phasing out certain plasticizer compounds in thermoplastic elastomer grips used across EU aftermarket channels. Compounders in Germany and the Netherlands are reformulating shore hardness specifications to maintain elasticity performance under revised chemical compliance boundaries. Vent mount variants with revised TPE formulations are commanding shelf space priority in French and Italian accessory retail.
Direct-to-consumer channel expansion is fragmenting traditional distributor relationships that previously controlled aftermarket placement. Chinese contract manufacturers including Baseus supply network participants are building proprietary storefront capacity on regional e-commerce platforms. This disintermediation is most visible in Southeast Asia where Shopee and Lazada storefront operations now capture thirty to forty percent of category volume.
Global Phone Car Mounts Market Segmentation
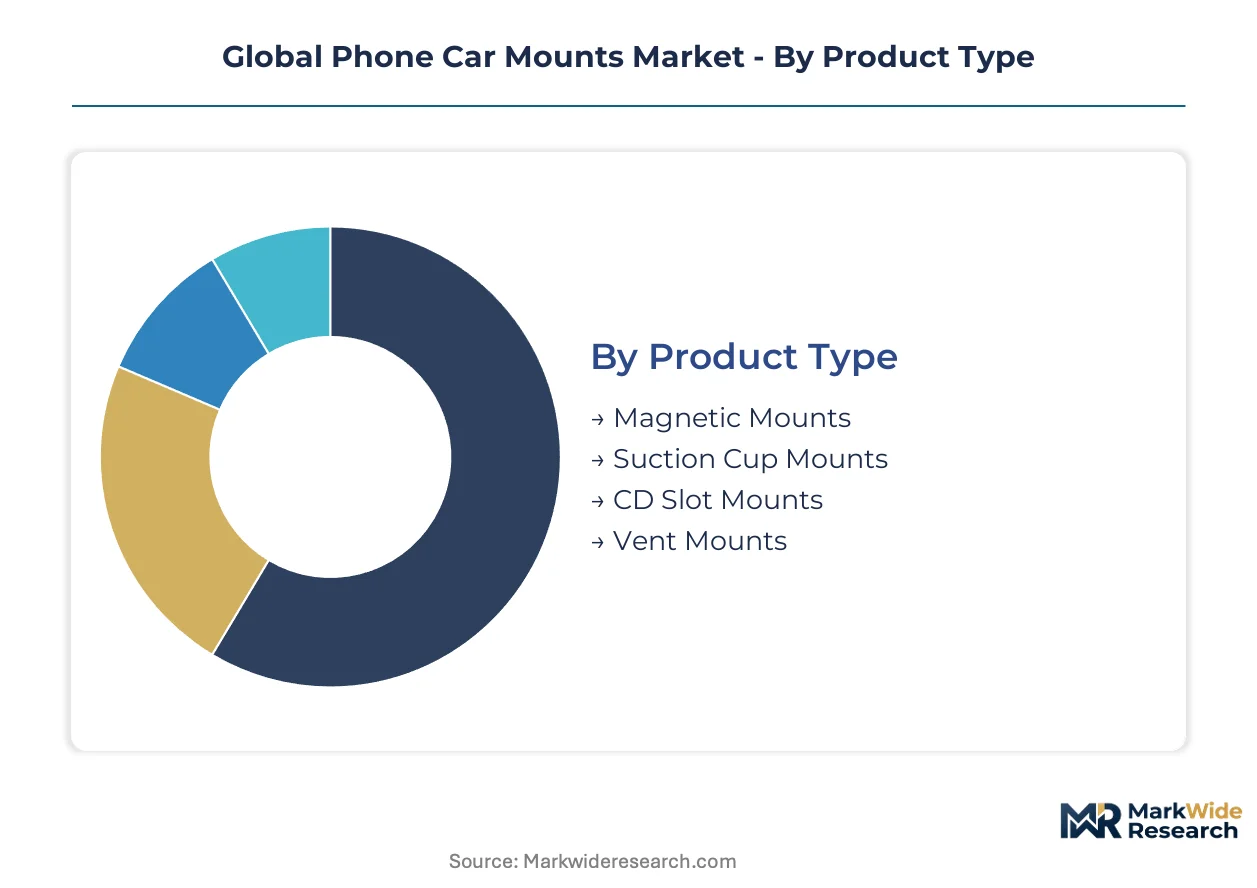
Product differentiation in phone car mounts hinges on retention mechanism physics, material thermal performance, and mounting surface geometry. Segmentation reveals how magnetic ecosystem standardization and fleet procurement standardization are reshaping category boundaries across consumer and commercial channels.
Product Type:
Mature suction cup designs coexist with emerging magnetic architectures as fleet operators and individual consumers diverge in retention priority.
- Magnetic Mounts:Neodymium magnet arrays paired with ferrite shielding enable contactless retention rated for minus twenty to plus eighty degrees Celsius temperature cycling. Demand concentrates in China's aftermarket accessory corridors around Shenzhen and Dongguan, driven by Apple MagSafe ecosystem proliferation and ride-hailing fleet dual-mount deployment per vehicle.
- Suction Cup Mounts:Vacuum-assisted mechanisms with thermoplastic elastomer gaskets retain margin pools in commercial fleet retrofit applications. Last-mile delivery operators in Brazil and Mexico standardize these specifications for vehicle model heterogeneity in aging fleet pools, prioritizing dashboard placement geometry compliance over magnetic field exposure concerns.
- CD Slot Mounts:Mechanical retention arms expanding into legacy dashboard apertures serve declining vehicle parc segments in European and North American markets.
- Vent Mounts:Aluminum and thermoplastic elastomer assemblies clip to HVAC louvers, with Baseus contract networks anchoring cost-efficient production through Shenzhen-based manufacturing clusters.
Magnetic Mounts retain volume leadership; Vent Mounts hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity polymer supply from certified alloy procurement cycles.
- Plastic:ABS and polycarbonate compounds dominate unit economics in mass-market channels, though REACH substance restriction updates are phasing out certain plasticizer compounds across EU aftermarket channels.
- Aluminum:6061-T6 alloy grades command pricing premiums in European aftermarket channels, with traceability documentation extending supplier qualification cycles. Spigen leverages material science specialization in aluminum-dampened assemblies for premium positioning.
- Silicone:Shore hardness reformulations maintain elasticity performance under revised chemical compliance boundaries in Germany and Netherlands compounding operations.
- Rubber:Natural and synthetic elastomer grips serve cost-sensitive segments with shorter replacement intervals in extreme climate zones.
Plastic retains volume leadership; Aluminum holds the steepest expansion curve.
Compatibility:
Device form factor divergence creates application-specific retention engineering requirements.
- Smartphones:Qi2 magnetic power transfer alignment merges power delivery with mechanical retention, collapsing charging and mounting into unified product architectures. EU General Safety Regulation mandates drive compliant placement requirements across OEM supply chains.
- GPS Devices:Dedicated navigation hardware retention persists in commercial fleet segments where smartphone battery dependency creates operational risk.
- Tablets:Larger form factor retention demands reinforced suction cup arrays or dual-point magnetic systems for dashboard stability.
- Others:Dashcams and handheld payment terminals occupy niche fleet retrofit specifications in Southeast Asian ride-hailing markets.
Smartphones retain volume leadership; Tablets hold the steepest expansion curve.
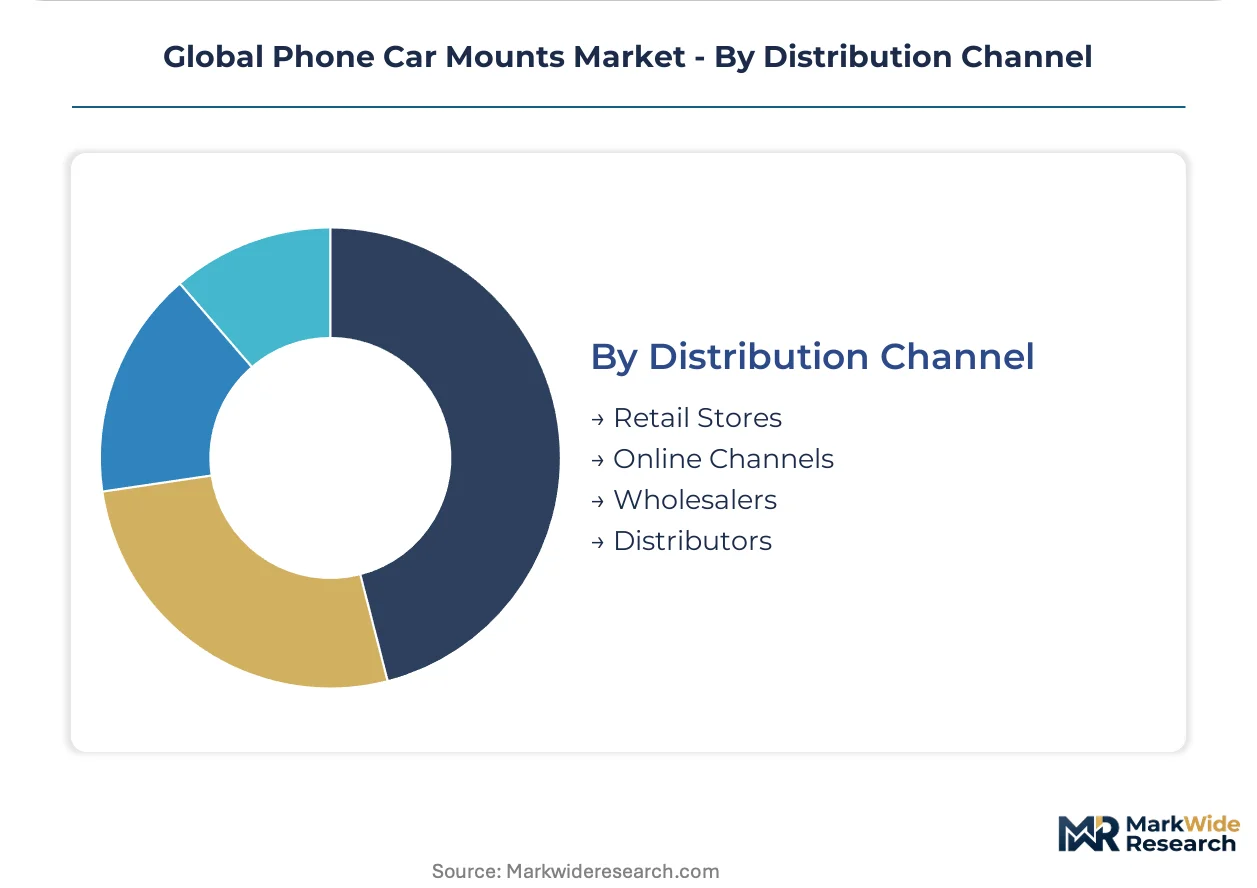
Distribution Channel:
Channel control fragmentation is disintermediating traditional distributor relationships across regional e-commerce platforms.
- Retail Stores:French and Italian accessory retail channels prioritize vent mount variants with revised TPE formulations under REACH compliance updates.
- Online Channels:Direct-to-consumer expansion captures thirty to forty percent of category volume in Southeast Asia through Shopee and Lazada storefront operations, with iOttie leveraging channel control for premium positioning.
- Wholesalers:Bulk procurement relationships serve organized retail channels in India where BIS certification creates first-mover advantage for certified suppliers.
- Distributors:Traditional placement control weakens as Chinese contract manufacturers build proprietary storefront capacity on regional platforms.
Online Channels retain volume leadership; Wholesalers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and ride-hailing platforms concentrate procurement in manufacturing corridors with established contract electronics capacity. Demand patterns diverge between aftermarket accessory channels and embedded OEM integration strategies.
United States
NHTSA distraction guidelines shape dashboard placement geometry requirements for domestic manufacturers. Premium direct-to-consumer channels capture significant volume through controlled storefront operations. California-based design houses specialize in magnetic array engineering for MagSafe ecosystem compatibility.
Germany
KBA vehicle certification processes intersect with EU General Safety Regulation implementation timelines. REACH substance restrictions drive thermoplastic elastomer reformulation among compounders in the Netherlands and Germany. Stuttgart and Munich automotive clusters influence embedded mount integration specifications for premium vehicle segments.
China
SAMR enforces GB standard magnetic field exposure limits for consumer automotive accessories. Shenzhen and Dongguan contract manufacturing networks anchor global production of aluminum vent mounts and neodymium magnet assemblies. Domestic aftermarket corridors serve expanding ride-hailing fleet deployment requirements.
Indonesia
Grab and Gojek operators standardize dual-mount configurations per vehicle for driver navigation and payment verification. National regulators monitor automotive electronics import compliance through quality certification pathways. Jakarta and Surabaya logistics corridors concentrate last-mile delivery fleet retrofit demand.
Brazil
ANVISA consumer product standards intersect with automotive accessory safety requirements for import authorization. Last-mile delivery operators in São Paulo standardize suction-cup mount specifications for aging fleet heterogeneity. Southeast manufacturing zones serve Mercosur distribution networks with cost-optimized plastic assemblies.
Global Phone Car Mounts Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans direct-to-consumer operators, contract manufacturing networks, and material science specialists. Three archetypes dominate: ecosystem-integrated magnetic specialists, cost-optimized aluminum fabricators, and silicone-dampened assembly engineers. Strategic moves concentrate on geographic storefront expansion and magnetization process IP development.
Within the premium-tier vector, iOttie occupies a position exemplifying channel control through North American direct-to-consumer operations. Baseus anchors cost-efficient production archetypes through Shenzhen-based contract network participation. Spigen represents material science specialization in silicone-dampened magnetic assemblies for European aftermarket channels.
| Leading Market Players |
|---|
| Belkin |
| iOttie |
| Scosche Industries |
| Arkon Mounts |
| Spigen |
| Baseus |
| Xiaomi |
| National Products Inc. |
| Kenu |
| Others |
Value Chain & Pricing Dynamics
Neodymium export quota volatility from China's Inner Mongolia and Jiangxi processing clusters compresses margin buffers across both premium magnetic assemblies and economy-grade vent mounts, forcing tiered pricing spreads that widen with magnetization precision requirements while concentrating procurement relationships among contract manufacturers with bonded warehouse access.
Pricing Analysis
Cost-plus contracts with neodymium price indexation dominate OEM supply relationships, while aftermarket channels operate on spot-adjusted transactional terms. Three-tier pricing structure across premium, standard, and economy levels separates MagSafe-certified magnetic arrays from uncertified alternatives and basic plastic vent clips. Price differentiation centers on GB standard magnetic field compliance certification and aluminum 6061-T6 alloy traceability documentation. Pricing pressure stems from embedded OEM integration by BMW and Mercedes-Benz displacing aftermarket attach rates. Fleet procurement teams in Southeast Asia exhibit highest price sensitivity; direct-to-consumer premium brands in North America show lowest.
Supply Chain Analysis
Neodymium feedstock draws from China's ion-adsorption clay deposits and Myanmar's heavy rare earth mines, with magnetization processing anchored in Shenzhen and Dongguan contract manufacturing networks. ABS and polycarbonate compounds source from petrochemical corridors in South Korea and Thailand; aluminum extrusions feed from Vietnam and Malaysia. Single-source vulnerability concentrates in ferrite shielding layer production for magnetic array assemblies. Distribution runs through regional e-commerce platforms including Shopee and Lazada, bypassing traditional wholesale tiers in Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qi2 magnetic power transfer alignment represents a technological inflection collapsing charging and mounting categories, creating high-growth disruption as wireless charging convergence redefines product architectures across consumer and commercial channels.
For Market Incumbents: Harden magnetization process IP through captive neodymium alloy formulation partnerships in Jiangxi province. Consolidate channel control against direct-to-consumer disintermediation by locking exclusive storefront placement on Lazada and Shopee. Invest in GB standard pre-certification for magnetic field exposure compliance to preempt SAMR enforcement actions.
For New Entrants and Emerging Players: India's BIS certification pathway for automotive electronics accessories represents the most penetrable entry point, with organized retail channels starved for compliant suppliers. Last-mile delivery fleet retrofit demand in Brazil and Mexico offers second white-space target, prioritizing suction-cup specifications for vehicle model heterogeneity. Go-to-market angle: ANVISA import authorization bundling with São Paulo logistics corridor distributors.
For Investors and Strategic Acquirers: The market sits at a standardization phase that favors precision magnetization specialists with OEM qualification relationships. Long-term viability across a 5-10 year window rests on vertical integration into neodymium processing rather than assembly-only positioning. Acquisition target archetype: contract manufacturers with ferrite shielding layer IP and bonded warehouse infrastructure in Dongguan. Signal to watch: EU General Safety Regulation amendment timelines affecting embedded mount displacement rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetization Process IP Development | Captures value shift from mechanical components to magnetic array engineering in contactless retention systems. |
| Qi2 Certification Pathway Investment | Positions suppliers for wireless charging convergence collapsing power delivery and mechanical retention categories. |
| Regional E-Commerce Storefront Expansion | Disintermediates traditional distributor relationships controlling thirty to forty percent of Southeast Asian volume. |
| GB Standard Pre-Certification Program | Accelerates SAMR market entry before magnetic field exposure enforcement tightens domestic compliance requirements. |
| Aluminum 6061-T6 Traceability Integration | Extends supplier qualification cycles for European aftermarket channels demanding alloy documentation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings by listed automotive accessory suppliers, and vehicle production databases. Primary interviews engaged contract manufacturing procurement leads, aftermarket distributor category managers, OEM platform engineers at European premium vehicle manufacturers, and ride-hailing fleet operations directors in Jakarta and São Paulo. Secondary validation drew from SAMR GB standard documentation, EU General Safety Regulation implementation notices, and NHTSA distraction guideline technical amendments. Bottom-up shipment estimates triangulate against top-down accessory spend allocation models.
Forecast inputs span retention mechanism physics, material thermal performance grades, mounting surface geometry specifications, and regional fleet deployment patterns across the projection horizon. Segmentation dimensions include product type, material certification tier, device compatibility class, and channel control structure. CAGRs derive from regression analysis of historical shipment correlations against vehicle parc growth and smartphone replacement cycles. Industry-specific inputs incorporate neodymium price index trajectories and embedded OEM integration adoption curves.
Macroeconomic conditions sit as an overlay; deviation in rare earth export quota enforcement, EU automotive production schedules, or Southeast Asian ride-hailing platform capital allocation would shift the trajectory. Forecasts reflect documented assumptions regarding magnetic ecosystem standardization timelines and REACH substance restriction implementation pacing. Cross-checking against IHS Markit vehicle registration data and regional e-commerce platform disclosed GMV is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market