
 Automotive Antifreeze Market | 2026-2036
Automotive Antifreeze Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Antifreeze Market Intelligence
Fleet operator consolidation is expanding across North America and Europe as large logistics providers centralize maintenance procurement. BASF SE leverages its integrated ethylene glycol supply chain to secure cost advantages for high-volume contracts. Valvoline Inc. sustains brand recognition through proprietary additive packages that extend drain intervals. ExxonMobil Corporation anchors its position with captive base stock production and direct OEM relationships.
Automotive antifreeze is an engineered heat-transfer fluid, typically formulated from ethylene glycol or propylene glycol base stocks combined with corrosion inhibitors, buffering agents, and antifoam compounds, designed to maintain stable engine operating temperatures across ambient extremes from minus forty to one hundred thirty degrees Celsius. Its primary commercial purpose is to prevent coolant system freeze damage, boil-over, and galvanic corrosion in internal combustion and hybrid thermal management circuits. Ethylene glycol formulations dominate installed volume due to lower unit cost and established OEM specifications, while propylene glycol alternatives capture premium positioning in environmentally sensitive applications and food-service vehicle fleets. The aftermarket channel generates the highest margin pools through branded premix products, though OEM fill volumes anchor steady baseline demand tied to new vehicle production cycles.
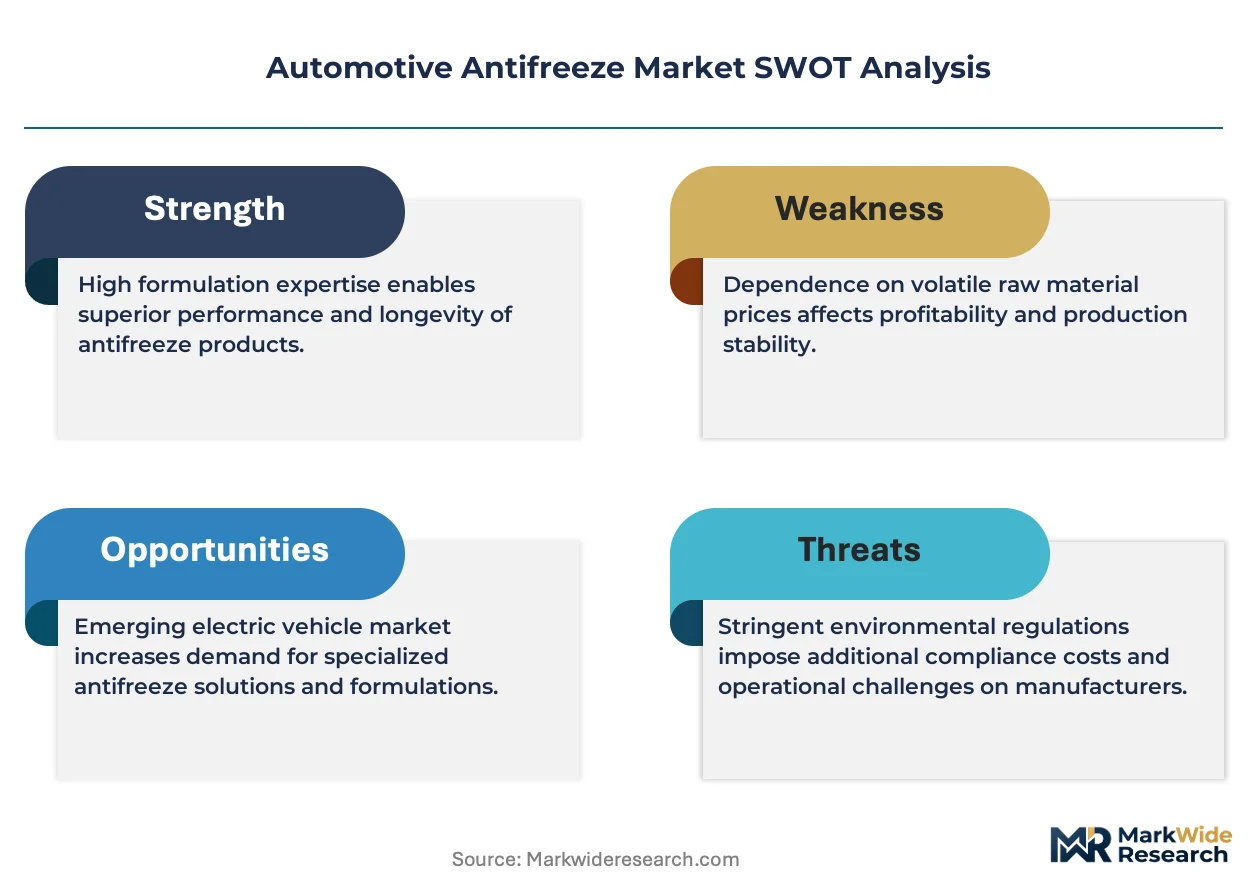
The EPA regulates coolant disposal and toxic substance labeling under TSCA and RCRA frameworks, while REACH in Europe mandates registration and hazard communication for glycol ether formulations. These regimes elevate compliance costs for smaller blenders and favor suppliers with dedicated regulatory affairs capabilities. OEMs, aftermarket distributors, and fleet procurement teams must monitor evolving low-GWP refrigerant regulations and their spillover effects on thermal system fluid specifications.
Market Dynamics
Fleet electrification is fragmenting coolant demand patterns as hybrid thermal systems require specialized formulations with divergent service intervals and corrosion inhibitor packages compared to conventional internal combustion engines.
Growth Catalysts
- Extended Drain Intervals:OEM specifications for long-life organic acid technology coolants stretch replacement cycles to five years or 150,000 miles, concentrating volume in fewer but larger procurement events favoring bulk suppliers.
- China's NEV Production Scale:Domestic battery electric and plug-in hybrid output is expanding service network density for thermal management fluids in tier-two and tier-three cities previously underserved by premium coolant distribution.
- REACH Registration Requirements:ECHA mandates for glycol ether hazard communication and substance registration elevate compliance barriers that filter smaller blenders from European aftermarket channels.
Market Restraints
- Ethylene Glycol Price Volatility:Petrochemical feedstock exposure ties base stock costs to naphtha and ethylene cracker margins, compressing blender margins during upstream supply disruptions.
- MEA Supply Concentration:Monoethanolamine corrosion inhibitor production clusters in Gulf Coast petrochemical corridors, creating single-source vulnerability for North American formulators.
- Propylene Glycol Performance Ceiling:Higher viscosity and lower heat transfer coefficients limit PG formulations to niche environmental compliance applications rather than broad OEM adoption.
Strategic Opportunities
- India's Fleet Modernization:BS-VI emission standards and commercial vehicle scrappage policies are expanding addressable coolant volume in organized workshops beyond traditional unbranded refill markets.
- Direct-to-Fleet E-Commerce:Digital procurement platforms are disintermediating traditional distributor tiers for large logistics operators with centralized maintenance management systems.
- Low-GWP Refrigerant Spillover:EU F-Gas Regulation phase-down schedules for mobile air conditioning are pressuring thermal system redesigns that integrate coolant and refrigerant specification harmonization.
Industry Challenges
- Additive Chemistry Talent Scarcity:Formulation chemists with hybrid electric vehicle thermal management expertise command premium compensation, constraining mid-tier blender R&D expansion.
- OEM Certification Timeline Compression:Accelerated vehicle development cycles for electric platforms shorten coolant validation windows, forcing suppliers to parallel-track testing with incomplete thermal system specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Antifreeze Market |
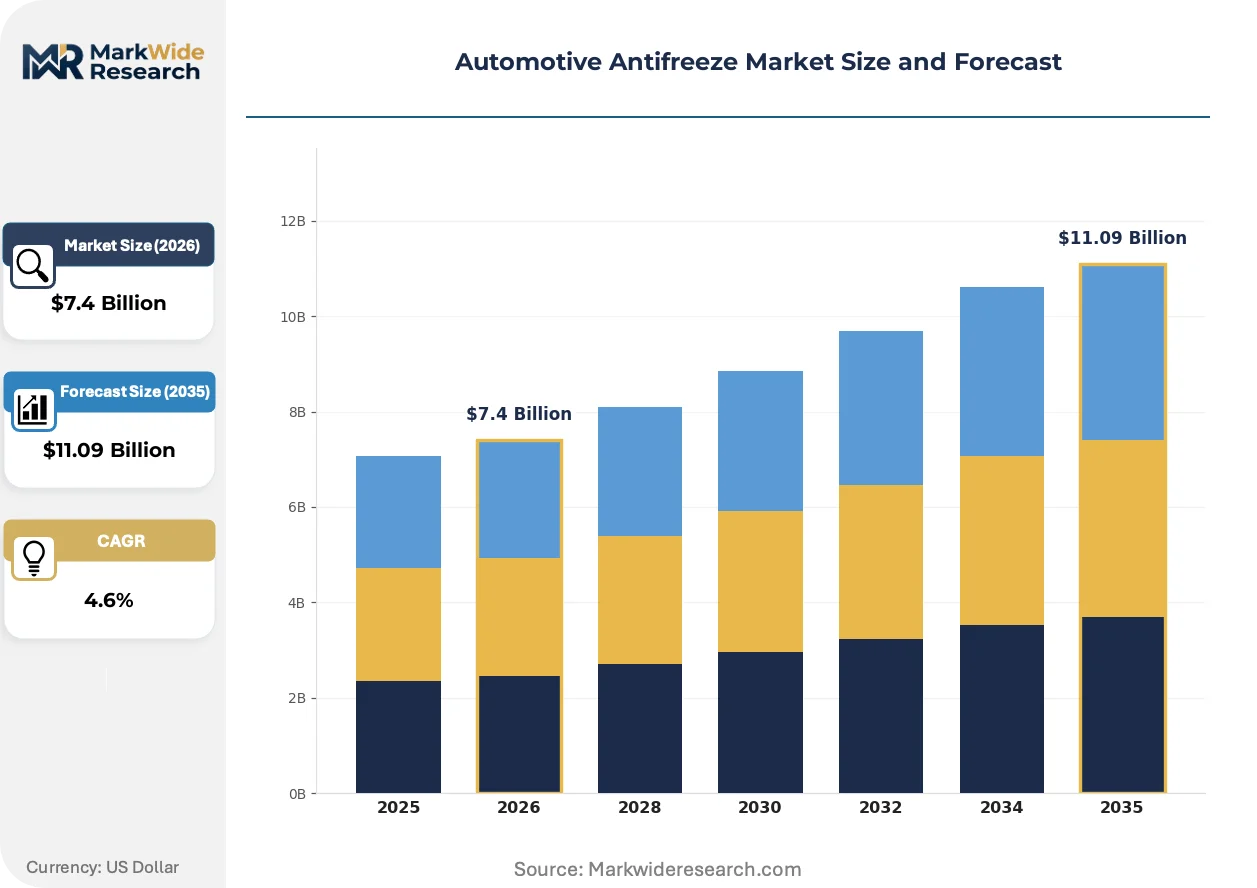
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.09 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Organic Acid Technology, Hybrid Technology End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Distribution Channel: Online Retail, Supermarkets, Auto Parts Stores, Wholesale Distributors Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | TotalEnergies SE, Valvoline Inc., BASF SE, Prestone Products Corporation, Fuchs Petrolub SE, ExxonMobil Corporation, Royal Dutch Shell plc, The Dow Chemical Company, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Antifreeze Market Strategic Shifts & Innovations
Thermal management complexity is escalating as powertrain electrification multiplies coolant circuit counts per vehicle and elevates dielectric property requirements for battery direct cooling applications.
Silicate-free organic acid technology is displacing traditional inorganic inhibitor packages in heavy-duty diesel and natural gas engines. Fleet operators operating mixed powertrain portfolios are consolidating procurement around universal formulations that simplify inventory. This chemistry is modularizing service bay operations by enabling single-coolant strategies across engine types and reducing misapplication risk.
EPA's evolving engine thermal management fluid standards under TSCA Section 5 are tightening pre-manufacture notification requirements for novel corrosion inhibitor chemistries. Blend reformulation costs are rising for suppliers without dedicated regulatory affairs infrastructure. North American aftermarket distributors are responding by narrowing supplier portfolios to established registrants with existing PMN clearances.
Consolidated maintenance procurement by mega-fleets is compressing distributor margins and elevating volume-commitment contract structures. Large logistics operators with captive service networks are displacing traditional jobber channels for coolant replenishment. This concentration is most visible in North American long-haul trucking where ten carriers control substantial Class 8 tractor maintenance spend.
Automotive Antifreeze Market Segmentation
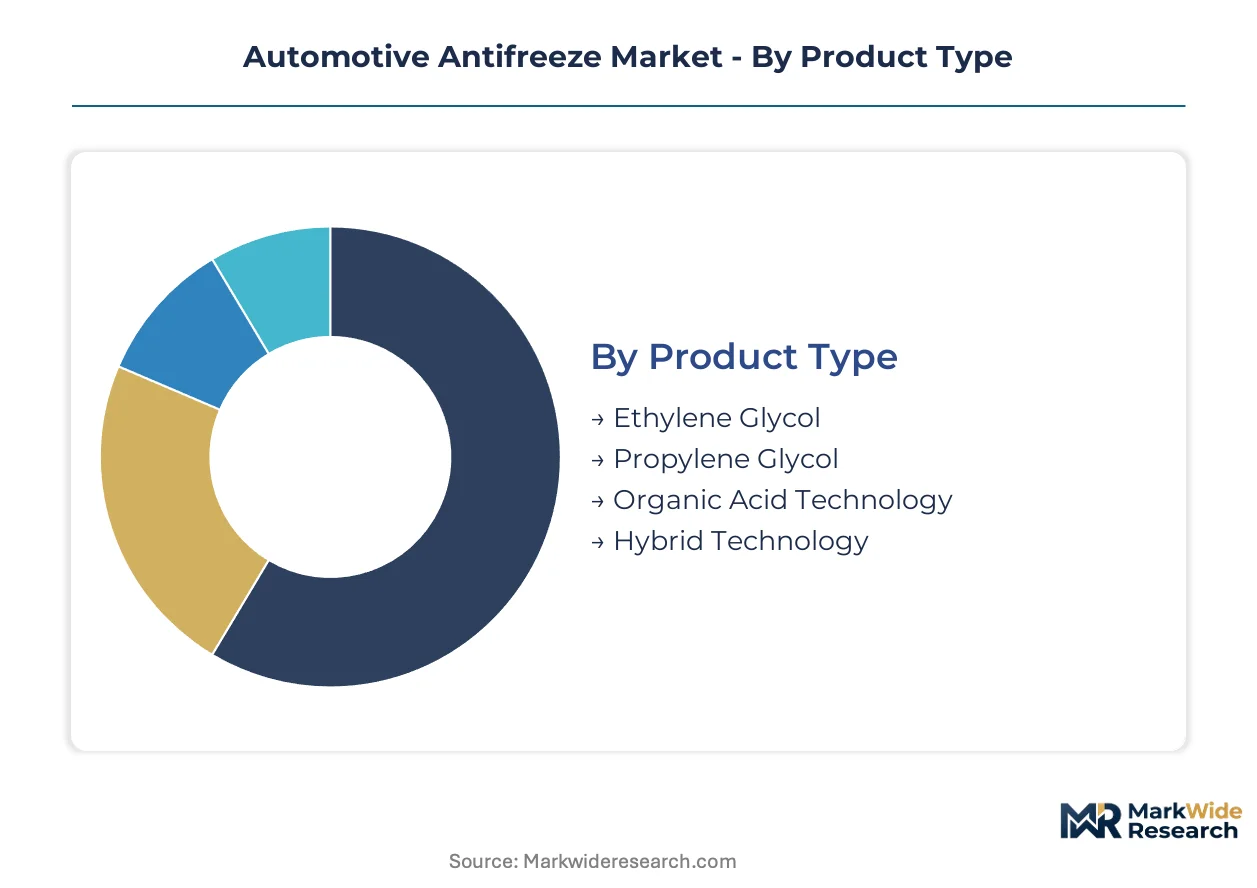
Antifreeze procurement patterns diverge sharply across product chemistries and customer types. Fleet electrification and extended drain intervals are compressing replacement frequency while elevating formulation complexity per service event.
Product Type:
Upgrade cycles vary dramatically by base stock chemistry, with long-life organic formulations displacing conventional inorganic packages in heavy-duty applications.
- Ethylene Glycol:Formulations derived from petrochemical ethylene oxide deliver superior heat transfer coefficients and lower unit costs. Demand concentrates in China and India where domestic vehicle production scales and cost-sensitive OEM fill specifications dominate procurement volumes.
- Organic Acid Technology:Silicate-free inhibitor packages extend service intervals to 150,000 miles or five years, reducing fleet inventory complexity. North American long-haul operators with centralized maintenance procurement favor OAT for mixed powertrain consolidation strategies.
- Propylene Glycol:Lower toxicity base stocks serve food-service vehicle fleets and environmentally sensitive applications where spill containment requirements elevate.
- Hybrid Technology:Combined organic-inorganic inhibitor systems bridge compatibility gaps during fleet transition periods between conventional and electrified thermal management circuits.
Ethylene Glycol sits at the top of the volume ranking, with Organic Acid Technology climbing the fastest.
End User:
Customer scale determines contract structure, with mega-fleets extracting volume commitments that reshape supplier margin pools.
- Fleet Operators:Consolidated logistics providers with captive service networks displace traditional distributor tiers through direct procurement platforms. E-commerce integration enables centralized inventory management across dispersed maintenance facilities.
- OEMs:Factory fill specifications anchor baseline demand tied to new vehicle production cycles, with validation timelines compressing for electric platform thermal systems.
- Aftermarket Providers:Branded premix products generate premium margins through retail channel distribution, though share is eroding to fleet direct purchasing.
- Dealerships:Authorized service networks capture warranty-period coolant replacement volume, retaining customers through certified additive package guarantees.
Fleet Operators command the steepest expansion trajectory as logistics electrification multiplies thermal system complexity per vehicle.
Distribution Channel:
Channel selection correlates with customer technical sophistication and procurement centralization.
- Wholesale Distributors:Bulk supply agreements serve independent repair shops and smaller fleet operators without captive inventory systems.
- Auto Parts Stores:Retail counter sales capture emergency replenishment and consumer DIY segments with immediate availability requirements.
- Online Retail:Digital platforms penetrate price-transparent segments with standardized specification products, accelerating in tier-two and tier-three cities.
- Supermarkets:Mass merchandiser placement reaches consumer vehicle owners through convenience positioning, typically limited to universal premix formulations.
Wholesale Distributors retain volume leadership, with Online Retail gaining share fastest in emerging market urban expansion.
Application:
Vehicle duty cycles dictate thermal stress profiles and corresponding formulation performance requirements.
- Heavy-Duty Trucks:Severe operating conditions with extended engine run hours demand robust corrosion inhibitor packages and higher glycol concentrations. North American Class 8 tractor fleets drive specification evolution through consolidated procurement power.
- Passenger Vehicles:Light-duty thermal systems prioritize long-life intervals and compatibility with aluminum engine components. China's NEV production scale is expanding service network density for battery thermal management fluids.
- Commercial Vehicles:Medium-duty delivery and vocational applications balance durability requirements with cost constraints across mixed fleet portfolios.
- Motorcycles:Compact cooling systems with high power-to-displacement ratios require specialized low-viscosity formulations and accelerated replacement protocols.
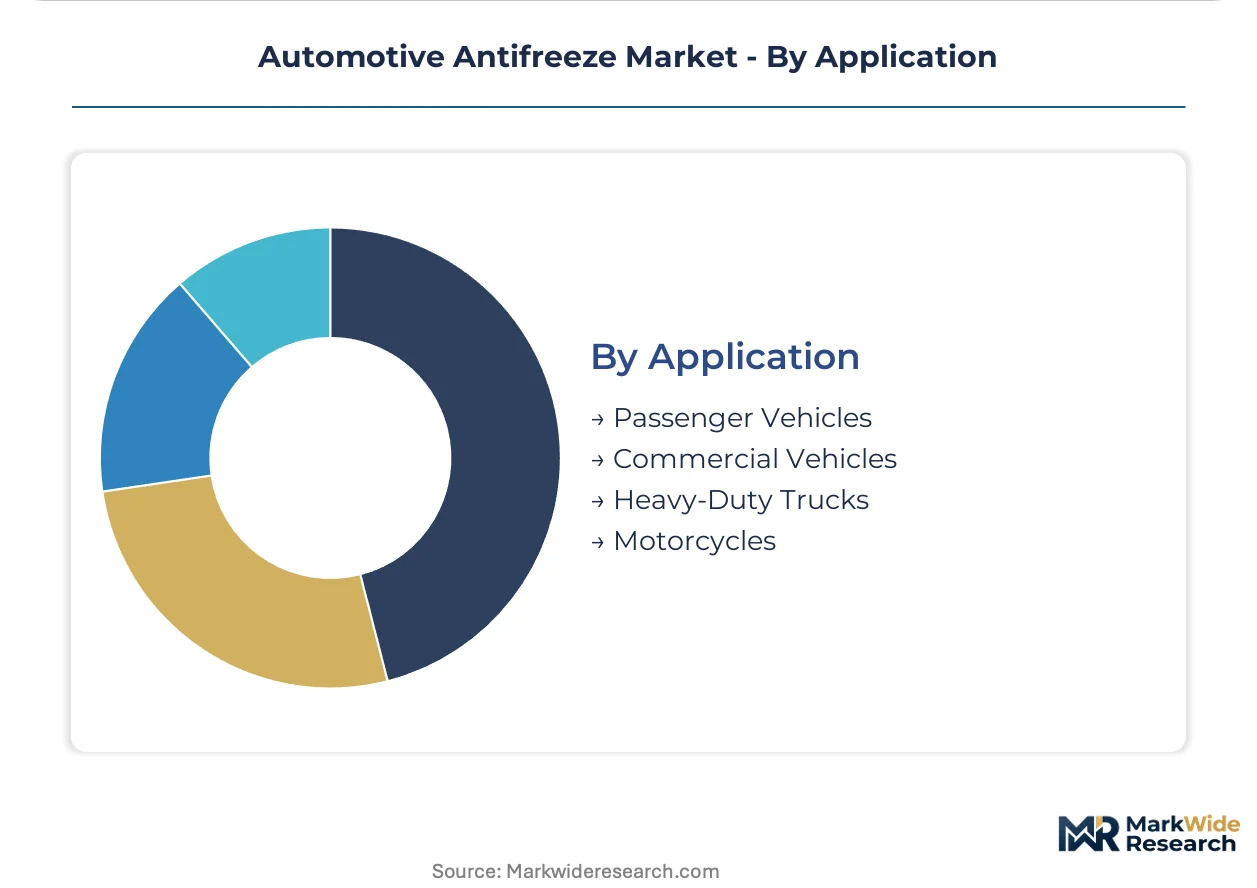
Passenger Vehicles hold the volume position, with Heavy-Duty Trucks showing the most rapid specification upgrading as fleet consolidation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic vehicle production scales faster than India's organized workshop expansion, concentrating coolant procurement volume in East Asian manufacturing corridors while South Asian demand fragments across unbranded refill markets.
China
Domestic NEV production scales service network density for thermal management fluids in tier-two and tier-three cities previously underserved by premium coolant distribution. MIIT's dual carbon goals pressure thermal system efficiency standards that elevate formulation complexity. The Yangtze River Delta cluster around Shanghai anchors glycol blending capacity expansion for both OEM fill and aftermarket premix supply.
United States
Class 8 tractor fleet consolidation concentrates procurement power among ten carriers controlling substantial maintenance spend. EPA's evolving TSCA Section 5 standards tighten pre-manufacture notification requirements for novel corrosion inhibitor chemistries. The Gulf Coast petrochemical corridor houses monoethanolamine production clusters that create single-source vulnerability for North American formulators.
Germany
Heavy-duty diesel specification upgrading accelerates as fleet operators consolidate procurement around universal formulations. REACH registration requirements for glycol ether hazard communication elevate compliance barriers that filter smaller blenders from European aftermarket channels. The North Rhine-Westphalia industrial basin retains blending capacity serving both domestic OEM fill and export markets.
India
BS-VI emission standards and commercial vehicle scrappage policies expand addressable coolant volume in organized workshops beyond traditional unbranded refill markets. BIS certification mandates for automotive fluids reshape quality tiers in the replacement market. The Maharashtra-Gujarat industrial corridor attracts blending capacity investments targeting fleet modernization procurement.
Japan
Hybrid thermal system complexity elevates demand for specialized formulations with divergent service intervals compared to conventional internal combustion engines. METI's energy efficiency standards pressure thermal management fluid performance specifications. The Kanto region around Tokyo maintains formulation R&D concentration serving domestic OEM validation requirements.
Automotive Antifreeze Market Key Industry Players
German chemical conglomerates anchor one tier; US petroleum majors and European oil specialists hold volume positions in regional aftermarket channels. The vendor base concentrates around integrated ethylene glycol producers with captive base stock supply and dedicated regulatory affairs infrastructure. Three archetypes dominate: petrochemical-integrated blenders with backward control over feedstock costs, branded premix specialists with proprietary additive packages, and lubricant majors leveraging distribution overlap. Competitive moves center on fleet direct procurement platform development and long-life organic acid technology certification acceleration.
Within the integrated chemical tier, BASF SE exemplifies petrochemical-integrated positioning with ethylene oxide supply chain control. Valvoline Inc. and ExxonMobil Corporation occupy distinct volume positions, with the former representing branded aftermarket specialists and the latter anchoring petroleum-major diversification into thermal management fluids. These three entities illustrate the competitive structure without exhausting its composition.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Valvoline Inc. |
| BASF SE |
| Prestone Products Corporation |
| Fuchs Petrolub SE |
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| The Dow Chemical Company |
| Chevron Corporation |
| Others |
Cost & Logistics Intelligence
Fleet procurement consolidation across North American long-haul trucking is compressing distributor tiers and forcing blenders toward volume-commitment contract structures that sacrifice margin for baseline demand security. This buyer concentration reshapes how suppliers position additive chemistry tiers and where they anchor blending capacity.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for ethylene glycol base stocks as domestic supply reduces import dependency. Three-tier pricing structure across premium long-life OAT, standard hybrid formulations, and economy conventional chemistries dominates contract negotiations. Cost compression in the economy tier is intensifying because Gulf Coast monoethanolamine supply concentration limits corrosion inhibitor sourcing flexibility. Fleet operators with centralized procurement systems exhibit lowest price sensitivity, while independent repair shops remain highly responsive to per-gallon fluctuations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through captive blending agreements tied to vehicle production schedules. Supply concentrates in China, the United States, and Germany, with ethylene oxide crackers and monoethanolamine production anchoring regional cost structures. Raw material dependencies rest on petrochemical ethylene, corrosion inhibitor packages, and glycol ether solvents. Single-source vulnerability in Gulf Coast MEA corridors creates formulator exposure to weather-related production interruptions. Distribution runs through wholesale distributors serving fragmented aftermarket channels alongside direct fleet procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in long-life organic acid technology certification as fleet operators consolidate procurement around extended-drain formulations that command premium positioning over conventional chemistries.
For Market Incumbents: Lock in ethylene glycol supply chain control through backward integration or long-term offtake agreements with Yangtze River Delta producers to defend against feedstock volatility. Accelerate REACH and EPA TSCA Section 5 registration timelines for novel corrosion inhibitor chemistries to filter mid-tier competitors from European and North American aftermarket channels. Channel control through direct fleet e-commerce platforms represents the critical defensive lever against distributor margin compression. For New Entrants and Emerging Players: REACH registration requirements in Europe open a window for specialized additive chemistry suppliers to capture share among smaller blenders lacking dedicated regulatory affairs infrastructure. India's BS-VI emission standards and organized workshop expansion present the most penetrable geography for branded premix penetration beyond traditional unbranded refill markets. A go-to-market angle anchored in food-service vehicle propylene glycol formulations exploits environmental compliance premiums where spill containment requirements elevate specification thresholds. For Investors and Strategic Acquirers: Asymmetric upside sits with petrochemical-integrated blenders possessing captive ethylene oxide supply and existing OEM validation relationships. The 5-10 year viability window favors suppliers with demonstrated hybrid electric vehicle thermal management formulation expertise as powertrain electrification multiplies coolant circuit complexity per vehicle. The signal to watch is fleet electrification penetration rates in Class 8 trucking, which will indicate when specialized low-conductivity formulations displace conventional chemistries at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply secures cost advantage against Gulf Coast petrochemical volatility. |
| Long-term Fleet Supply Agreement | Mega-fleet procurement consolidation rewards volume-commitment structures with baseline demand anchoring. |
| Organic Acid Technology Certification | Extended-drain validation with North American OEMs filters competitors from premium specification tiers. |
| Direct-to-Fleet E-commerce Platform | Digital procurement penetration disintermediates traditional distributor margins in logistics maintenance. |
| Hybrid Thermal System R&D Partnership | Collaboration with NEV platform engineers accelerates dielectric coolant validation for battery direct cooling. |
Research Approach
Bottom-up fleet operator and OEM procurement modeling reconciled against top-down ethylene glycol production and trade flow tracking forms the analytical core of this study. Primary interviews with aftermarket distribution channel heads, fleet maintenance procurement directors, OEM thermal system engineers, and blending plant technical managers combined with secondary validation from customs trade databases, ACC industry reports, SEC 10-K filings, and vehicle production registration data. Triangulation between supply-side capacity announcements and demand-side contract structures ensures volume and value estimates reflect actual procurement patterns rather than production capacity alone.
Input-output matrices map ethylene oxide cracker output through formulation blending to end-use consumption across passenger vehicle, heavy-duty truck, and commercial vehicle duty cycles. Segmentation dimensions include base stock chemistry, inhibitor technology tier, vehicle propulsion architecture, and regional regulatory cluster. CAGRs derive from production forecast reconciliation against service interval compression effects and fleet electrification penetration assumptions. Key forecast inputs encompass MIIT dual carbon goal implementation timelines and EPA TSCA Section 5 pre-manufacture notification clearance rates for novel additive chemistries.
Revisions become necessary when ethylene glycol feedstock volatility disrupts blender margin structures or when accelerated OEM electric platform development cycles compress coolant validation windows beyond historical norms. Forecasts reflect assumptions regarding REACH registration compliance timelines and fleet procurement centralization trajectories. Periodic stress-testing of base assumptions against actual fleet e-commerce penetration rates and NEV thermal system specification changes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Singapore Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market