
 Automotive Fluids Market | 2026-2036
Automotive Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fluids Market Analysis
Fleet operator consolidation is expanding across North America and Europe as logistics companies centralize procurement. Shell plc leverages its integrated refining network to sustain bulk supply contracts with these consolidated buyers. Valvoline Inc. differentiates through quick-lube channel control in the fragmented aftermarket repair segment. Fuchs Petrolub SE specializes in high-performance formulations for German commercial vehicle manufacturers.
Automotive fluids encompass lubricants, coolants, brake fluids, and transmission fluids formulated from base oils and additive packages meeting specific viscosity grades and thermal stability thresholds. These formulations reduce friction, dissipate heat, and prevent corrosion in powertrain and braking systems operating across temperature ranges from minus forty to one hundred fifty degrees Celsius. Engine oil retains the largest volume share among product types due to mandatory drain intervals, while synthetic oil grades command premium positioning as OEMs specify longer service life. The aftermarket provider channel generates recurring revenue pools through replacement cycles, though OEM fill volumes anchor initial specification authority.
The EPA regulates fuel economy and emissions standards that directly determine engine oil viscosity grades and thermal performance requirements for vehicles sold in the United States. REACH compliance in Europe restricts certain additive chemistries, compelling reformulation investments by suppliers serving EU member states. China's MIIT enforces domestic GB standards that foreign fluid producers must satisfy for market access. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product architectures deliver superior returns.
Market Dynamics
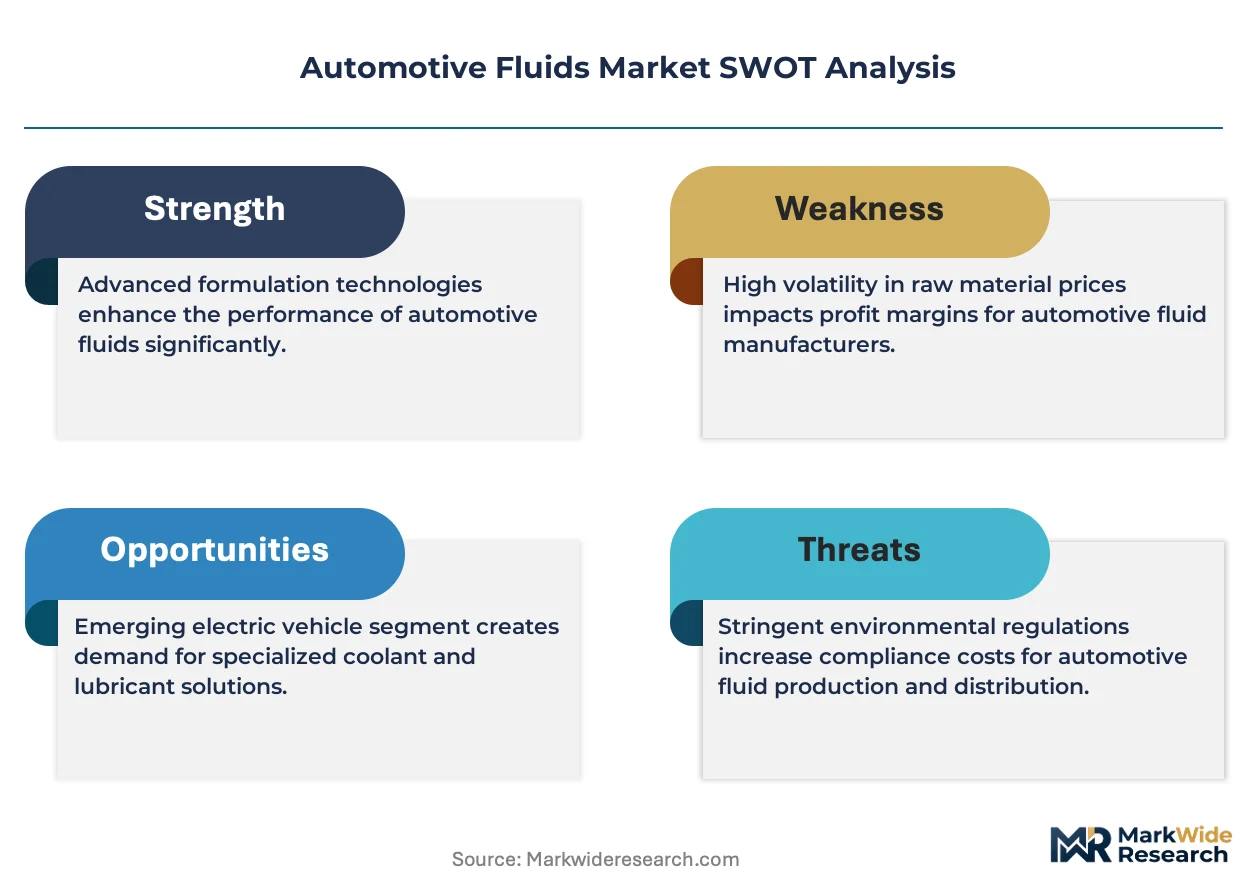
The automotive fluids market is restructuring around thermal management complexity in electrified powertrains, as electric vehicle battery cooling requirements force reformulation of dielectric coolants and lubricants across OEM specifications.
Growth Catalysts
- EPA fuel economy mandates:Tightened Corporate Average Fuel Economy standards compel automakers to specify lower-viscosity engine oils, expanding demand for advanced synthetic formulations that reduce parasitic losses in internal combustion powertrains.
- Electric vehicle thermal systems:Battery electric vehicle production is accelerating adoption of dielectric coolants and specialized greases for e-axle units, creating incremental fluid categories absent from conventional vehicle architectures.
- China automotive production concentration:The country's dominance in global vehicle assembly anchors fluid demand volumes, with domestic GB standards enforcement requiring foreign suppliers to establish localized blending capacity.
Market Restraints
- Base oil supply concentration:Group II/III base stock production clusters in the US Gulf Coast and Middle Eastern refining hubs, exposing formulators to feedstock cost volatility and geographic supply disruptions.
- REACH additive restrictions:ECHA classifications on certain boron and sulfur chemistries force European formulators to redesign additive packages, extending R&D timelines and raising compliance costs for EU-serving suppliers.
- Extended drain intervals:Synthetic oil longevity improvements compress replacement frequency, constraining aftermarket volume growth despite premium pricing on advanced formulations.
Strategic Opportunities
- India commercial vehicle fleet expansion:The country's logistics sector modernization and infrastructure investment are expanding heavy-duty truck populations, driving demand for high-performance diesel engine oils and transmission fluids in an underpenetrated service network.
- Data center immersion cooling crossover:Dielectric fluid technologies developed for EV batteries are transferring to server thermal management, opening adjacent revenue streams for automotive fluid specialists with electrical insulation expertise.
- EU Green Deal carbon border adjustments:Embodied carbon regulations on imported goods incentivize European production of low-carbon-footprint lubricants, rewarding suppliers with renewable feedstock integration and regional manufacturing assets.
Industry Challenges
- Electrification talent scarcity:Formulation chemists with dielectric fluid and e-mobility thermal management expertise remain concentrated at specialty chemical firms, constraining OEM and tier-one supplier hiring pipelines.
- Multi-standard certification complexity:Simultaneous compliance with API SP, ILSAC GF-6, ACEA C sequences, and OEM-specific approvals extends product launch timelines and fragments R&D resource allocation.
- Legacy distribution integration:Traditional quick-lube networks lack equipment and training for EV-specific fluid services, creating channel conflict as OEMs push direct-to-consumer maintenance models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fluids Market |
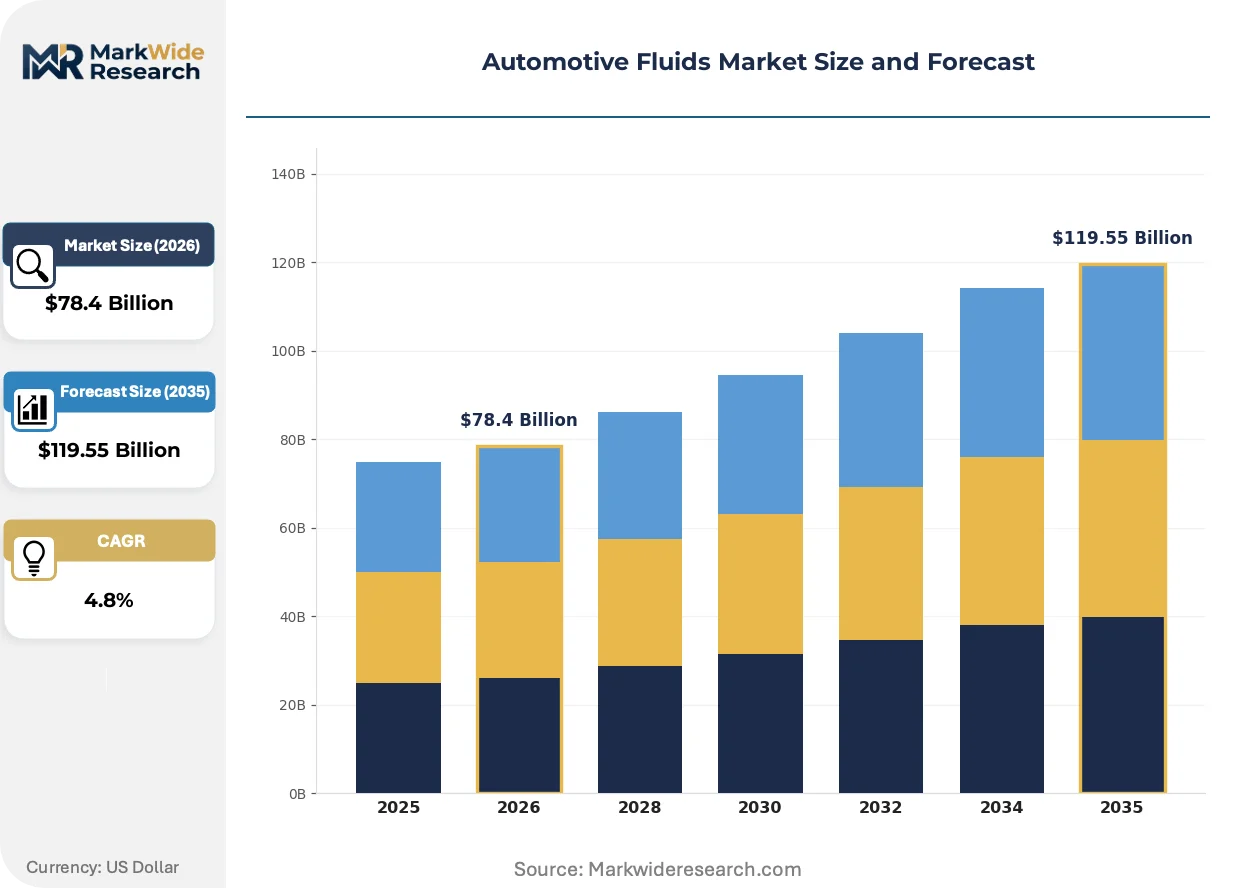
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Coolant Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks End User: OEMs, Aftermarket Providers, Repair Shops, Fleet Operators Grade: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-based Oil |
| Companies Covered | Chevron Corporation, Fuchs Petrolub SE, Shell plc, China Petroleum & Chemical Corporation, PetroChina Company Limited, ExxonMobil Corporation, TotalEnergies SE, Valvoline Inc., BP p.l.c., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fluids Market Emerging Trajectories
Electrification is fragmenting fluid specifications into powertrain-specific categories, while regulatory pressure on carbon intensity and circularity forces reformulation of chemistries and packaging systems across the value chain.
Immersion cooling technology is modularizing thermal management architectures in battery electric vehicles. Dielectric fluids now circulate directly through battery cell arrays rather than external cold plates, enabling higher power density and faster charging protocols. Porsche and Hyundai-Kia suppliers are qualifying these systems for 800-volt platforms, compressing the traditional separation between power electronics and battery thermal loops into unified fluid circuits.
REACH authorization requirements are tightening scrutiny on persistent organic pollutants in lubricant additives. ECHA's 2023-2024 substance evaluations targeted chlorinated paraffins and certain organometallic friction modifiers, forcing reformulation investments before sunset dates. European formulators are accelerating phosphate ester and ionic liquid additive development to maintain anti-wear performance under stricter toxicity thresholds.
Fleet operators are consolidating procurement through direct supplier contracts rather than distributor networks. Large logistics companies in Germany and the US are negotiating multi-year bulk supply agreements with Shell and Fuchs, bypassing traditional jobber channels. This concentration is most visible in long-haul trucking segments where telematics-enabled usage tracking supports fluid-as-a-service billing models tied to actual equipment runtime rather than calendar-based replacement intervals.
Automotive Fluids Market Segmentation
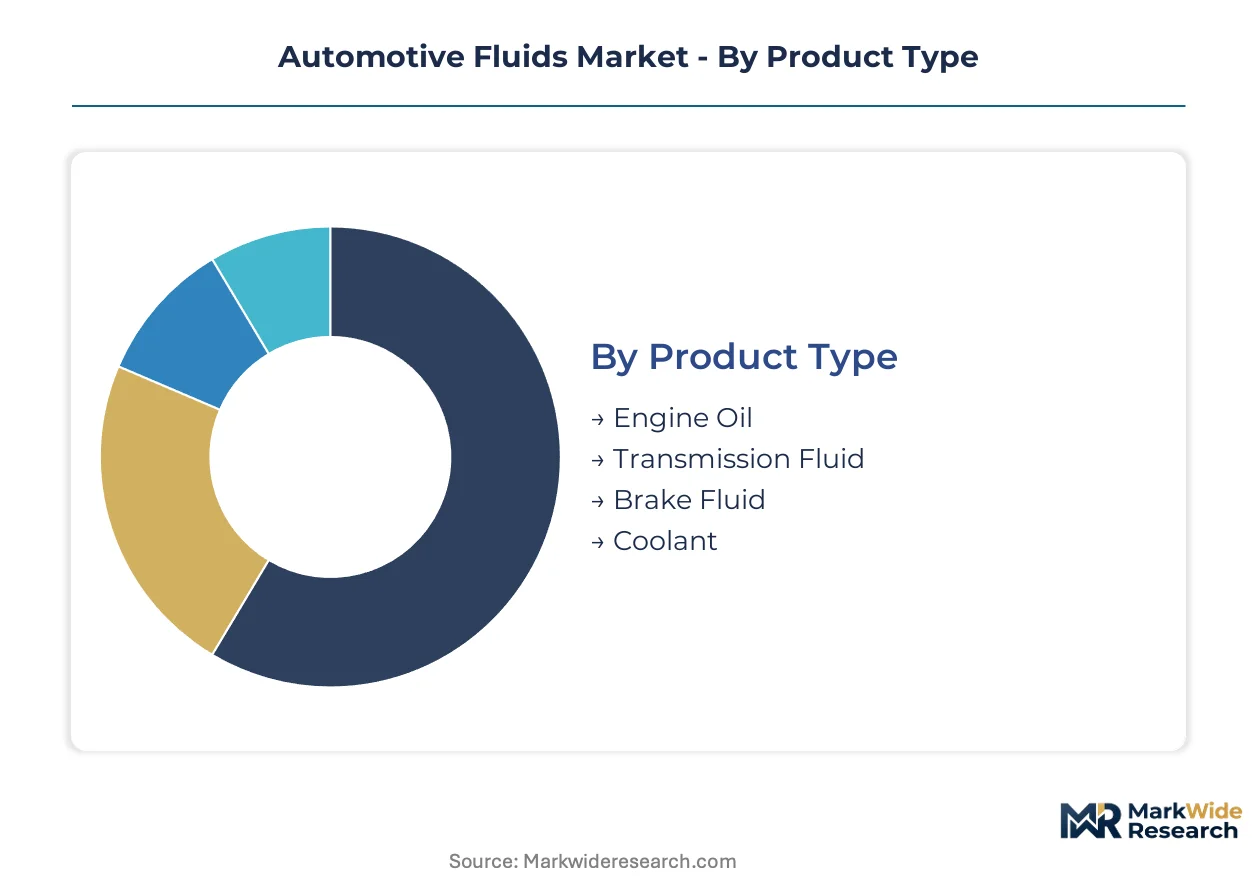
Automotive fluid purchasing behavior splits sharply between specification-driven OEM fill programs and price-sensitive aftermarket replacement cycles. Understanding these divergent buyer logics determines channel strategy and formulation investment priorities across the value chain.
Product Type:
Volume concentration and drain interval frequency differentiate buyer economics across fluid categories.
- Engine Oil:Formulated from Group II/III base stocks with additive packages meeting API SP and ACEA C sequences for friction reduction and oxidation stability. Mandatory drain intervals every 5,000-15,000 miles anchor recurring aftermarket revenue pools in the United States and China. Engine oil leads volumes today; dielectric coolant formulations for EV thermal management are gaining share fastest.
- Transmission Fluid:ATF and CVT-specific formulations with controlled friction coefficients for clutch pack engagement and shear stability across temperature ranges. Demand concentrates in heavy-duty truck fleets specifying extended-drain synthetic grades for automated manual transmissions.
- Brake Fluid:Glycol-ether or silicone-based formulations meeting DOT 3/4/5.1 boiling point specifications for hydraulic system safety.
- Coolant:Ethylene glycol or propionate-based solutions with corrosion inhibitors for engine and battery thermal loops.
Engine oil commands the largest volume position; transmission fluid exhibits the steepest expansion trajectory in electrified powertrains.
Application:
Duty cycles and thermal load profiles determine fluid specification severity and replacement frequency.
- Passenger Vehicles:Light-duty formulations optimized for start-stop systems and turbocharged downsized engines. OEM specifications from Volkswagen, Toyota, and General Motors drive synthetic grade adoption in Germany, Japan, and the United States as CAFE standards tighten viscosity requirements.
- Commercial Vehicles:Heavy-duty diesel engine oils with elevated TBN for soot handling and extended drain intervals. Fleet operators in India and Brazil centralize procurement through direct supplier contracts, bypassing traditional distributor networks.
- Two-Wheelers:Low-viscosity formulations for air-cooled engines with high thermal stress and frequent top-off requirements.
- Heavy-Duty Trucks:API CK-4 and FA-4 category lubricants for Class 8 tractors operating in long-haul corridors across North America.
Passenger vehicles generate the highest absolute volume; heavy-duty trucks deliver the strongest per-unit value capture.
End User:
Specification authority and procurement scale separate initial fill programs from replacement demand.
- OEMs:Factory fill programs with proprietary approvals locking in formulation specifications for warranty coverage. Volkswagen's 504.00/507.00 and BMW's Longlife-04 standards in Germany force additive package customization that extends R&D timelines.
- Aftermarket Providers:Quick-lube chains and retail channels serving price-sensitive consumers with licensed formulations. Valvoline's instant oil change network in the United States controls access to the fragmented DIY segment.
- Repair Shops:Independent service centers balancing OEM compliance with inventory complexity constraints.
- Fleet Operators:Consolidated buyers negotiating bulk supply agreements with telematics-enabled usage tracking.
OEMs anchor specification authority; fleet operators are consolidating procurement fastest.
Grade:
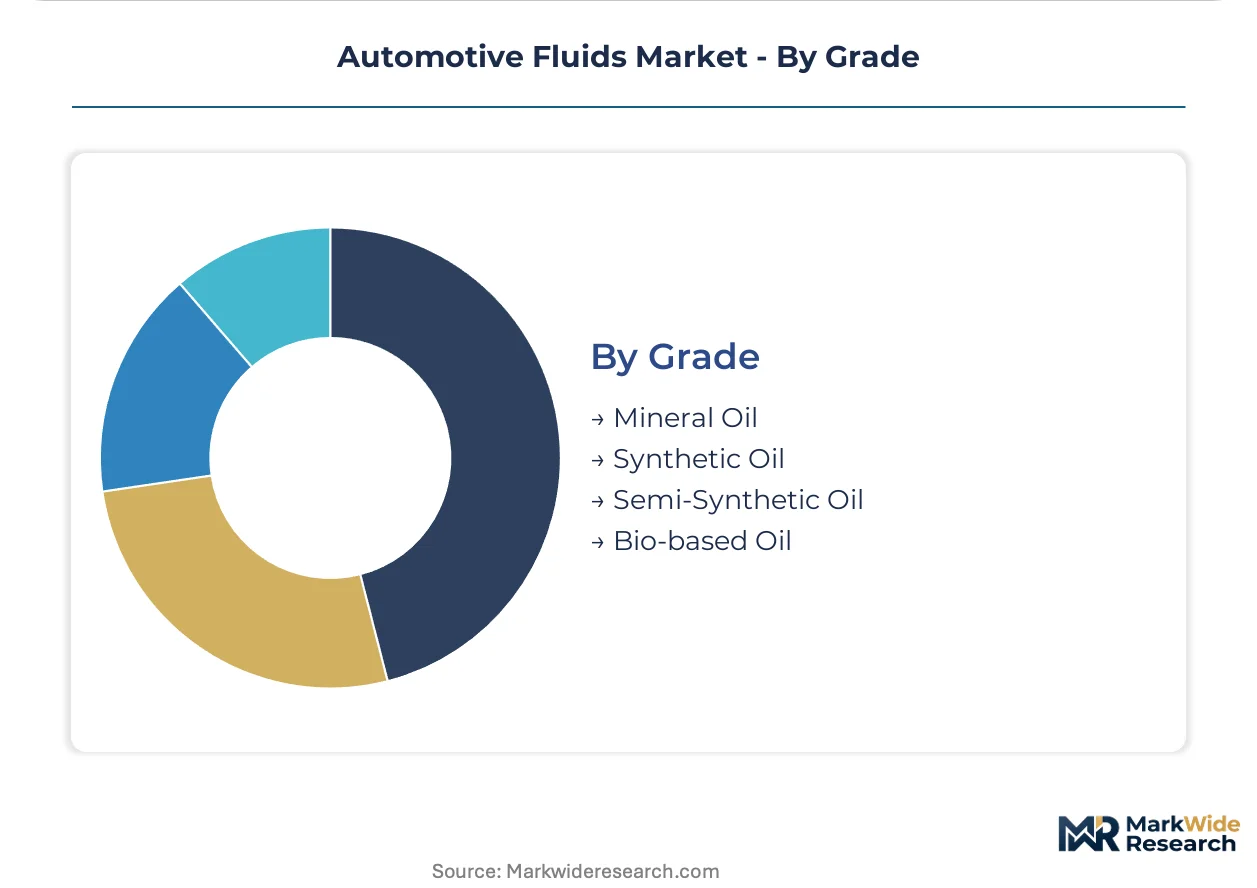
Performance tier and feedstock chemistry determine margin structure and regulatory exposure.
- Mineral Oil:Group I base stock formulations with shorter drain intervals and lower price positioning. Demand persists in price-sensitive markets and older vehicle populations.
- Synthetic Oil:Group III/IV/V base stocks engineered for thermal stability and extended service life. Porsche and Mercedes-Benz specifications in Germany mandate synthetic grades for turbocharged direct-injection engines.
- Semi-Synthetic Oil:Blended formulations balancing cost and performance for mid-market vehicle segments.
- Bio-based Oil:Renewable feedstock lubricants with reduced carbon intensity profiles. EU Green Deal carbon border adjustments incentivize European production of these grades.
Mineral oil retains volume leadership in emerging markets; synthetic oil is climbing the fastest in OEM specification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with dielectric fluid expertise cluster in Germany's industrial corridor, China's Yangtze Delta research parks, and the US Gulf Coast petrochemical belt. These talent concentrations anchor regional competitive advantages as electrification reshapes specification requirements.
United States
Heavy-duty trucking fleets in Texas and California drive demand for extended-drain synthetic formulations. The EPA's Corporate Average Fuel Economy standards mandate lower-viscosity engine oils for 2027 model year vehicles. Houston's Group II/III base oil refineries supply formulators across North America.
Germany
Porsche and BMW thermal management specifications push dielectric coolant innovation for 800-volt battery platforms. REACH authorization timelines force additive package redesigns before 2025 sunset dates. Stuttgart's automotive supplier ecosystem hosts Fuchs Petrolub's high-performance lubricant R&D operations.
China
Domestic electric vehicle production concentrates fluid demand in the Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT enforcement of GB standards requires foreign suppliers to establish localized blending capacity. BYD and CATL battery thermal specifications drive dielectric coolant formulation investment.
India
Commercial vehicle fleet expansion in Maharashtra and Gujarat creates demand for high-performance diesel engine oils. The PLI scheme for automotive manufacturing attracts fluid suppliers to establish regional production. Gurugram's logistics corridor anchors heavy-duty truck population growth.
Japan
Toyota and Nissan hybrid thermal management specifications bridge conventional and electrified fluid categories. METI carbon neutrality roadmaps incentivize bio-based lubricant development. Nagoya's automotive supplier cluster concentrates formulation expertise for Asian OEM programs.
Automotive Fluids Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers. Integrated oil majors leverage captive base oil supply and global distribution networks. Mid-scale formulators anchor regional OEM relationships through customized additive packages. Consolidation accelerates as fleet operators centralize procurement and electrification fragments technical requirements.
Within the integrated oil major tier, Shell plc and ExxonMobil Corporation exemplify scale-driven positioning through refining network control and bulk supply contracting. Valvoline Inc. occupies a distinct channel-focused archetype, anchoring aftermarket access through service network penetration. Fuchs Petrolub SE represents the specialized formulator model, concentrating on high-performance OEM specifications within German commercial vehicle programs.
| Leading Market Players |
|---|
| Chevron Corporation |
| Fuchs Petrolub SE |
| Shell plc |
| China Petroleum & Chemical Corporation |
| PetroChina Company Limited |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Valvoline Inc. |
| BP p.l.c. |
| Others |
Supply Flow & Price Mechanics
Fleet operator consolidation across North America and Germany is compressing distributor margins and forcing formulators toward direct bulk contracting, which concentrates volume leverage among fewer buyers and elevates price transparency in synthetic grade negotiations.
Pricing Analysis
Capacity additions in the US Gulf Coast are reshaping price floors for Group II/III base stocks, intensifying competition among formulators. Three-tier pricing structure across premium synthetic, standard synthetic, and mineral oil levels dominates, with differentiation driven by OEM certification tier and volume scale commitments. Cost compression in mineral oil segments is intensifying because of extended drain interval adoption. Fleet operators exhibit lowest price sensitivity due to telematics-enabled usage tracking, while independent repair shops face highest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern Group II/III base oil refineries serving Asian formulators. Production clusters in the United States, Saudi Arabia, and South Korea anchor global supply. Automotive fluid formulation draws from Group II/III base stocks, phosphate ester additives, and ionic liquid friction modifiers. Tariff exposure on additive imports into the European Union elevates cost uncertainty. Distribution runs through integrated oil major networks, quick-lube chains, and direct fleet contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive fluids market reads as a late-cycle quality story, justified by OEM specification mandates toward lower-viscosity synthetic grades that reward formulation expertise over commodity positioning.
For Market Incumbents: Cement specification authority through captive additive package development and backward integration into base oil refining. Deepen channel control in the quick-lube segment to defend against direct-to-consumer EV maintenance models. Prioritize dielectric coolant certification investments with Porsche and Hyundai-Kia suppliers.
For New Entrants and Emerging Players: E-commerce platforms serving independent repair shops offer the most penetrable route into fragmented aftermarket demand. Target India's commercial vehicle fleet expansion in Maharashtra and Gujarat with high-performance diesel formulations. Pursue white-label supply agreements with logistics companies bypassing traditional jobber networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized formulators holding dielectric fluid expertise for 800-volt battery platforms. Long-term viability over the next decade hinges on electrification thermal management capabilities. Acquisition targets should demonstrate OEM qualification progress with CATL or BYD specifications. Monitor ECHA authorization timelines for additive chemistry sunset dates as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Dielectric Coolant Qualification | OEM approval with 800-volt platform suppliers unlocks premium positioning in EV thermal management. |
| Backward Integration into Base Oil | Captive Group II/III supply secures margin stability against feedstock volatility in Gulf Coast markets. |
| Fleet Telematics Partnership | Usage-based fluid-as-a-service contracts with logistics operators displace calendar-based replacement models. |
| REACH-Compliant Additive Development | Phosphate ester and ionic liquid investments preempt ECHA sunset restrictions on legacy chemistries. |
| India Regional Production Footprint | Localized blending capacity satisfies PLI scheme requirements and reduces logistics costs to Gujarat corridors. |
Methodological Framework
Bottom-up vehicle class modeling reconciled against top-down base oil supply tracking forms the analytical core. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers combined with secondary validation from vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from integrated oil majors. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped fluid demand across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EPA CAFE trajectory assumptions, MIIT enforcement intensity on GB standards, and ECHA authorization timeline probabilities for restricted additive chemistries.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook. Forecasts reflect assumptions on electrification penetration, regulatory enforcement consistency, and base oil capacity expansion timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Tappet Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Bulgaria Automotive Lubricants Market