
 Industrial V Belt Market | 2026-2036
Industrial V Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial V Belt Market Intelligence
The expansion of automated agricultural machinery and high-efficiency HVAC systems is broadening the traditional manufacturing-centric end-user base. Gates Corporation leverages its extensive distribution network to serve these diversifying applications. Continental AG competes on material science innovation, developing belts for high-temperature and high-stress environments. Meanwhile, Mitsuboshi Belting Ltd. specializes in power transmission solutions for the automotive aftermarket in Asia.
An industrial V belt is a flexible power transmission component with a trapezoidal cross-section designed to fit securely in a grooved pulley. Constructed typically from rubber or synthetic polymers reinforced with polyester or aramid cords, it transmits torque between rotating shafts. Raw edge V belts are gaining preference over classical wrapped belts due to higher power transmission efficiency and flexibility. Rubber remains the dominant material choice, though advanced polyester composites offer superior performance in demanding applications.
Global manufacturing standards, such as those from the ISO, define performance and dimensional specifications for V belts, ensuring interchangeability. In Europe, the ECHA's REACH regulation restricts the use of certain chemicals in rubber compounds, influencing material selection. Concurrently, workplace safety rules from bodies like the US OSHA mandate proper machine guarding for belt-driven systems. The key decision for equipment manufacturers now centers on balancing the upfront cost of high-performance belts against the long-term benefits of energy efficiency and reduced maintenance.
Market Dynamics
The central force shaping the industrial V belt market is the shift in demand from general-purpose components to engineered solutions. This is driven by the dual pressures of automation in new industrial geographies and the pursuit of energy efficiency in established sectors.
Growth Catalysts
- Material Advancement:The development of high-performance rubber and polyester composites enhances belt durability and power transmission capacity, meeting the demands of heavy-duty agricultural machinery and high-speed industrial conveyors.
- Agricultural Mechanization:Accelerated adoption of automated farming equipment, particularly in developing economies like Vietnam, creates sustained demand for reliable V belts in applications from tractors to harvesters.
- Global Standardization:Adherence to performance and dimensional specifications set by bodies like the ISO ensures V belt interchangeability, simplifying maintenance and bolstering the global aftermarket for replacement parts.
Market Restraints
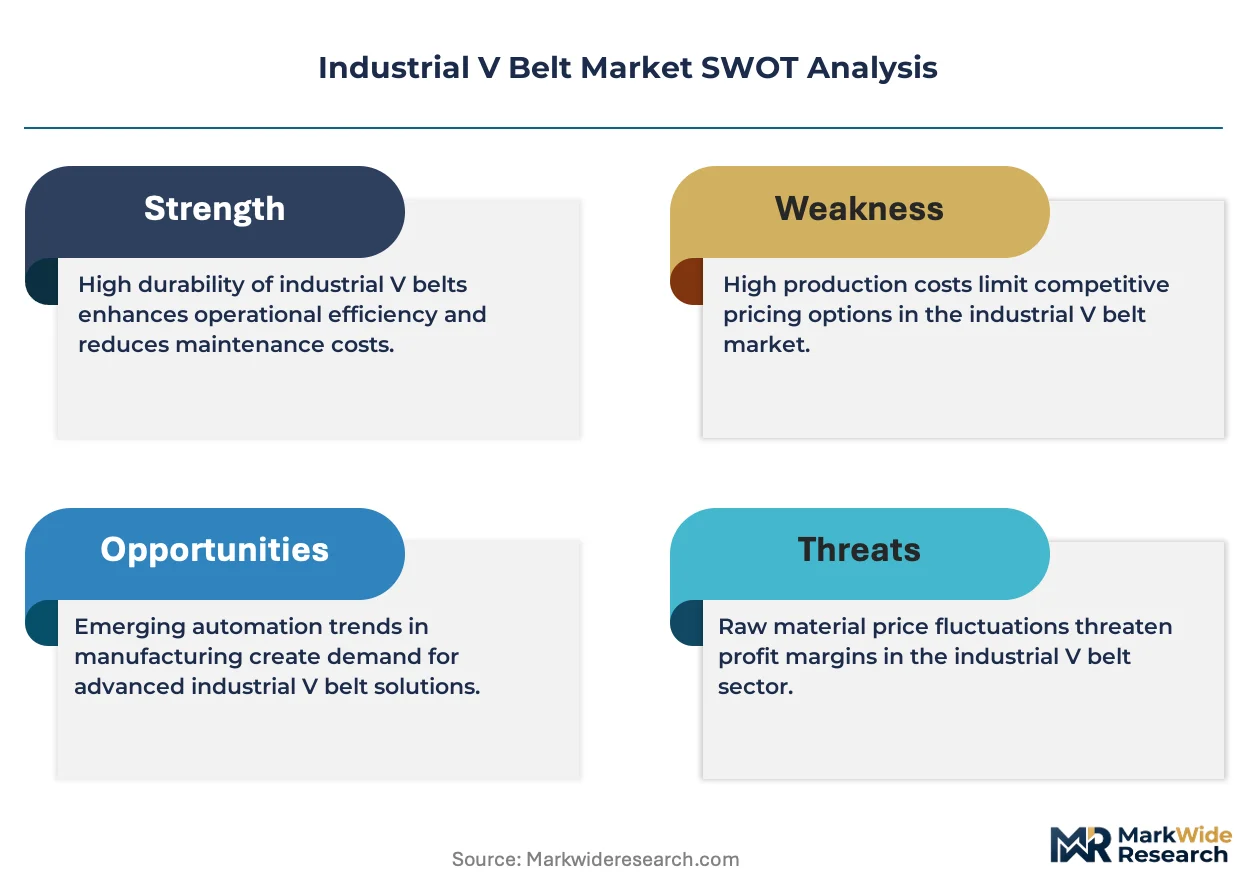
- Input Cost Volatility:Fluctuations in the price of key raw materials, especially natural rubber and synthetic polymers like EPDM, directly impact manufacturing costs and create price instability for end-users.
- Substitution by Direct Drives:In certain high-precision or compact new equipment designs, direct-drive motors are eliminating the need for belt-and-pulley systems, representing a direct technological substitution threat. -
- Inherent Efficiency Limits:Compared to synchronous or timing belts, classical V belts are prone to slippage, which results in energy loss and makes them unsuitable for applications requiring precise motion control.
Strategic Opportunities
- Predictive Maintenance Integration:Developing V belts with embedded sensors or condition-monitoring capabilities offers a path to higher-margin, service-oriented revenue streams focused on preventing unplanned downtime in critical industrial systems.
- Aftermarket for HVAC Systems:The large installed base of commercial HVAC equipment creates a substantial and recurring opportunity for higher-efficiency replacement belts that offer energy savings and reduced maintenance cycles.
- Nearshoring Industrial Hubs:Expanding distribution and technical support in manufacturing clusters in Mexico allows suppliers to serve the growing number of automated facilities being established to shorten supply chains.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers must continuously adapt rubber and polymer formulations to comply with evolving chemical safety regulations, such as the ECHA's REACH framework in Europe, which adds complexity and cost.
- Legacy System Integration:Mismatches between modern, high-efficiency raw edge V belts and older, classical pulley groove profiles on legacy machinery can lead to suboptimal performance and accelerated wear if not properly managed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial V Belt Market |
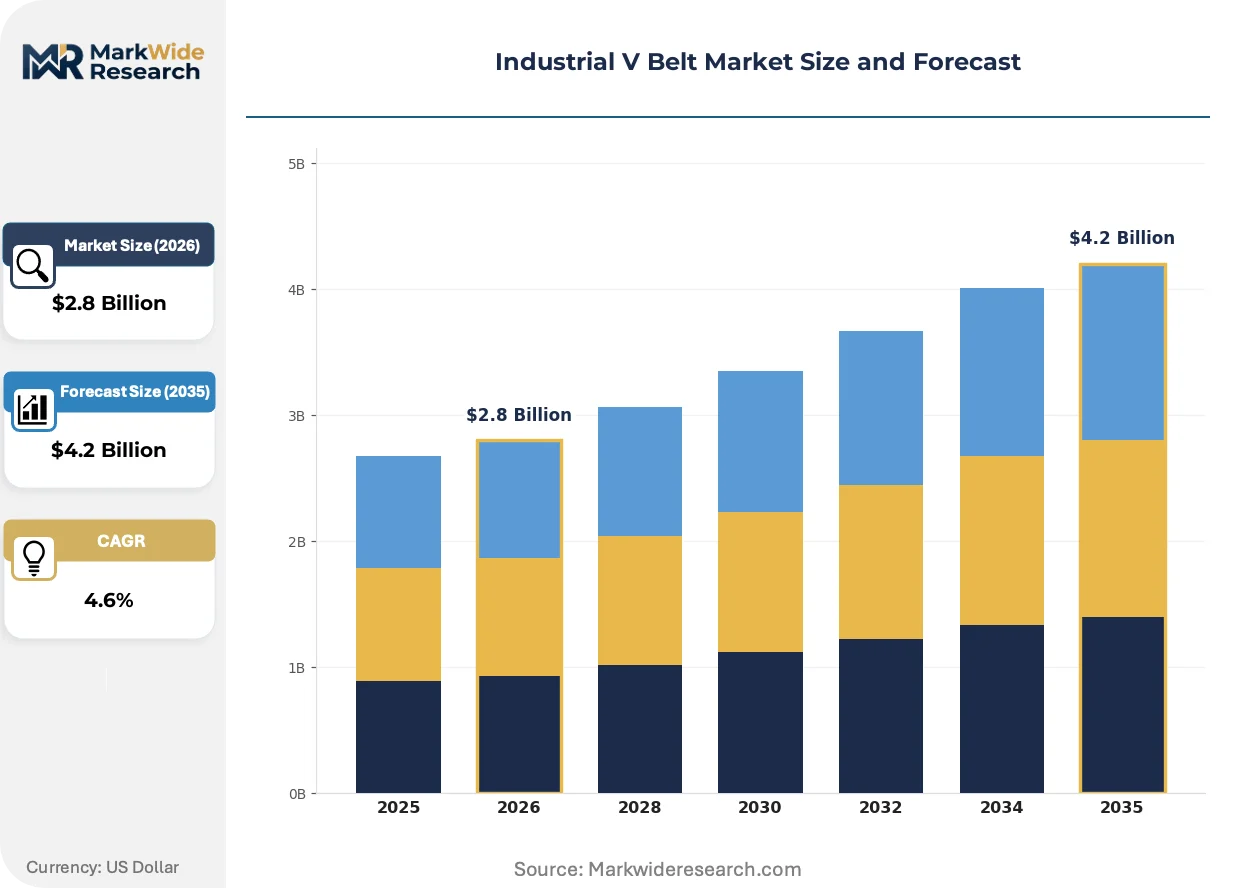
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Edge, Wrapped, Classical, Narrow End User: Manufacturing, Automotive, Agriculture, Mining Application: Power Transmission, Driven Application, Heavy Duty Machinery, HVAC Material: Polyester, Cotton, Rubber, Others |
| Companies Covered | Gates Corporation, Continental AG, Mitsuboshi Belting Ltd, Fenner Drives, Optibelt GmbH, Hutchinson, Dayco Products, Bando Chemical Industries, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial V Belt Market Strategic Shifts & Innovations
A fundamental re-evaluation of the V belt's role from a simple commodity to a critical component for system efficiency is underway. This shift is driven by advancements in material science that enable greater performance and by a growing end-user focus on total cost of ownership.
Advanced Composite Materials Advanced polyester and aramid fiber composites provide superior tensile strength and heat resistance compared to traditional materials. These high-performance belts are seeing rapid adoption in demanding environments such as mining conveyors and agricultural combines where durability is paramount. This advanced material science is converging with new manufacturing techniques to produce belts with tighter dimensional tolerances for improved efficiency.
Workplace Safety Mandates Regulations from bodies like the US OSHA on machine guarding directly influence equipment design. These rules require comprehensive guarding for belt-driven systems to prevent worker injury, compelling machinery OEMs to integrate safety features from the initial design phase. The heavy manufacturing and aggregate processing sectors are most impacted, often needing to retrofit older equipment to meet current safety standards.
Total Cost of Ownership Focus End-user procurement behavior is evolving, with a greater emphasis on total cost of ownership rather than just the initial purchase price. This trend favors suppliers of premium, energy-efficient raw edge V belts over cheaper, less efficient classical wrapped belts. The preference is most visible within automated manufacturing and logistics centers in countries like Mexico, where energy savings and maximum uptime are critical operational metrics.
Industrial V Belt Market Segmentation
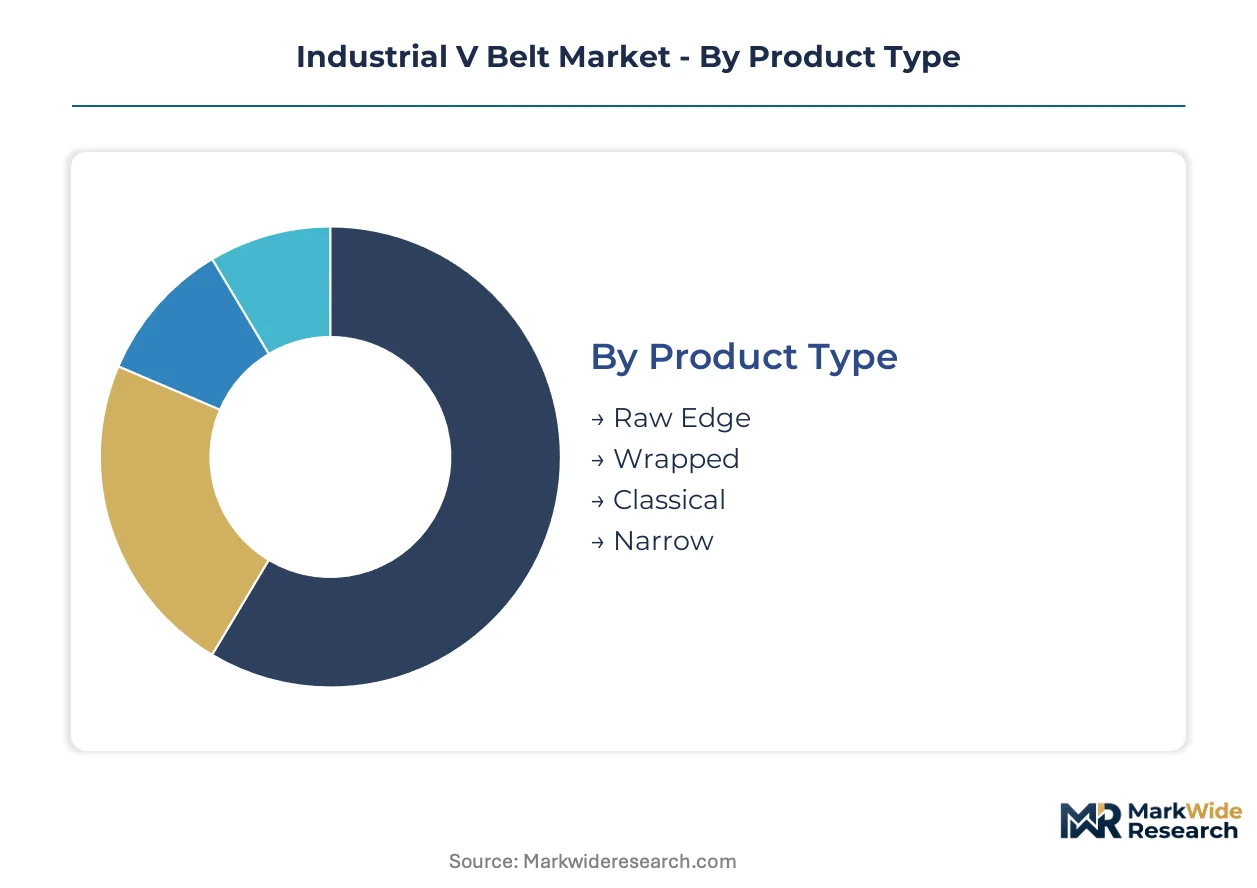
Segmentation within the industrial V belt market clarifies the diverse product offerings and their specific utility across various end-use sectors. This granular view helps manufacturers tailor solutions for distinct operational requirements and performance expectations. Understanding these segments is crucial for aligning product development with evolving industry demands.
Product Type:
The industrial V belt market differentiates products based on performance characteristics, often reflecting a split between high-volume, standard components and premium, engineered solutions for specific operational demands.
- Raw Edge:These belts feature precision-molded raw edges, offering higher power transmission efficiency and increased flexibility due to reduced internal friction. Demand is concentrating within automated manufacturing facilities in Mexico where energy savings are a critical operational metric.
- Wrapped:Traditional wrapped belts enclose the core components in a fabric cover, providing protection against abrasion and oil, suitable for general-purpose industrial applications. These belts maintain a substantial installed base in legacy systems across diverse manufacturing sectors.
- Classical:Classical V belts represent an older design standard, primarily used in established machinery and for replacement parts in the maintenance aftermarket.
- Narrow:Narrow V belts deliver higher power capacity in a more compact footprint, making them ideal for space-constrained applications and high-speed industrial equipment.
Today's leader: Wrapped belts. Tomorrow's challenger: Raw Edge belts.
End User:
End-user segmentation highlights the diverse operational environments where V belts are critical, from heavy industrial processes to specialized agricultural tasks.
- Manufacturing:This segment encompasses a broad range of industrial processes, including conveyors, machine tools, and pumps within automated production lines. Facilities in Vietnam and Mexico increasingly rely on V belts for efficient power transfer in their expanding operations.
- Agriculture:V belts are essential components in various agricultural machinery, including tractors, harvesters, and irrigation systems, facilitating power transmission for farming operations. Accelerated mechanization in developing economies like Vietnam drives sustained demand for reliable belts.
- Automotive:The automotive sector primarily utilizes V belts in the aftermarket for accessory drives and power steering systems in vehicles.
- Mining:Mining operations depend on robust V belts for heavy-duty conveyors and crushing equipment, requiring exceptional durability in harsh environments.
Agriculture is expanding most quickly due to accelerated mechanization in developing economies.
Application:
Applications define the specific functional roles V belts fulfill, ranging from fundamental power transfer to supporting complex machinery operations.
- Power Transmission:This fundamental application involves the efficient transfer of mechanical power and torque between rotating shafts in a wide array of industrial equipment. It remains the core function, essential for the operation of automated systems.
- HVAC:V belts are critical components in heating, ventilation, and air conditioning systems, driving fans, blowers, and compressors in commercial and industrial buildings. The large installed base of commercial HVAC equipment creates a recurring opportunity for replacement belts.
- Driven Application:This category includes specific equipment where V belts drive components like pumps, compressors, and generators within a larger system.
- Heavy Duty Machinery:V belts in heavy-duty machinery, such as large industrial conveyors or construction equipment, withstand high stress and continuous operation.
HVAC applications are seeing significant growth driven by energy efficiency mandates and system upgrades.
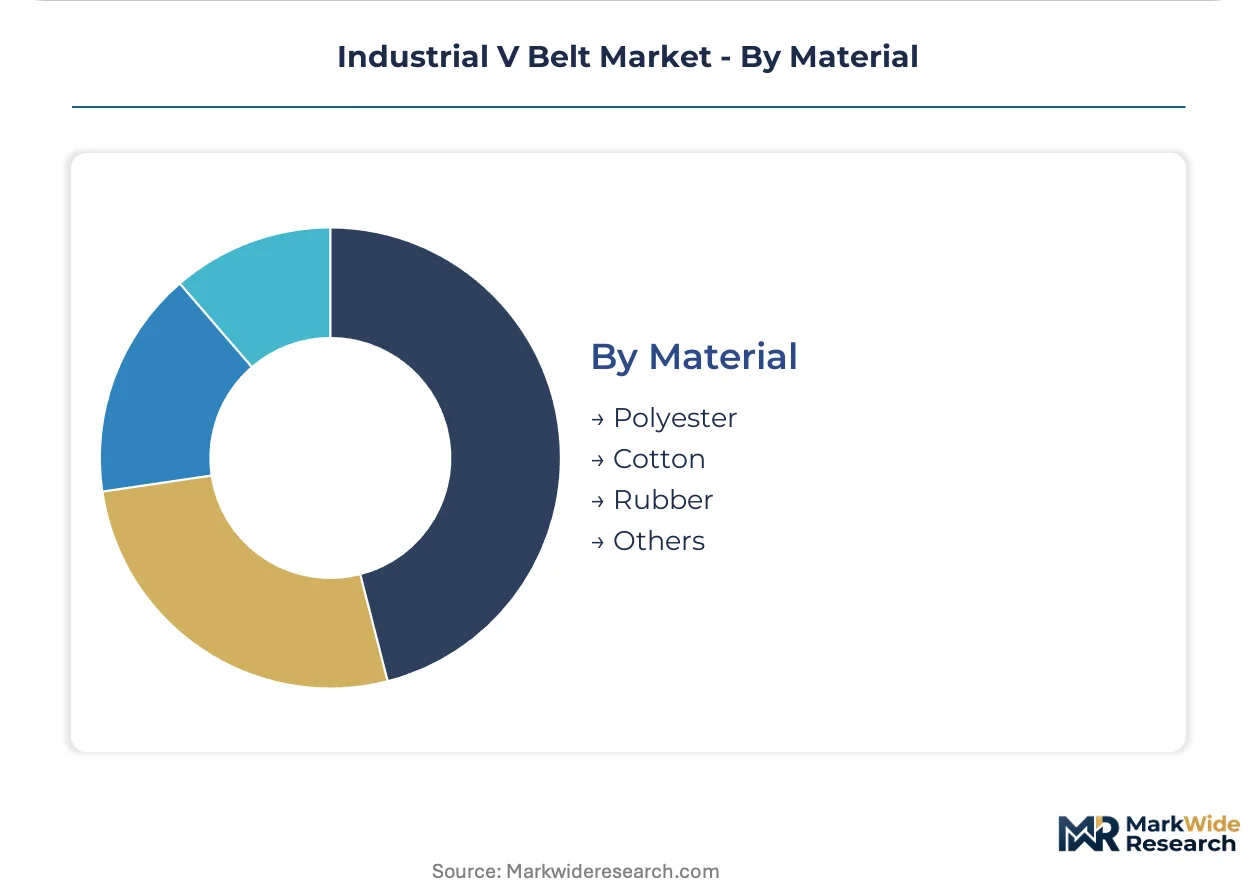
Material:
Material segmentation reflects the balance between performance requirements, cost implications, and regulatory compliance in V belt manufacturing.
- Rubber:Rubber remains the dominant material choice for V belts, offering excellent flexibility, grip, and cost-effectiveness for a wide range of industrial applications. Material advancements in rubber compounds enhance durability and temperature resistance.
- Polyester:Polyester is commonly used as a reinforcement cord in V belts, providing high tensile strength and dimensional stability for demanding power transmission tasks. Advanced polyester composites offer superior performance in high-stress environments.
- Cotton:Cotton was historically used in V belt construction, primarily for its flexibility, but is now largely confined to older systems and low-stress applications.
- Others:This category includes advanced materials like aramid fibers and EPDM rubber, specifically engineered for extreme temperatures, chemical resistance, or high-performance requirements.
Advanced material development in Polyester is defining new performance benchmarks for durability and efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated manufacturing facilities in Mexico and Vietnam, alongside expanding agricultural mechanization, drive significant demand for industrial V belts. This global market sees diverse regional pressures influencing material selection and product specifications. Energy efficiency mandates and workplace safety regulations further shape procurement decisions across industrial sectors.
Vietnam
Accelerated agricultural mechanization and expanding manufacturing sectors fuel substantial V belt demand in Vietnam. The country's industrial development policies prioritize localized production and technological upgrades. Industrial zones around Ho Chi Minh City attract foreign direct investment, boosting requirements for power transmission components in automated facilities.
Mexico
Nearshoring industrial hubs and the proliferation of automated manufacturing facilities drive V belt consumption in Mexico. Mexico's trade agreements, such as USMCA, foster a robust environment for industrial growth. Monterrey's advanced manufacturing sector demands high-efficiency power transmission solutions for its diverse production lines.
Germany
High-precision industrial equipment and a focus on advanced material science innovation characterize V belt demand in Germany. The ECHA's REACH regulation significantly influences material selection for rubber compounds used in V belts. Bavaria's strong automotive and machinery industries prioritize durable, high-performance V belts for continuous operation.
United States
The large installed base of commercial HVAC systems and heavy-duty agricultural machinery generate consistent V belt demand across the United States. US OSHA workplace safety rules mandate proper machine guarding, impacting equipment design. The Midwest's agricultural equipment manufacturing centers require robust V belt solutions for their varied product lines.
India
India's expanding agricultural sector and growing industrial base contribute significantly to V belt market growth. The "Make in India" initiative encourages domestic manufacturing capabilities for industrial components. Pune's automotive and engineering industries drive demand for reliable power transmission solutions in various applications.
Industrial V Belt Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the need to serve new industrial geographies and evolving material demands. The market structure is tiered, featuring global manufacturers, specialized material innovators, and regional aftermarket suppliers. Strategic partnerships and technology licensing represent other key competitive moves among market participants.
At the scale-driven end, Gates Corporation exemplifies a global player with an extensive distribution network serving diverse applications. Continental AG occupies a position as a material science innovator, developing belts for high-temperature and high-stress environments. Mitsuboshi Belting Ltd. sits within the specialized segment, focusing on power transmission solutions for the automotive aftermarket in Asia.
| Leading Market Players |
|---|
| Gates Corporation |
| Continental AG |
| Mitsuboshi Belting Ltd |
| Fenner Drives |
| Optibelt GmbH |
| Hutchinson |
| Dayco Products |
| Bando Chemical Industries |
| SKF |
| Others |
Cost & Logistics Intelligence
ECHA's REACH regulation gates both qualified supply and premium-tier pricing access for V belt manufacturers. This mandate necessitates specific material formulations, influencing production costs and market positioning for compliant products.
Pricing Analysis
Direct-to-OEM discounts and aftermarket distributor margins characterize the industrial V belt market's pricing structure. The dominant pricing model is per-unit transactional, supplemented by contract-based long-term agreements for large industrial buyers. Price differentiation stems from quality grade, particularly between raw edge and classical belts, and superior performance in high-stress environments. Pricing softness affects classical wrapped belts due to substitution by more efficient raw edge alternatives. Automated manufacturing facilities in Mexico exhibit lower price sensitivity, prioritizing total cost of ownership over initial purchase price.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns support the industrial V belt supply chain. Geographic supply concentrates in manufacturing hubs like Vietnam, Mexico, and Germany. The industry draws from raw material dependencies on natural rubber, synthetic polymers such as EPDM, and polyester cords. Input cost volatility for natural rubber and synthetic polymers represents a key structural supply chain risk. Downstream distribution runs through extensive networks serving both OEM and aftermarket channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial V belt market presents a margin-expansion story, driven by the shift towards high-performance, energy-efficient raw edge belts and a focus on total cost of ownership.
For Market Incumbents: Cement market leadership through continuous material science innovation, particularly in advanced polyester and aramid composites. Expand technical support and distribution within nearshoring industrial hubs like Mexico to better serve automated facilities. This counters substitution threats from direct drives in new equipment designs and reinforces channel control.
For New Entrants and Emerging Players: Facility management companies represent a key channel for market penetration. Target the large aftermarket for high-efficiency HVAC systems with energy-saving raw edge belts. Develop V belts with embedded sensors for predictive maintenance, offering a service-oriented revenue stream and enabling white-space entry into critical industrial applications.
For Investors and Strategic Acquirers: Roll-up economics work for specialized material science innovators because the market values performance over commodity components. The long-term viability of the V belt market remains strong for the next 5-10 years due to ongoing industrial automation and agricultural mechanization. Focus on acquiring companies with advanced composite expertise or strong aftermarket presence in growing regions. Watch for the accelerated adoption of sensor-integrated V belts as an inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports growing demand from automated manufacturing facilities in new industrial geographies like Mexico. |
| Material Science R&D | Develops advanced rubber and polyester composites for enhanced durability and power transmission efficiency. |
| Predictive Maintenance Integration | Offers higher-margin, service-oriented revenue streams by preventing unplanned downtime in critical systems. |
| Distribution Network Optimization | Ensures efficient delivery to nearshoring hubs and the expanding aftermarket for HVAC systems. |
| Regulatory Compliance Investment | Adapts material formulations to meet evolving chemical safety regulations such as ECHA's REACH framework. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This involved interviews with plant engineers, OEM procurement teams, and distribution channel partners. Secondary validation drew from ISO standards documents, ECHA REACH guidelines, and trade association publications. Bottom-up and top-down triangulation ensured data integrity and comprehensive market understanding.
Rate-of-change decomposition framed the analytical framework across the analysis window. Segmentation modeled product type, end user, application, material, and regional manufacturing output. Compound annual growth rates derived from historical trends and projected shifts in industrial automation. Industrial production indices and agricultural mechanization rates served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and technological substitution. The forecasts reflect assumptions regarding industrial growth and regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Tire Mold Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Norway Automotive Engine Oils Market