
 Tire Mold Market | 2026-2036
Tire Mold Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Mold Market Analysis
Modular mold segment offerings is rebalancing procurement patterns among tire manufacturers seeking flexible capacity without full capital commitment. Himile Mechanical Science & Technology anchors its position through integrated casting and machining operations. Shinko Mold Industrial Co. Ltd. differentiates via precision thermal control systems for high-performance radial production. Greatoo Inc. competes aggressively on cost-engineered solutions for emerging market tire builders.
A tire mold is a precision-engineered cavity assembly, typically machined from forged steel or aluminum blocks with tolerances below 0.02 millimeters, that shapes uncured rubber compounds into tread patterns and sidewall geometries during vulcanization. Radial molds command the largest revenue share due to passenger vehicle fleet turnover and OE fitment requirements, while 3D printing technology in mold prototyping is compressing development cycles for specialty and low-volume tire programs. Steel remains the dominant material category for heavy-duty truck molds where thermal fatigue resistance determines operational lifespan.
EPA emissions thresholds for tire manufacturing facilities indirectly constrain mold design by limiting curing cycle energy intensity, while China's SAMR enforces GB standards on mold dimensional repeatability that affect cross-border equipment certification. The EU F-Gas Regulation phases down fluorinated greenhouse gases used in certain mold release agent formulations, altering maintenance chemical specifications. Stakeholders must monitor how dual carbon goals in Beijing and Brussels reshape capital allocation toward energy-efficient curing technologies and recycled-content mold materials.
Market Dynamics
Modular mold architectures are forcing traditional capital equipment vendors to reconfigure their commercial models as tire manufacturers seek flexible capacity commitments rather than outright ownership.
Growth Catalysts
- Commercial fleet replacement cycles:Logistics operators in North America and Europe are accelerating tire refresh schedules to maintain fuel efficiency ratings, pulling demand for high-precision radial molds.
- REACH material compliance:ECHA surface treatment specifications for mold release agents are creating upgrade demand across European tire production facilities.
- 3D printing in prototyping:Additive manufacturing is compressing development timelines for specialty tread patterns, enabling faster OEM validation cycles.
Market Restraints
- Forged steel input volatility:Alloy steel billet prices fluctuate with scrap metal markets, squeezing margin predictability for heavy-duty truck mold producers.
- Supplier concentration in East Asia:Integrated casting and machining capacity clusters predominantly in China, creating geographic risk exposure for buyers elsewhere.
- Fluorinated compound phase-down:EU F-Gas Regulation restrictions on certain mold release formulations force reformulation investments without immediate performance equivalence.
Strategic Opportunities
- Captive mold production in India:Domestic tire makers under PLI scheme incentives are building in-house tooling capacity, creating equipment supply partnerships.
- Recycled-content mold materials:Beijing's dual carbon goals are pressuring state-owned tire producers to specify molds with lower embodied carbon, favoring suppliers with certified green steel sourcing.
- Precision thermal control convergence:Integration of IoT sensors with traditional mold heating systems enables real-time curing optimization, opening premium service attach rates.
Industry Challenges
- CNC programming expertise scarcity:Complex tread pattern geometries require specialized five-axis machining knowledge that outpaces vocational training pipeline output.
- Cross-border certification timelines:China's SAMR dimensional repeatability standards create documentation bottlenecks for mold imports from non-GB-certified facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Mold Market |
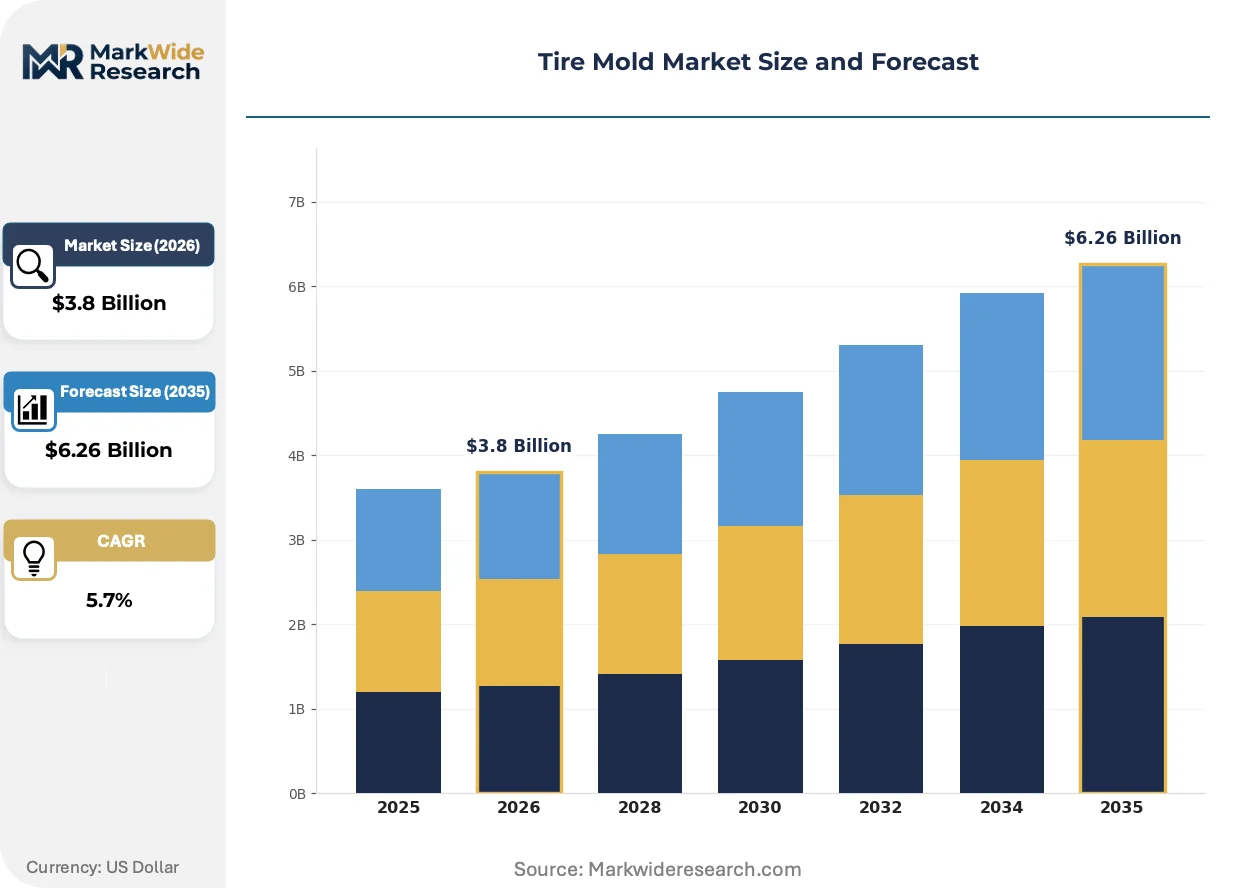
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Molds, Bias Molds, Truck Molds, Specialty Molds Material: Steel, Aluminum, Composite, Rubber End User: Tire Manufacturers, OEMs, Aftermarket Providers, Distributors Technology: Thermal Molding, Compression Molding, Injection Molding, 3D Printing |
| Companies Covered | Tianyang Mold Co. Ltd., Shinko Mold Industrial Co. Ltd., Himile Mechanical Science & Technology, MESNAC Co. Ltd., King Machine Tire Molds, Greatoo Inc., Saehwa IMC, A-Z Formen- und Maschinenbau GmbH, HERBERT Maschinenbau GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Mold Market Emerging Trajectories
Digital design-to-manufacture pipelines are collapsing traditional mold development timelines while regulatory chemistry restrictions force material science pivots across the supply base.
Direct metal laser sintering is overtaking conventional EDM finishing for complex venting geometries in prototype molds. Tier-one tire makers in Germany and Japan are adopting this approach for low-volume motorsport programs. The technology is overtaking legacy methods by eliminating electrode fabrication lead times and enabling topology-optimized cooling channel designs previously impossible to machine.
EPA emissions thresholds for tire manufacturing facilities are indirectly constraining curing cycle energy intensity, forcing mold designers to optimize thermal mass and heating uniformity. Mold producers serving US-based tire plants must now document energy-per-cure metrics to maintain preferred supplier status. Heavy-duty steel segment molds face the steepest redesign pressure given their thermal inertia.
Outcome-based service contracts are replacing traditional equipment sales in the passenger radial segment. Tire manufacturers in Southeast Asia are piloting pay-per-cure arrangements where mold suppliers retain ownership and guarantee dimensional stability over contract terms. This model is most visible in Thailand and Indonesia where capital constraints meet aggressive capacity expansion timelines.
Tire Mold Market Segmentation
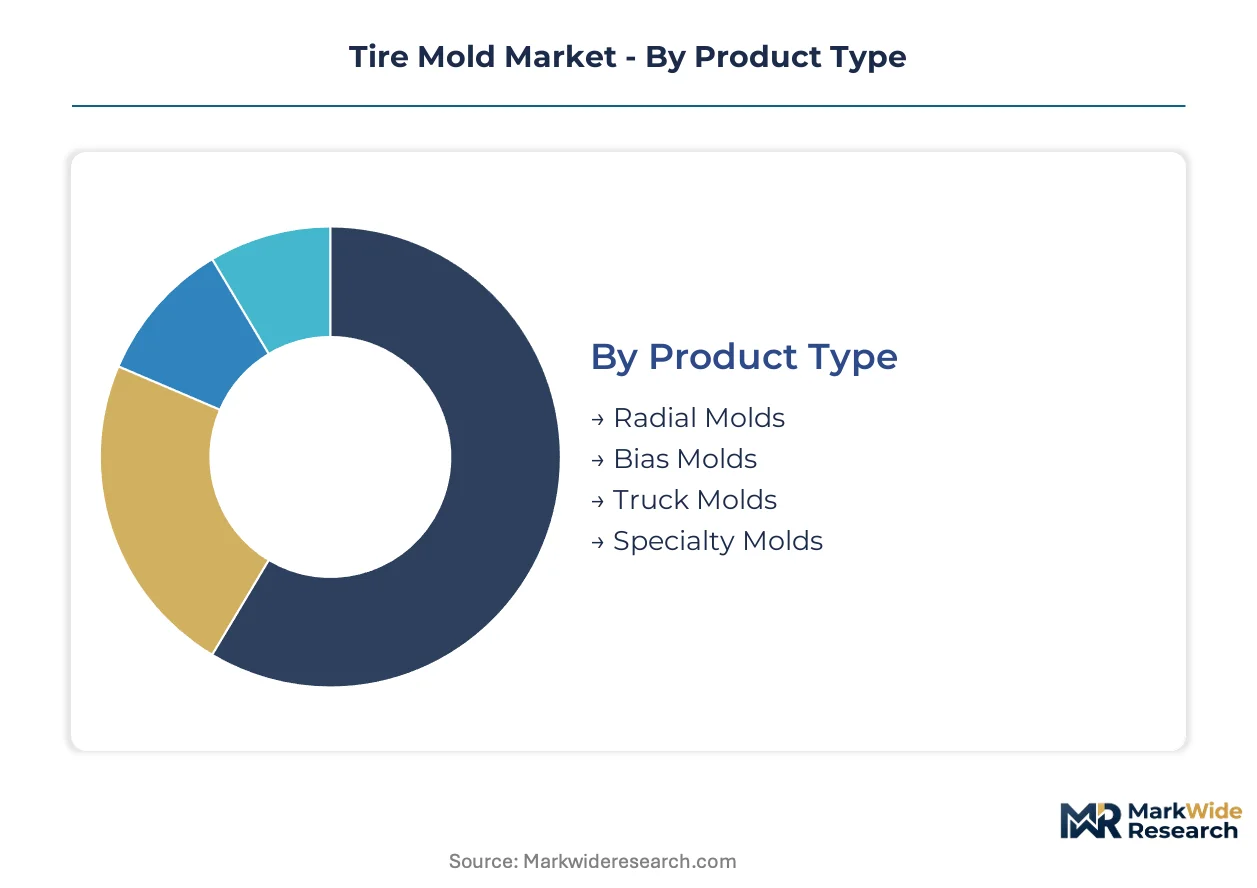
Tire mold segmentation reveals divergent margin profiles across product architectures and material specifications. Procurement patterns split between high-volume standardized radial production and low-volume specialty programs requiring rapid design iteration.
Product Type:
Volume concentration dominates passenger radial applications while premium pricing attaches to complex tread geometries for commercial and specialty segments.
- Radial Molds:These precision cavity assemblies machine forged steel or aluminum blocks to tolerances below 0.02 millimeters for passenger vehicle vulcanization. Demand concentrates in China where domestic tire makers are scaling captive mold production capacity under state industrial policy support.
- Truck Molds:Heavy-duty steel constructions engineered for thermal fatigue resistance across extended curing cycles for commercial fleet tire production. North American logistics operators are accelerating tire refresh schedules to maintain fuel efficiency ratings, pulling order volumes for high-precision radial truck mold configurations.
- Bias Molds:Cross-ply cavity designs serving agricultural and off-road equipment tire builders in emerging markets.
- Specialty Molds:Custom tread patterns for motorsport and industrial applications requiring compressed development timelines.
Mature deployment sits with Radial Molds. Newer deployment is concentrated in Specialty Molds.
Material:
Cost tier separation runs from commodity steel through engineered composites with divergent thermal performance profiles.
- Steel:Forged alloy billets deliver thermal mass stability for heavy-duty truck mold applications where operational lifespan determines total cost of ownership. REACH compliance in Europe and China's evolving GB standards are tightening material specifications for mold surfaces across steel suppliers.
- Aluminum:Lightweight blocks enabling faster heating cycles and reduced energy intensity for passenger radial production. EPA emissions thresholds for tire manufacturing facilities indirectly constrain mold design by limiting curing cycle energy intensity, favoring aluminum thermal mass in US-based tire plants.
- Composite:Hybrid material constructions blending thermal conductivity with corrosion resistance for specialized chemical environments.
- Rubber:Prototype and temporary cavity liners for design validation before hardened steel production.
Steel retains the dominant installed base. Aluminum is gaining share fastest in new capacity additions.
End User:
Customer type differentiation separates capital-constrained aftermarket distributors from integrated tire manufacturers with captive engineering resources.
- Tire Manufacturers:Direct procurement of precision molds for in-house vulcanization lines with volume commitments spanning multi-year contracts. Modular mold segment offerings are rebalancing procurement patterns among tire manufacturers seeking flexible capacity without full capital commitment.
- OEMs:Original equipment fitment specifications requiring dimensional repeatability certification under China's SAMR GB standards for cross-border equipment validation.
- Aftermarket Providers:Independent retread and replacement tire producers sourcing cost-engineered mold solutions.
- Distributors:Inventory-holding intermediaries serving fragmented regional tire builder markets with standardized mold specifications.
Integrated procurement dominates Tire Manufacturers. Fragmented purchasing characterizes Distributors.
Technology:
Maturity gradient separates established thermal and compression methods from emerging additive manufacturing approaches.
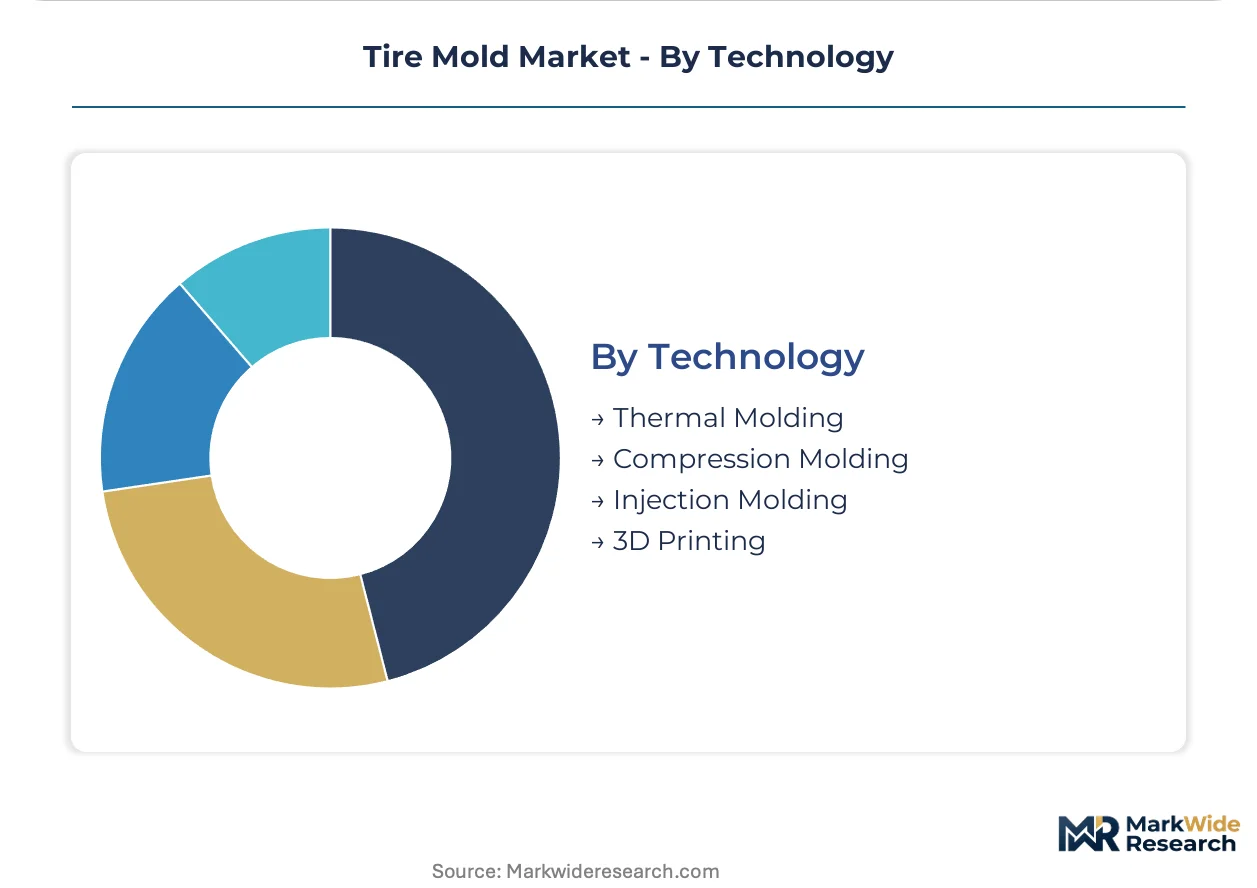
- Thermal Molding:Conventional heating systems with integrated temperature control for uniform vulcanization across cavity surfaces. Shinko Mold Industrial Co. Ltd. differentiates via precision thermal control systems for high-performance radial production.
- 3D Printing:Direct metal laser sintering overtaking conventional EDM finishing for complex venting geometries in prototype molds. Tier-one tire makers in Germany and Japan are adopting this approach for low-volume motorsport programs, eliminating electrode fabrication lead times.
- Compression Molding:Mechanical force application for simpler tread patterns in high-volume commodity tire production.
- Injection Molding:Liquid rubber injection systems for specialized compound distribution in complex sidewall geometries.
Thermal Molding represents the established installed base. 3D Printing shows the steepest expansion trajectory in prototyping applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of tire molds consumed worldwide, yet commercial fleet replacement cycles in the United States and Europe generate the largest order values for precision radial configurations. This production-consumption asymmetry shapes cross-border equipment flows and certification requirements.
China
Domestic tire makers under state industrial policy support are scaling captive mold production capacity in Shandong and Jiangsu provinces. SAMR enforces GB standards on mold dimensional repeatability that affect cross-border equipment certification for export-bound production. Qingdao and Weifang host concentrated clusters where integrated casting and machining operations serve both captive and merchant demand.
United States
North American logistics operators are accelerating tire refresh schedules to maintain fuel efficiency ratings, pulling demand for high-precision radial truck molds. EPA emissions thresholds for tire manufacturing facilities indirectly constrain mold design by limiting curing cycle energy intensity. Ohio and Tennessee house major tire production facilities where mold suppliers must document energy-per-cure metrics to maintain preferred supplier status.
Germany
Tier-one tire makers in Germany are adopting direct metal laser sintering for low-volume motorsport programs, compressing development timelines for specialty tread patterns. ECHA surface treatment specifications under REACH compliance create upgrade demand across European tire production facilities. Baden-Württemberg and Bavaria concentrate precision engineering capacity serving premium OE fitment requirements.
India
Domestic tire makers under PLI scheme incentives are building in-house tooling capacity, creating equipment supply partnerships for modular mold architectures. BIS certification requirements for imported industrial equipment add procedural steps for cross-border mold transactions. Maharashtra and Gujarat host emerging production clusters where state industrial incentives attract mold fabrication joint ventures.
Japan
Precision thermal control systems for high-performance radial production command premium positioning in Japanese technical specifications. METI industrial standards influence mold material selection for domestic tire export programs. Nagoya and Osaka metropolitan areas maintain specialized machining expertise for complex tread pattern geometries requiring five-axis CNC programming.
Tire Mold Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: integrated casting-machining operators, precision thermal control specialists, and cost-engineered solution providers. Scale-driven capacity expansion and technology licensing partnerships represent the dominant competitive moves as manufacturers seek geographic coverage without greenfield facility investment.
Among China-based fabricators, Himile Mechanical Science & Technology Co., Ltd. and Greatoo Inc. exemplify divergent positioning archetypes within the domestic supply base. Shinko Mold Industrial Co. Ltd. occupies a position representing precision thermal control specialization for high-performance applications. These three companies anchor the competitive spectrum from cost-engineered volume production to premium technical specifications.
| Leading Market Players |
|---|
| Tianyang Mold Co. Ltd. |
| Shinko Mold Industrial Co. Ltd. |
| Himile Mechanical Science & Technology |
| MESNAC Co. Ltd. |
| King Machine Tire Molds |
| Greatoo Inc. |
| Saehwa IMC |
| A-Z Formen- und Maschinenbau GmbH |
| HERBERT Maschinenbau GmbH |
| Others |
Supply Flow & Price Mechanics
Five-axis CNC programming expertise concentration in Japan's Nagoya and Osaka metropolitan areas feeds labor-cost differentials that widen pricing-tier spreads between premium thermal-control systems and commodity radial mold offerings.
Pricing Analysis
Margin tightening in heavy-duty steel truck molds reflects forged alloy billet price volatility tied to scrap metal markets. Three-tier pricing structure across precision thermal-control, standard radial, and economy bias configurations separates buyers by certification grade and volume commitment. Cost-down pressure on aluminum passenger radial segments accelerates as EPA emissions thresholds force energy-per-cure documentation. Aftermarket distributors exhibit highest price sensitivity; integrated tire manufacturers with captive engineering resources absorb premium positioning for dimensional repeatability guarantees.
Supply Chain Analysis
Dual-sourcing requirements from tier-one tire makers in Germany and Japan mandate multi-supplier qualification across China, Japan, and Germany for critical thermal-control components. Raw material flows draw from forged steel billet producers, aluminum block suppliers, and precision machining equipment manufacturers. Single-source vulnerability concentrates in East Asian integrated casting and machining clusters. Distribution runs through direct long-term contracts with tire manufacturers and equipment supply partnerships with emerging captive producers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH surface treatment specifications and China's SAMR GB standards erect barrier-to-entry moats favoring incumbents with certified European and Chinese regulatory dossiers.
For Market Incumbents: Deploy precision thermal control convergence as the primary defensive lever. Integrate IoT sensors with traditional mold heating systems to capture premium service attach rates and real-time curing optimization revenue streams. Counter modular mold architecture threats by anchoring long-term outcome-based contracts with guaranteed dimensional stability terms. Deepen backward integration into certified green steel sourcing to meet Beijing's dual carbon procurement mandates from state-owned tire producers. For New Entrants and Emerging Players: India's PLI scheme incentives open a window for equipment supply partnerships with domestic tire makers building in-house tooling capacity. Target Maharashtra and Gujarat emerging production clusters where state industrial incentives attract joint ventures. Pursue modular mold architecture white-space in Southeast Asian pay-per-cure pilot programs. Lead with cost-engineered aluminum solutions for capital-constrained Indonesian and Thai tire manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with precision thermal control specialists given IoT-enabled curing optimization catalysts. Long-term viability favors vendors with dual REACH and GB certification coverage spanning European and Chinese regulatory jurisdictions. Monitor equipment supply partnership announcements from Indian PLI scheme beneficiaries as inflection indicators for geographic demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Green Steel Sourcing | Beijing's dual carbon goals pressure state-owned tire producers to specify lower-embodied-carbon mold materials. |
| IoT Sensor Integration for Thermal Control | Real-time curing optimization opens premium service attach rates with tire manufacturers in Germany and Japan. |
| Outcome-Based Service Contract Pilots | Pay-per-cure arrangements in Thailand and Indonesia address capital constraints during aggressive capacity expansion. |
| Direct Metal Laser Sintering Prototyping Capacity | Additive manufacturing compresses development timelines for low-volume motorsport programs at tier-one German tire makers. |
| Joint Ventures in Indian Production Clusters | Maharashtra and Gujarat state incentives attract mold fabrication partnerships under PLI scheme coverage. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tire manufacturer procurement directors, mold fabrication plant managers, five-axis CNC programming specialists, and aftermarket distributor operations heads combined with secondary validation from ECHA REACH dossiers, SAMR GB standard publications, and EPA emissions compliance documentation. Bottom-up mold shipment tracking and top-down tire production capacity modeling enabled triangulation across data sources.
Granularity-level modeling disaggregated volume and value outputs across product type, material specification, end-user category, and technology maturity dimensions. CAGRs were derived from segment-level growth trajectory analysis. Forecast inputs incorporated commercial fleet replacement cycle intensity, regulatory chemistry restriction timelines, and 3D printing adoption curves in prototype applications.
The model assumes a particular technology adoption path; alternative pathways for direct metal laser sintering penetration would alter the outlook. Forecasts reflect assumptions regarding REACH compliance upgrade schedules and PLI scheme incentive continuity. Deviation in alloy steel billet price volatility or SAMR certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
North America Ceramic Ball Bearings Market