
 Rolling Stock Wheel Market | 2026-2036
Rolling Stock Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Rolling Stock Wheel Market Insights
Steel is consolidating its dominance over cast iron in rolling stock wheel production as thermal fatigue resistance and axle-load capacity become decisive procurement criteria. Interpipe leverages its integrated steelmaking and forging infrastructure to supply European and Asian rail operators with vacuum-degassed wheel blanks. Amsted Rail anchors North American demand through its network of foundries and heat-treatment facilities optimized for heavy-haul freight applications. Lucchini RS specializes in high-speed passenger wheel sets, competing on metallurgical precision for tilting-train and intercity platforms.
A rolling stock wheel is a load-bearing steel or cast-iron disc mounted on a railway axle, typically forged from Class B vacuum-degassed steel per AAR M-107/M-208 specifications and heat-treated to achieve 320–360 Brinell hardness, designed to transmit traction, braking, and vertical loads to the rail head while resisting shelling and thermal cracking. Freight car wheels and locomotive wheels command the largest volume pools, though high-speed train wheel demand generates disproportionate margin concentration due to stringent metallurgical certification and shorter replacement cycles. Composite and aluminum materials occupy niche positions in light rail and metro segments where unsprung mass reduction yields energy savings, but steel retains structural primacy across intercity and heavy-haul duty cycles.
The US Federal Railroad Administration mandates ultrasonic testing and thermal fatigue validation under 49 CFR Part 215, while the EU F-Gas Regulation and MDR framework indirectly shape wheel procurement through embedded carbon accounting in rolling stock tendering. China's NMPA and GB standards enforce domestic alloy specifications that foreign suppliers must meet through joint-venture localization or technology transfer. Stakeholders must monitor divergence between North American AAR specifications and emerging EN 13262 amendments, as incompatible certification paths threaten to fragment supplier economies of scale.
Market Dynamics
The transition from cast iron to forged steel wheel compositions is compressing replacement cycles and redrawing procurement specifications across freight and passenger rail networks. Thermal fatigue standards enforced by the US Federal Railroad Administration and China's GB specifications are forcing metallurgical upgrades that favor integrated steelmakers with vacuum-degassing capabilities.
Growth Catalysts
- Freight axle-load escalation:North American Class I railroads are pushing 286,000-pound gross rail load limits, mandating higher-grade steel wheels with enhanced rim strength and tread durability.
- 49 CFR Part 215:The US Federal Railroad Administration's ultrasonic testing and thermal fatigue validation requirements are disqualifying lower-grade wheel suppliers and consolidating procurement toward certified domestic and import sources.
- High-speed rail expansion:China's state-backed rail modernization programs sustain concentrated demand for passenger car wheels with shorter replacement intervals and premium alloy specifications.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face input cost swings that compress forging margins and complicate long-term contract pricing with rail operators.
- Supplier concentration in Eurasia:Integrated steel-wheel production clusters in Ukraine and Russia create geographic supply risk that rail operators hedge through dual-source mandates and strategic inventory builds.
- Composite material substitution:Aluminum and carbon-fiber wheel technologies are capturing niche share in light rail and metro segments where unsprung mass reduction yields measurable energy savings.
Strategic Opportunities
- Indian freight corridor modernization:Dedicated freight corridors under the Ministry of Railways are generating procurement volume for heavy-haul wheels compatible with 25-ton axle loads and tropical climate conditions.
- EU Green Deal embedded carbon accounting:The F-Gas Regulation and emerging CSRD disclosure requirements are creating preference for low-carbon steel wheels with documented Scope 3 emissions reductions.
- Predictive maintenance integration:Wheel-mounted sensor systems converging with IoT telemetry are enabling condition-based replacement contracts that shift revenue from unit sales to performance-guaranteed service agreements.
Industry Challenges
- AAR M-107/M-208 certification timelines:New alloy formulations require 18-24 months of field testing and Association of American Railroads approval, delaying product commercialization and locking out speculative R&D investments.
- Heat-treatment skill scarcity:Specialized furnace operators and metallurgical engineers with vacuum-degassing expertise are concentrated at legacy facilities, constraining capacity expansion and geographic diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolling Stock Wheel Market |
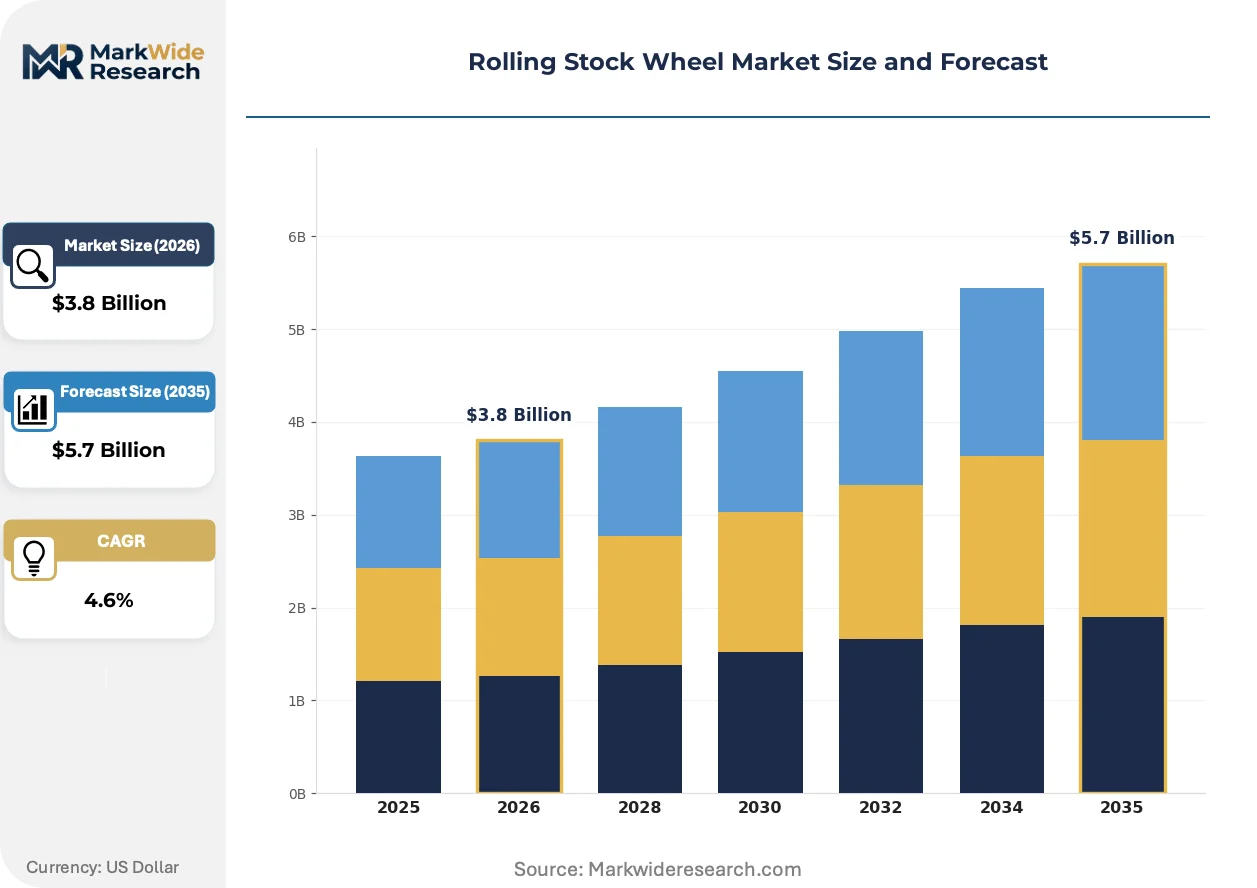
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locomotive Wheels, Passenger Car Wheels, Freight Car Wheels, Specialty Wheels Material: Steel, Cast Iron, Composite, Aluminum Usage: High-Speed Trains, Cargo Trains, Light Rail Vehicles, Maintenance of Way Manufacturing Process: Forging, Casting, Machining, Heat Treatment |
| Companies Covered | Interpipe, Amsted Rail, OMK Steel, Masteel Group, EVRAZ NTMK, ZHIQI RAILWAY EQUIPMENT, Nippon Steel Corporation, Lucchini RS, Bharat Forge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolling Stock Wheel Market Trends and Innovations
Digital thread technologies and embedded sensing are transforming wheelsets from passive components into data-generating assets. Three convergent developments are reshaping how rail operators specify, procure, and manage wheel life cycles across freight and passenger applications.
Vacuum-degassed Class B steel is absorbing market share from traditional rim-quenched grades as thermal crack resistance becomes the decisive specification criterion. Freight operators in North America and Eurasia are accelerating adoption of premium-grade compositions to extend service intervals under heavier axle loads. This metallurgical upgrade is absorbing margin from commodity wheel suppliers and concentrating procurement toward integrated steelmakers with in-house forging and heat-treatment capabilities.
China's NMPA and GB standards are tightening domestic alloy specifications that foreign suppliers must meet through joint-venture localization or technology transfer agreements. The industrial consequence is a bifurcation of certification paths: wheels destined for Chinese state rail procurement require domestic testing protocols, while export-oriented production follows AAR or EN 13262 specifications. European and North American OEMs are responding by establishing captive forging partnerships within China rather than relying on import qualification.
Condition-based replacement contracts are displacing traditional time-based procurement in high-speed passenger segments. Rail operators in Japan and Western Europe are unbundling wheel supply from installation and maintenance, awarding multi-year performance agreements to suppliers guaranteeing availability and tread life metrics. This behavioral shift is most visible in the Shinkansen and TGV networks, where downtime costs exceed component replacement economics and predictive analytics enable just-in-time wheel changeouts.
Rolling Stock Wheel Market Segmentation
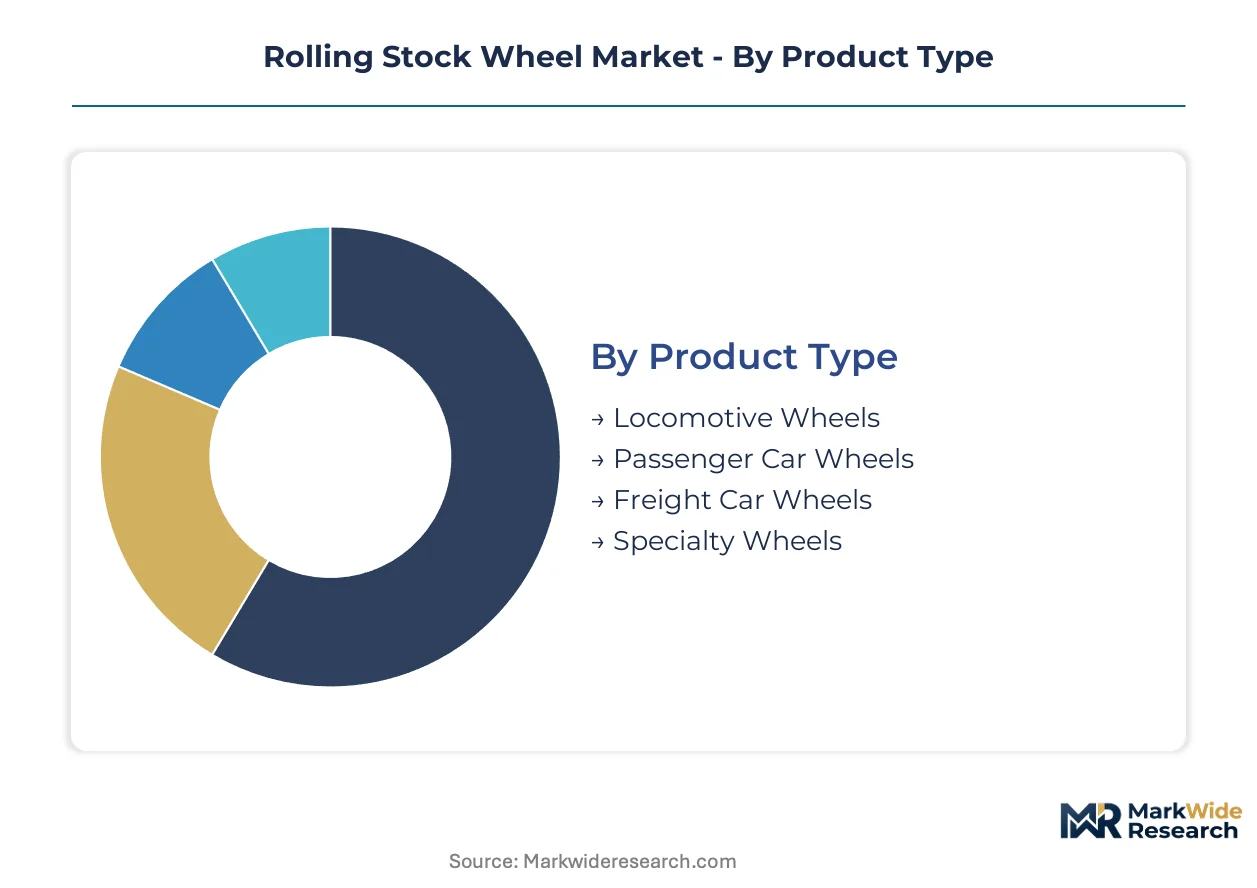
Wheel specification varies sharply across rail duty cycles, with metallurgical grade and manufacturing method determining service intervals and procurement cost structures. Segmentation reveals how freight operators prioritize rim durability under thermal loading while passenger networks optimize for unsprung mass and ride quality.
Product Type:
Wheel diameter and rim profile specifications diverge according to axle-load requirements and braking system configurations.
- Freight Car Wheels:Forged steel construction with 36-inch nominal diameter dominates heavy-haul procurement in the US and Russia. Rim-quenched Class B steel withstands thermal cracking under continuous braking on mountain grades.
- Locomotive Wheels:High-power traction motors demand 40-inch forged wheels with enhanced web strength. Chinese railways specify premium vacuum-degassed grades for 25-ton axle loads on coal corridors.
- Passenger Car Wheels:High-speed applications require tighter dimensional tolerances and shorter replacement intervals. TGV and Shinkansen networks specify forged wheels with 330–350 Brinell hardness.
- Specialty Wheels:Low-floor tram and metro applications use compact 22–28-inch diameters. European light rail operators specify noise-dampened wheel profiles for urban tunnel segments.
Mature deployment sits with Freight Car Wheels. Newer deployment is concentrated in Specialty Wheels for urban transit expansion.
Material:
Material selection tracks thermal fatigue resistance requirements and embedded carbon accounting pressures across procurement jurisdictions.
- Steel:Vacuum-degassed Class B compositions per AAR M-107/M-208 specifications command premium pricing in North American heavy-haul. Integrated steelmakers with in-house forging capture margin from commodity rim-quenched grades.
- Cast Iron:Pearlite-grade compositions persist in low-speed freight and industrial switching applications. Russian and Indian railways maintain legacy procurement for non-interchange service.
- Composite:Carbon-fiber reinforced polymer wheels reduce unsprung mass by 40–50% in light rail. German and French tram networks trial hybrid construction for energy recovery systems.
- Aluminum:Forged aluminum alloys serve metro applications where acceleration performance outweighs wear-rate penalties. Japanese subways specify aluminum for frequent-stop duty cycles.
Steel commands volume concentration across intercity and freight networks. Composite materials are expanding most quickly in European urban transit procurement.
Usage:
Operating speed and duty cycle intensity dictate wheel replacement economics and supplier qualification requirements.
- Cargo Trains:Heavy-haul unit trains in Australia and Brazil operate 286,000-pound gross loads with forged steel wheels replaced on tread-wear schedules. Thermal damage from dynamic braking accelerates rim replacement.
- High-Speed Trains:Passenger wheels on China's Beijing-Shanghai corridor require ultrasonic inspection every 180,000 kilometers. Shorter service intervals concentrate procurement volume despite smaller fleet size.
- Light Rail Vehicles:Street-running trams face abrasive rail conditions and tight curve radii. Wheel flange wear dominates replacement triggers in European and North American urban systems.
- Maintenance of Way:Work equipment wheels operate at low speeds with intermittent loading. Grind-and-profile machines use hardened steel wheels for rail surface restoration.
Cargo Trains anchor procurement volume globally. High-Speed Trains generate disproportionate margin concentration due to certification barriers.
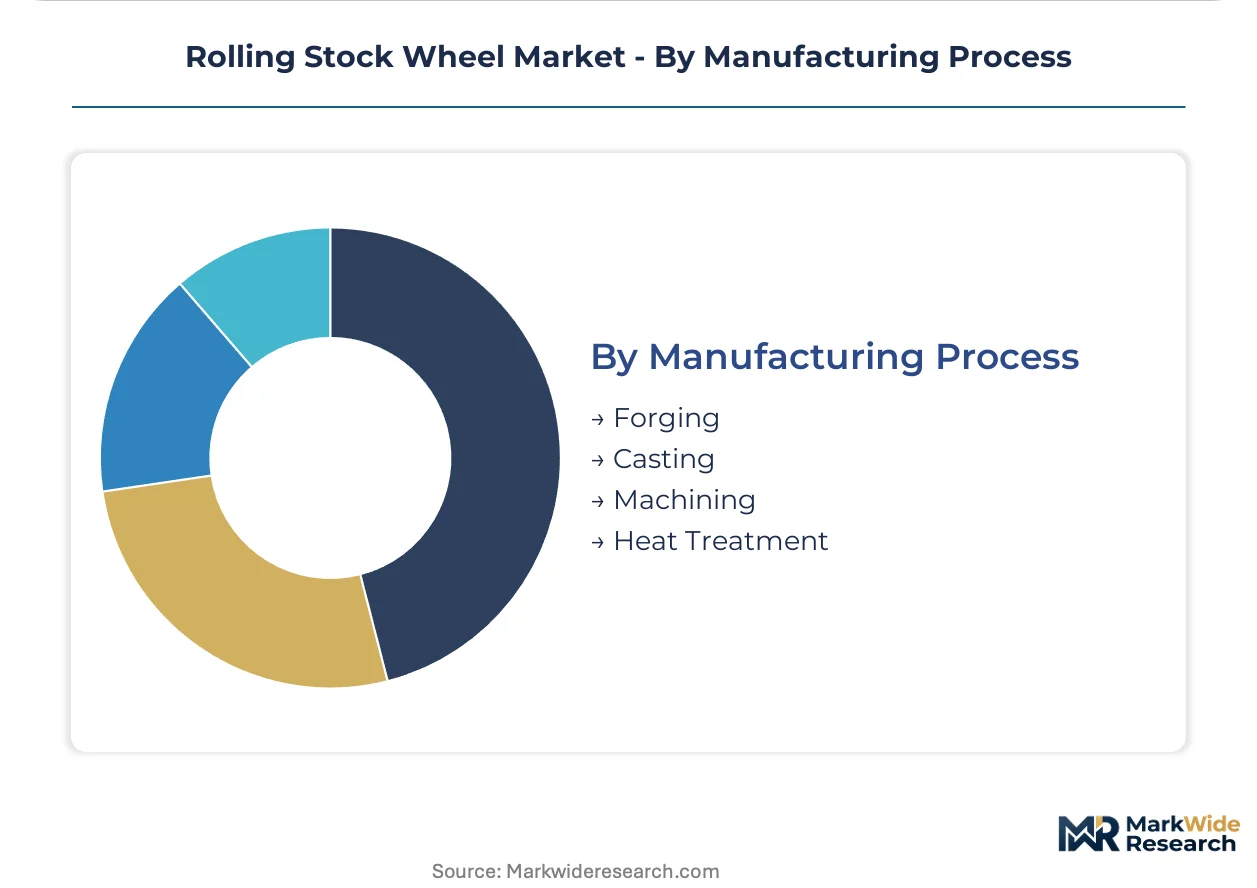
Manufacturing Process:
Process selection determines microstructure uniformity and defect detection capabilities required by regulatory specifications.
- Forging:Closed-die forging of vacuum-degassed billets produces radial grain flow for enhanced fatigue resistance. Interpipe and Amsted Rail operate integrated forging lines with 10,000-ton press capacity.
- Heat Treatment:Rim quenching and tempering cycles achieve hardness gradients optimized for tread durability. Specialized furnace operators with AAR certification concentrate in the US Midwest and Ukraine.
- Casting:Centrifugal casting of steel wheels persists for select freight applications with lower thermal loading. Indian foundries supply domestic railways with cast wheels for 22.5-ton axle loads.
- Machining:CNC turning and drilling operations achieve final dimensional tolerances for press-fit axle mounting. Precision machining capacity constrains supplier expansion in emerging markets.
Forging dominates premium-grade procurement. Heat Treatment capability scarcity limits new supplier entry despite demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume through state-backed rail modernization, while the United States and Germany anchor premium-grade demand through heavy-haul freight and high-speed passenger networks respectively.
China
State rail procurement sustains high-volume demand for passenger car and freight wheels through Ministry of Railways programs. GB standards and NMPA regulations enforce domestic alloy specifications that foreign suppliers meet via joint-venture localization. Manufacturing clusters in the Yangtze River Delta region concentrate forging capacity for 25-ton axle load applications.
United States
Class I railroads drive replacement demand through 286,000-pound gross rail load escalation and thermal fatigue failures. The Federal Railroad Administration enforces 49 CFR Part 215 ultrasonic testing requirements that disqualify uncertified suppliers. Foundry and heat-treatment facilities concentrate in the Midwest industrial corridor serving Union Pacific and BNSF procurement.
Germany
Deutsche Bahn and private freight operators generate demand for high-speed passenger and heavy-haul wheels. The EU F-Gas Regulation and emerging CSRD disclosure requirements shape procurement through embedded carbon accounting. Industrial forging capacity clusters in the Ruhr region and Baden-Württemberg supply tilting-train and intercity platforms.
India
Dedicated freight corridors under the Ministry of Railways generate procurement volume for 25-ton axle load wheels in tropical climate conditions. BIS standards and PLI scheme incentives promote domestic manufacturing capacity expansion. Steel forging clusters in Maharashtra and Gujarat supply Wheels India and other domestic fabricators.
Japan
Shinkansen networks sustain premium-grade wheel demand with shorter replacement intervals and stringent metallurgical certification. METI oversight and JIS standards govern high-speed wheel specifications for JR Central and JR East. Manufacturing concentrates in the Nagoya industrial corridor with integrated forging and precision machining capabilities.
Rolling Stock Wheel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steelmakers capturing premium-grade procurement and regional foundries serving commodity replacement cycles. The vendor base concentrates around Eurasian production clusters where vacuum-degassing and heat-treatment capabilities limit new entry. Three archetypes dominate: integrated steel-forging conglomerates with captive raw material supply, precision specialists focused on high-speed passenger applications, and regional foundries serving domestic freight operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as rail operators dual-source to mitigate geographic supply risk.
Among integrated steel-forging conglomerates, Interpipe and Amsted Rail exemplify the archetype of backward-integrated suppliers controlling billet production through final heat treatment. Lucchini RS occupies a position within the precision-specialist tier, representing metallurgical-focused competition for high-speed and intercity passenger platforms. These three companies anchor the competitive structure across distinct procurement channels: heavy-haul freight, state-backed rail modernization, and premium passenger networks.
| Leading Market Players |
|---|
| Interpipe |
| Amsted Rail |
| OMK Steel |
| Masteel Group |
| EVRAZ NTMK |
| ZHIQI RAILWAY EQUIPMENT |
| Nippon Steel Corporation |
| Lucchini RS |
| Bharat Forge Limited |
| Others |
Pricing and Supply Chain Analysis
Specialized furnace operators and metallurgical engineers concentrated in the US Midwest and Eastern Ukraine create labor-cost differentials that widen pricing spreads between premium vacuum-degassed grades and commodity rim-quenched wheels. Chinese domestic producers leverage lower heat-treatment labor costs to undercut European forging margins on standard-grade freight wheels.
Pricing Analysis
Freight car wheels generate volume concentration while high-speed passenger wheels capture disproportionate margin due to metallurgical certification barriers. Pricing stratifies across premium vacuum-degassed Class B compositions, standard rim-quenched grades, and legacy cast iron for industrial switching. Cost compression in standard-grade segments is intensifying because electric arc furnace operators face scrap steel input volatility. Price-sensitive buyers in Indian and Russian domestic freight procurement prioritize lowest-unit-cost rim-quenched wheels, while JR Central and Deutsche Bahn accept premium pricing for shorter replacement intervals and guaranteed availability.
Supply Chain Analysis
Single-source vulnerability sits with integrated forging capacity concentrated in Ukraine, Russia, and the US Midwest. Raw material flows draw from electric arc furnace scrap steel, vacuum-degassed billet supply, and specialized alloying elements for high-speed grades. Tariff exposure threatens cross-border wheel blank movements between Eurasian production clusters and Western European finish-machining facilities. Distribution runs through direct OEM supply contracts for new rolling stock and aftermarket service networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as thermal fatigue standards enforced by the US Federal Railroad Administration and China's GB specifications disqualify uncertified suppliers. Weaker commodity-grade producers without vacuum-degassing capabilities face forced exit as procurement concentrates toward integrated steelmakers.
For Market Incumbents: Hedge geographic supply risk by establishing dual-source forging partnerships in India and Southeast Asia alongside legacy Eurasian capacity. Invest in captive heat-treatment certification to defend against emerging Chinese producers with backward-integrated billet supply. Thermal fatigue testing capability scarcity creates defensive moats for AAR M-107/M-208 certified facilities. For New Entrants and Emerging Players: Capture white-space opportunity in Indian dedicated freight corridor procurement where 25-ton axle load specifications and tropical climate requirements favor new domestic forging investments. Target European light rail and metro composite wheel segments where aluminum and carbon-fiber substitution is accelerating. Pursue joint-venture localization with Chinese state rail procurement to bypass import qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with precision-specialist forging assets given condition-based replacement contract adoption by Shinkansen and TGV networks. Long-term viability over a five-to-ten-year window favors targets with in-house vacuum-degassing and sensor-integrated wheelset capabilities. Monitor AAR certification backlog as an inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Certification Investment | AAR M-107/M-208 approval locks in procurement access from Union Pacific and BNSF. |
| Joint Venture Localization | Chinese GB standard compliance via Yangtze River Delta partnerships bypasses import barriers. |
| Condition-Based Service Contracts | Performance-guaranteed availability agreements with JR Central shift revenue from unit sales. |
| Composite Material R&D Partnership | Carbon-fiber wheel development with German tram networks captures unsprung mass reduction demand. |
| Scrap Steel Supply Integration | Captive electric arc furnace capacity insulates forging margins from commodity price swings. |
Research Methodology
Independent corroboration across Association of American Railroads certification records, Chinese Ministry of Railways procurement disclosures, and European EN 13262 amendment drafts underwrites the qualitative findings. Primary interviews with heat-treatment facility managers, rail operator procurement directors, and metallurgical engineering consultants combined with secondary validation from customs trade data, SEC filings of listed steelmakers, and railway operator maintenance expenditure reports. Bottom-up wheel production capacity estimates and top-down rail fleet replacement demand triangulate market sizing.
Rate-of-change decomposition across the analysis window separates freight axle-load escalation effects from high-speed rail expansion drivers. Segmentation modeling covers product type, material grade, manufacturing process, and regional regulatory cluster dimensions. CAGRs derive from rolling stock fleet growth projections, replacement interval compression under heavier loads, and alloy specification upgrade penetration curves. Forecast inputs include Class I railroad capital expenditure plans and Chinese state rail modernization program procurement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to scrap steel price volatility and geopolitical disruption of Eurasian forging capacity. Forecasts reflect documented assumptions about thermal fatigue standard enforcement timelines and certification approval durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Automotive Tire Chains Market