
 Thin-Section Ball Bearings Market | 2026-2036
Thin-Section Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Thin-Section Ball Bearings Market Insights
AS9100 certification is collapsing the supplier base for aerospace-grade thin-section bearings, forcing tier-two manufacturers to absorb audit costs or exit the segment. SKF Group leverages its European test-lab network to sustain qualification pipelines for satellite momentum-wheel applications. Schaeffler Technologies AG & Co. KG anchors German production of ceramic-hybrid thin-section units for semiconductor wafer-handling robots. Timken Company differentiates through in-house vacuum-melt steel processing, controlling material traceability for defense contractors.
Thin-section ball bearings are precision rolling-element bearings with cross-sections that remain constant regardless of bore diameter, typically manufactured from vacuum-degassed 52100 chrome steel or silicon nitride ceramic and finished to ABEC-5 or tighter tolerances; they transmit radial and axial loads while minimizing weight and envelope dimensions in constrained rotational assemblies. Angular contact configurations dominate aerospace and robotics applications where combined loading and positional accuracy matter, while ceramic material variants capture the fastest expansion as thermal stability and corrosion resistance requirements intensify in medical imaging gantries and semiconductor equipment. Deep groove designs retain the largest volume share across industrial automation, though margin pools concentrate in thrust and self-aligning variants serving specialized medical device and satellite pointing mechanisms.
FAA airworthiness directives and EASA CS-25 certification standards govern bearing integration into commercial and defense aircraft systems, compelling manufacturers to maintain dual-qualification testing protocols that extend development cycles and raise barriers to market entry. China's SAMR enforces GB/T rolling-bearing standards that increasingly reference ISO dimensions while adding domestic efficiency-testing requirements for equipment imports. Japan's METI circular economy guidelines push JIS-certified suppliers toward remanufacturing programs that recover high-value bearing races from decommissioned industrial equipment. Stakeholders must monitor how divergent qualification timelines across FAA, EASA, and CAAC jurisdictions reshape competitive access to next-generation urban air mobility platforms and low-earth-orbit satellite constellations.
Market Dynamics
AS9100 certification requirements are collapsing the supplier base for aerospace-grade thin-section bearings, forcing tier-two manufacturers to absorb six-figure audit costs or exit the segment entirely. This structural consolidation is reshaping competitive access across satellite momentum-wheel and UAV flight-control applications.
Growth Catalysts
- Aerospace OEM procurement:North American and European satellite manufacturers are expanding lightweight bearing assemblies for low-earth-orbit constellations and unmanned aerial vehicle mechanisms.
- China's MIIT dual carbon goals:Stricter GB standards on industrial energy efficiency are pushing domestic manufacturers toward ceramic hybrid bearing designs with lower friction losses.
- Silicon nitride ceramics:Thermal stability and corrosion resistance properties are capturing demand from medical imaging gantries and semiconductor wafer-handling equipment.
Market Restraints
- Vacuum-degassed 52100 chrome steel supply:Material traceability requirements from defense contractors are concentrating qualified steel sources in a handful of specialty melt shops.
- Dual-qualification testing protocols:Divergent FAA and EASA certification timelines are extending development cycles and raising barriers to entry for urban air mobility platforms.
- Magnetic bearing substitution:Contactless suspension systems are displacing mechanical bearings in high-speed precision spindles above 50,000 RPM.
Strategic Opportunities
- Urban air mobility certification:Emerging FAA pathways for eVTOL airworthiness are creating first-mover advantages for bearing suppliers with existing AS9100-D credentials.
- Japan's METI circular economy guidelines:JIS-certified suppliers are building remanufacturing programs to recover high-value bearing races from decommissioned industrial equipment.
- Semiconductor equipment localization:China's domestic wafer-fab buildout is creating demand for ceramic-hybrid units that bypass Western export control classifications.
Industry Challenges
- ABEC-5 tolerance grinding expertise:The precision bearing industry faces a shortage of operators trained in sub-micron spherical geometry control and raceway superfinishing.
- CAAC qualification timeline uncertainty:China's civil aviation regulator has not harmonized with FAA-EASA reciprocity frameworks, forcing redundant testing for satellite subsystem exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin-Section Ball Bearings Market |
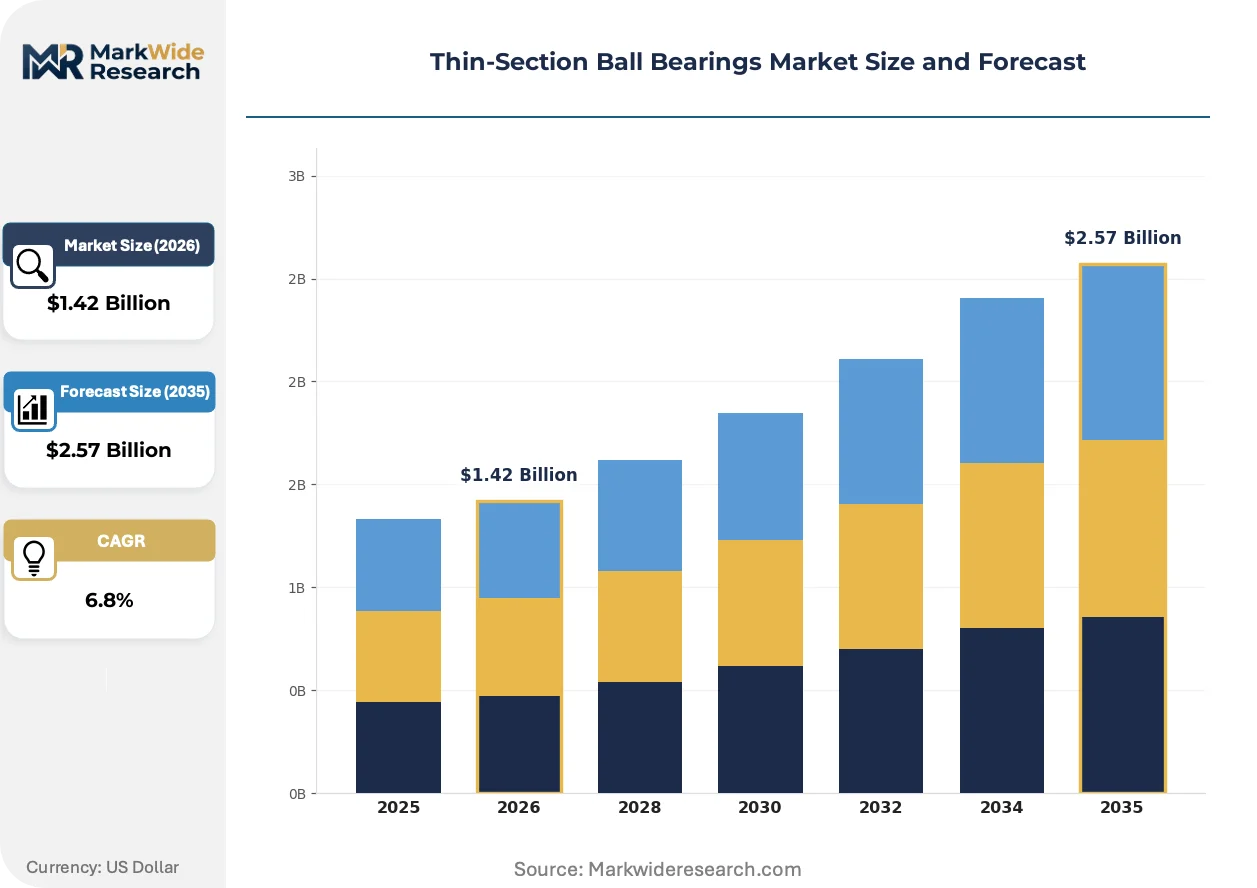
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angular Contact, Deep Groove, Thrust, Self-Aligning Material: Steel, Ceramic, Plastic, Stainless Steel Application: Aerospace, Robotics, Medical Devices, Automotive End User: Manufacturers, Distributors, OEMs, Aftermarket Providers |
| Companies Covered | SKF Group, Schaeffler Technologies AG & Co. KG, NSK Ltd., Timken Company, NTN Corporation, JTEKT Corporation, RBC Bearings Incorporated, Kaydon Corporation, AST Bearings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin-Section Ball Bearings Market Trends and Innovations
Ceramic material variants and digital qualification workflows are fragmenting traditional supply relationships while compressing development cycles for next-generation rotational assemblies.
Silicon nitride ceramic rolling elements are fragmenting the historical dominance of vacuum-melt steel in precision bearing applications. Medical imaging OEMs and semiconductor equipment builders are adopting hybrid ceramic-steel configurations at accelerated procurement cycles. This material shift is fragmenting supplier hierarchies as ceramic powder metallurgy specialists bypass traditional steel-centric bearing houses.
REACH substance restrictions and EU F-Gas Regulation are tightening material disclosure requirements for lubricants and surface treatments used in vacuum-compatible bearings. Manufacturers must now document perfluoropolyether grease chemistries and thin-film coating compositions through extended supply chains. Satellite mechanism suppliers serving European prime contractors are responding by qualifying domestic lubricant formulators to reduce import dependency.
Direct technical engagement between bearing engineers and OEM design teams is displacing traditional distributor-led specification processes. Aerospace and medical device buyers are establishing captive application engineering relationships with qualified manufacturers. This channel compression is most visible in Germany's precision manufacturing corridor, where SKF and Schaeffler anchor specialized production lines for semiconductor handling robots.
Thin-Section Ball Bearings Market Segmentation
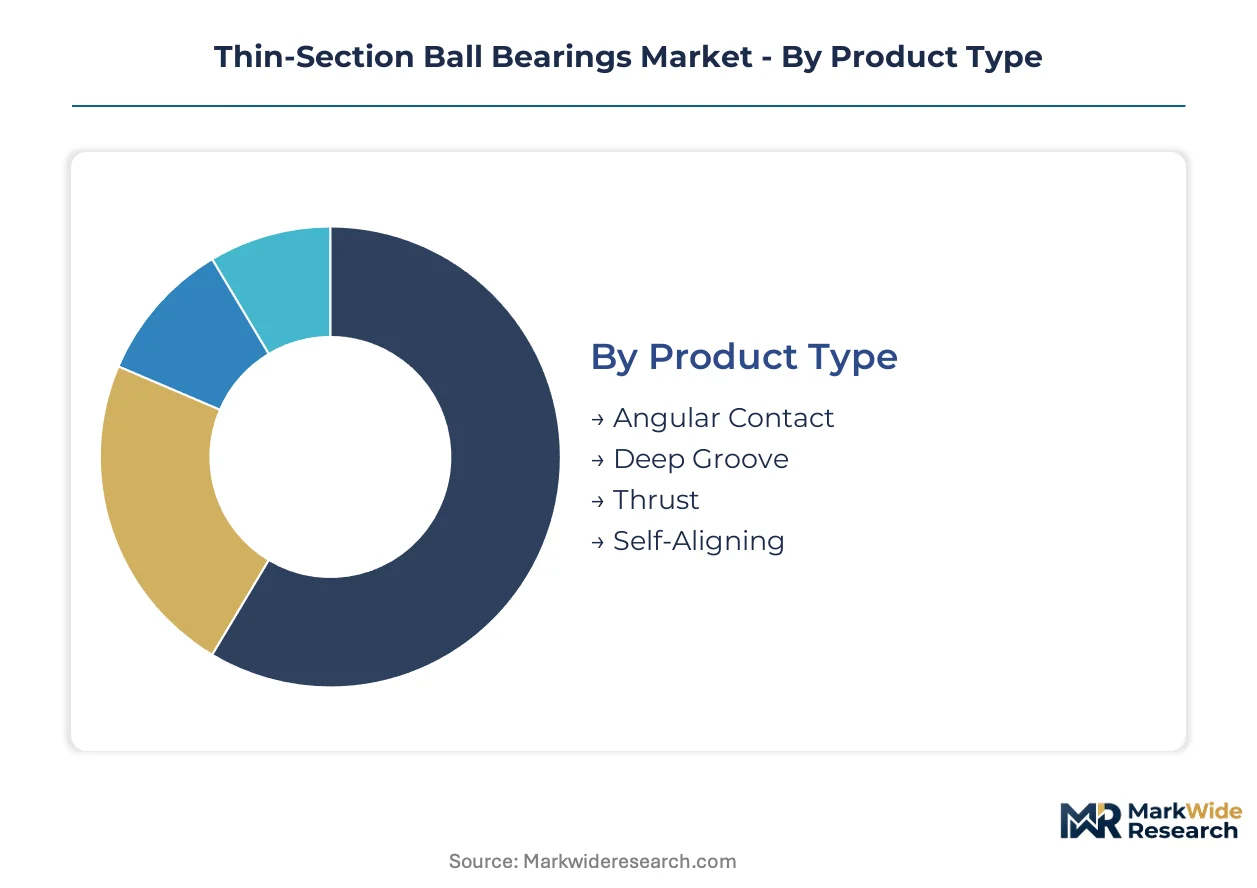
Segmentation in thin-section ball bearings reveals how margin pools concentrate in precision-critical applications rather than commodity industrial uses. Understanding these divisions exposes where certification barriers and material specialization create defendable competitive positions.
Product Type:
Margin pools concentrate in configurations requiring sub-micron tolerance grinding and combined load-handling capability.
- Angular Contact:These bearings handle simultaneous radial and axial loads through raceway geometry designed for precise contact angles. Demand concentrates in Germany's precision manufacturing corridor for semiconductor wafer-handling robots and satellite momentum-wheel assemblies where positional accuracy governs system performance.
- Deep Groove:The most widely deployed configuration accommodates radial loads with occasional axial loading through uninterrupted raceway curvature. Volume concentrates in industrial automation across China's expanding manufacturing base, though stricter GB standards on energy efficiency are pushing procurement toward ceramic hybrid variants.
- Thrust:Designed for pure axial load transmission with minimal radial capacity. Medical imaging gantries and specialized pointing mechanisms represent concentrated demand.
- Self-Aligning:Accommodates angular misalignment through sphered outer raceway geometry. Satellite deployment mechanisms and precision optical systems drive specification.
The dominant share belongs to Deep Groove, while Angular Contact is closing the gap fastest.
Material:
Cost tier stratification separates vacuum-degassed specialty steels from emerging ceramic alternatives.
- Steel:Vacuum-degassed 52100 chrome steel remains the baseline material, specified for ABEC-5 tolerance applications where magnetic permeability and fracture toughness matter. Defense contractors impose traceability requirements that concentrate qualified supply in specialty melt shops.
- Ceramic:Silicon nitride rolling elements deliver thermal stability and corrosion resistance without lubricant dependency. Medical imaging OEMs and semiconductor equipment builders in North America and Europe are accelerating procurement cycles for hybrid ceramic-steel configurations.
- Plastic:Polymer races and cages serve corrosive environments and electrical isolation requirements. Chemical processing and food-grade applications specify these units.
- Stainless Steel:AISI 440C and precipitation-hardened variants resist washdown and sterilization cycles. Medical device sterilization equipment and marine exposure applications dominate.
Ceramic variants command premium positioning, while Stainless Steel applications are expanding most quickly in medical sterilization equipment.
Application:
Customer type determines whether procurement flows through captive engineering relationships or distributor channels.
- Aerospace:AS9100 certification requirements collapse the supplier base for satellite momentum-wheel and UAV flight-control mechanisms. FAA and EASA dual-qualification protocols extend development cycles.
- Robotics:Semiconductor handling robots and precision assembly systems specify angular contact configurations with ceramic elements. Germany's precision corridor anchors specialized production lines.
- Medical Devices:Imaging gantries and surgical equipment demand corrosion-resistant configurations meeting FDA and EMA device regulations.
- Automotive:Electric power steering and transmission systems specify deep groove units at volume scale, though magnetic bearing substitution threatens high-speed spindle applications above 50,000 RPM.
Aerospace retains the highest margin concentration, while Robotics is gaining share fastest through semiconductor localization programs.
End User:
Supply concentration varies sharply between specification-controlled OEM relationships and price-sensitive aftermarket channels.
- Manufacturers:Captive bearing production for internal consumption, rare in this market given capital intensity of precision grinding.
- Distributors:Traditional channel for standard industrial grades, losing share to direct technical engagement models.
- OEMs:Aerospace and medical device builders establish captive application engineering relationships with qualified manufacturers, compressing distributor involvement.
- Aftermarket Providers:Japan's METI circular economy guidelines push remanufacturing programs to recover high-value bearing races from decommissioned equipment.
OEMs control specification authority, while Aftermarket Providers are restructuring fastest around remanufacturing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon goals and stricter GB standards on industrial energy efficiency are reshaping procurement patterns across major manufacturing economies. Satellite constellation deployments and semiconductor localization programs are concentrating demand in specific national industrial corridors.
United States
FAA airworthiness directives and emerging eVTOL certification pathways are driving specification authority toward AS9100-D qualified suppliers. Defense contractors impose vacuum-melt steel traceability requirements that concentrate qualified sources in specialty melt shops. Aerospace OEMs in California and Washington state are expanding procurement of lightweight bearing assemblies for low-earth-orbit satellite mechanisms.
Germany
EASA CS-25 certification standards and REACH substance restrictions govern bearing integration into commercial aircraft systems. The country's precision manufacturing corridor anchors specialized production lines for semiconductor wafer-handling robots and medical imaging equipment. SKF and Schaeffler maintain captive application engineering relationships with OEM design teams in Bavaria and Baden-Württemberg.
China
SAMR enforces GB/T rolling-bearing standards that increasingly reference ISO dimensions while adding domestic efficiency-testing requirements for equipment imports. The MIIT dual carbon goals are pushing domestic manufacturers toward ceramic hybrid bearing designs with lower friction losses. Domestic wafer-fab buildout in the Yangtze River Delta and Pearl River Delta is creating demand for ceramic-hybrid units.
Japan
METI circular economy guidelines push JIS-certified suppliers toward remanufacturing programs that recover high-value bearing races from decommissioned industrial equipment. The Kanto and Kansai regions host precision grinding expertise for ABEC-5 tolerance applications. NSK and JTEKT anchor production networks serving robotics and semiconductor equipment builders.
South Korea
MFDS medical device regulations and national semiconductor self-sufficiency initiatives are accelerating procurement of ceramic hybrid configurations. The Seoul Capital Area and Busan-Ulsan corridor concentrate demand from medical imaging OEMs and precision automation suppliers. Local bearing fabricators are building qualification pipelines for satellite subsystem exports.
Thin-Section Ball Bearings Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive aerospace certification pipelines and specialized precision grinding houses serving medical and semiconductor equipment builders. The supplier base exhibits tiered consolidation around AS9100-D qualified incumbents and emerging ceramic powder metallurgy specialists. Two strategic archetypes dominate: vertically integrated steel-centric bearing houses with vacuum-melt supply control, and ceramic-focused challengers bypassing traditional material hierarchies. Competitive moves concentrate on dual-qualification testing protocols for FAA-EASA harmonization and direct technical engagement models that compress distributor involvement.
Within the diversified conglomerate tier, SKF Group and Schaeffler Technologies AG & Co. KG represent European incumbents with established test-lab networks and captive aerospace qualification pipelines. Timken Company occupies a position among North American suppliers with in-house material processing capabilities. These three anchors exemplify how geographic clustering around regulatory jurisdictions and industrial corridors shapes competitive access to specification-controlled OEM relationships.
| Leading Market Players |
|---|
| SKF Group |
| Schaeffler Technologies AG & Co. KG |
| NSK Ltd. |
| Timken Company |
| NTN Corporation |
| JTEKT Corporation |
| RBC Bearings Incorporated |
| Kaydon Corporation |
| AST Bearings LLC |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at specialty vacuum-melt steel shops in the United States and Germany shapes both supply concentration and price floors for aerospace-grade thin-section bearings, with AS9100-D qualified suppliers capturing margin premiums that tier-two manufacturers cannot match.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with AS9100-D qualified units commanding substantial premiums over industrial-grade alternatives. Three-tier pricing structure separates aerospace-certified from medical-grade from standard industrial bearings, with volume scale and material traceability as secondary differentiation drivers. Cost compression in industrial-grade deep groove configurations is intensifying because Chinese manufacturers are expanding ceramic hybrid production under MIIT efficiency mandates. Aftermarket remanufacturing programs exhibit the highest price sensitivity, while satellite momentum-wheel applications show minimal elasticity due to qualification lock-in.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes from Shanghai and Busan are elevating inbound logistics costs for silicon nitride ceramic powder shipments destined for hybrid bearing fabricators. Geographic supply concentrates in Germany, Japan, and the United States for precision grinding capacity, while China builds domestic ceramic element production. Raw material dependencies rest on vacuum-degassed 52100 chrome steel from specialty melt shops, silicon nitride ceramic powders, and perfluoropolyether lubricants subject to REACH disclosure requirements. Single-source vulnerability characterizes qualified steel supply for defense contractors. Distribution runs through direct technical engagement models for aerospace and medical OEMs, with distributor channels retaining industrial automation volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where AS9100 certification creates regulatory entrenchment that new entrants cannot easily replicate, locking in specification authority for qualified incumbents.
For Market Incumbents: Consolidate qualification pipelines by deepening captive test-lab networks for dual FAA-EASA certification, while acquiring ceramic powder metallurgy specialists to secure hybrid bearing supply chains against emerging Chinese competitors. Magnetic bearing substitution in high-speed spindles above 50,000 RPM represents the most credible technology threat. Vertical integration into silicon nitride ceramic element production offers the strongest margin defense lever. For New Entrants and Emerging Players: Aftermarket remanufacturing capabilities represent the most penetrable service-layer gap, as Japanese JIS-certified suppliers have not scaled remanufacturing programs beyond domestic markets. White-space targets include ceramic hybrid units for China's domestic wafer-fab buildout and urban air mobility bearing qualification for emerging eVTOL platforms. A go-to-market angle anchored in application engineering partnerships with semiconductor equipment builders bypasses distributor channel blockades. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic-focused challengers with powder metallurgy expertise over steel-centric incumbents facing raw material concentration risk. Long-term viability across the analysis window hinges on qualification pipeline depth rather than scale alone. Acquisition targets should display existing AS9100-D credentials or ceramic hybrid production capability. The signal to watch is CAAC-FAA-EASA harmonization progress on satellite subsystem reciprocity, which would compress redundant testing costs and reshape competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Qualification Pipeline Investment | AS9100-D plus EASA CS-25 credentials unlock urban air mobility specification authority. |
| Ceramic Powder Metallurgy Acquisition | Silicon nitride element control secures hybrid bearing margins against steel supply volatility. |
| Remanufacturing Program Buildout | METI-aligned circular economy capabilities capture aftermarket value from decommissioned equipment. |
| Direct Technical Engagement Model | Captive OEM relationships compress distributor involvement in semiconductor and medical segments. |
| Domestic Lubricant Formulator Qualification | REACH-compliant grease sourcing reduces European prime contractor import dependency. |
Research Methodology
A spread of perspectives from aerospace procurement directors, precision grinding plant managers, ceramic powder metallurgy specialists, and semiconductor equipment OEMs converged on the working assumptions underlying this analysis. Primary field engagement with bearing application engineers and regulatory affairs leads at AS9100-certified facilities combined with secondary validation from FAA airworthiness directives, EASA certification databases, GB/T rolling-bearing standards filings, and customs trade data for vacuum-melt steel shipments. Bottom-up unit economics from individual product configurations triangulated against top-down demand aggregation from satellite constellation deployment schedules and semiconductor capital expenditure disclosures.
Segmentation dimensions modeled include bearing configuration type, material composition, application sector, and end-user channel structure across the projection horizon. Analytical framework approaches derived CAGRs from installed base expansion rates, replacement cycle timing, and technology substitution curves for magnetic bearings in high-speed applications. Industry-specific forecast inputs incorporated wafer-fab buildout timelines in the Yangtze River Delta and Pearl River Delta, plus eVTOL airworthiness certification pathway progress under emerging FAA frameworks.
Underlying assumptions cover sustained AS9100-D qualification timelines, continued ceramic hybrid adoption acceleration under China's MIIT dual carbon goals, and stable vacuum-melt steel supply from qualified specialty melt shops, with deviation risk concentrated in CAAC regulatory reciprocity delays and magnetic bearing substitution thresholds in precision spindle applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market