
 Automotive Transmission Valve Spool Market | 2026-2036
Automotive Transmission Valve Spool Market Size, Share, and Industry Trends Forecast 2026-2036
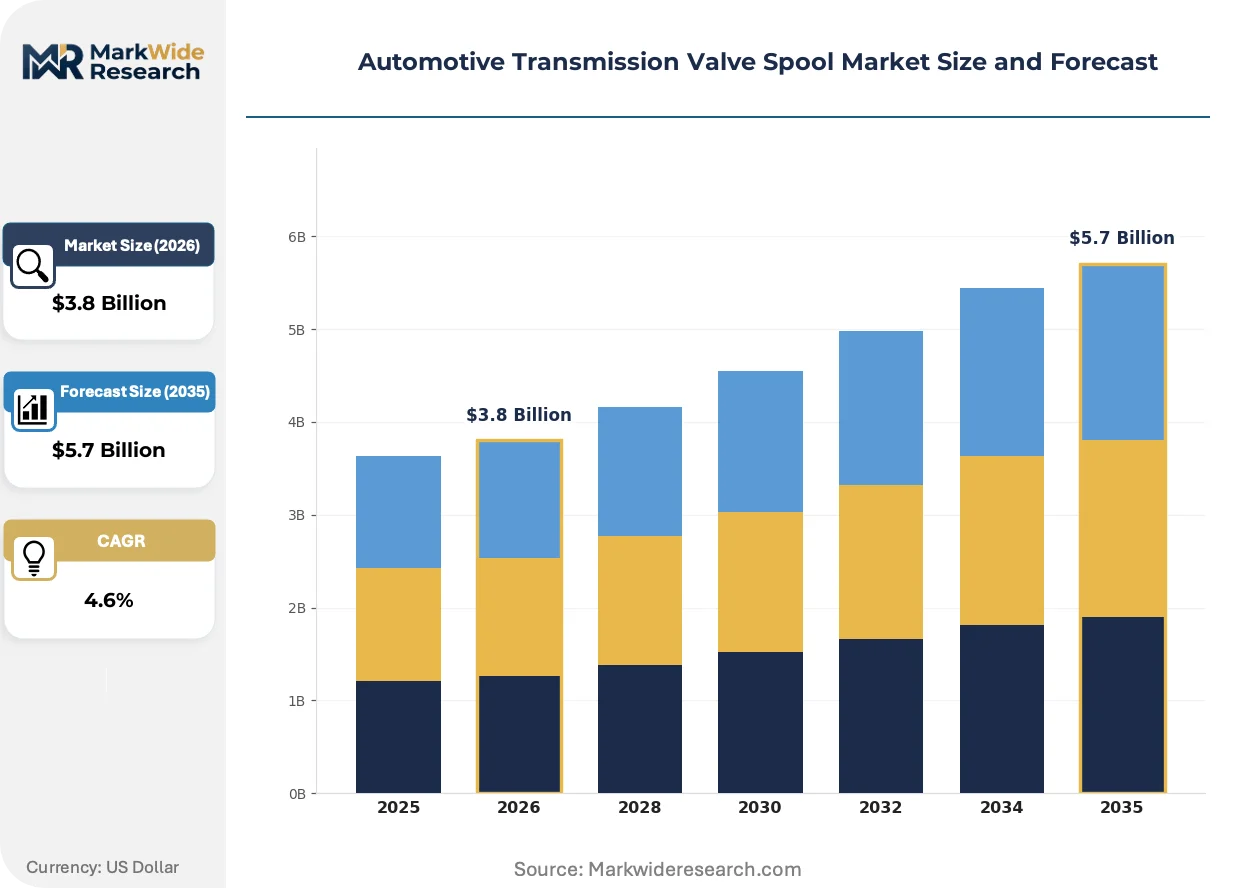
Automotive Transmission Valve Spool Market Outlook
Buyer concentration among passenger vehicle OEMs is restructuring procurement patterns across the supply base. Eaton Corporation plc leverages its integrated powertrain portfolio to sustain long-term contracts with major assemblers. Bosch Rexroth AG anchors European supply through specialized hydraulic component manufacturing. Parker-Hannifin Corporation competes on channel control across aftermarket distribution networks.
An automotive transmission valve spool is a precision-machined cylindrical component, typically hardened steel or aluminum alloy with tolerances below 5 micrometers, that slides within a valve body to direct hydraulic fluid flow and enable gear selection in automatic and dual-clutch transmissions. Hydraulic spools dominate current volume due to their proven durability in high-pressure automatic transmissions, while electric spools represent the fastest-expanding category as electrified powertrains require electronic shift-by-wire architectures. Steel spools command premium positioning in heavy-duty applications, whereas aluminum spools gain ground in lightweight passenger vehicle designs where mass reduction directly impacts fuel efficiency compliance.
EPA tailpipe standards and China's MIIT fuel consumption regulations are forcing spool manufacturers to tighten leakage specifications and reduce actuation energy losses. NHTSA safety protocols govern shift-quality reliability, while ISO 4406 cleanliness codes define permissible particulate contamination in hydraulic circuits. Stakeholders must monitor how electrification transitions reshape spool count per transmission and whether aftermarket demand for legacy hydraulic systems stabilizes or erodes.
Market Dynamics
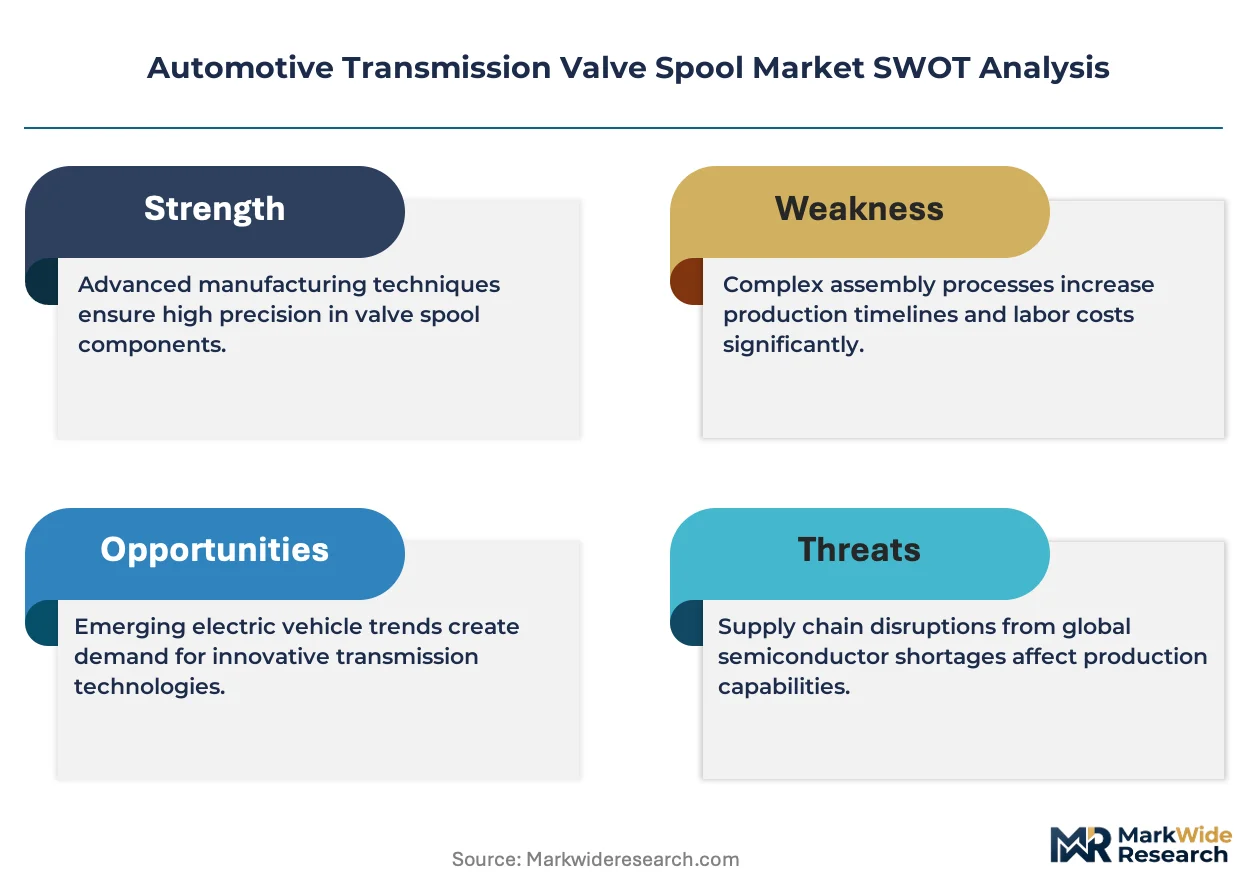
The transition from hydraulic to electronic shift-by-wire architectures is compressing spool counts per transmission while elevating precision requirements for remaining components. OEM procurement consolidation around integrated powertrain suppliers is redistributing bargaining power across the valve spool supply base.
Growth Catalysts
- EPA Fuel Economy Standards:US tailpipe regulations mandate reduced parasitic losses in automatic transmissions, forcing spool manufacturers to tighten leakage tolerances below 3 micrometers and adopt superfinished surface treatments.
- Dual-Clutch Transmission Proliferation:Passenger vehicle OEMs in Germany's manufacturing corridor are expanding DCT adoption for efficiency gains, creating sustained demand for high-cycle aluminum spools with hardened coatings.
- China MIIT Regulations:Corporate average fuel consumption targets are accelerating domestic production of precision valve bodies, pulling localized spool manufacturing capacity online in Jiangsu and Zhejiang provinces.
Market Restraints
- Aluminum Alloy Price Volatility:LME aluminum fluctuations above 15% annually compress margin structures for lightweight spool producers serving mass-market passenger segments.
- Tooling Concentration in Germany:Precision grinding and honing equipment for sub-5-micron tolerances remains captive to a narrow supplier base in Baden-Württemberg, creating single-source vulnerability.
- Electrification Substitution:Battery-electric powertrains eliminate multi-speed transmissions entirely, eroding addressable spool volume in segments where BEV penetration advances fastest.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive components are attracting spool manufacturers to establish local capacity serving Maruti Suzuki and Hyundai Motor India assembly plants.
- Shift-by-Wire Convergence:Integration of electromechanical actuators with legacy hydraulic architectures creates hybrid spool demand requiring both fluid dynamics and electronics expertise.
- Aftermarket Remanufacturing:Extended vehicle lifespans in Brazil and Mexico are expanding demand for refurbished transmission valve bodies with replacement spool kits through independent rebuilders.
Industry Challenges
- Metrology Talent Scarcity:CMM programming and surface roughness analysis for sub-micron validation remains concentrated among aging specialists in Stuttgart and Detroit technical centers.
- ISO 4406 Cleanliness Compliance:Particulate contamination limits below 18/16/13 codes require capital-intensive cleanroom expansion and automated washing systems at component finishing stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Transmission Valve Spool Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Spool, Pneumatic Spool, Electric Spool, Mechanical Spool Material: Aluminum, Steel, Brass, Composite Installation Type: Inline, Modular, Compact, Custom End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Maintenance Shops |
| Companies Covered | HYDAC International GmbH, Eaton Corporation plc, Bosch Rexroth AG, Eagle Industry Co., Ltd., GMB Corporation, Argo-Hytos Inc., Parker-Hannifin Corporation, Christian Bürkert Gmbh & Co. KG, HAWE Hydraulik SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Transmission Valve Spool Market Strategic Shifts
Electrification is bifurcating the valve spool landscape into legacy hydraulic refinement and electromechanical integration. Manufacturers must now engineer for two divergent transmission architectures simultaneously.
Superfinished DLC-coated steel spools are unifying durability requirements across heavy-duty commercial and high-performance passenger applications. Fleet operators and premium OEMs are specifying these surfaces for million-cycle reliability. The technology is unifying previously separate material specifications into a single cross-segment standard.
REACH restrictions on hexavalent chromium plating are forcing conversion to trivalent alternatives and PVD coatings across European supply chains. Surface treatment houses in the Czech Republic and Poland are retooling electrolytic lines to meet ECHA substance restrictions. German transmission assemblers are qualifying new coating vendors ahead of sunset dates for legacy processes.
Consolidated powertrain procurement is compressing supplier tiers as OEMs award valve body contracts to integrated system houses rather than component specialists. Tier 2 spool manufacturers are responding by developing direct relationships with remanufacturing channels. This channel pivot is most visible in North American aftermarket distribution where independent rebuilders seek bypass sourcing.
Automotive Transmission Valve Spool Market Segmentation
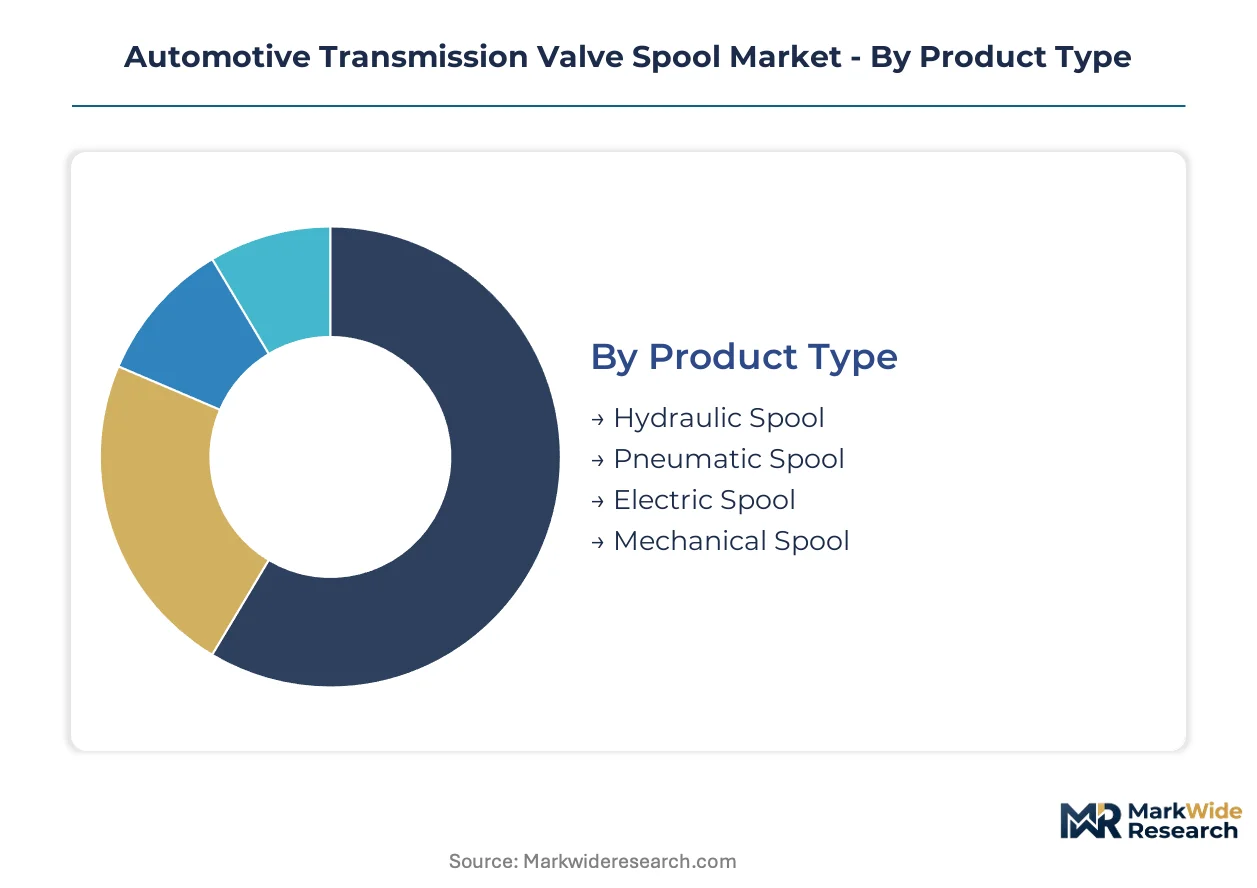
Valve spool segmentation reveals divergent capital requirements across manufacturing technologies and material systems. OEM procurement patterns favor precision-grade categories while aftermarket channels sustain legacy specifications.
Product Type:
Capital intensity peaks with electric spool production lines requiring cleanroom assembly and electronic calibration stations.
- Hydraulic Spool:Machined from hardened steel or aluminum with sub-5-micron tolerances, these components direct high-pressure fluid flow in automatic transmissions. Demand concentrates in Germany's manufacturing corridor where ZF Friedrichshafen and Mercedes-Benz assembly plants source multi-million-unit annual volumes. EPA fuel economy standards are forcing tighter leakage specifications below 3 micrometers.
- Electric Spool:Integrating electromechanical actuators with position sensors for shift-by-wire architectures. China's MIIT regulations are accelerating domestic production in Jiangsu province as BYD and Geely expand electrified powertrain capacity.
- Pneumatic Spool:Compressed air actuation systems for auxiliary transmission functions in commercial vehicles.
- Mechanical Spool:Legacy cable-operated designs for cost-sensitive manual transmission variants in Brazil and India.
Hydraulic spools absorb the bulk of installed capacity; electric spools are expanding most quickly.
Material:
Raw material sourcing strategies diverge between lightweight aluminum for passenger efficiency and hardened steel for commercial durability.
- Steel:Through-hardened alloy grades with DLC coatings deliver million-cycle reliability in heavy-duty commercial applications. Fleet operators in North America specify these surfaces for Class 8 truck transmissions subject to NHTSA safety protocols.
- Aluminum:Anodized or coated lightweight alloys reduce rotating mass in dual-clutch transmissions. German OEMs prioritize these for EU Green Deal compliance targets.
- Brass:Corrosion-resistant specifications for marine and extreme-climate aftermarket replacements.
- Composite:Polymer-matrix experimental grades for prototype electrified powertrains.
Steel commands premium positioning in commercial segments; aluminum is gaining share fastest in passenger OEM contracts.
Installation Type:
Assembly line integration requirements determine whether spools ship as discrete components or pre-validated subsystems.
- Inline:Direct valve body insertion with minimal secondary processing. High-volume OEM contracts in Stuttgart and Detroit favor this format for throughput efficiency.
- Modular:Pre-assembled cartridge units enabling field service replacement. Aftermarket providers in Mexico and Brazil stock these for independent rebuilders.
- Compact:Space-constrained packaging for hybrid transmission designs.
- Custom:Application-specific geometries for motorsport and specialty vehicle producers.
Inline configurations dominate OEM assembly volumes; modular formats are climbing fastest in aftermarket channels.
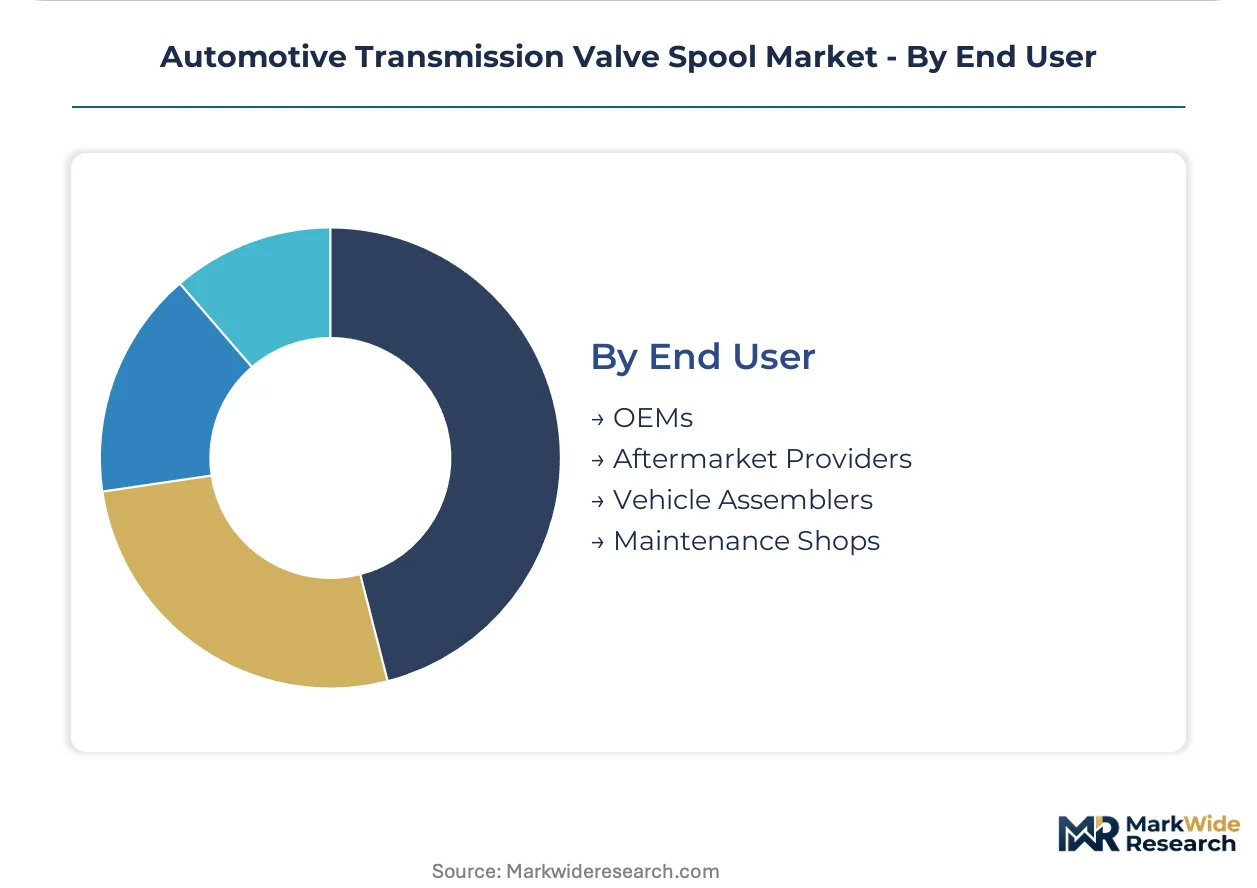
End User:
Procurement authority concentrates with integrated powertrain suppliers while fragmented service channels sustain replacement demand.
- OEMs:Long-term supply agreements with transmission system houses like Eaton and Bosch Rexroth specify statistical process control and ISO 4406 cleanliness compliance. These contracts require dedicated production cells and metrology laboratories.
- Aftermarket Providers:Independent distributors and remanufacturing specialists source replacement spool kits for legacy hydraulic systems. Extended vehicle lifespans in Brazil and Mexico are expanding this channel.
- Vehicle Assemblers:Direct procurement for captive transmission production.
- Maintenance Shops:Small-lot orders for repair and refurbishment services.
OEMs absorb the bulk of precision manufacturing capacity; aftermarket providers are expanding most quickly in emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor concentrates the highest demand density for precision valve spools, with passenger vehicle OEMs and integrated powertrain suppliers anchoring procurement volumes across multiple continents.
United States
EPA tailpipe regulations and NHTSA safety protocols are tightening leakage specifications below 3 micrometers for automatic transmission components. The Detroit technical corridor hosts metrology specialists validating sub-micron surface roughness for OEM supply contracts. Fleet operators in Class 8 trucking specify DLC-coated steel spools for million-cycle durability.
Germany
ZF Friedrichshafen and Mercedes-Benz assembly plants source multi-million-unit annual volumes of high-cycle aluminum spools for dual-clutch transmissions. REACH restrictions on hexavalent chromium plating are forcing surface treatment houses in Baden-Württemberg to retool electrolytic lines. Stuttgart's precision grinding equipment suppliers remain the narrow base for sub-5-micron tolerance tooling.
China
MIIT fuel consumption regulations and dual carbon goals are accelerating domestic production of precision valve bodies. BYD and Geely are expanding electrified powertrain capacity in Jiangsu and Zhejiang provinces. Localized spool manufacturing capacity is pulling online to serve these assembly plants.
India
Maruti Suzuki and Hyundai Motor India are expanding assembly plant capacity under the PLI scheme for advanced automotive components. Production-linked incentives are attracting spool manufacturers to establish local supply relationships. Extended vehicle lifespans are simultaneously expanding aftermarket demand for replacement spool kits.
Brazil
Extended vehicle lifespans are expanding demand for refurbished transmission valve bodies through independent rebuilders. Legacy hydraulic systems sustain replacement spool kit volumes in the maintenance channel. Cost-sensitive manual transmission variants continue specifying mechanical spool designs for mass-market segments.
Automotive Transmission Valve Spool Market Competitive Environment
German producers anchor one tier; American and Japanese specialists hold differentiated positions in hydraulic and electromechanical integration. The supply base exhibits moderate concentration around integrated powertrain system houses, with component specialists occupying niche positions in aftermarket channels and precision manufacturing. Three archetypes dominate: diversified industrial conglomerates with captive transmission divisions, pure-play hydraulic component manufacturers, and precision machining houses serving remanufacturing networks. Competitive moves center on backward integration into valve body assembly and geographic expansion into PLI-subsidized manufacturing zones.
Within the diversified conglomerate tier, Eaton Corporation plc and Bosch Rexroth AG exemplify integrated powertrain portfolio strategies that sustain long-term OEM contracts. Parker-Hannifin Corporation occupies a position in aftermarket channel control across distribution networks. These three anchors represent distinct geographic and structural approaches to the valve spool supply base.
| Leading Market Players |
|---|
| HYDAC International GmbH |
| Eaton Corporation plc |
| Bosch Rexroth AG |
| Eagle Industry Co., Ltd. |
| GMB Corporation |
| Argo-Hytos Inc. |
| Parker-Hannifin Corporation |
| Christian Bürkert Gmbh & Co. KG |
| HAWE Hydraulik SE |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap precision machining houses in Baden-Württemberg and Stuttgart anchor supply discipline through generational capital stewardship, insulating pricing power from quarterly earnings pressure while sustaining sub-5-micron tolerance investments that commodity competitors cannot match.
Pricing Analysis
High-volume hydraulic spool contracts absorb manufacturing capacity at compressed margins, while low-volume electric spool programs capture premium positioning through cleanroom assembly requirements. Three-tier pricing structure across premium DLC-coated steel, standard anodized aluminum, and economy uncoated grades separates fleet-specified commercial durability from passenger vehicle lightweighting mandates. Cost compression in aluminum alloy inputs is intensifying because LME price volatility above 15% annually erodes producer margins without corresponding OEM relief. Aftermarket rebuilders in Brazil and Mexico exhibit highest price sensitivity, whereas German OEM transmission system houses prioritize performance certification over unit cost.
Supply Chain Analysis
Workforce availability for CMM programming and surface roughness validation concentrates among aging specialists in Stuttgart and Detroit technical centers, constraining capacity expansion regardless of capital deployment. Precision grinding and honing equipment for sub-5-micron tolerances remains captive to German tooling suppliers, while raw material sourcing draws from Swedish specialty steel mills and Chinese aluminum smelters. Single-source vulnerability in Baden-Württemberg precision equipment creates structural supply risk. Distribution runs through integrated powertrain system houses rather than direct component procurement, compressing supplier tiers and elevating channel control value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive transmission valve spool market sits in a technology-transition phase, with electromechanical shift-by-wire architectures displacing legacy hydraulic control systems across passenger vehicle platforms.
For Market Incumbents: To counter electrification-driven spool count compression, backward integration into valve body assembly secures tier positioning against consolidated powertrain procurement. Captive metrology laboratory investment in Stuttgart or Detroit technical centers locks in ISO 4406 cleanliness compliance capabilities that OEM contracts mandate. DLC coating process control separates million-cycle durability specifications from commodity competitors. For New Entrants and Emerging Players: India's PLI scheme for advanced automotive components opens a window for greenfield capacity serving Maruti Suzuki and Hyundai Motor India assembly relationships. Aftermarket remanufacturing channels in Brazil and Mexico present the most penetrable white-space, with independent rebuilders seeking bypass sourcing from consolidated system houses. Direct distributor relationships with regional transmission specialists enable channel entry without OEM qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining houses with captive cleanroom capacity in Jiangsu province, where domestic OEM electrification investments outpace local supplier maturation. Five-to-ten year viability hinges on hybrid spool capability spanning hydraulic fluid dynamics and electromechanical integration expertise. The signal to watch is BYD and Geely platform standardization announcements, which would trigger dedicated production cell demand pull.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Assembly Investment | ISO 4406 cleanliness compliance enables electric spool qualification with BYD and Geely. |
| DLC Coating Process Scale-Up | Million-cycle durability specifications unify heavy-duty commercial and premium passenger contracts. |
| India PLI Manufacturing Footprint | Localized capacity captures Maruti Suzuki and Hyundai Motor India procurement localization mandates. |
| Aftermarket Channel Direct Relationships | Bypass sourcing from consolidated system houses expands margin capture in Brazil and Mexico rebuild networks. |
| Metrology Talent Acquisition | CMM programming specialists in Stuttgart and Detroit anchor sub-micron validation capabilities. |
Study Parameters
Multi-period observation of EPA fuel economy standard implementation, MIIT fuel consumption regulation enforcement, and REACH coating restriction timelines anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and precision machining house technical directors. Secondary validation drew from NHTSA safety protocol filings, ECHA substance restriction databases, vehicle production registration data, and SEC disclosures from integrated powertrain suppliers. Bottom-up spool demand modeling by transmission architecture and top-down market sizing by regional OEM procurement value were triangulated for consistency.
Segment-weighting across hydraulic, electric, pneumatic, and mechanical spool categories, further stratified by steel, aluminum, brass, and composite material systems, informed the analytical framework across the analysis window. CAGRs were derived from installed transmission volume forecasts, spool count per transmission by architecture type, and content value per vehicle assumptions. Electrification penetration curves and dual-clutch transmission adoption rates in Germany's manufacturing corridor served as primary demand drivers.
The model assumes a particular technology adoption path for shift-by-wire architectures; alternative pathways for battery-electric powertrain standardization would alter the outlook through accelerated spool count erosion. Forecasts reflect assumptions regarding EPA and MIIT regulatory stringency enforcement, REACH coating restriction phase-out adherence, and aluminum alloy price volatility stabilization. Material deviation in electrification penetration rates, OEM procurement consolidation pace, or precision equipment supplier capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
X-Arm Type Window Regulator Market