
 Automotive Pneumatic Actuators Market | 2026-2036
Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pneumatic Actuators Market Outlook
A capital-intensity divergence between integrated pneumatic specialists and component assemblers is unwinding traditional competitive boundaries in the automotive supply base. SMC Corporation leverages captive manufacturing of precision valves and cylinders to control cost positions across Asian production networks. Continental AG anchors European demand through embedded electropneumatic modules designed for brake-by-wire architectures. Parker Hannifin Corporation extends its fluid power portfolio into smart actuation systems that integrate proportional control electronics with conventional pneumatic mechanics.
Automotive pneumatic actuators are compressed-air-driven mechanical devices that convert pneumatic energy into linear or rotary motion, typically operating at pressures between 4 and 10 bar to control engine intake valves, brake calipers, and suspension dampers in vehicle systems. Double acting actuators dominate volume production for brake and steering applications where bidirectional force control ensures rapid response under variable load conditions, while electropneumatic technology commands expanding share as manufacturers embed position sensors and CAN bus interfaces for real-time feedback. Spring return configurations retain cost-sensitive positions in engine control and secondary safety systems where fail-safe default positioning remains mandatory.
The EPA and NHTSA jointly shape United States demand through overlapping emissions and safety mandates that specify actuator durability testing protocols and material compatibility with synthetic lubricants. ISO 26262 functional safety standards and EU CE marking requirements under the Machinery Directive constrain market access for non-compliant suppliers serving European OEMs. Stakeholders must monitor convergence between pneumatic and electropneumatic control architectures as smart actuation protocols redefine component qualification criteria and supplier certification timelines.
Market Dynamics
The automotive pneumatic actuators market is restructuring around electropneumatic hybrid architectures as brake-by-wire mandates and heavy-duty emissions compliance force suppliers to embed sensing and control electronics into formerly mechanical air-power systems. This convergence is dissolving traditional boundaries between pneumatic mechanics and electronic control modules.
Growth Catalysts
- EPA-NHTSA heavy-duty mandates:Joint emissions and brake performance standards in the United States are accelerating fleet replacement cycles and specifying durability testing protocols that favor electropneumatic actuator suppliers with embedded qualification data.
- Commercial vehicle brake reliability:Fleet operators under heavy load conditions are specifying electropneumatic brake actuators as standard procurement items, concentrating demand around suppliers with proven stopping performance under variable pressure.
- German manufacturing corridor concentration:Tier 1 suppliers coordinating just-in-time actuator deliveries to powertrain integration facilities are compressing lead times and locking in volume commitments from pneumatic specialists.
Market Restraints
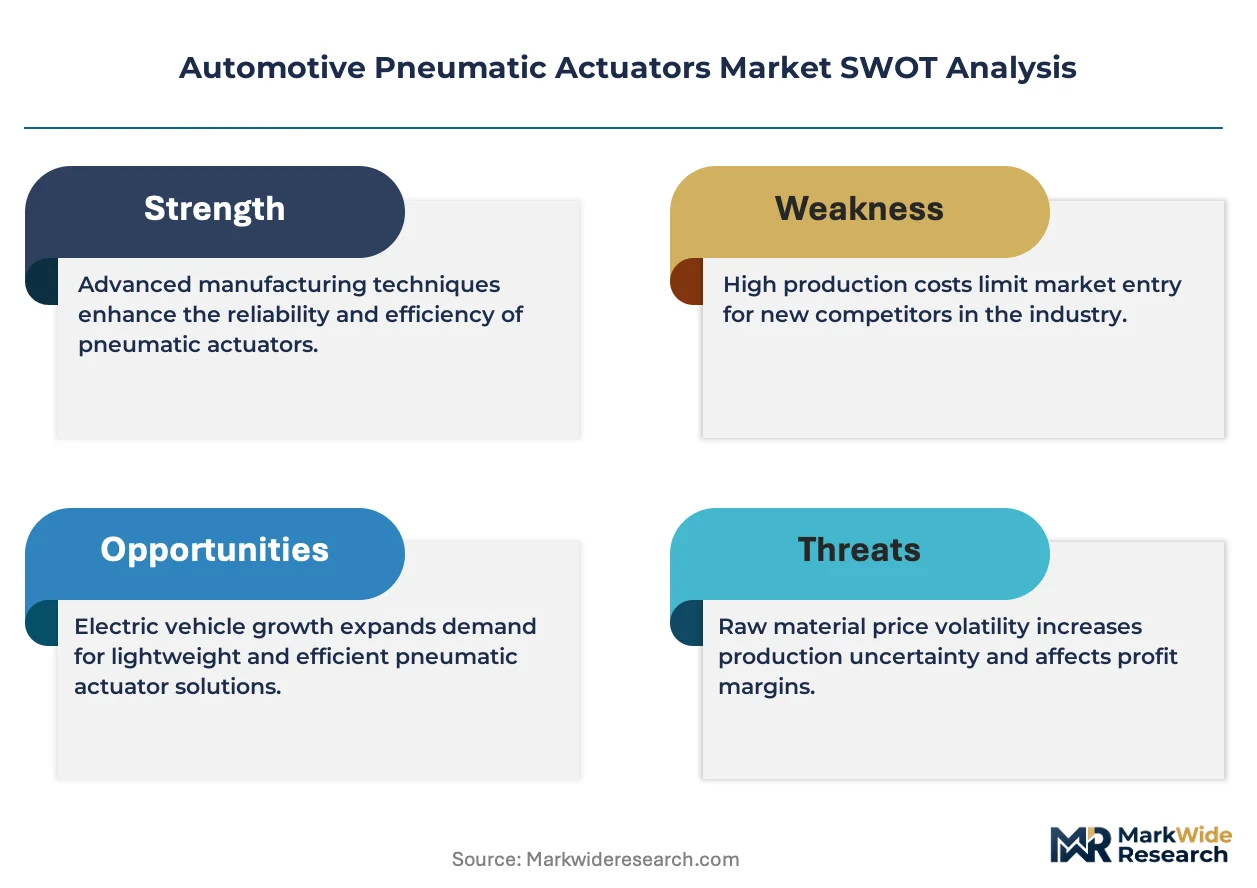
- Aluminum and specialty steel input costs:Cylinder housing and piston material price volatility is compressing margin positions for component assemblers lacking captive metallurgical supply.
- Precision valve supply concentration:Asian manufacturing networks dominate high-tolerance pneumatic valve production, creating single-source exposure for European and North American actuator integrators.
- Electromechanical substitution:All-electric linear actuators are displacing pneumatic solutions in light vehicle engine valve control where 48V electrical architectures eliminate compressed air infrastructure.
Strategic Opportunities
- India commercial vehicle expansion:Domestic truck and bus production growth under BIS automotive standards is creating first-mover advantage for electropneumatic brake actuator suppliers establishing local assembly.
- Smart actuation protocol convergence:Integration of CAN bus interfaces with proportional control electronics is opening aftermarket retrofit demand from fleet operators seeking telematics-compatible brake systems.
- EU Green Deal manufacturing incentives:CE marking acceleration funds and Machinery Directive compliance support are lowering certification barriers for pneumatic suppliers expanding European embedded module production.
Industry Challenges
- ISO 26262 functional safety certification:The 18-24 month qualification timeline for automotive safety integrity level compliance is delaying product launches and freezing engineering resources on documentation.
- Electropneumatic integration complexity:Legacy pneumatic mechanics require redesign to accommodate position sensors and control electronics without compromising 4-10 bar operating pressure envelopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pneumatic Actuators Market |
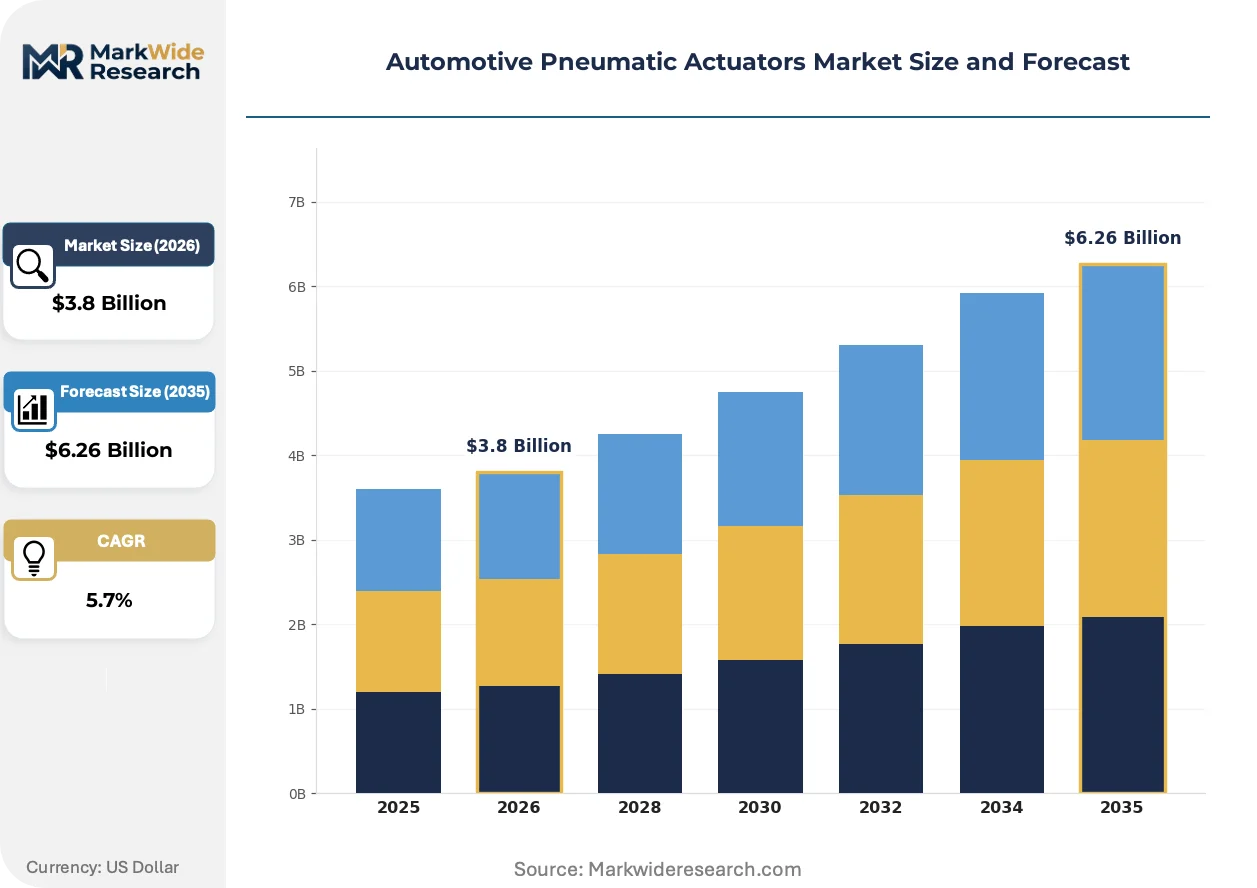
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Spring Return, Vacuum Actuators Application: Brake Systems, Steering Systems, Engine Control, Suspension Systems End User: OEMs, Aftermarket, Vehicle Manufacturers, System Integrators Technology: Pneumatic Control, Electropneumatic, Smart Actuation, Proportional Control |
| Companies Covered | SMC Corporation, Continental AG, Robert Bosch GmbH, Parker Hannifin Corporation, Nidec Corporation, Denso Corporation, Festo SE & Co. KG, Bosch Rexroth AG, Emerson Electric Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pneumatic Actuators Market Strategic Shifts
Electropneumatic architectures are fragmenting the traditional pneumatic actuator value chain as position sensing, proportional control, and bus communication become standard rather than premium features. Suppliers must now qualify as electronics integrators, not merely mechanical fabricators.
Proportional solenoid valve technology is decomposing the conventional binary on-off pneumatic control paradigm. Brake system architects at commercial vehicle OEMs are specifying continuous pressure modulation for anti-lock and stability control integration. This capability compression is collapsing the distinction between standalone pneumatic actuators and electropneumatic control modules, forcing mechanical specialists to source or develop embedded electronics competency.
REACH substance restrictions and RoHS material compliance in Europe are constraining seal elastomer and lubricant formulation choices. Suppliers serving German and French OEMs must validate alternative synthetic compounds that maintain 4-10 bar pressure integrity across temperature cycling. The electropneumatic segment faces the tightest substitution deadlines as embedded electronics multiply material contact points subject to hazardous substance audits.
Just-in-time delivery contracts are compressing inventory buffers throughout the actuator supply chain. Tier 1 powertrain integrators in Germany and the United States are transferring demand volatility directly to pneumatic component suppliers through vendor-managed inventory arrangements. This working capital intensity is most acute for double-acting brake actuator specialists serving commercial vehicle platforms with irregular production scheduling.
Automotive Pneumatic Actuators Market Segmentation
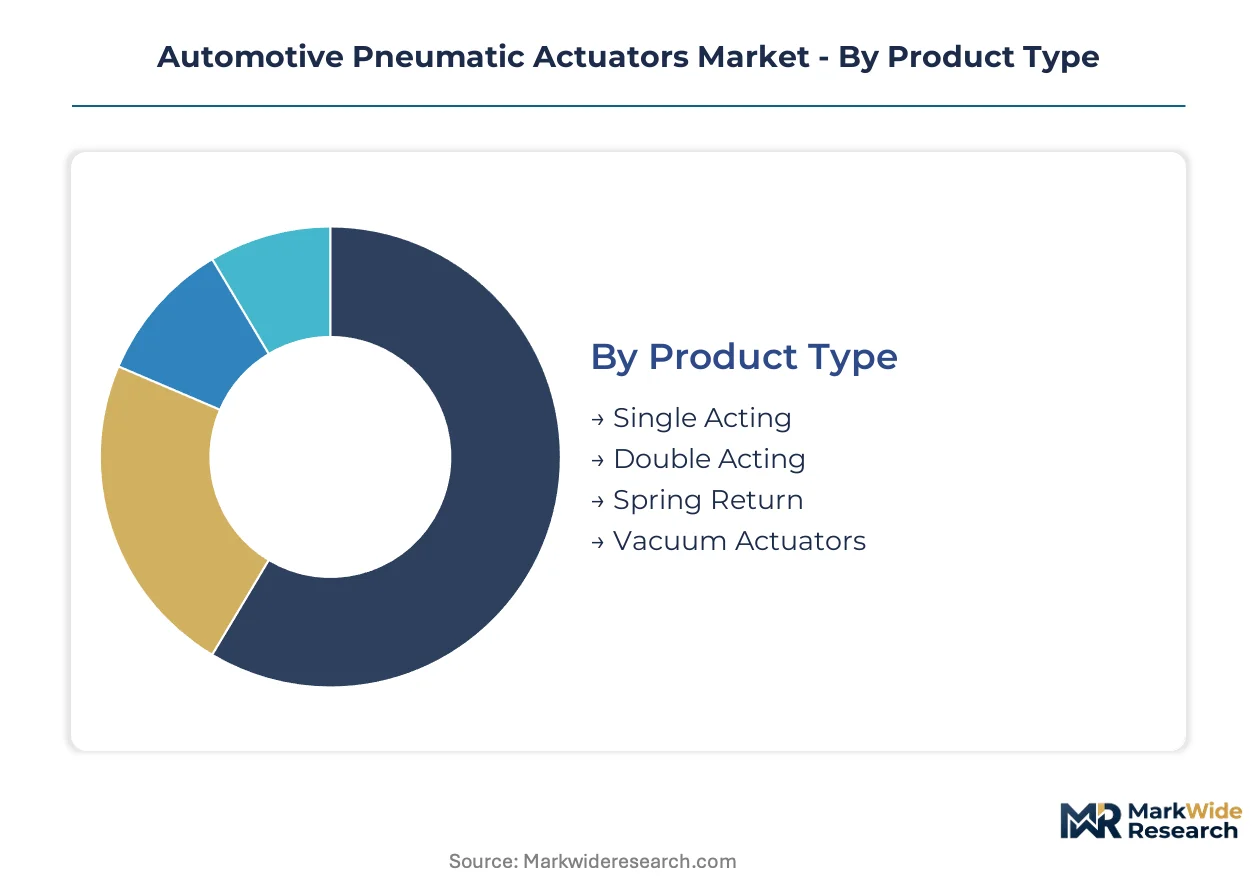
Segmentation in automotive pneumatic actuators reveals how technology migration and regulatory pressure are redistributing margin pools across mechanical, electropneumatic, and smart actuation architectures. Understanding these divides exposes where suppliers must requalify as electronics integrators versus defend mechanical fabrication positions.
Product Type:
Margin concentration sits with configurations that support bidirectional force control and fail-safe redundancy demanded by brake-by-wire mandates and heavy-duty fleet specifications.
- Double Acting:Compressed air drives piston motion in both directions through dual pressure ports, enabling precise force modulation for commercial vehicle brake calipers and steering rack positioning. Fleet operators in Germany's manufacturing corridor specify these actuators as standard procurement items for heavy-load stopping reliability under EPA-NHTSA durability testing protocols.
- Spring Return:A mechanical spring provides default position restoration when pneumatic pressure drops, ensuring fail-safe engine valve closure and secondary safety system activation. OEMs retain this configuration for cost-sensitive engine control modules where ISO 26262 safety integrity mandates default positioning without electronic backup.
- Single Acting:Unidirectional pneumatic force with gravity or external load return, common in simple clamping and hatch mechanisms with minimal cycle requirements.
- Vacuum Actuators:Negative pressure drives diaphragm displacement for low-force applications including HVAC damper control and emission recirculation valves.
The dominant share belongs to Double Acting configurations, while Spring Return retains critical positioning in safety-mandated engine applications.
Application:
Volume flows track where electropneumatic hybrid architectures are replacing purely mechanical systems under joint emissions and safety mandates.
- Brake Systems:Electropneumatic actuators convert air pressure into caliper force with embedded position sensing for anti-lock and stability control integration. Commercial vehicle OEM procurement concentrates demand around suppliers with proven stopping performance under variable 4-10 bar pressure envelopes and NHTSA-mandated durability testing.
- Engine Control:Pneumatic and electropneumatic actuators manage intake valve timing, turbocharger wastegates, and exhaust gas recirculation. Electromechanical substitution is accelerating here as 48V electrical architectures eliminate compressed air infrastructure in light vehicle platforms.
- Steering Systems:Double-acting actuators provide rack-and-pinion assistance in heavy commercial vehicles where hydraulic alternatives face thermal management constraints.
- Suspension Systems:Air spring leveling and adaptive damping control use pneumatic actuation for ride height adjustment under variable load conditions.
Brake Systems command the largest revenue pool, though Engine Control faces the steepest substitution pressure from all-electric alternatives.
End User:
Customer concentration reflects divergent qualification requirements between production-line integration and aftermarket retrofit demand.
- OEMs:Original equipment manufacturers specify actuators during vehicle platform development with 18-24 month ISO 26262 functional safety certification timelines. German Tier 1 suppliers coordinate just-in-time deliveries to powertrain integration facilities, locking volume commitments through vendor-managed inventory arrangements.
- Vehicle Manufacturers:Final assembly operations procure complete actuator modules for chassis and powertrain integration, concentrating demand around embedded electropneumatic suppliers with CAN bus interface capabilities.
- Aftermarket:Fleet operators and independent repair channels source replacement units and telematics-compatible retrofit systems, creating demand for smart actuation protocol convergence.
- System Integrators:Specialized suppliers combine pneumatic components with custom control electronics for niche commercial and off-highway applications.
OEMs retain the dominant procurement position, while Aftermarket channels are expanding most quickly through smart actuation retrofit demand.
Technology:
Value capture is shifting toward architectures that embed sensing, control, and communication capabilities formerly external to pneumatic mechanics.
- Electropneumatic:Integration of proportional solenoid valves, position sensors, and CAN bus interfaces enables real-time pressure modulation and feedback. Continental AG anchors European demand through embedded modules designed for brake-by-wire architectures, while EPA-NHTSA mandates accelerate fleet replacement cycles.
- Smart Actuation:Full protocol convergence combining pneumatic mechanics with programmable control electronics and telematics connectivity. Parker Hannifin Corporation extends fluid power portfolios into these systems for aftermarket fleet operators seeking predictive maintenance capabilities.
- Pneumatic Control:Conventional binary on-off valve systems retain cost positions in secondary applications without real-time feedback requirements.
- Proportional Control:Continuous pressure modulation technology decomposes traditional pneumatic paradigms, collapsing distinctions between standalone actuators and control modules.
Electropneumatic technology holds the established revenue base, while Smart Actuation is gaining share fastest through telematics integration and predictive maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's manufacturing corridor while cost-sensitive procurement dominates India's commercial vehicle expansion. This asymmetry is reshaping supplier qualification requirements across both mature and emerging production networks.
United States
Heavy-duty fleet operators under EPA-NHTSA joint mandates are specifying electropneumatic brake actuators with embedded durability testing data. The overlapping emissions and brake performance standards accelerate replacement cycles for commercial vehicles operating under variable load conditions. Detroit-area powertrain integration facilities coordinate just-in-time actuator deliveries through vendor-managed inventory arrangements with Tier 1 suppliers.
Germany
Baden-Württemberg and Bavaria anchor European demand through embedded electropneumatic modules designed for brake-by-wire architectures. EU CE marking requirements under the Machinery Directive and ISO 26262 functional safety standards constrain market access for non-compliant suppliers. Stuttgart's automotive manufacturing corridor compresses lead times through synchronized just-in-time deliveries to powertrain integration facilities.
China
Domestic truck and bus production growth under MIIT automotive standards is creating demand concentration for pneumatic brake systems. The country's dual carbon goals and GB standards for heavy-duty vehicle emissions are tightening specification requirements for pneumatic components. Yangtze River Delta manufacturing clusters coordinate captive production of precision valves and cylinders across Asian supply networks.
India
Commercial vehicle production expansion under BIS automotive standards is creating first-mover advantage for electropneumatic brake actuator suppliers. Domestic fleet operators prioritize stopping reliability under heavy load conditions on deteriorating road infrastructure. Maharashtra and Gujarat manufacturing corridors are attracting local assembly investments from pneumatic specialists seeking to bypass import duty structures.
Japan
METI industrial standards and JIS certification requirements maintain high barriers for non-domestic pneumatic component suppliers. Automotive OEMs in the Nagoya and Tokyo manufacturing belts specify double-acting actuators for steering rack assistance in heavy commercial vehicles. Precision valve supply relationships with Asian manufacturing networks create single-source exposure for actuator integrators serving Japanese vehicle manufacturers.
Automotive Pneumatic Actuators Market Competitive Environment
Concentration sits with diversified industrial conglomerates that have backward integrated into precision valve and cylinder manufacturing. The vendor base spans three distinct tiers: integrated pneumatic specialists with captive metallurgical supply, component assemblers dependent on external precision valve sourcing, and electronics integrators qualifying as electropneumatic module suppliers. Strategic moves center on M&A activity targeting embedded electronics competency and capacity expansion into German and Indian manufacturing corridors.
Within the integrated industrial tier, SMC Corporation and Parker Hannifin Corporation exemplify archetypes that have upstream control over precision valve production. Continental AG occupies a position representing European electropneumatic module specialization for brake-by-wire architectures. Among diversified automotive suppliers, Robert Bosch GmbH and Denso Corporation sit within the tier of component assemblers navigating electromechanical substitution pressure in engine control applications. These named entities serve as anchors for understanding how competitive positioning fragments across mechanical fabrication, electronics integration, and smart actuation protocol convergence.
| Leading Market Players |
|---|
| SMC Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Parker Hannifin Corporation |
| Nidec Corporation |
| Denso Corporation |
| Festo SE & Co. KG |
| Bosch Rexroth AG |
| Emerson Electric Co |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with Tier 1 powertrain integrators lock in both precision valve supply access and price visibility for electropneumatic brake actuator specialists serving German and United States commercial vehicle platforms. These arrangements transfer demand volatility directly to component suppliers while insulating OEM procurement from aluminum and specialty steel input cost swings.
Pricing Analysis
The customization-premium spread between configured-to-order electropneumatic modules and standard double-acting pneumatic actuators runs wide across the automotive supply base. Project-based pricing dominates OEM procurement with ISO 26262 certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from electromechanical substitution in light vehicle engine control where 48V architectures eliminate compressed air infrastructure. Aftermarket fleet operators exhibit highest price sensitivity while German Tier 1 integrators prioritize qualification reliability over unit cost.
Supply Chain Analysis
Inventory buffers have compressed to near-zero levels under vendor-managed inventory arrangements between German manufacturing corridor integrators and pneumatic specialists. Supply concentrates in China, Germany, and Japan for precision valve and cylinder production. Raw material dependencies center on aluminum cylinder housings, specialty steel pistons, and synthetic seal elastomers. Single-source vulnerability persists for high-tolerance pneumatic valve sourcing from Asian manufacturing networks. Distribution runs through Tier 1 powertrain integration facilities with just-in-time delivery protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive pneumatic actuators market sits in a cyclical recovery phase as EPA-NHTSA heavy-duty fleet replacement cycles accelerate commercial vehicle procurement. This cyclical upswing favors suppliers with embedded electropneumatic qualification data and brake-by-wire architecture readiness.
For Market Incumbents: Shield margin positions through backward integration into precision valve manufacturing and captive metallurgical supply for cylinder housings. Electromechanical substitution in engine control applications threatens traditional pneumatic volume; defend against this displacement by accelerating CAN bus interface development for brake system retrofits. Capacity addition in India's Maharashtra and Gujarat corridors captures BIS-standard commercial vehicle expansion. For New Entrants and Emerging Players: Anchor in India's domestic truck and bus production growth where electropneumatic brake actuator localization creates first-mover advantage under import duty structures. Target aftermarket fleet operators seeking telematics-compatible smart actuation retrofit systems as the most penetrable segment. A go-to-market angle emphasizing predictive maintenance capabilities and embedded position sensing differentiates against legacy pneumatic suppliers. For Investors and Strategic Acquirers: Electronics-integrating mid-tier actuator specialists with ISO 26262 certification progress represent the most compelling acquisition target archetype for long-term viability across a 5-10 year holding window. These targets bridge mechanical fabrication heritage with embedded control module competency. The signal to watch is NHTSA brake-by-wire mandate acceleration as inflection indicator for electropneumatic demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Electropneumatic Module Certification | ISO 26262 compliance opens access to German Tier 1 vendor-managed inventory contracts. |
| Precision Valve Backward Integration | Captive manufacturing of high-tolerance components insulates margin from Asian supply concentration. |
| India Manufacturing Footprint | Local assembly under BIS standards bypasses import duties on commercial vehicle brake systems. |
| Smart Actuation Protocol Development | CAN bus integration captures aftermarket fleet operator demand for telematics-compatible retrofits. |
| Electromechanical Substitution Defense | Brake-by-wire specialization protects against 48V architecture displacement in engine control. |
Study Parameters
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings in this analysis. Conversations with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and electropneumatic module R&D directors informed demand-side assumptions. Secondary validation drew from vehicle production databases, EPA and NHTSA regulatory filings, IHS Markit registration data, and customs trade records for pneumatic component flows. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across product configurations.
Sensitivity analysis around aluminum and specialty steel input cost scenarios, electromechanical substitution rates, and regulatory mandate timing shapes the forecast framework. The analytical approach segments by product type, application, end user, and technology architecture across the projection horizon. CAGRs derive from regression analysis against commercial vehicle production trajectories and brake system content-per-vehicle trends. Electropneumatic penetration curves and smart actuation protocol adoption rates serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA-NHTSA regulatory stringency and continued German manufacturing corridor concentration; material deviation in fleet replacement cycles or electromechanical substitution acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Air Brake Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Traffic Control Products Market