
 Japan Anesthesia Devices Market | 2026-2036
Japan Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Anesthesia Devices Market Foresight
Japan's medical device sustainability compact is expanding procurement criteria for energy-efficient anesthesia equipment. Nihon Kohden Corporation leverages its domestic manufacturing base to supply hybrid electronic-mechanical systems. GE HealthCare Technologies Inc. anchors its position through R&D partnerships with Japanese university hospitals. Drägerwerk AG & Co. KGaA differentiates via specialized vaporizer technology for precision anesthesia delivery.
Anesthesia devices encompass machines, vaporizers, monitors, and delivery systems engineered to administer precise gas mixtures at controlled flow rates typically between 0.2 and 15 liters per minute, ensuring patient unconsciousness and analgesia during invasive procedures. Electronic technology segments lead capital expenditure as hospitals replace mechanical units with digitally integrated platforms offering automated record-keeping and closed-loop control. Delivery systems represent the fastest-growing product category, driven by rising ambulatory surgical unit volumes across Japan's urban corridors.
PMDA's device approval pathways and METI's medical cybersecurity guidelines shape product development timelines and software validation requirements for manufacturers seeking Japanese market access. JIS standards for electrical safety and electromagnetic compatibility further constrain design choices, particularly for wireless-enabled monitors. Stakeholders must weigh PMDA's evolving software-as-medical-device classification against the capital requirements for localized clinical testing.
Market Dynamics
Japan's anesthesia devices sector is undergoing structural compression as METI's medical cybersecurity mandates force manufacturers to rebuild software architectures from embedded firmware upward. This regulatory pressure coincides with hospital consolidation in Tokyo and Osaka, concentrating purchasing power among fewer procurement committees.
Growth Catalysts
- PMDA's streamlined software-as-medical-device pathway:Reduced validation timelines for AI-enabled monitors are accelerating hospital upgrade cycles.
- Metropolitan hospital cluster consolidation:Tokyo's merged healthcare networks are standardizing on unified anesthesia platforms to reduce training overhead.
- Ambulatory surgical unit expansion:Osaka's outpatient procedure volumes are driving compact delivery system procurement.
Market Restraints
- Semiconductor supply concentration:Dependence on imported sensor chips creates lead time volatility for monitor production.
- JIS electromagnetic compatibility testing:Extended certification cycles delay product launches by 8-14 months.
- Fluorinated anesthetic gas substitution:Desflurane phase-out pressures vaporizer redesign investments.
Strategic Opportunities
- Hokkaido and Tohoku regional penetration:Underserved prefectures lack advanced electronic anesthesia systems.
- Closed-loop control convergence with electronic health records:Integrated data streams enable automated anesthesia documentation.
- METI green procurement incentives:Energy-efficient equipment qualifies for preferential hospital budgeting.
Industry Challenges
- Biomedical engineer specialization gap:Shortage of technicians trained on hybrid electronic-mechanical systems limits service coverage.
- Legacy mechanical unit integration:Hospitals retain functional pneumatic machines, complicating fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Anesthesia Devices Market |
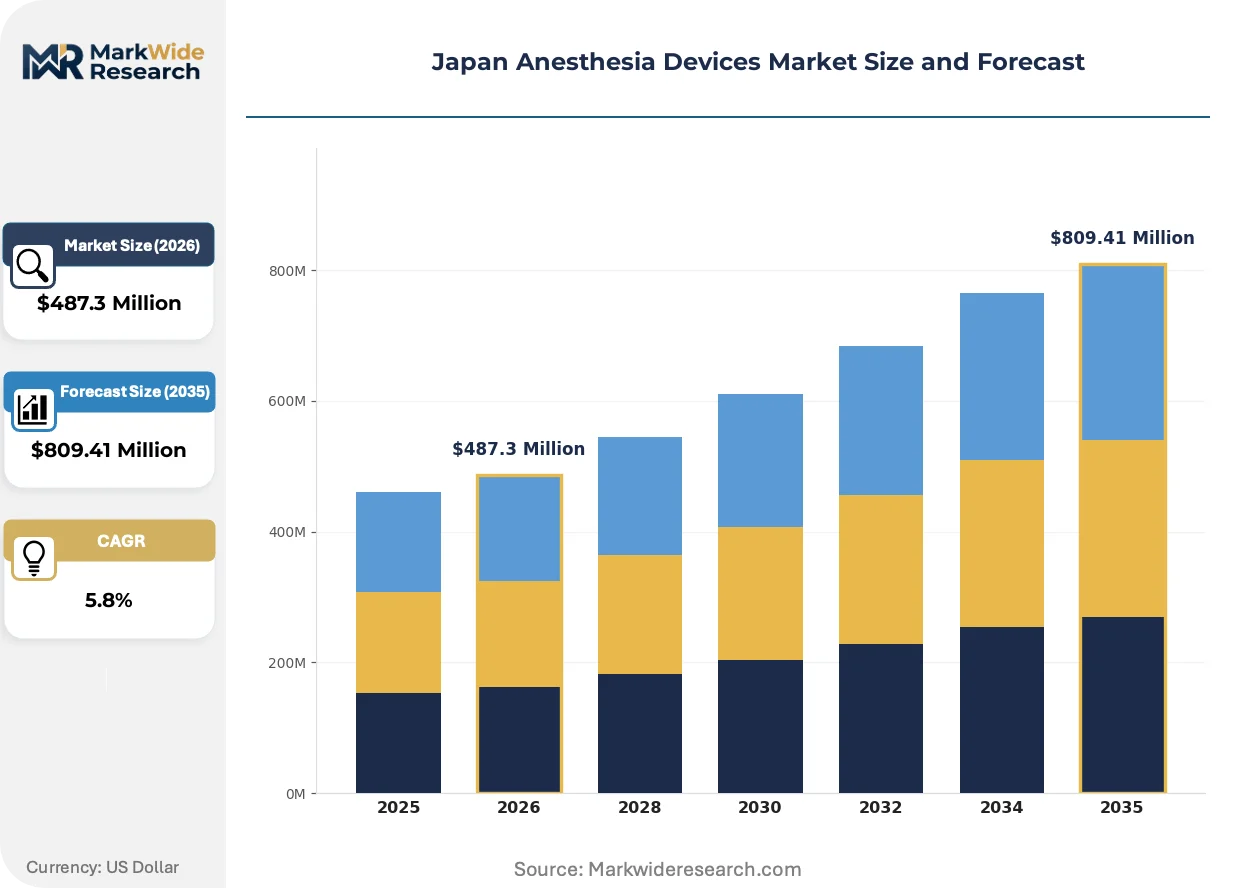
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anesthesia Machines, Vaporizers, Monitors, Delivery Systems End User: Hospitals, Surgical Centers, Clinics, Ambulatory Surgical Units Technology: Electronic, Mechanical, Digital, Hybrid Application: General Surgery, Dental Surgery, Cardiothoracic Surgery, Obstetric Surgery |
| Companies Covered | Nihon Kohden Corporation, GE HealthCare Technologies Inc., Drägerwerk AG & Co. KGaA, Medtronic plc, B. Braun Melsungen AG, Fisher & Paykel Healthcare Corporation Limited, Smiths Medical, Teleflex Incorporated, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Anesthesia Devices Market Shifts & Advancements
Digital integration is reconfiguring how anesthesia care is delivered across Japanese surgical facilities. Three distinct vectors are compressing traditional equipment lifecycles and reshaping vendor relationships.
Wireless patient monitoring is decentralizing anesthesia oversight from centralized nursing stations to distributed recovery bays and pre-operative holding areas. Smaller metropolitan hospitals in Nagoya and Fukuoka are deploying battery-enabled monitors for flexible room utilization. This topology shift is compressing capital allocation toward portable platforms and away from fixed installation systems.
METI's 2024 medical device cybersecurity framework is mandating encrypted data transmission and automated vulnerability patching for all network-connected anesthesia equipment. Manufacturers must now maintain software update infrastructure throughout product lifecycles. Electronic monitor segments face the steepest compliance costs, with development teams restructuring around continuous validation protocols.
Hospital procurement committees are consolidating vendor relationships to reduce clinical training diversity. Single-source contracts for anesthesia platforms now span machines, vaporizers, and monitors. Tokyo's merged academic medical centers are pioneering this consolidation, demanding unified service agreements and interoperable data formats from equipment suppliers.
Japan Anesthesia Devices Market Segmentation
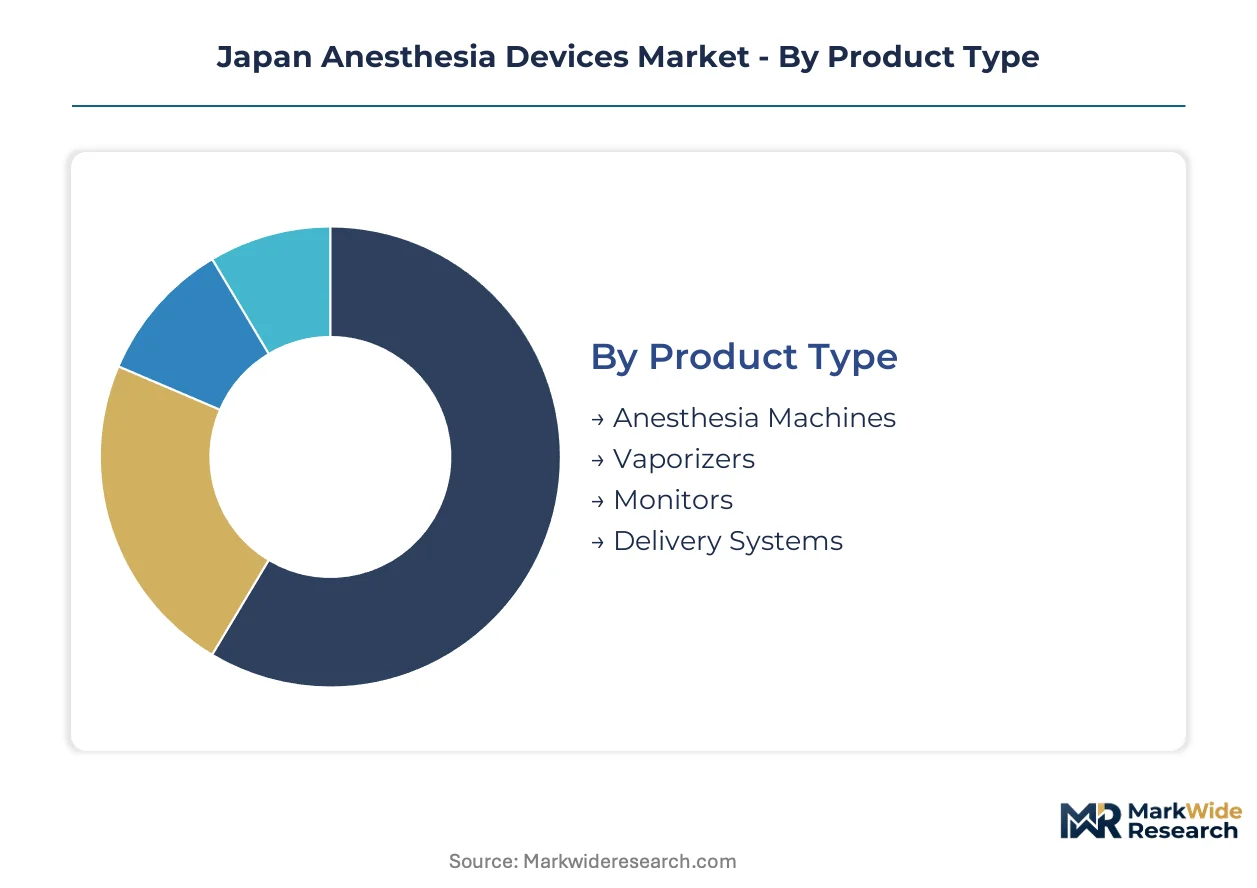
Segmentation reveals how capital deployment and regulatory compliance vary across equipment categories in Japan's anesthesia devices market. Procurement committees weigh upfront equipment costs against lifecycle cybersecurity maintenance obligations mandated by METI.
Product Type:
Capital intensity peaks with integrated anesthesia machines requiring embedded software validation, while monitors demand continuous firmware upgrade infrastructure under PMDA guidelines.
- Anesthesia Machines:Integrated platforms combine gas delivery, ventilation, and patient monitoring in single units. Tokyo's merged academic medical centers concentrate procurement of these systems to standardize training protocols across surgical floors.
- Monitors:Electronic units with wireless connectivity and automated record-keeping capabilities. Osaka's surgical hub drives replacement cycles as hospitals phase out mechanical units for digitally integrated platforms with closed-loop control.
- Vaporizers:Precision delivery modules for volatile anesthetic agents. PMDA's evolving desflurane phase-out timeline pressures redesign investments.
- Delivery Systems:Compact units for ambulatory settings. Nagoya and Fukuoka metropolitan hospitals deploy battery-enabled configurations for flexible room utilization.
Most installed capacity flows through Monitors. Expansion is steepest in Delivery Systems.
End User:
Customer type determines procurement scale and service contract complexity, with consolidated hospital networks wielding concentrated purchasing power.
- Hospitals:Large-scale purchasers with dedicated biomedical engineering departments. Tokyo's metropolitan cluster standardizes on unified platforms to reduce vendor diversity and training overhead.
- Surgical Centers:Mid-volume facilities prioritizing equipment uptime guarantees. Osaka's hub concentrates demand for rapid service response contracts.
- Ambulatory Surgical Units:Outpatient-focused settings requiring compact, portable configurations. Urban corridor expansion drives procurement of space-optimized delivery systems.
- Clinics:Smaller-scale purchasers with limited technical support capacity. Hokkaido and Tohoku regions show underpenetration of advanced electronic systems.
Procurement volume concentrates in Hospitals. Ambulatory Surgical Units are gaining share fastest.
Technology:
Technology selection hinges on METI cybersecurity compliance costs versus legacy mechanical reliability in resource-constrained settings.
- Electronic:Fully digital platforms with network connectivity and automated documentation. METI's 2024 cybersecurity framework mandates encrypted transmission and vulnerability patching infrastructure.
- Hybrid:Combined electronic-mechanical systems balancing digital functionality with pneumatic backup. Nihon Kohden's domestic manufacturing base supplies these configurations for risk-averse purchasers.
- Digital:Software-centric platforms with AI-enabled monitoring features. PMDA's streamlined software-as-medical-device pathway accelerates validation timelines.
- Mechanical:Pneumatic units without network connectivity. Legacy installations persist in Tohoku prefectures with limited biomedical engineering coverage.
Electronic platforms dominate capital expenditure. Hybrid systems are climbing the fastest as transitional replacements.
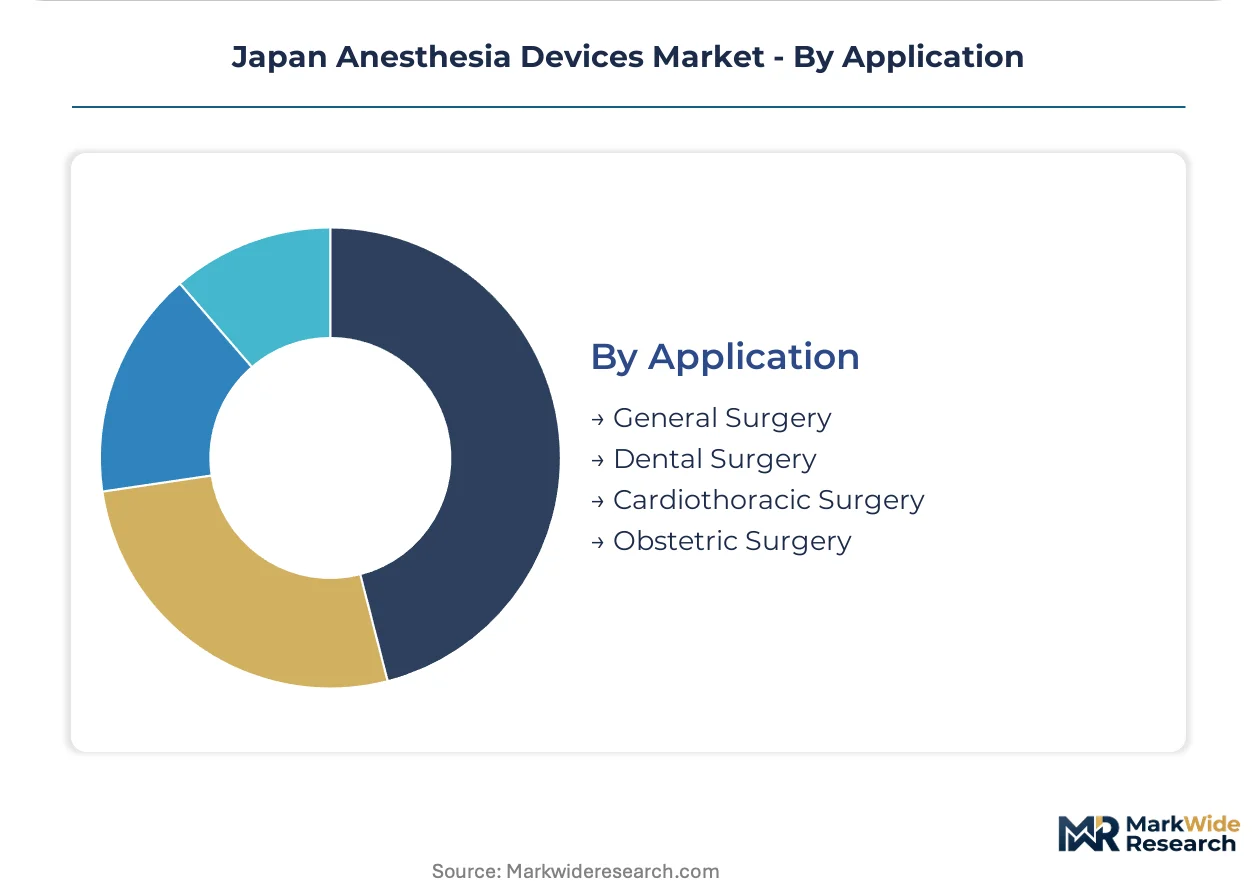
Application:
Procedure complexity dictates equipment specification requirements, with cardiothoracic and obstetric applications demanding specialized monitoring capabilities.
- General Surgery:Broad-based demand across standard procedural suites. Standardized anesthesia platforms serve routine abdominal and orthopedic interventions.
- Cardiothoracic Surgery:High-acuity procedures requiring hemodynamic monitoring integration. Tokyo's academic centers concentrate demand for advanced perfusion-coordinated systems.
- Obstetric Surgery:Maternal-fetal monitoring configurations with rapid induction protocols. Osaka's women's hospitals drive specialized vaporizer procurement.
- Dental Surgery:Sedation-focused applications with compact delivery requirements. Clinic-based oral surgery units in Fukuoka prefer portable nitrous oxide systems.
General Surgery absorbs the largest equipment base. Obstetric Surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's biomedical engineering workforce concentrates in the Kanto and Kansai corridors, anchoring anesthesia device demand in metropolitan hospital clusters. Regional penetration varies sharply between urban centers with consolidated procurement power and peripheral prefectures retaining legacy mechanical installations.
Kanto/Tokyo
Tokyo's merged academic medical centers drive standardized platform procurement to reduce training overhead across surgical floors. METI's medical cybersecurity framework mandates encrypted data transmission for all network-connected equipment in these facilities. The metropolitan cluster concentrates demand for integrated anesthesia machines with automated record-keeping capabilities.
Kansai/Osaka
Osaka's surgical hub generates rapid replacement cycles as hospitals phase out mechanical units for digitally integrated platforms. PMDA's streamlined software-as-medical-device pathway accelerates validation timelines for AI-enabled monitors in this region. Ambulatory surgical unit expansion across the urban corridor drives compact delivery system procurement.
Chubu/Nagoya
Nagoya metropolitan hospitals deploy battery-enabled monitors for flexible room utilization across distributed recovery bays. JIS electromagnetic compatibility testing requirements extend certification cycles for wireless-enabled equipment entering this market. Smaller metropolitan facilities here prioritize portable platforms over fixed installation systems.
Kyushu/Fukuoka
Fukuoka's clinic-based oral surgery units prefer portable nitrous oxide systems for dental sedation applications. Regional procurement committees lack the concentrated purchasing power of Tokyo and Osaka networks. Biomedical engineer specialization gaps limit service coverage for hybrid electronic-mechanical systems in this corridor.
Hokkaido and Tohoku
These northern prefectures show underpenetration of advanced electronic anesthesia systems relative to national averages. Legacy pneumatic machines persist in facilities with limited technical support capacity. METI's green procurement incentives aim to accelerate energy-efficient equipment adoption in these underserved markets.
Japan Anesthesia Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's anesthesia devices sector. The vendor base clusters around three strategic archetypes: domestic manufacturers leveraging localized production, multinational technology conglomerates anchoring through R&D partnerships, and specialized European engineering houses. Market consolidation pressures intensify as hospital procurement committees reduce vendor diversity. Competitive moves center on single-source contract expansion and cybersecurity compliance infrastructure development.
Among Japan-based fabricators, Nihon Kohden Corporation occupies a position representing domestic manufacturing scale advantages. GE HealthCare Technologies Inc. and Drägerwerk AG & Co. KGaA exemplify the multinational technology tier competing through university hospital R&D partnerships and specialized vaporizer engineering respectively. These three anchors sit within a structure where procurement consolidation favors vendors offering unified service agreements and interoperable data formats.
| Leading Market Players |
|---|
| Nihon Kohden Corporation |
| GE HealthCare Technologies Inc. |
| Drägerwerk AG & Co. KGaA |
| Medtronic plc |
| B. Braun Melsungen AG |
| Fisher & Paykel Healthcare Corporation Limited |
| Smiths Medical |
| Teleflex Incorporated |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
Semiconductor sensor chip costs cascade through Japan's anesthesia device tiers, with imported MEMS pressure transducers and flow sensors commanding premium placement in Tokyo's consolidated hospital networks while pneumatic-mechanical alternatives anchor economy positioning in peripheral prefectures.
Pricing Analysis
The bundled-vs-unbundled service split defines procurement economics across Japanese anesthesia platforms. Three-tier pricing structure across premium, standard, and economy levels separates integrated machine-monitor-vaporizer packages with full cybersecurity compliance from standalone monitors with limited firmware support and basic mechanical delivery systems. Price differentiation rests on METI cybersecurity certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because legacy pneumatic unit maintenance contracts undercut electronic platform lifecycle costs. Ambulatory surgical units in Osaka and Nagoya exhibit highest price sensitivity; Tokyo's merged academic medical centers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
METI's medical device localization incentives are reshaping sourcing patterns for anesthesia equipment manufacturers serving Japanese hospitals. Component supply concentrates in Taiwan, South Korea, and the United States for MEMS sensors, microcontroller units, and wireless communication modules. Raw material dependencies center on fluoropolymer seals, medical-grade aluminum alloys, and precision-machined brass vaporizer components. Single-source vulnerability in semiconductor foundry capacity creates lead time volatility for monitor production. Distribution runs through authorized medical device distributors with PMDA-licensed warehousing and biomedical engineer field service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's anesthesia devices market functions as a geographic-arbitrage play where METI cybersecurity compliance costs in metropolitan Tokyo and Osaka create margin headroom for manufacturers with established software validation infrastructure versus peripheral prefectures where legacy mechanical units avoid firmware upgrade obligations.
For Market Incumbents: Anticipate desflurane phase-out timelines forcing vaporizer platform redesign investments before PMDA mandates crystallize. Consolidate service coverage in Hokkaido and Tohoku through acquisition of regional biomedical engineering contractors to close the specialization gap threatening aftermarket revenue. Cybersecurity maintenance infrastructure represents the priority defensive lever as METI's continuous validation protocols raise rival capital requirements. For New Entrants and Emerging Players: The premium-to-economy price-point gap in wireless-enabled monitors creates entry space for hybrid electronic-mechanical systems with modular upgrade pathways. Target clinic segments in Fukuoka and Nagoya with portable delivery systems requiring minimal field service coverage. Pursue GPO contracts with mid-tier surgical centers seeking alternatives to Tokyo-centric vendor consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement committee standardization reduces viable vendor slots from five to three per anesthesia platform category. Five-to-ten year viability favors manufacturers with captive software development capabilities and METI pre-certified cybersecurity architectures. Watch for PMDA software-as-medical-device pathway expansion as the inflection signal accelerating AI-enabled monitor replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerated validation timelines compress rival product development windows under METI guidelines. |
| Hospital System Partnership | Single-source contracts with Tokyo's merged academic centers lock in multi-year platform standardization. |
| Cybersecurity Infrastructure Investment | Continuous firmware patching capabilities satisfy METI's 2024 medical device framework mandates. |
| Regional Service Network Expansion | Hokkaido and Tohoku coverage gaps limit incumbent aftermarket revenue capture for hybrid systems. |
| Green Procurement Certification | METI energy-efficient equipment incentives qualify preferential budgeting in consolidated hospital networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and PMDA regulatory consultants with secondary validation against METI medical device cybersecurity guidelines, PMDA approval databases, JIS electromagnetic compatibility standards, and hospital procurement records. Bottom-up equipment installation tracking and top-down market sizing triangulated segment-level estimates.
Segment-weighting approaches distributed value across product type, end user, technology, and application dimensions throughout the projection horizon. Analytical frameworks modeled anesthesia machine, monitor, vaporizer, and delivery system trajectories separately, with technology splits between electronic, hybrid, digital, and mechanical platforms. CAGRs derived from replacement cycle analysis, ambulatory surgical unit expansion rates, and cybersecurity compliance-driven upgrade elasticities.
Caveats apply where semiconductor supply disruptions, PMDA software classification revisions, or fluorinated anesthetic gas substitution timelines could materially shift the outlook. Forecasts reflect documented assumptions about hospital consolidation velocity and METI enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
TMJ Implants Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Jet Nebulizers Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
US Contact Lenses Market
Medical Devices
Neuromodulation Market
Medical Devices
Urology Guidewires Market