
 Global Peripheral Vascular Devices and Accessories Market | 2026-2036
Global Peripheral Vascular Devices and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peripheral Vascular Devices and Accessories Market Foresight
Software-defined procedural planning and remote monitoring subscriptions is broadening what vascular device vendors monetize beyond the physical implant. Medtronic leverages integrated digital cath-lab ecosystems to sustain recurring revenue alongside hardware placements. Boston Scientific Corporation anchors its peripheral portfolio through R&D intensity in drug-eluting balloon platforms. Abbott Laboratories differentiates via catheter-based mapping technologies that extend clinician workflow capture across hospital networks.
Peripheral vascular devices and accessories comprise implantable and disposable instruments designed to restore, maintain, or improve blood flow in vessels outside the coronary and cerebral circulations, typically constructed from nitinol, cobalt-chromium alloys, or biodegradable polymers and delivered through 4-8 French catheter systems under fluoroscopic guidance. Stent systems and embolic protection devices command the deepest margin pools where chronic restenosis management drives repeat intervention economics. Catheters and guidewires represent high-velocity categories shaped by hydrophilic coating innovations and torque-response improvements that reduce procedure time in complex tibial and carotid anatomies. Drug-eluting and bioabsorbable technologies are gaining structural prominence as bare-metal platforms face reimbursement compression in markets with mature health technology assessment frameworks.
FDA 510(k) and PMA pathways, EU MDR technical documentation requirements, and Japan PMDA orphan device reviews collectively shape product development timelines, clinical evidence thresholds, and market access sequencing for peripheral vascular innovators. The EU Green Deal and REACH chemical compliance frameworks are additionally influencing polymer and coating material selections across the supply base. Stakeholders must monitor how real-world evidence mandates from FDA and post-market surveillance obligations under MDR Article 83 reshape competitive positioning between established players and emerging technology developers.
Market Dynamics
Catheter-based procedural migration from inpatient suites to ambulatory surgical centers is compressing device procurement cycles and forcing vendors to restructure field service coverage around same-day discharge protocols.
Growth Catalysts
- EU MDR Article 83 post-market surveillance mandates:Device manufacturers must maintain systematic clinical follow-up registries, creating recurring data infrastructure contracts that extend vendor-client relationships beyond initial implant sales.
- Japan's aging tibial intervention population:PMDA orphan device pathways for below-the-knee drug-eluting platforms accelerate regulatory timelines for innovators targeting critical limb ischemia.
- Nitinol laser-cutting precision advances:Femtosecond machining improvements enable thinner stent struts without sacrificing radial force, expanding treatable lesion complexity in calcified femoropopliteal segments.
Market Restraints
- Cobalt-chromium alloy supply concentration:Three European specialty metal processors control 70% of medical-grade feedstock, exposing stent manufacturers to price volatility and allocation risk during energy-intensive smelter curtailments.
- REACH chemical compliance burdens:ECHA substance-of-very-high-concern listings for certain polymer plasticizers force coating reformulations that extend validation timelines by 18-24 months.
- Bare-metal stent reimbursement compression:Germany's G-BA health technology assessment now requires drug-eluting superiority evidence for full tariff coverage, stranding legacy inventory in hospital purchasing pipelines.
Strategic Opportunities
- India's underpenetrated peripheral intervention infrastructure:CDSCO streamlined medical device rules and PLI scheme production incentives attract catheter manufacturing investments targeting 400 million diabetic patients with vascular complications.
- Remote physiologic monitoring integration:Wearable ankle-brachial index sensors paired with cloud-based surveillance platforms enable pre-symptomatic referral capture, expanding addressable patient pools beyond acute intervention candidates.
- AI-enabled procedural planning subscriptions:Machine learning algorithms that predict lesion preparation requirements and stent sizing are automating cath-lab workflow standardization, creating SaaS revenue streams detached from physical device sales.
Industry Challenges
- Interventionalist training pipeline constraints:Complex tibial and pedal access techniques require fellowship-level proficiency that outpaces vascular surgery residency program expansion, creating procedural bottleneck risk in high-volume markets.
- EU MDR technical documentation remediation:Legacy product portfolios face 2026 certificate expiration cliffs, forcing simultaneous clinical evidence generation across hundreds of SKUs with limited notified body audit capacity.
- Multi-vendor cath-lab interoperability:Proprietary imaging and hemodynamic data formats from dominant fluoroscopy vendors fragment digital integration roadmaps for third-party device connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peripheral Vascular Devices and Accessories Market |
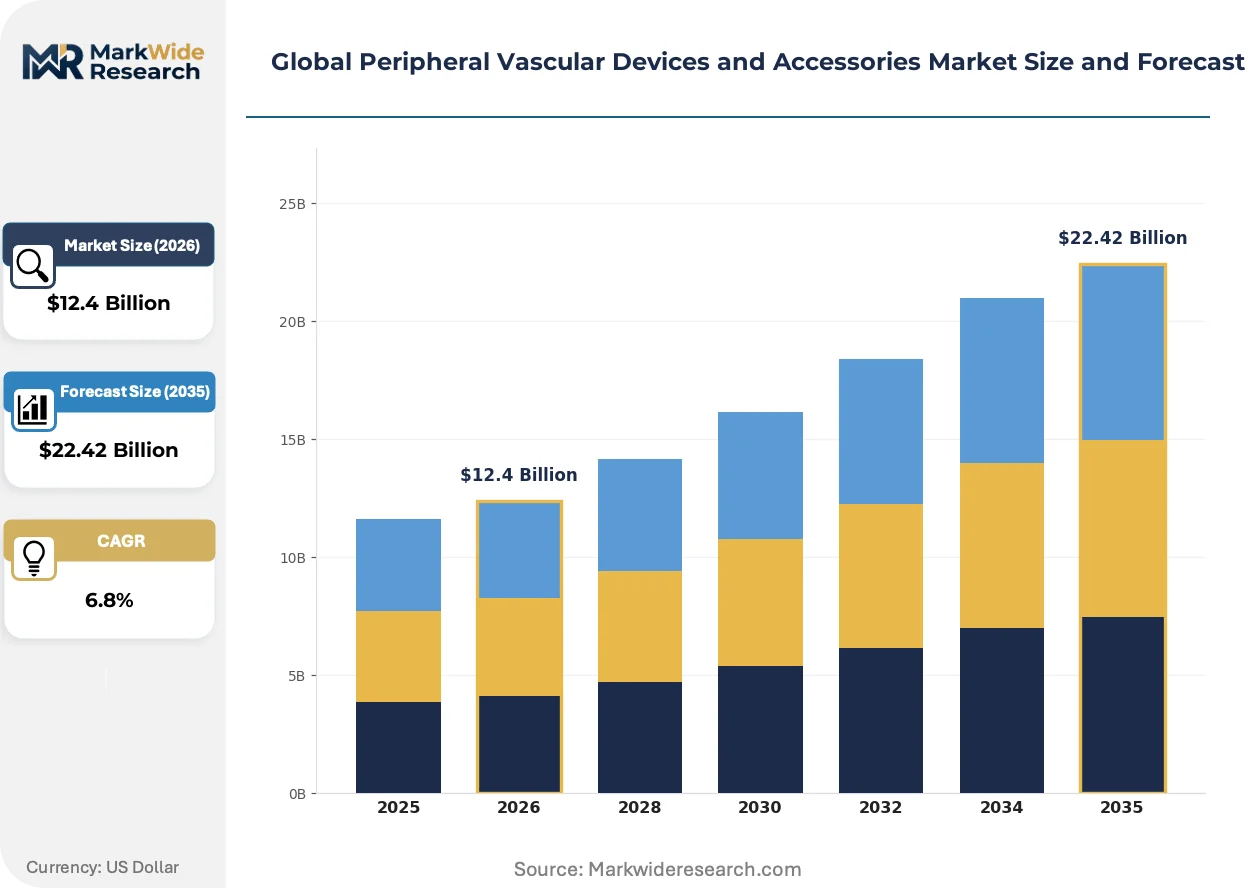
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Systems, Catheters, Guidewires, Balloons, Embolic Protection Devices Technology: Drug-Eluting, Bare-Metal, Bioabsorbable, Polymer-Coated, Radiopaque Application: Peripheral Artery Disease, Chronic Venous Insufficiency, Deep Vein Thrombosis, Varicose Veins, Lymphatic Disorders End User: Cardiology Units, Vascular Surgery Centers, Specialty Clinics, Outpatient Facilities, Ambulatory Surgical Centers |
| Companies Covered | Medtronic, Boston Scientific Corporation, B. Braun SE, W. L. Gore & Associates, Abbott Laboratories, Edwards Lifesciences Corporation, Terumo Corporation, LeMaitre Vascular, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peripheral Vascular Devices and Accessories Market Shifts & Advancements
Digital thread integration across device design, manufacturing, and post-market surveillance is collapsing traditional silos between R&D and real-world evidence generation.
Robotic catheter navigation systems are automating guidewire manipulation in complex chronic total occlusion cases, reducing operator radiation exposure and procedure time variability. Academic medical centers in Germany and Japan are piloting these platforms for high-volume femoropopliteal interventions, compressing the learning curve for trainees while standardizing technical outcomes across operator experience levels.
EU MDR clinical evaluation requirements are forcing manufacturers to maintain active implant follow-up registries that span the full device lifecycle. This surveillance obligation is restructuring competitive advantage toward firms with established health economics capabilities and hospital network data-sharing agreements, disadvantaging mid-tier competitors reliant on legacy literature-based equivalence arguments.
Hospital purchasing consortia in the United States are consolidating procurement authority for peripheral vascular devices under centralized value analysis committees. This concentration is displacing individual physician preference contracting, forcing vendors to demonstrate total cost-of-care impact across the intervention episode rather than device-centric value propositions alone.
Global Peripheral Vascular Devices and Accessories Market Segmentation
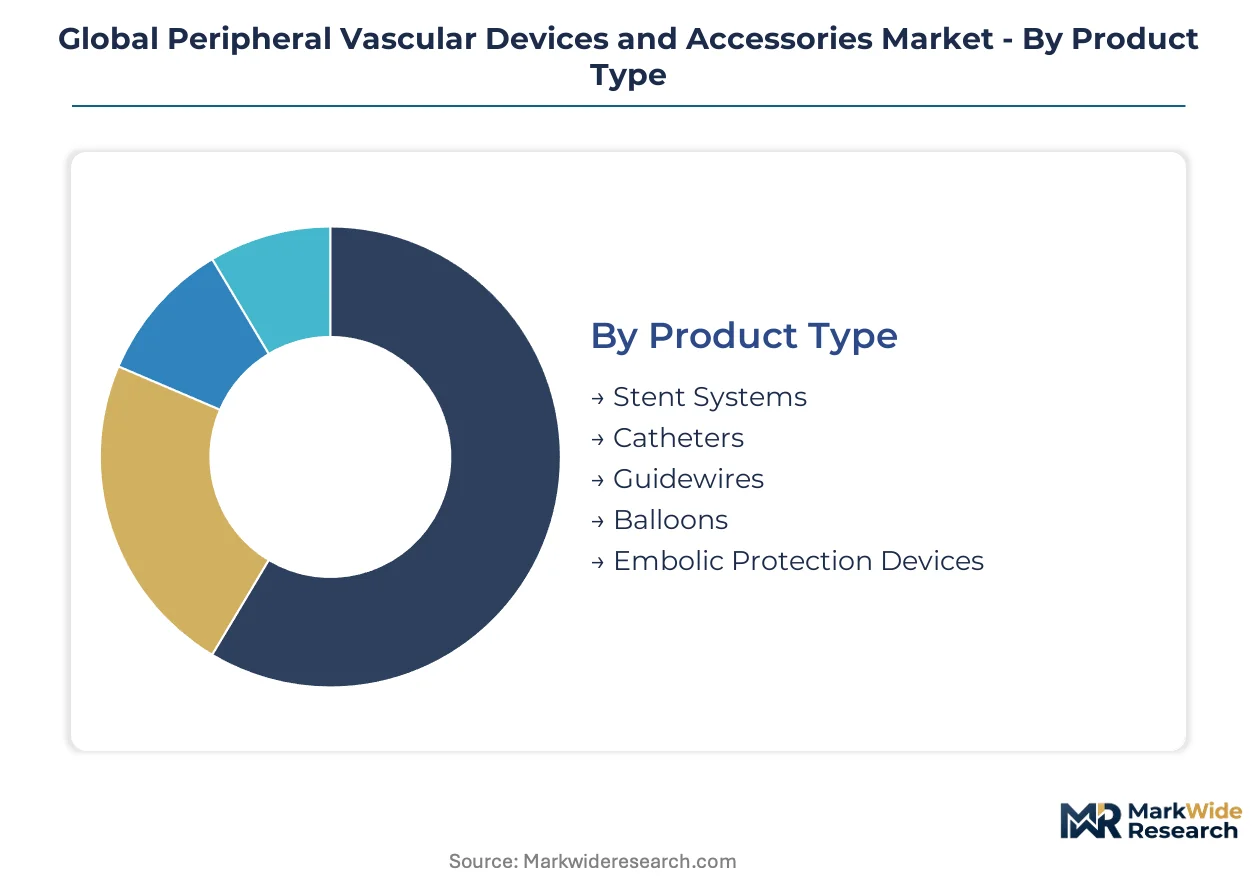
Segmentation in peripheral vascular devices reveals how procurement authority, reimbursement pathways, and clinical workflow requirements reshape competitive positioning across product categories. Device vendors must align portfolio depth with the specific evidence thresholds and purchasing consolidation patterns governing each segment.
Product Type:
Standardization dominates high-volume consumables while implantable systems demand extensive customization to lesion morphology and vessel calcification patterns.
- Stent Systems:Self-expanding nitinol scaffolds with closed-cell or open-cell geometries deliver radial force in femoropopliteal and tibial segments. Demand concentrates in Germany and Japan where chronic restenosis management drives repeat intervention economics and drug-eluting platforms command premium reimbursement.
- Catheters:Hydrophilic-coated delivery systems ranging from 4-8 French diameters enable access through tortuous iliac and subclavian anatomies. United States ambulatory surgical centers are standardizing catheter procurement under value analysis committee oversight, compressing vendor field service requirements around same-day discharge protocols.
- Guidewires:Torque-responsive stainless steel or nitinol cores with variable tip stiffness navigate chronic total occlusions.
- Balloons:Semi-compliant and non-compliant inflation platforms predominate in lesion preparation.
- Embolic Protection Devices:Filter and occlusion-type systems capture debris during carotid and saphenous vein graft interventions.
Leading the category by volume: Catheters. Growing fastest: Stent Systems.
Technology:
Cost tiers separate legacy platforms facing reimbursement compression from next-generation modalities requiring expanded clinical evidence packages.
- Drug-Eluting:Paclitaxel or sirolimus formulations embedded in polymer matrices inhibit neointimal hyperplasia. Germany's G-BA health technology assessment now mandates drug-eluting superiority evidence for full tariff coverage, stranding bare-metal inventory and accelerating hospital conversion to eluting platforms.
- Bare-Metal:Uncoated nitinol or cobalt-chromium scaffolds retain utility in cost-constrained markets and patients with contraindications to antiproliferative agents. United States Medicare bundled payment models are compressing bare-metal margins, forcing manufacturers to demonstrate total cost-of-care equivalence against drug-eluting alternatives.
- Bioabsorbable:Magnesium or polymeric scaffolds that resorb after vessel remodeling eliminate permanent implant concerns.
- Polymer-Coated:Passive coatings reduce thrombogenicity without drug delivery.
- Radiopaque:Tantalum or platinum markers enhance fluoroscopic visibility during deployment.
Drug-Eluting technology commands the highest average selling prices. Bioabsorbable platforms are expanding most quickly from investigational into commercial phases.
Application:
Procedure volume distributes across acute intervention candidates and chronic disease management populations with divergent reimbursement and referral pathway structures.
- Peripheral Artery Disease:Atherosclerotic stenosis or occlusion in lower extremity vessels drives the majority of femoropopliteal and infrapopliteal interventions. Japan's aging diabetic population with critical limb ischemia is expanding tibial intervention volumes, with PMDA orphan device pathways accelerating regulatory timelines for below-the-knee drug-eluting platforms.
- Chronic Venous Insufficiency:Valve incompetence and venous hypertension require endovenous thermal or non-thermal ablation systems. United States office-based lab expansion is shifting venous procedures from hospital outpatient departments, altering device procurement cycles toward direct-to-practice distribution.
- Deep Vein Thrombosis:Acute iliofemoral clot burden necessitates pharmacomechanical thrombectomy.
- Varicose Veins:Saphenous reflux and tributary disease respond to catheter-based closure.
- Lymphatic Disorders:Lymphedema and lymphatic obstruction represent emerging interventional targets with limited established device platforms.
Peripheral Artery Disease generates the largest procedure volume. Chronic Venous Insufficiency is climbing the fastest as ambulatory migration expands treatable patient pools.
End User:
Customer type determines purchasing authority concentration, technical support requirements, and the balance between capital equipment and disposable revenue models.
- Cardiology Units:Integrated cath-lab ecosystems within hospital systems consolidate peripheral vascular procedures alongside coronary interventions. United States cardiology departments are deploying software-defined procedural planning tools that standardize stent sizing and lesion preparation across operator experience levels.
- Vascular Surgery Centers:Dedicated facilities with open surgical backup manage complex chronic total occlusions and limb salvage cases. Germany's vascular surgery residency programs are expanding robotic catheter navigation training to compress the learning curve for complex tibial access techniques.
- Specialty Clinics:Focused venous or arterial practices concentrate high-volume elective procedures.
- Outpatient Facilities:Hospital outpatient departments retain higher-acuity cases requiring overnight observation.
- Ambulatory Surgical Centers:Same-day discharge protocols dominate low-complexity femoropopliteal and venous interventions.
Cardiology Units lead the category by installed base and procedure throughput. Ambulatory Surgical Centers are gaining share fastest as reimbursement migration accelerates site-of-service shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of nitinol and cobalt-chromium feedstock concentrates in European specialty metal processors, while procedural consumption tilts toward aging populations in the United States, Germany, and Japan. This production-consumption divide shapes regulatory sequencing and vendor field service deployment.
United States
Medicare bundled payment models for peripheral vascular interventions accelerate site-of-service migration toward ambulatory surgical centers. FDA 510(k) and PMA pathways maintain stringent clinical evidence thresholds for drug-eluting stent approvals. Minneapolis and Boston anchor device innovation clusters where integrated cath-lab ecosystems dominate hospital procurement.
Germany
The G-BA health technology assessment now mandates drug-eluting superiority evidence for full tariff coverage, compressing bare-metal stent margins. EU MDR Article 83 post-market surveillance obligations force manufacturers to maintain systematic implant follow-up registries. Baden-Württemberg and Bavaria host vascular surgery residency programs expanding robotic catheter navigation training.
Japan
PMDA orphan device pathways accelerate regulatory timelines for below-the-knee drug-eluting platforms targeting critical limb ischemia. METI production incentives support domestic catheter manufacturing investments. Tokyo and Osaka medical centers pilot software-defined procedural planning tools that standardize stent sizing across operator experience levels.
India
CDSCO streamlined medical device rules and PLI scheme production incentives attract catheter manufacturing investments targeting diabetic vascular complications. The country's national pharmaceutical regulator tightens quality benchmarks for imported stent systems. Hyderabad and Bengaluru emerge as contract manufacturing hubs for hydrophilic-coated delivery systems.
China
NMPA innovation device pathways compress review timelines for domestic drug-eluting platforms, displacing imported share in femoropopliteal segments. Dual carbon goals drive energy-intensive smelter curtailments that threaten cobalt-chromium alloy feedstock availability. Shanghai and Suzhou concentrate catheter production for regional export markets.
Global Peripheral Vascular Devices and Accessories Market Competitive Landscape
Top-tier vendors anchor integrated cath-lab ecosystems, while mid-tier specialists concentrate on single-modality excellence. The vendor base stratifies across three tiers: diversified medtech conglomerates with digital revenue streams, focused vascular device manufacturers with deep nitinol processing expertise, and emerging regional players exploiting local regulatory fast-tracks. Consolidation pressures intensify as hospital purchasing consortia displace individual physician preference contracting. Dominant competitive moves include backward integration into cobalt-chromium feedstock sourcing and technology licensing for bioabsorbable scaffold platforms.
Within the diversified medtech tier, Medtronic and Boston Scientific Corporation exemplify vendors monetizing software-defined procedural planning beyond physical implant sales. Abbott Laboratories anchors the catheter-based mapping technology segment. Among European-focused manufacturers, B. Braun SE and W. L. Gore & Associates occupy positions shaped by EU MDR compliance capabilities and specialized polymer processing heritage.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| B. Braun SE |
| W. L. Gore & Associates |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Terumo Corporation |
| LeMaitre Vascular |
| AngioDynamics |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up catheter specialists have consolidated regional service networks across the United States and Germany, tightening pricing discipline through captive distribution while compressing procurement cycles for ambulatory surgical centers. This ownership pattern feeds directly into supply behavior, as portfolio companies prioritize predictable margin streams over volume share grabs in EU MDR compliance-heavy markets.
Pricing Analysis
Margin tightening in bare-metal stent tiers reflects Germany's G-BA health technology assessment mandating drug-eluting superiority evidence for full tariff coverage. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy polymer-coated platforms separates reimbursement-eligible systems from cash-pay alternatives. Cost-down pressure on catheter bundles accelerates as United States hospital purchasing consortia displace individual physician preference contracting. Ambulatory surgical centers exhibit highest price sensitivity, while integrated hospital systems absorb premium tiers for bundled episode economics.
Supply Chain Analysis
Nitinol and cobalt-chromium feedstock rests on European specialty metal processors in Germany, France, and Belgium, with secondary refining capacity concentrated in United States and Japanese aerospace-grade suppliers. Laser-cut stent scaffolds, hydrophilic polymer coatings, and femtosecond machining equipment constitute critical component dependencies. Single-source vulnerability in medical-grade alloy smelting exposes manufacturers to energy-intensive production curtailments under EU Green Deal frameworks. Distribution runs through manufacturer-direct field service teams for implantable systems, with disposable catheters flowing through regional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in notified body audit capacity for EU MDR technical documentation are propping pricing power for compliant incumbents, as certificate expiration cliffs strand legacy portfolios and compress available supply.
For Market Incumbents: Hedge cobalt-chromium supply exposure through backward integration into European specialty metal processors or long-term offtake agreements with German and Belgian smelters. Accelerate software-defined procedural planning subscriptions to detach revenue from physical implant sales, countering bare-metal reimbursement compression. Prioritize EU MDR Article 83 registry infrastructure investments to extend vendor-client relationships beyond initial implant transactions. For New Entrants and Emerging Players: The mid-tier pricing gap between premium drug-eluting platforms and economy bare-metal systems opens white-space in India's underpenetrated peripheral intervention infrastructure, where CDSCO streamlined rules and PLI scheme incentives reduce capital barriers. Target tibial access catheter manufacturing for diabetic vascular complications, exploiting PMDA orphan device pathway precedents. Deploy direct-to-hospital digital sales models to bypass consolidated United States purchasing consortia. For Investors and Strategic Acquirers: Distressed-cycle entries favor EU MDR-compliant mid-caps with established notified body relationships and active implant registries, particularly in German and Japanese markets where regulatory timelines accelerate competitive sorting. Long-term viability hinges on digital revenue attachment rates and health economics capabilities rather than hardware share alone. Watch FDA real-world evidence mandates as inflection indicator for valuation premium shifts toward surveillance-enabled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Remediation | Notified body audit scarcity in Germany and Netherlands extends certificate expiration timelines for prepared manufacturers. |
| Software Companion Development | Machine learning procedural planning tools from Tokyo and Boston clusters automate cath-lab workflow standardization. |
| Backward Integration into Alloy Feedstock | Captive cobalt-chromium supply from Baden-Württemberg processors mitigates energy-curtailment risk for stent manufacturers. |
| Hospital System Partnership | Integrated cath-lab ecosystem contracts with United States cardiology units secure multi-year disposable procurement commitments. |
| Reimbursement Strategy | G-BA health technology assessment alignment in Germany preserves full tariff coverage for drug-eluting platform conversions. |
Research Methodology
Multi-period observation of procedural volume migration, regulatory certificate expirations, and reimbursement tariff revisions anchored the trend analysis, supplemented by interviews with vascular surgeons, catheter laboratory directors, hospital purchasing committee chairs, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body audit disclosures, CMS Medicare claims data, and Japanese PMDA orphan device approval records. Bottom-up installed base modeling and top-down expenditure flow analysis were triangulated against manufacturer-reported segment revenues.
Segment-weighting across product type, technology tier, application, and end-user facility category structured the analytical framework over the projection horizon. CAGRs were derived from logistic diffusion curves fitted to procedural adoption patterns and equipment replacement cycles. Forecast inputs incorporated nitinol alloy price indices, ambulatory surgical center site-of-service reimbursement differentials, and EU MDR compliance cost pass-through assumptions.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time notified body audit queue data introduce uncertainty bands around EU MDR transition timing assumptions. Forecasts reflect documented assumptions regarding reimbursement stability and alloy supply continuity. Regulatory acceleration in Japan's PMDA pathways and supply disruption in Chinese dual-carbon smelter curtailments warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Medical Devices Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
Lactate Meter Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Global PC-Based Audiometer Market